
 Cryopreservation Equipment Market | 2026-2036
Cryopreservation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cryopreservation Equipment Market Analysis
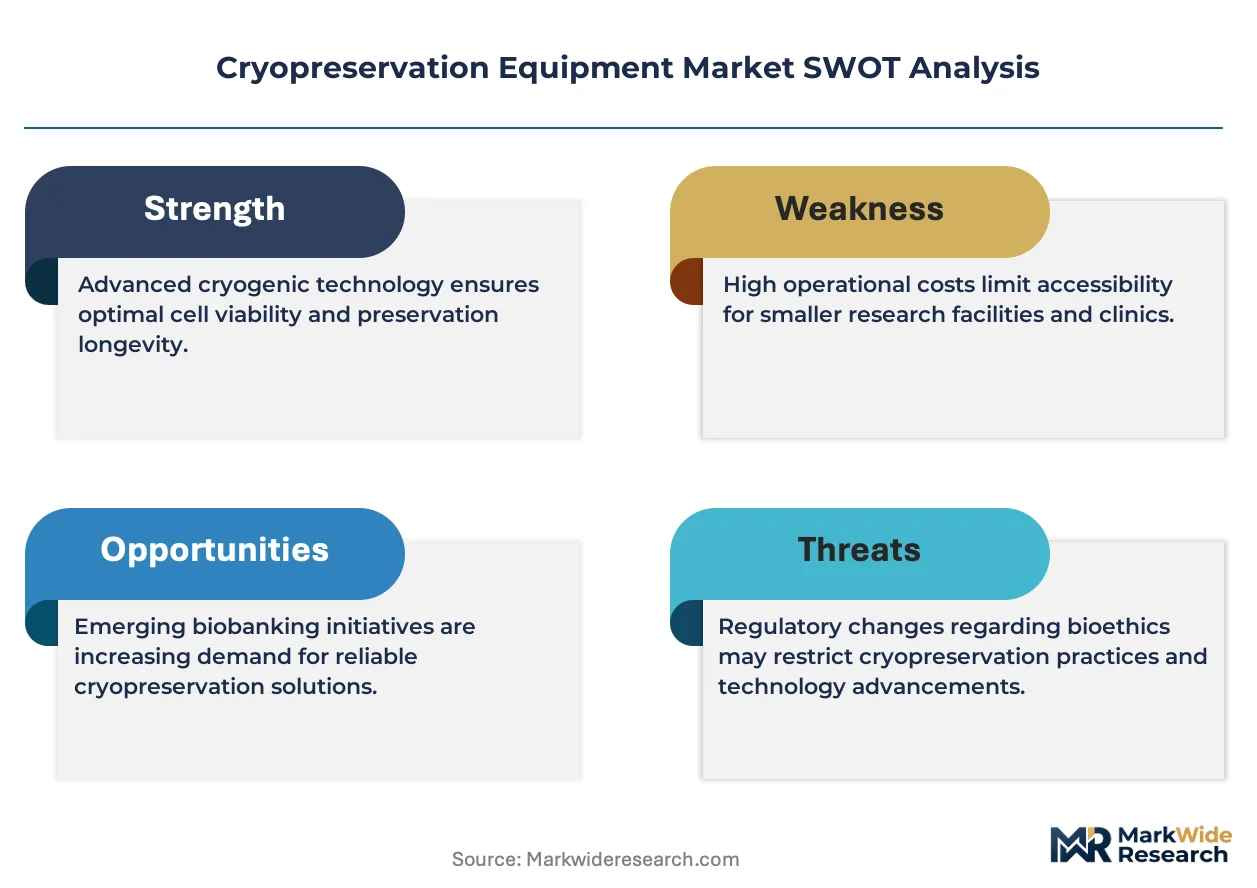
Ultra-low temperature specification tiers down to minus 150 degrees Celsius is redrawing procurement benchmarks across biobanking infrastructure. Thermo Fisher Scientific Inc. leverages its end-to-end cold chain portfolio to anchor large-scale biorepository contracts. Haier Biomedical competes aggressively on manufacturing scale, offering modular freezer farms that reduce facility footprint. Azenta US Inc. specializes in automated sample management systems that integrate retrieval robotics with inventory software.
Cryopreservation equipment encompasses engineered systems that maintain biological specimens at cryogenic temperatures, typically utilizing liquid nitrogen or mechanical cascade refrigeration to achieve and sustain temperatures between minus 80 and minus 196 degrees Celsius for metabolic arrest and long-term viability. The primary purpose spans cell therapy manufacturing, reproductive medicine, and genomic research where thermal stability directly preserves functional integrity of living materials. Cryogenic freezers and liquid nitrogen tanks constitute the mature volume base, while automated systems capture expanding margin pools as biobanks scale toward millions of samples. Vapor phase technology leads installed capacity for operator safety, yet controlled rate freezing commands premium positioning in cell therapy workflows where post-thaw recovery rates determine commercial value.
FDA 21 CFR Part 11 and EU MDR frame validation requirements for equipment used in therapeutic manufacturing, compelling vendors to embed electronic records and quality system documentation. EMA guidelines on advanced therapy medicinal products extend these standards to cryopreservation steps within cell and gene therapy production chains. ISO 20387 for biobanking adds a third compliance layer governing sample traceability and temperature monitoring across the storage lifecycle. Stakeholders must weigh capital deployment between incremental freezer additions and integrated automation platforms that preempt stricter chain-of-custody regulations anticipated across major jurisdictions.
Market Dynamics
Automated sample management systems are compressing procurement cycles as biobanks scale toward multi-million-sample repositories, forcing capital allocation trade-offs between standalone freezers and integrated robotics platforms.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in cell therapy manufacturing are validating investment in automated cryogenic systems with embedded audit trails.
- Cell therapy manufacturing:Commercial-scale production of CAR-T and gene therapies requires controlled-rate freezing workflows to preserve post-thaw viability.
- Japan biobanking infrastructure:National precision medicine initiatives are driving centralized procurement of vapor-phase nitrogen storage systems.
Market Restraints
- Liquid nitrogen supply concentration:Regional production bottlenecks in industrial gas supply create operational vulnerability for vapor-phase dependent facilities.
- Mechanical cascade refrigeration energy intensity:Ultra-low temperature mechanical systems face escalating electricity costs and carbon accounting pressures.
- ISO 20387 compliance timelines:Biobank certification requirements extend sales cycles and strain vendor quality system resources.
Strategic Opportunities
- India biorepository buildout:CDSCO regulatory frameworks for advanced therapies are creating first-mover advantage for automated storage vendors.
- Reproductive medicine digitization:Integration of cryogenic storage with laboratory information management systems opens recurring software revenue streams.
- EU Green Deal alignment:F-Gas Regulation phase-down creates replacement demand for nitrogen-based alternatives to mechanical refrigeration.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in thermal system design and robotics integration outpaces vocational training pipeline output.
- Legacy inventory migration complexity:Biobanks with decades of sample accumulation face barcode standardization and retrieval automation retrofit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryopreservation Equipment Market |
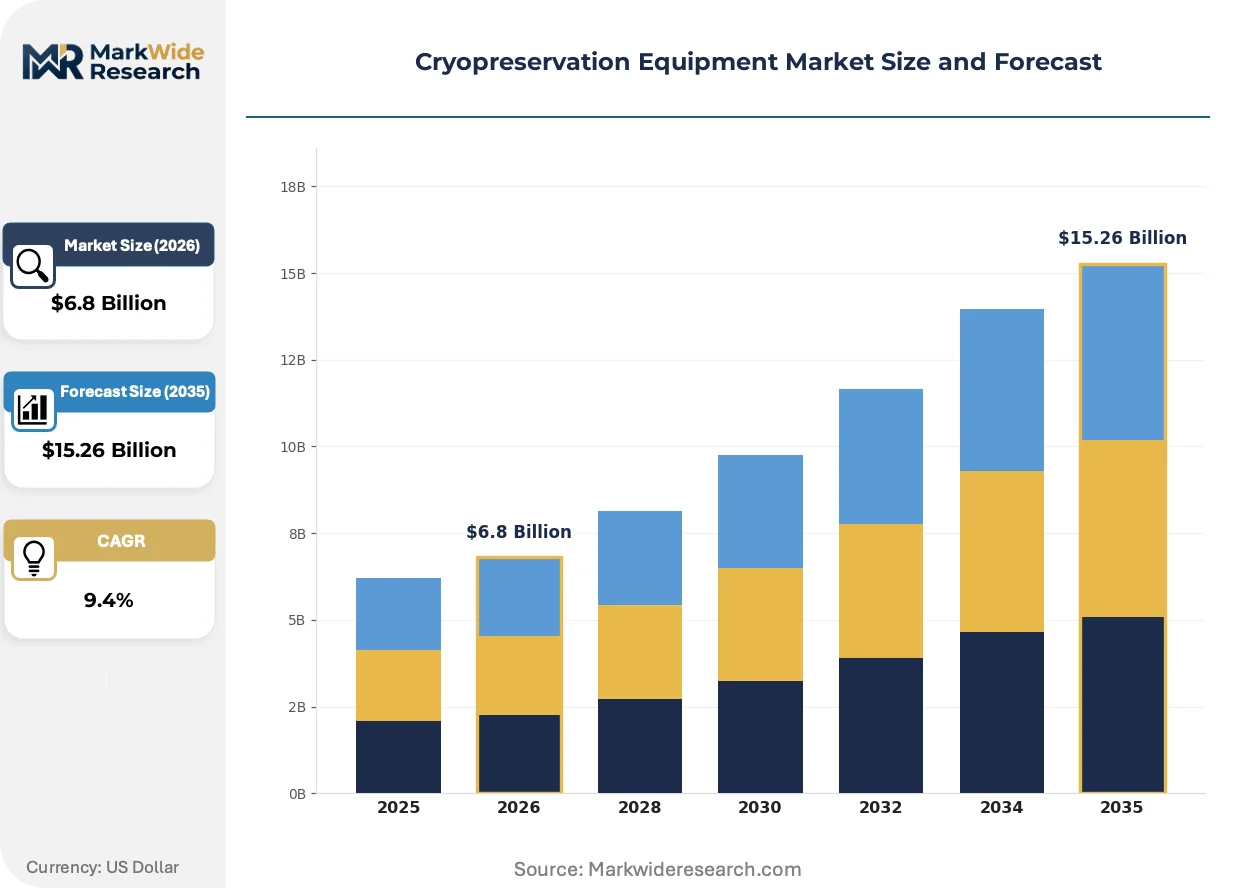
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic Freezers, Liquid Nitrogen Tanks, Thawing Equipment, Storage Containers Technology: Vapor Phase, Controlled Rate Freezing, Dry Ice Technology, Automated Systems End User: Research Laboratories, Biobanks, Hospitals, Pharmaceutical Companies Application: Stem Cell Preservation, Sperm Banks, Tissue Preservation, IVF Processes |
| Companies Covered | Thermo Fisher Scientific Inc., Azenta US Inc., MVE Biological Solutions, Haier Biomedical, PHC Holdings Corporation, Merck KGaA, Planer, a Hamilton Thorne company, Custom Biogenic Systems, Chart Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryopreservation Equipment Market Emerging Trajectories
Hardware-software convergence is redefining competitive moats as buyers prioritize sample traceability and predictive maintenance over standalone temperature performance. Vendors are racing to embed analytics capabilities that preempt regulatory scrutiny.
Mechanical vapor compression technology is displacing liquid nitrogen immersion systems in high-throughput biobanking operations. Pharmaceutical manufacturers with EMA-certified cell therapy lines are adopting cascade refrigeration for controlled-rate freezing to eliminate nitrogen handling hazards. This displacement is compressing margins for traditional tank suppliers while elevating system integrators with thermal engineering depth.
EMA guidelines on advanced therapy medicinal products now mandate temperature mapping validation across cryopreservation steps. Manufacturing sites in Germany and Switzerland are retrofitting existing infrastructure with redundant monitoring sensors and automated alarm escalation. Cell therapy contract development organizations face the steepest compliance burden, driving consolidation toward vendors with pre-validated quality documentation packages.
Biobank procurement committees now weight total cost of ownership over capital expenditure, unbundling after-sales service from equipment purchase. Large academic medical centers in the United States are negotiating multi-year service contracts with guaranteed uptime penalties. This behavioral shift favors vendors with regional field service density over low-cost manufacturers with limited support infrastructure.
Cryopreservation Equipment Market Segmentation
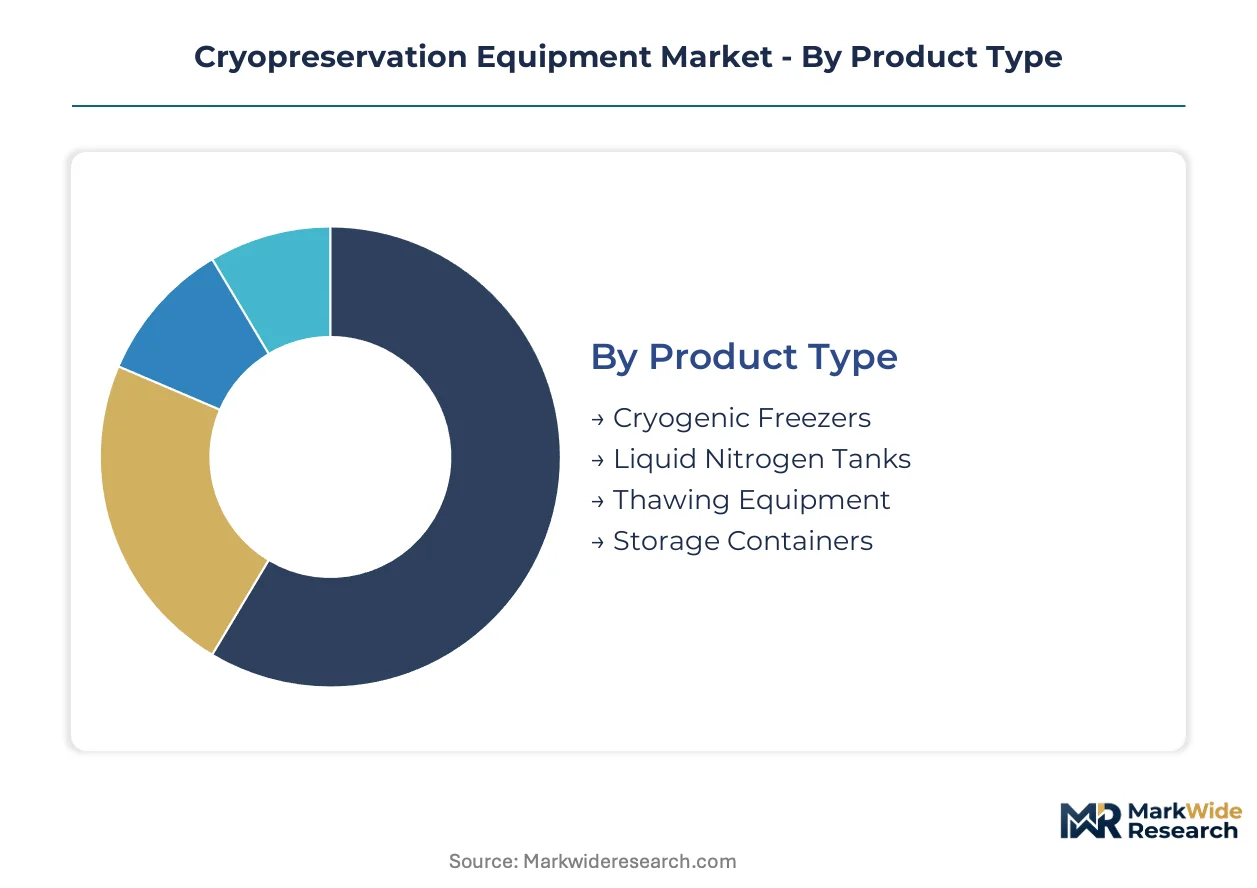
Cryopreservation equipment procurement diverges sharply across end-use workflows, with biobanks prioritizing automation density while cell therapy manufacturers emphasize controlled-rate precision. Channel dynamics favor direct vendor relationships for integrated systems versus distribution partnerships for standard freezer replacements.
Product Type:
Equipment categories flow through distinct commercial channels: cryogenic freezers and liquid nitrogen tanks move through industrial gas distributors and life science dealers, while thawing equipment and automated storage platforms require direct manufacturer engagement for validation support.
- Cryogenic Freezers:Mechanical cascade refrigeration systems sustain temperatures between minus 80 and minus 150 degrees Celsius for metabolic arrest of biological specimens. Academic medical centers in Germany and pharmaceutical manufacturers in Switzerland are retrofitting aging fleets with EU MDR-compliant units featuring redundant monitoring sensors and electronic batch records.
- Liquid Nitrogen Tanks:Vacuum-insulated vessels store samples at minus 196 degrees Celsius through liquid nitrogen immersion or vapor phase technology. Japan's national biobanking initiative is driving centralized procurement of vapor-phase systems for operator safety compliance in multi-site repository networks.
- Thawing Equipment:Water bath and dry heat systems enable controlled warming of cryopreserved materials.
- Storage Containers:Racks, boxes, and canisters organize specimen inventory within freezer systems.
Cryogenic freezers dominate installed base. Automated storage platforms are where expansion concentrates.
Technology:
Technology selection maps directly to application risk tolerance: vapor phase and dry ice serve research settings with lower regulatory burden, while controlled rate freezing and automated systems command premium positioning in therapeutic manufacturing where post-thaw viability determines commercial value.
- Vapor Phase:Nitrogen vapor maintains cryogenic temperatures without direct liquid contact, eliminating cross-contamination risks and operator splash hazards. Biobanks across the United States are standardizing on vapor-phase infrastructure as FDA 21 CFR Part 11 audit trail requirements extend to storage conditions.
- Controlled Rate Freezing:Programmable cooling curves reduce ice crystal formation through precise thermal ramping, typically 1 degree Celsius per minute for cell suspensions. CAR-T manufacturing sites in Germany and Switzerland require these systems for EMA-validated advanced therapy medicinal product workflows.
- Dry Ice Technology:Solid carbon dioxide achieves minus 78 degrees Celsius for short-term transport and temporary storage.
- Automated Systems:Robotic retrieval and inventory management integrate with laboratory information systems.
Vapor phase technology anchors the majority of installed capacity. Controlled rate freezing is climbing the fastest as cell therapy manufacturing scales.
End User:
Customer type determines procurement sophistication: pharmaceutical companies and biobanks negotiate enterprise frameworks with multi-year service commitments, while research laboratories and hospitals rely on capital budget cycles with shorter replacement horizons.
- Research Laboratories:Academic and government facilities utilize cryopreservation for genomic sample archiving and basic cell biology. Universities in Japan are expanding vapor-phase nitrogen infrastructure under METI-funded precision medicine consortia requiring centralized biorepository access.
- Biobanks:Population-scale repositories manage millions of samples with chain-of-custody documentation. Large-scale biorepositories in the United States are shifting procurement toward automated systems with predictive maintenance contracts to reduce total cost of ownership.
- Hospitals:Clinical settings apply cryopreservation for fertility services and rare disease specimen banking.
- Pharmaceutical Companies:Cell therapy manufacturers require validated equipment for commercial production.
Biobanks represent the largest volume purchaser. Pharmaceutical companies are gaining share fastest as gene therapy pipelines mature.
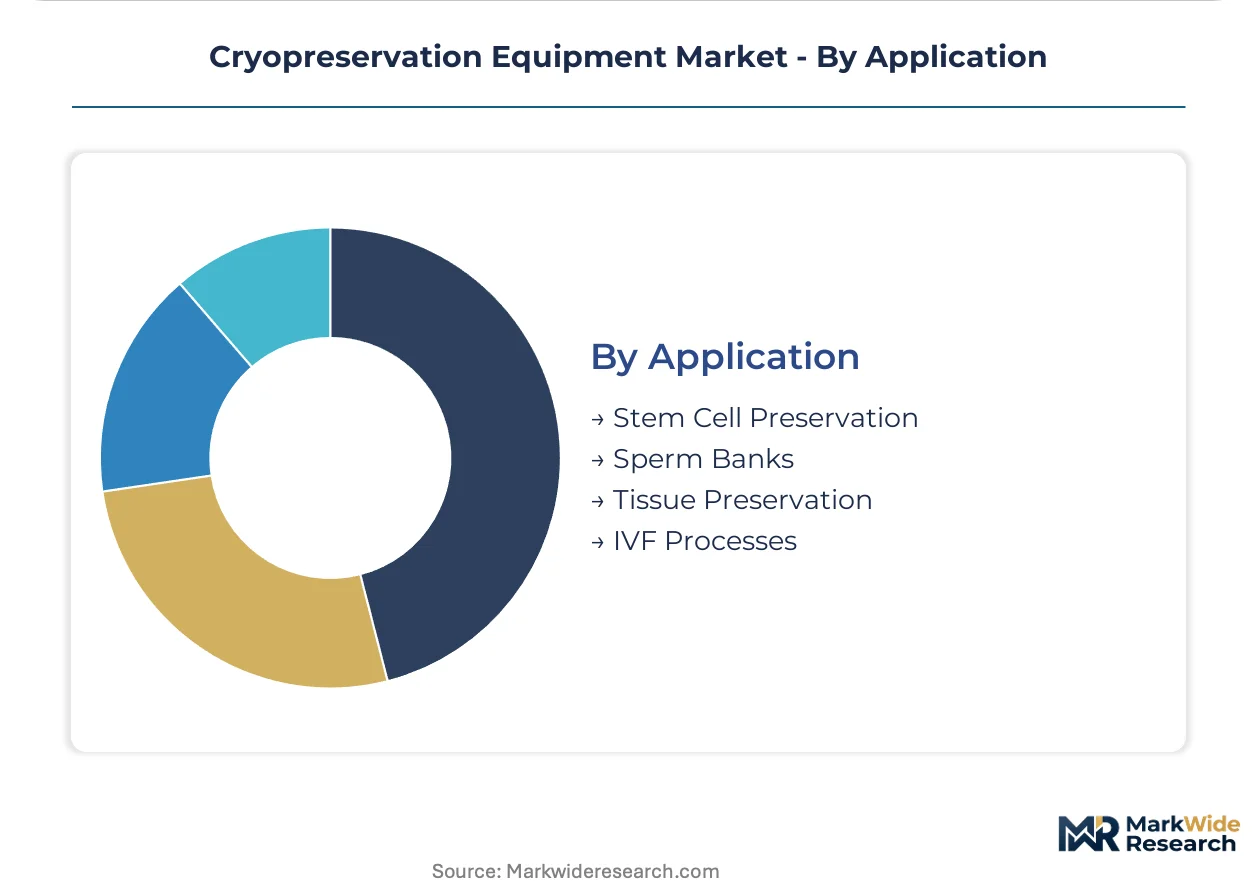
Application:
Application requirements stratify equipment specifications: stem cell and tissue preservation demand ultra-low temperature stability with full traceability, while sperm banking and IVF processes prioritize rapid access and workflow integration.
- Stem Cell Preservation:Long-term viability of pluripotent and hematopoietic stem cells requires sustained minus 150 degrees Celsius or below with continuous temperature monitoring. Cell therapy contract development organizations in Germany face EMA-mandated validation of cryopreservation steps within manufacturing chains.
- Sperm Banks:Reproductive tissue repositories utilize vapor-phase nitrogen systems for indefinite genetic material storage. Fertility clinics in Japan are digitizing cryogenic inventory through integration with laboratory information management systems.
- Tissue Preservation:Organ and tissue samples require controlled-rate freezing to maintain structural integrity.
- IVF Processes:Embryo and oocyte cryopreservation demands rapid warming protocols and workflow efficiency.
Stem cell preservation commands the highest equipment specification tier. Sperm banking is expanding most quickly as reproductive medicine digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany demonstrate low price elasticity as regulatory compliance dominates procurement criteria, while emerging markets in India and Southeast Asia remain highly sensitive to capital expenditure thresholds.
United States
Academic medical centers and cell therapy contract manufacturers drive procurement of automated storage systems with embedded audit trails. FDA 21 CFR Part 11 mandates electronic records for therapeutic manufacturing, compelling vendors to pre-validate quality documentation packages. The Greater Boston biotech corridor anchors demand as CAR-T developers retrofit facilities for commercial-scale production.
Germany
EMA-certified advanced therapy medicinal product workflows require controlled-rate freezing systems with redundant temperature monitoring. The EU MDR tightens validation requirements for equipment used in cell and gene therapy manufacturing chains. The Rhine-Main biopharma cluster around Frankfurt hosts the steepest compliance burden, driving consolidation toward vendors with pre-validated thermal engineering capabilities.
Japan
METI-funded precision medicine consortia expand centralized biorepository networks with vapor-phase nitrogen infrastructure. PMDA guidelines align with international standards for cell therapy manufacturing, accelerating replacement of aging mechanical freezer fleets. The Kanto region around Tokyo concentrates national biobanking procurement as universities digitize cryogenic inventory systems.
India
CDSCO regulatory frameworks for advanced therapies create first-mover opportunity for automated storage vendors entering the market. The PLI scheme for pharmaceuticals incentivizes domestic manufacturing capacity, though cryopreservation equipment remains import-dependent. Maharashtra's biotech corridor in Mumbai-Pune anchors early adoption as contract research organizations scale cell therapy capabilities.
Switzerland
Swissmedic oversight of cell and gene therapy manufacturing elevates specifications for cryopreservation validation documentation. The country's pharmaceutical manufacturing base demands cascade refrigeration systems to eliminate nitrogen handling hazards in EMA-certified production lines. The Basel biopharma cluster drives premium-tier procurement as Novartis and Roche suppliers retrofit for chain-of-custody compliance.
Cryopreservation Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium automation vendors coexist with scaled freezer manufacturers. The vendor base clusters around three strategic positions: end-to-end cold chain integrators, modular equipment fabricators, and specialized robotics developers. Consolidation pressure intensifies as biobanks shift procurement toward multi-year service contracts with guaranteed uptime penalties. Geographic expansion and strategic partnerships represent the dominant competitive moves as vendors seek regional field service density.
Within the integrated systems tier, Thermo Fisher Scientific Inc. and Azenta US Inc. occupy positions anchored by end-to-end portfolio breadth and automated sample management specialization respectively. Haier Biomedical represents the scale-driven archetype competing on manufacturing footprint and modular freezer farm configurations. These three entities exemplify the strategic divergence between premium automation platforms and cost-optimized equipment deployment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Azenta US Inc. |
| MVE Biological Solutions |
| Haier Biomedical |
| PHC Holdings Corporation |
| Merck KGaA |
| Planer, a Hamilton Thorne company |
| Custom Biogenic Systems |
| Chart Industries Inc. |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 and EU MDR certification tiers gate both supplier qualification and price differentiation simultaneously, creating a bifurcated market where validated automation platforms command substantial premiums over standard freezer replacements. Biobank procurement committees now weight total cost of ownership over capital expenditure, unbundling after-sales service from equipment purchase and reshaping how vendors structure lifetime value capture.
Pricing Analysis
Multi-year service contracts with guaranteed uptime penalties now drive lifetime value, particularly for automated storage platforms where predictive maintenance and remote monitoring generate recurring revenue streams. Three-tier pricing structure across premium automation, validated mechanical systems, and standard freezer tiers reflects certification grade and after-sales bundling intensity. Cost compression in the standard freezer tier is intensifying because Haier Biomedical and other scale manufacturers compete aggressively on manufacturing footprint. Academic medical centers in the United States demonstrate lowest price sensitivity due to FDA compliance mandates, while research laboratories in emerging markets remain highly capital-constrained.
Supply Chain Analysis
Extended lead times for cryogenic-grade stainless steel and specialized refrigeration compressors now stretch 16-24 weeks for premium system integrators. Manufacturing concentration rests on the United States, Germany, and China, with vacuum-insulated vessel fabrication concentrated in Czech Republic and Japan. Supply chains draw from liquid nitrogen production facilities, precision temperature sensors, and robotic retrieval components. Single-source vulnerability in industrial gas supply creates operational exposure for vapor-phase dependent biobanks. Distribution runs through direct manufacturer engagement for integrated systems and industrial gas distributors for standard tank replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software convergence in cryopreservation is creating platform-economics dynamics where sample traceability and predictive maintenance capabilities determine vendor lock-in. Interoperability with laboratory information management systems now separates sustainable competitive positions from commodity equipment suppliers.
For Market Incumbents: Shield installed base relationships by embedding predictive analytics and remote diagnostics into service contracts, preempting third-party maintenance entrants. Deepen backward integration into temperature sensor manufacturing to secure supply continuity and margin control. Prioritize ISO 20387 pre-validation documentation packages to accelerate biobank procurement cycles and defend against low-cost competitors with limited quality system resources. For New Entrants and Emerging Players: Lead with software-first positioning targeting reproductive medicine digitization in Japan and India, where laboratory information management system integration remains underpenetrated. Target India's CDSCO-regulated cell therapy buildout as the most penetrable geography, where domestic manufacturing incentives create first-mover windows for automated storage vendors. Pursue partnership-based go-to-market models with established industrial gas distributors to bypass direct field service infrastructure requirements. For Investors and Strategic Acquirers: EU MDR and FDA 21 CFR Part 11 convergence reshapes the acquisition landscape toward vendors with pre-validated quality documentation and regional field service density. Long-term viability over the next decade hinges on automation platform recurring revenue rather than equipment shipment cyclicality. Target acquisition archetype: specialized robotics developers with thermal engineering depth and existing biobank reference sites. Watch for liquid nitrogen supply concentration disruptions as the critical inflection signal for mechanical cascade refrigeration substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Storage Platform Integration | Robotic retrieval systems with LIMS connectivity capture recurring software revenue from biobanks. |
| Pre-validated Quality Documentation Packages | FDA 21 CFR Part 11 and EU MDR compliance bundles compress sales cycles for cell therapy manufacturers. |
| Regional Field Service Density Expansion | Guaranteed uptime contracts require localized technician networks to compete for academic medical center procurement. |
| Predictive Maintenance Capability Development | Remote temperature monitoring and alarm escalation preempt regulatory scrutiny and lock in multi-year service relationships. |
| Mechanical Cascade Refrigeration Scale-up | EMA-certified production lines in Germany and Switzerland demand nitrogen-free alternatives for operator safety compliance. |
Methodological Framework
A spread of perspectives from biobank operations directors, cell therapy manufacturing executives, regulatory affairs specialists, and cryogenic engineering consultants converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation against FDA 510(k) filings, EMA advanced therapy medicinal product guidance documents, ISO 20387 biobanking standards, and hospital procurement database records. Bottom-up equipment shipment modeling and top-down biobank capacity estimates were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled include equipment type, cooling technology, automation level, end-user workflow, application criticality, and regional regulatory cluster across the projection horizon. CAGRs were derived from fitted growth curves anchored to biologics pipeline data and national biobanking initiative funding disclosures. Forecast inputs incorporated cell therapy manufacturing capacity buildout timelines and precision medicine consortium procurement schedules.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and EMA advanced therapy frameworks; material policy shifts would require re-modeling compliance cost burdens and equipment replacement cycles. Revision becomes warranted when liquid nitrogen supply disruptions or F-Gas Regulation acceleration crosses thresholds that fundamentally alter technology substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market