
 Europe Cell and Gene Therapy Thawing Equipment Market | 2026-2036
Europe Cell and Gene Therapy Thawing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cell and Gene Therapy Thawing Equipment Market Foresight
Project finance and equipment leasing for cell therapy manufacturing suites is narrowing the competitive field to firms with strong balance sheets or captive financing arms. Cytiva leverages its integrated bioprocessing portfolio to bundle thawing systems with upstream workflows. Sartorius anchors its position through membrane and filtration adjacencies that create pull-through for temperature-controlled handling equipment. Barkey GmbH specializes in German-engineered precision heating devices that dominate European hospital and blood-bank installations.
Cell and gene therapy thawing equipment encompasses engineered systems that restore cryopreserved biological materials to physiological temperatures without compromising cellular viability through controlled thermal profiles, typically maintaining ramp rates between one and ten degrees Celsius per minute to prevent ice-recrystallization damage. These systems serve the commercial and clinical release of chimeric antigen receptor T-cells, stem-cell derivatives, and viral vectors where post-thaw potency directly determines therapeutic efficacy. Automated thawing systems capture the dominant share of value as pharmaceutical companies scale from clinical-trial batches toward commercial production, while dry heat systems displace water-bath technology amid contamination concerns and EMA sterility expectations. Rapid thawing solutions represent the fastest-expanding technology segment as manufacturers seek to minimize dwell time in the critical zone between minus eighty and minus twenty degrees Celsius where intracellular ice reformulation risks peak.
EMA's Advanced Therapy Medicinal Products regulation and the EU Good Manufacturing Practice Annex 1 revision on sterile manufacturing together mandate validated thawing protocols with documented temperature traceability, forcing equipment vendors to embed continuous monitoring and audit-trail capabilities. REACH compliance on heating-element materials and the EU Medical Device Regulation's Class IIa reclassification for automated systems add compliance layers that favor established suppliers with regulatory affairs infrastructure. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to algorithmic thawing-profile optimization, as this will determine whether machine-learning-enabled systems face additional conformity assessment burdens or gain competitive differentiation through predictive viability scoring.
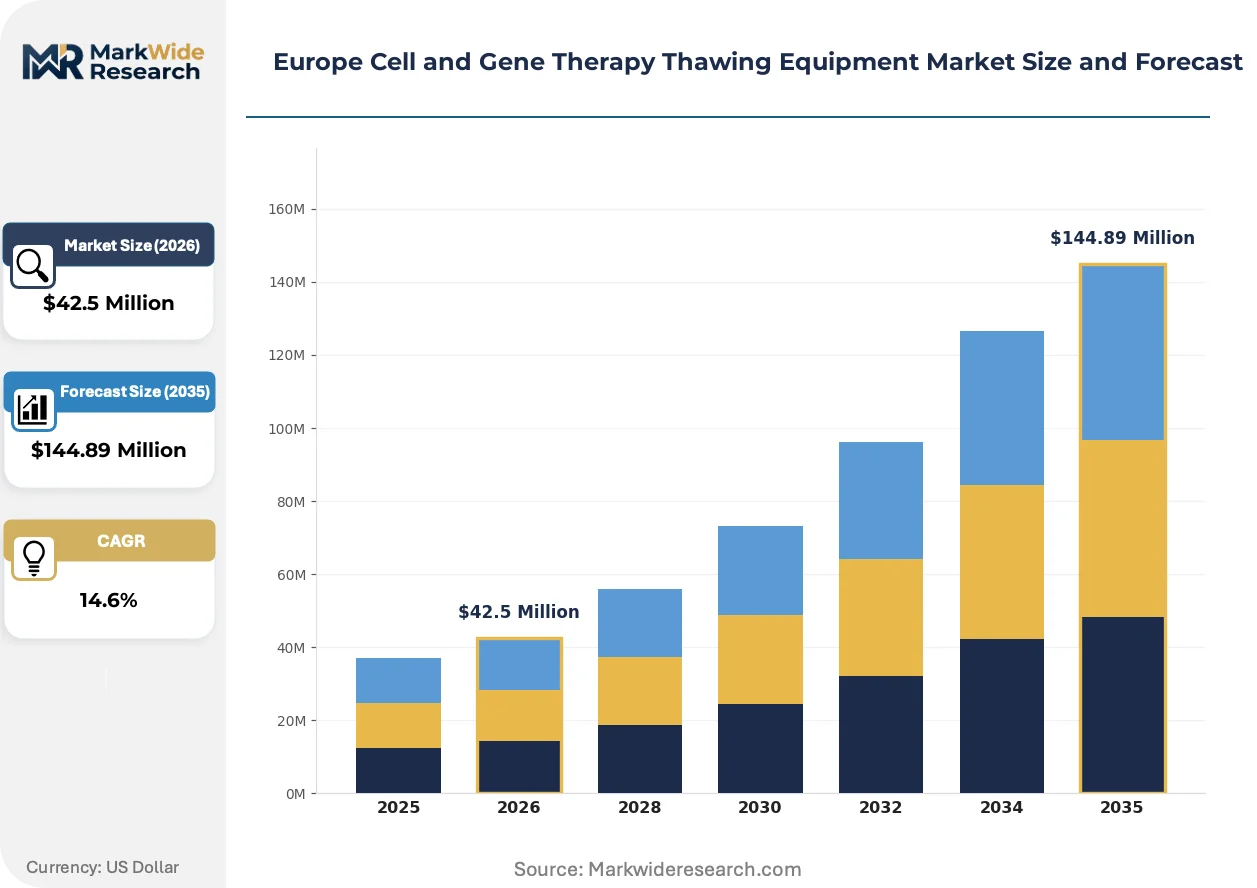
Market Dynamics
EMA's Advanced Therapy Medicinal Products regulation and the EU Good Manufacturing Practice Annex 1 revision on sterile manufacturing are compressing equipment validation timelines and forcing vendors to embed continuous monitoring and audit-trail capabilities as standard features rather than premium add-ons.
Growth Catalysts
- Commercial batch scaling:Contract manufacturing organizations across Germany and the Netherlands are expanding cryopreserved cell therapy production, creating pull-through demand for validated thawing infrastructure with documented temperature traceability.
- REACH compliance on heating-element materials:The European Chemicals Agency's substance restrictions are accelerating replacement cycles for legacy water-bath systems with dry heat alternatives that eliminate contamination vectors.
- Algorithmic thawing-profile optimization:Machine learning-enabled systems are gaining competitive differentiation through predictive viability scoring, though the EU AI Act's risk-classification framework will determine conformity assessment burdens.
Market Restraints
- Supply concentration in precision heating components:German-engineered thermal control modules dominate the subassembly tier, creating vulnerability to input bottlenecks and extended lead times for non-captive manufacturers.
- EU Medical Device Regulation Class IIa reclassification:Automated thawing systems now face elevated conformity assessment burdens that favor established suppliers with regulatory affairs infrastructure and disadvantage newer entrants.
- Technical limitation in rapid thawing:Minimizing dwell time between minus eighty and minus twenty degrees Celsius requires thermal profiles that risk overshoot damage, constraining throughput gains in high-volume manufacturing settings.
Strategic Opportunities
- Underpenetrated Nordic hospital networks:Sweden and Denmark's advanced therapy clinical trial infrastructure lags behind Germany in automated thawing adoption, presenting first-mover positioning for vendors with EMA-compliant documentation packages.
- Technology convergence with single-use bioprocessing:Integrating thawing systems with closed-system cell therapy manufacturing workflows eliminates open-transfer steps and aligns with the EU Good Manufacturing Practice Annex 1 emphasis on contamination control.
- France's academic hospital procurement centralization:The ANSM's tightening oversight of hospital-based advanced therapy preparation is consolidating purchasing authority at the regional level, creating channel efficiency for vendors with national framework agreements.
Industry Challenges
- Cryobiology specialist talent scarcity:The intersection of thermal engineering and cell viability science requires expertise that concentrates in Heidelberg, Munich, and Basel, forcing manufacturers to compete for limited personnel or invest in internal training academies.
- Legacy water-bath infrastructure lock-in:Hospital blood banks across Southern Europe maintain extensive installed bases of manual thawing equipment, creating switching friction despite EMA sterility expectations and contamination incident documentation.
- Integration complexity with manufacturing execution systems:Automated thawing platforms must interface with batch record systems and environmental monitoring networks, requiring custom validation protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cell and Gene Therapy Thawing Equipment Market |
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $144.89 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Thawing Systems, Manual Thawing Devices, Thawing Containers, Temperature-Controlled Systems Application: Clinical Trials, Commercial Production, Research Laboratories, Regenerative Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals Technology: Water Bath, Dry Heat Systems, Microwave Technology, Rapid Thawing Solutions |
| Companies Covered | Cytiva, Thermo Fisher Scientific, Sartorius, BioLife Solutions, Barkey GmbH, Helmer Scientific, PHC Holdings, Brooks Life Sciences, Eppendorf, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cell and Gene Therapy Thawing Equipment Market Shifts & Advancements
Dry heat technology is actively displacing water-bath systems across European cell therapy manufacturing, driven by sterility expectations and the elimination of contamination vectors that EMA documentation increasingly scrutinizes.
Controlled-rate thawing systems are migrating from clinical-trial batch processing toward commercial-scale manufacturing workflows. Pharmaceutical companies scaling chimeric antigen receptor T-cell production are adopting automated platforms that maintain ramp rates between one and ten degrees Celsius per minute. This technology shift is compressing the competitive field to vendors with integrated bioprocessing portfolios and captive financing arms.
EMA's Advanced Therapy Medicinal Products regulation and the EU Good Manufacturing Practice Annex 1 revision together mandate validated thawing protocols with continuous temperature monitoring. Equipment vendors are embedding audit-trail capabilities as standard features rather than premium configurations. Automated systems face elevated conformity assessment burdens under the EU Medical Device Regulation's Class IIa reclassification, favoring established suppliers with regulatory infrastructure.
Regional hospital procurement centralization is consolidating purchasing authority for advanced therapy equipment. France's ANSM oversight and Germany's hospital procurement frameworks are shifting buying decisions from individual clinical sites to regional or national tendering bodies. This channel restructuring favors vendors with framework agreements and dedicated regulatory affairs support across multiple European jurisdictions.
Europe Cell and Gene Therapy Thawing Equipment Market Segmentation
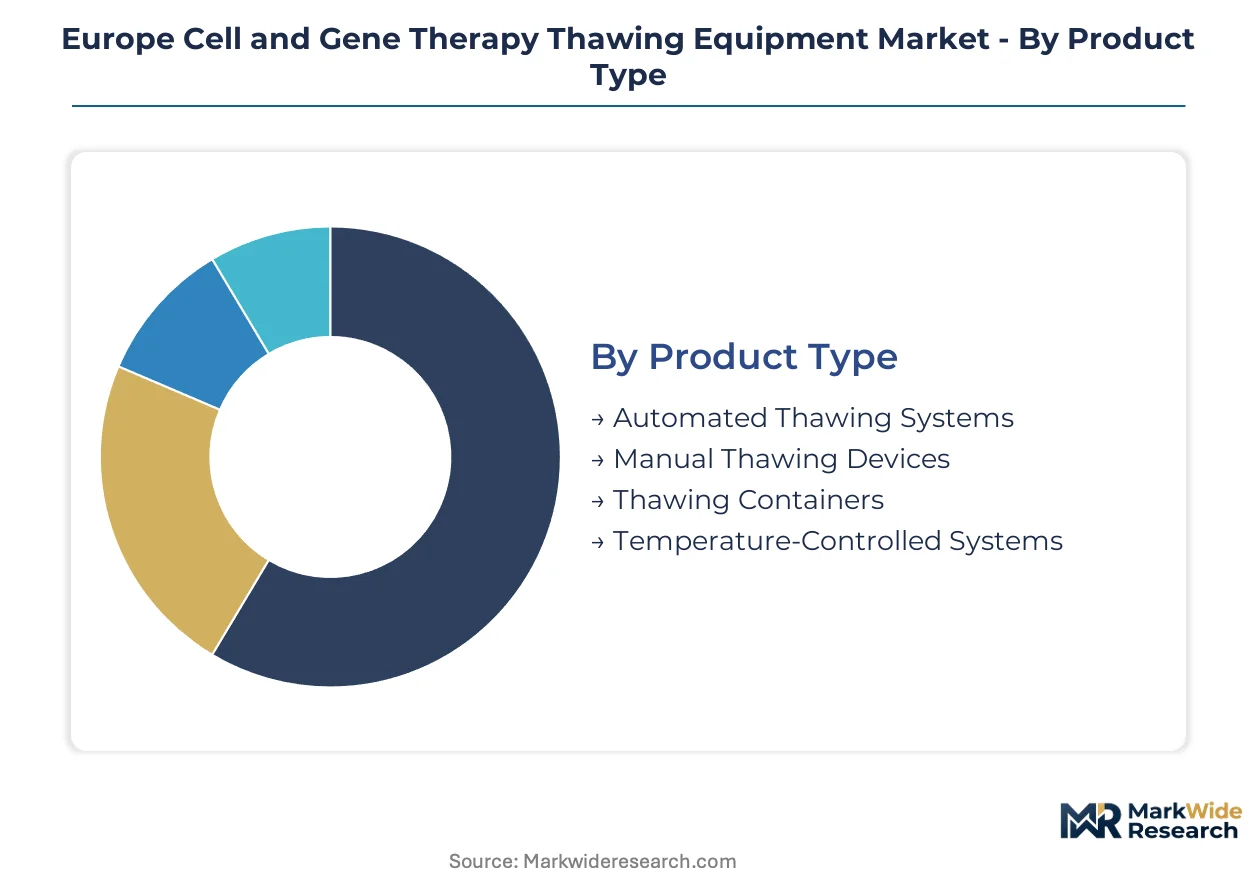
Segmentation in the Europe Cell and Gene Therapy Thawing Equipment Market reveals how clinical workflow demands, regulatory validation requirements, and manufacturing scale interact to shape procurement decisions across the continent. Understanding these divisions enables equipment vendors to align product development with the specific thermal performance and documentation needs of distinct customer clusters.
Product Type:
Automated platforms dominate commercial manufacturing workflows while manual systems retain footholds in research and early-phase clinical settings across Germany, France, and the Netherlands.
- Automated Thawing Systems:These platforms integrate programmable thermal profiles with continuous data logging to satisfy EMA validation requirements for commercial batch release. Demand concentrates among contract manufacturing organizations in Germany's Heidelberg-Munich biotech corridor where throughput scaling and audit-trail documentation are non-negotiable procurement criteria.
- Manual Thawing Devices:Hand-operated water-bath or dry-heat units serve research laboratories and small clinical sites with lower throughput requirements. Southern European hospital blood banks maintain extensive installed bases despite EMA sterility expectations, creating replacement cycle opportunities as contamination incidents drive documentation scrutiny.
- Thawing Containers:Single-use vessels designed for closed-system transfer eliminate open handling steps in cell therapy manufacturing workflows. These products align with EU Good Manufacturing Practice Annex 1 contamination control mandates.
- Temperature-Controlled Systems:Integrated platforms combining thawing with controlled-rate cooling for sample preparation. Research institutions in Switzerland and the Netherlands deploy these for protocol development bridging clinical and commercial phases.
Established volume favors Automated Thawing Systems; emerging adoption favors Temperature-Controlled Systems.
Application:
Commercial production commands premium equipment specifications while clinical trials drive flexibility requirements in system configuration and validation documentation.
- Commercial Production:Large-batch manufacturing of chimeric antigen receptor T-cells and viral vectors requires validated thawing protocols with documented temperature traceability. Contract manufacturing organizations across Germany and the Netherlands are expanding cryopreserved production capacity, pulling through demand for platforms with manufacturing execution system integration.
- Clinical Trials:Phase I and II studies need adaptable thawing equipment supporting variable batch sizes and protocol modifications. Academic hospital networks in France and Sweden prioritize systems with rapid reconfiguration capabilities as trial designs evolve.
- Research Laboratories:Exploratory cell therapy development employs manual and semi-automated systems where cost constraints outweigh validation requirements. Heidelberg and Basel cluster institutions drive specialized demand.
- Regenerative Medicine:Stem-cell derivative processing requires precise thermal control to preserve differentiation potential. German and Swiss tissue engineering centers represent concentrated end-use.
Commercial Production captures the largest equipment investment per site; Clinical Trials represent the fastest-expanding application segment as pipeline assets advance toward registration.
End User:
Pharmaceutical procurement emphasizes regulatory documentation depth while hospital purchasing responds to centralized tendering authority.
- Pharmaceutical Companies:Integrated biopharmaceutical firms and cell therapy specialists require thawing platforms with embedded compliance features for EMA Advanced Therapy Medicinal Products submissions. These buyers prioritize vendors with established regulatory affairs infrastructure across multiple European jurisdictions.
- Biotechnology Firms:Emerging cell therapy developers balance validation requirements against capital constraints, favoring equipment leasing and bundled service agreements. Netherlands-based startups demonstrate strong leasing uptake.
- Research Institutions:University and government laboratories drive early-phase protocol development with flexible, lower-throughput systems. French CNRS and German Max Planck networks maintain significant installed base.
- Hospitals:Regional procurement centralization under France's ANSM and Germany's hospital frameworks is consolidating purchasing authority, favoring vendors with national framework agreements.
Pharmaceutical Companies anchor premium system demand; Biotechnology Firms are gaining share fastest through project financing structures.
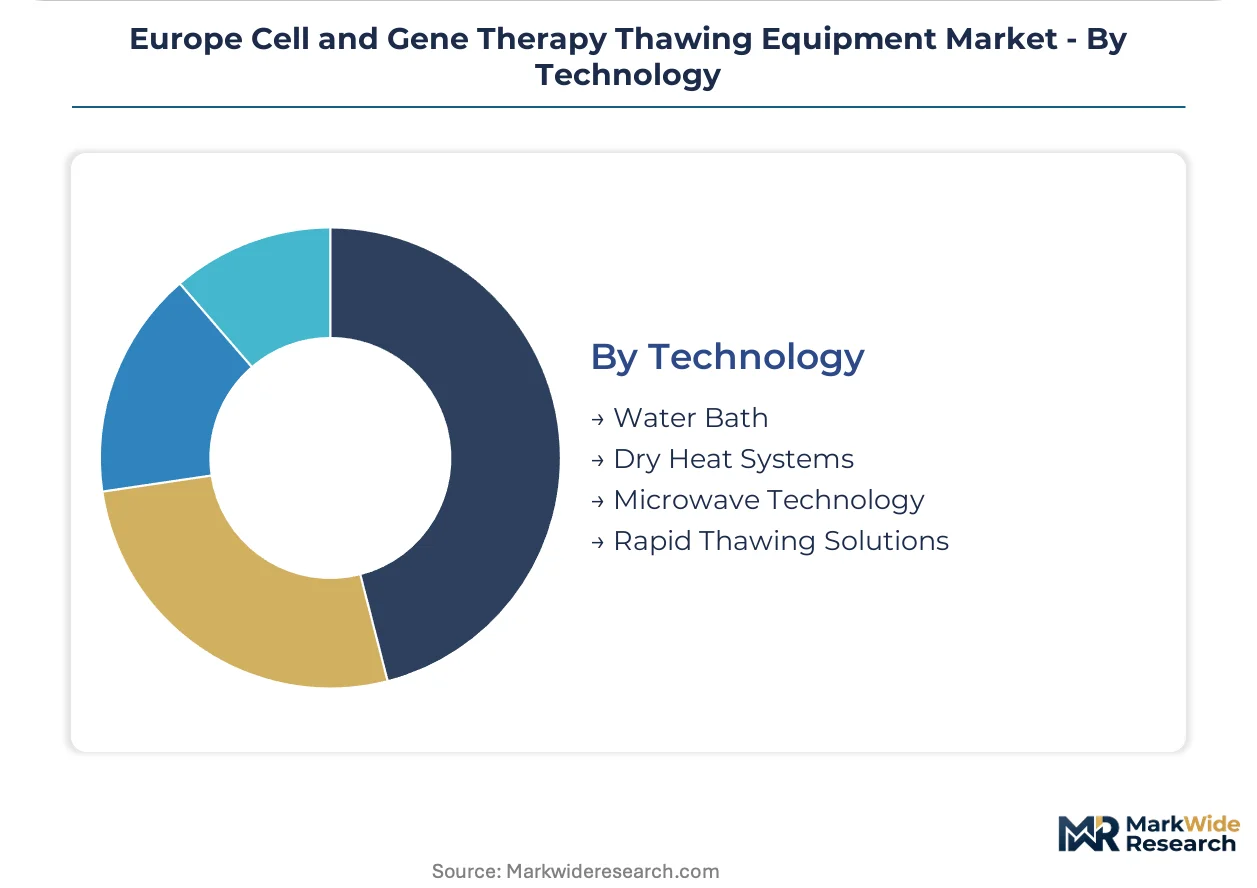
Technology:
Dry heat platforms are displacing legacy water-bath infrastructure as sterility expectations tighten, while rapid thawing solutions address throughput bottlenecks in commercial manufacturing.
- Dry Heat Systems:Electric heating elements eliminate water-bath contamination vectors while maintaining controlled ramp rates between one and ten degrees Celsius per minute. REACH compliance on heating-element materials is accelerating replacement cycles for legacy infrastructure across European manufacturing sites.
- Rapid Thawing Solutions:Advanced thermal transfer technologies minimize dwell time in the critical minus eighty to minus twenty degrees Celsius zone where intracellular ice reformulation risks peak. These systems are expanding most quickly in high-volume chimeric antigen receptor T-cell production facilities.
- Water Bath:Conventional immersion thawing retains presence in budget-constrained settings and legacy installations. Southern European hospital blood banks represent concentrated residual demand.
- Microwave Technology:Electromagnetic heating approaches remain experimental for cell therapy applications due to thermal uniformity challenges. Limited pilot deployment in research settings.
Dry Heat Systems command the dominant installed base; Rapid Thawing Solutions are climbing the fastest as manufacturers prioritize throughput optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's cell and gene therapy thawing equipment trade flows reflect a pronounced import dependency for precision thermal control modules, with German-engineered subassemblies supplying manufacturing sites across the continent while finished systems flow toward Nordic and Southern European clinical hubs.
Germany
Contract manufacturing organizations in the Heidelberg-Munich biotech corridor are expanding commercial cryopreserved cell therapy production, driving demand for validated thawing infrastructure. EMA's Advanced Therapy Medicinal Products regulation mandates documented temperature traceability for batch release. Bavaria's concentration of CAR-T manufacturing facilities anchors the continent's largest installed base of automated thawing platforms.
France
Academic hospital networks in Paris and Lyon are advancing cell therapy clinical trials, creating demand for flexible thawing equipment with rapid reconfiguration capabilities. ANSM's tightening oversight of hospital-based advanced therapy preparation is consolidating purchasing authority at the regional level. The Île-de-France region's procurement centralization favors vendors with national framework agreements.
Netherlands
Biotechnology startups in the Leiden biotech cluster are adopting equipment leasing structures to navigate capital constraints while meeting validation requirements. REACH compliance on heating-element materials is accelerating replacement cycles for legacy water-bath systems. The Randstad region's contract manufacturing expansion is pulling through demand for manufacturing execution system-integrated thawing platforms.
Switzerland
Research institutions in Basel are driving early-phase protocol development with temperature-controlled systems bridging clinical and commercial phases. Swissmedic's alignment with EMA standards ensures regulatory continuity for cross-border supply chains. The Basel-Land canton's tissue engineering centers represent concentrated demand for precision thermal control preserving stem-cell differentiation potential.
Sweden
Advanced therapy clinical trial infrastructure in Stockholm and Uppsala lags behind Germany in automated thawing adoption, presenting first-mover positioning for EMA-compliant vendors. The Swedish Medical Products Agency's implementation of EU Good Manufacturing Practice Annex 1 standards is elevating sterility expectations for hospital blood banks. The Stockholm-Uppsala life science cluster's academic hospital procurement is shifting toward centralized tendering.
Europe Cell and Gene Therapy Thawing Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision thermal control modules to multiple equipment vendors. The vendor structure consolidates around integrated bioprocessing portfolios with captive financing arms, while mid-scale specialists compete on regulatory documentation depth. Two archetypes dominate: diversified life science conglomerates leveraging cross-selling synergies, and focused thermal engineering firms with regional hospital network penetration. Competitive dynamics center on strategic partnerships with contract manufacturing organizations and backward integration into heating-element supply chains.
Among diversified platform vendors, Cytiva and Thermo Fisher Scientific exemplify the integrated bioprocessing archetype, bundling thawing systems with upstream workflows and leveraging global regulatory affairs infrastructure. Sartorius occupies a position anchoring filtration adjacencies that create pull-through for temperature-controlled handling equipment. Barkey GmbH represents the specialized precision engineering tier, with German-engineered heating devices dominating European hospital and blood-bank installations through regional framework agreements.
| Leading Market Players |
|---|
| Cytiva |
| Thermo Fisher Scientific |
| Sartorius |
| BioLife Solutions |
| Barkey GmbH |
| Helmer Scientific |
| PHC Holdings |
| Brooks Life Sciences |
| Eppendorf |
| Others |
Supply & Pricing Matrix
Bavaria's concentration of CAR-T manufacturing facilities concentrates precision thermal module production capacity, creating asymmetric pricing power for German-engineered subassembly vendors serving equipment integrators across the continent. Contract manufacturing organizations in the Heidelberg-Munich corridor face extended lead times for non-captive heating elements, compressing margins on finished systems while elevating premiums for validated platforms with embedded EMA-compliant documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Europe cell and gene therapy thawing equipment market. Premium tiers command substantial markups based on EU Medical Device Regulation Class IIa certification depth and integrated manufacturing execution system compatibility, while economy segments serve research laboratories with stripped-down thermal control. Pricing pressure stems from REACH compliance-driven replacement cycles for legacy water-bath infrastructure, with biotechnology firms demonstrating highest price sensitivity due to project financing constraints and pharmaceutical companies absorbing premiums for regulatory documentation depth.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German thermal control module vendors are tightening working capital requirements for equipment assemblers serving Nordic and Southern European markets. Precision heating element production concentrates in Germany, Switzerland, and Austria, with subassembly tiers drawing from specialized ceramics and platinum temperature sensor supply chains concentrated in Central Europe. Single-source vulnerability in algorithmic thawing-profile optimization chipsets creates procurement risk for machine-learning-enabled platforms, while distribution runs through regional framework agreements with hospital procurement centralization in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
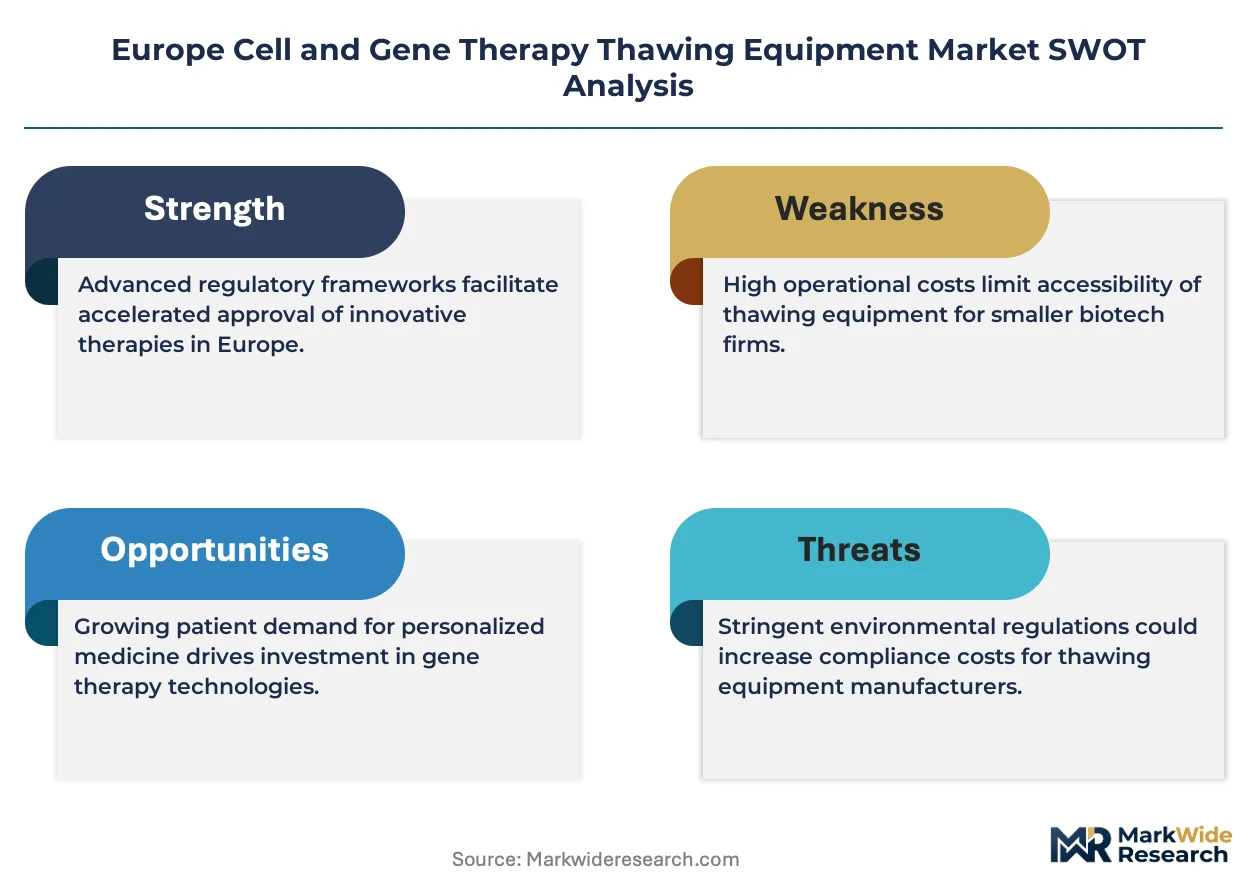
The Europe cell and gene therapy thawing equipment market represents a high-growth disruption driven by EMA's Advanced Therapy Medicinal Products regulation mandating validated thawing protocols with continuous temperature monitoring for commercial batch release.
For Market Incumbents: Pre-empt margin compression from REACH compliance cost pass-through by anchoring captive financing arms for equipment leasing structures that biotechnology startups increasingly demand. Deepen backward integration into platinum temperature sensor supply chains to insulate against German subassembly vendor concentration, while embedding predictive viability scoring algorithms ahead of EU AI Act risk-classification determinations to capture first-mover differentiation. For New Entrants and Emerging Players: Build out regulatory affairs infrastructure targeting Sweden and Denmark's underpenetrated Nordic hospital networks where automated thawing adoption lags Germany's biotech corridor. France's ANSM-driven procurement centralization creates channel efficiency for vendors with national framework agreements, while dry heat technology displacement of water-bath systems in Southern European blood banks offers replacement cycle entry points through contamination incident documentation support. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturing organization-anchored equipment lessors with integrated service agreements spanning validation documentation and manufacturing execution system integration. Long-term viability over the five-to-ten year window favors vendors with cross-jurisdictional EMA-Swissmedic regulatory continuity and captive thermal control module supply. Watch algorithmic thawing-profile optimization regulatory classification under the EU AI Act as the critical inflection signal determining conformity assessment burden distribution and competitive moat depth.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Compliance Documentation Investment | Embedded audit-trail capabilities satisfy EU Good Manufacturing Practice Annex 1 sterile manufacturing mandates for commercial batch release. |
| Dry Heat Technology Platform Migration | Electric heating elements eliminate water-bath contamination vectors while maintaining controlled ramp rates for cell viability preservation. |
| Manufacturing Execution System Integration | Automated thawing platforms interface with batch record systems to compress deployment timelines for contract manufacturing organizations. |
| Regional Framework Agreement Penetration | National tendering authority consolidation under France's ANSM favors vendors with dedicated multi-jurisdictional regulatory affairs support. |
| Algorithmic Thawing-Profile Development | Machine learning-enabled predictive viability scoring awaits EU AI Act risk-classification determining conformity assessment pathways. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cell therapy manufacturing executives, regulatory affairs leads at EMA-notified bodies, hospital procurement managers in France and Germany, and cryobiology specialists concentrated in Heidelberg, Munich, and Basel; alongside secondary validation through EMA Advanced Therapy Medicinal Products submission databases, EU Medical Device Regulation conformity assessment body records, and hospital procurement tender documentation from ANSM and German hospital framework authorities. Bottom-up equipment shipment estimates triangulated against top-down contract manufacturing organization capacity expansion announcements across the analysis window.
Forecast inputs encompassed product type segmentation across automated and manual thawing systems, application tiering between commercial production and clinical trials, technology differentiation between dry heat and rapid thawing solutions, and end-user clustering among pharmaceutical companies, biotechnology firms, and centralized hospital networks. CAGRs were derived from modeled adoption curves for validated thawing infrastructure tied to EMA regulatory enforcement timelines and REACH compliance-driven replacement cycles for legacy water-bath installations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates or specialized thermal engineering firms would shift outcomes. Macroeconomic deviation in European project finance availability, regulatory acceleration in EU AI Act implementation, or breakthrough advances in microwave thermal uniformity for cell therapy applications would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
North America Gene Therapy Market