
 Bio-Inspired and Nano-Engineered Surfaces Market | 2026-2036
Bio-Inspired and Nano-Engineered Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Inspired and Nano-Engineered Surfaces Market Outlook
Aftermarket service revenue from surface recoating and performance validation is tilting toward original equipment manufacturers as end-users seek extended warranty terms and certified lifecycle management. BASF leverages its integrated chemical supply chain to captive-produce nano-particle precursors for self-cleaning formulations. Henkel anchors European medical device coating demand through specialized biomimetic adhesive platforms. SLIPS Technologies differentiates with liquid-infused surface architectures that reduce bacterial adhesion in catheter applications.
Bio-inspired and nano-engineered surfaces are functional interfaces that replicate natural structures such as lotus-leaf micro-roughness or gecko-foot van der Waals forces, typically fabricated through electrospinning, nanolithography, or layer-by-layer assembly to achieve controlled wettability, adhesion, or optical properties. Their primary purpose spans infection prevention in implanted medical devices, drag reduction in fluid-handling systems, and barrier enhancement in food packaging. Anti-microbial coatings lead product type revenue as hospital-acquired infection protocols harden, while water-repellent surfaces in automotive components represent the fastest-growing application segment as electric vehicle thermal management requirements intensify. Biomimetic coatings command premium positioning due to regulatory validation burdens and patent-protected synthesis routes.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern medical device surface commercialization, with ECHA REACH restrictions on perfluorinated compounds forcing substitution toward silicone and polysaccharide-based chemistries. ISO 10993 biocompatibility standards and ASTM E2180 anti-microbial test methods shape product development priorities across healthcare and food packaging end users. Stakeholders must monitor evolving nano-material toxicity classifications under OECD testing guidelines and decide whether to pursue vertical integration into precursor synthesis or secure qualified second-source supply agreements.
Market Dynamics
EU MDR sterilization mandates and ECHA REACH restrictions on perfluorinated compounds are forcing simultaneous chemistry reformulation and validation pipeline rebuilds across medical device coating supply chains.
Growth Catalysts
- Hospital-acquired infection protocols:FDA 510(k) clearance requirements for implantable devices are hardening, accelerating demand for validated anti-microbial surface technologies in catheter and stent applications.
- Electric vehicle thermal management:Water-repellent nano-engineered surfaces are penetrating automotive battery enclosures and cooling systems as OEMs chase efficiency gains.
- REACH substitution mandates:ECHA restrictions on PFAS chemistries are pulling silicone and polysaccharide-based alternatives into commercial production ahead of compliance deadlines.
Market Restraints
- Precursor supply concentration:Nano-particle synthesis capabilities cluster in German industrial clusters around Stuttgart and Dresden, creating qualified-supplier scarcity for non-integrated formulators.
- Biocompatibility validation costs:ISO 10993 testing protocols require 18-24 month certification cycles that compress margins on standardized coating formulations.
- Fluoropolymer substitution friction:Perfluorinated compounds retain performance advantages in extreme-wetting applications, slowing complete phase-out despite regulatory pressure.
Strategic Opportunities
- Food packaging barrier enhancement:Biomimetic surface architectures are penetrating active packaging segments where oxygen and moisture transmission rates determine shelf-life economics.
- Drag reduction in marine transport:Liquid-infused surfaces modeled on shark-skin riblet structures are entering commercial trial with container shipping operators chasing fuel efficiency.
- Aftermarket recoating services:End-users are unbundling performance validation and lifecycle management from equipment purchase, creating service revenue pools for certified applicators.
Industry Challenges
- Cross-functional talent scarcity:Surface engineering roles requiring simultaneous expertise in nanolithography, regulatory affairs, and polymer chemistry command 40% wage premiums over conventional materials science positions.
- Dual certification complexity:Concurrent FDA 510(k) and EU MDR conformity assessments demand parallel documentation streams that strain quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Inspired and Nano-Engineered Surfaces Market |
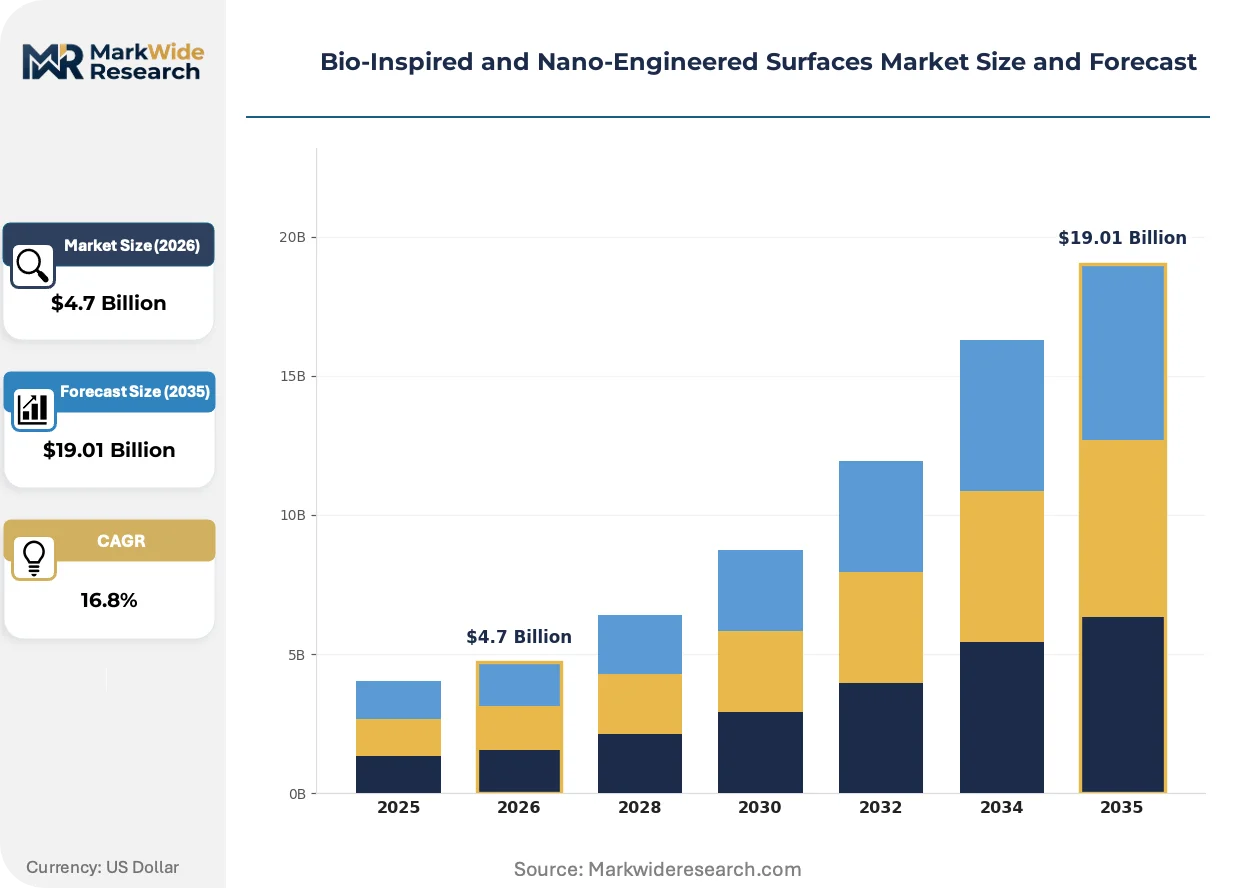
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Cleaning, Anti-Fogging, Anti-Microbial, Water-Repellent Application: Medical Devices, Food Packaging, Textile Coatings, Automotive Components End User: Healthcare, Food Industry, Automotive Manufacturing, Consumer Goods Technology: Electrospinning, Layer-by-Layer Assembly, Nanolithography, Biomimetic Coatings |
| Companies Covered | Nanopool GmbH, Rolith, BASF, Magnolia Solar, Furukawa Kikou, Henkel, PolymerPlus, SLIPS Technologies, Entegris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Inspired and Nano-Engineered Surfaces Market Strategic Shifts
Layer-by-layer assembly and electrospinning fabrication methods are compressing development cycles for functional surface architectures, while regulatory chemistry restrictions are accelerating bio-based feedstock adoption.
Electrospun nanofiber meshes are collapsing the performance gap between conventional anti-microbial coatings and mechanically durable surface architectures. Medical device manufacturers in Germany and the United States are piloting these materials in catheter lumens and implantable sensor housings. The technology is collapsing premium pricing tiers for infection-resistant surfaces as manufacturing scale economies emerge from Fraunhofer institute technology transfers.
REACH Annex XVII restrictions on perfluorooctanoic acid and related substances are forcing coating formulators toward silicone and polysaccharide backbones. Industrial consequence includes 12-18 month reformulation timelines and parallel toxicology dossier preparation for ECHA notification. Medical device segments with extended FDA validation pipelines are most affected, with manufacturers accelerating dual-track chemistry development to preserve market access.
Certified lifecycle management contracts are displacing spot procurement of surface recoating services. Hospital procurement departments in Germany and France are consolidating vendor relationships around extended warranty terms that bundle performance validation with material supply. This concentration is most visible in catheter and endoscope reprocessing workflows, where OEMs are capturing aftermarket revenue streams previously held by independent service providers.
Bio-Inspired and Nano-Engineered Surfaces Market Segmentation
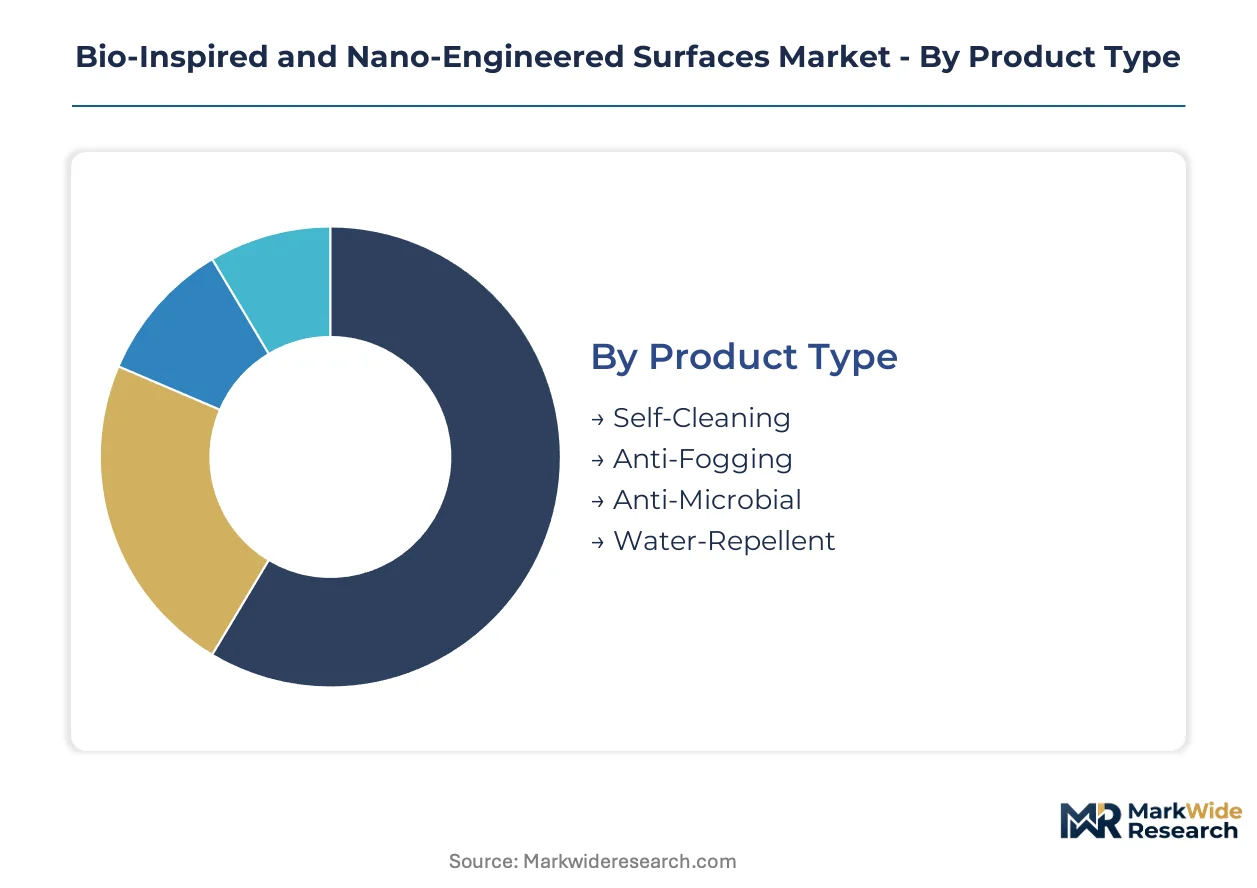
Segmentation in bio-inspired surfaces reveals how fabrication complexity and regulatory burden concentrate margin capture. Product type and application dimensions expose where chemistry reformulation costs collide with end-use performance requirements.
Product Type:
Cost tier stratification separates validated medical-grade formulations from commodity architectural coatings.
- Anti-Microbial:Silver-ion and copper-nanoparticle formulations dominate catheter and implantable device applications. FDA 510(k) clearance requirements in the United States and EU MDR conformity assessments in Germany harden procurement specifications for hospital-acquired infection prevention protocols.
- Water-Repellent:Fluoropolymer alternatives and silicone-based architectures penetrate automotive battery enclosures and cooling systems. ECHA REACH restrictions on perfluorinated compounds force 12-18 month reformulation cycles as formulators rebuild toxicology dossiers for commercial access.
- Self-Cleaning:Lotus-effect micro-roughness surfaces command premium positioning in architectural glass and solar panel applications where soiling resistance determines maintenance economics.
- Anti-Fogging:Hydrophilic polysaccharide coatings serve food packaging and optical device segments with moderate regulatory exposure.
Anti-microbial surfaces hold installed capacity. Water-repellent formulations are rotating up the share rankings.
Application:
End-use maturity separates medical devices with 18-24 month ISO 10993 validation cycles from packaging segments with faster commercialization timelines.
- Medical Devices:Catheter lumens, stent surfaces, and implantable sensor housings absorb the majority of biomimetic coating R&D expenditure. Fraunhofer institute technology transfers in Germany accelerate electrospun nanofiber commercialization for infection-resistant architectures.
- Automotive Components:Electric vehicle thermal management systems drive nano-engineered surface penetration in battery enclosures and cooling circuits. Stuttgart industrial clusters supply integrated OEM development programs with captive precursor synthesis capabilities.
- Food Packaging:Active barrier layers with oxygen and moisture transmission control address shelf-life economics in processed food distribution.
- Textile Coatings:Functional sportswear and protective equipment applications exploit self-cleaning and water-repellent surface architectures with lower regulatory validation burdens.
Medical devices anchor revenue concentration. Automotive components are climbing the fastest as electrification intensifies thermal management requirements.
End User:
Customer type determines procurement sophistication, with healthcare systems bundling lifecycle management contracts against spot purchasing in consumer segments.
- Healthcare:Hospital procurement departments in Germany and France consolidate vendor relationships around extended warranty terms that bundle performance validation with material supply. OEMs capture aftermarket recoating revenue previously held by independent service providers.
- Food Industry:Processors and packagers prioritize oxygen transmission rate performance in active packaging segments where biomimetic barrier enhancement extends distribution reach.
- Automotive Manufacturing:Tier-1 suppliers and OEMs integrate nano-engineered surfaces into thermal management subsystems with qualification requirements tied to platform life cycles.
- Consumer Goods:Electronics and apparel brands access surface technologies through licensed coating applicators with reduced direct regulatory exposure.
Healthcare commands premium pricing. Automotive manufacturing is gaining share fastest as battery platform volumes scale.
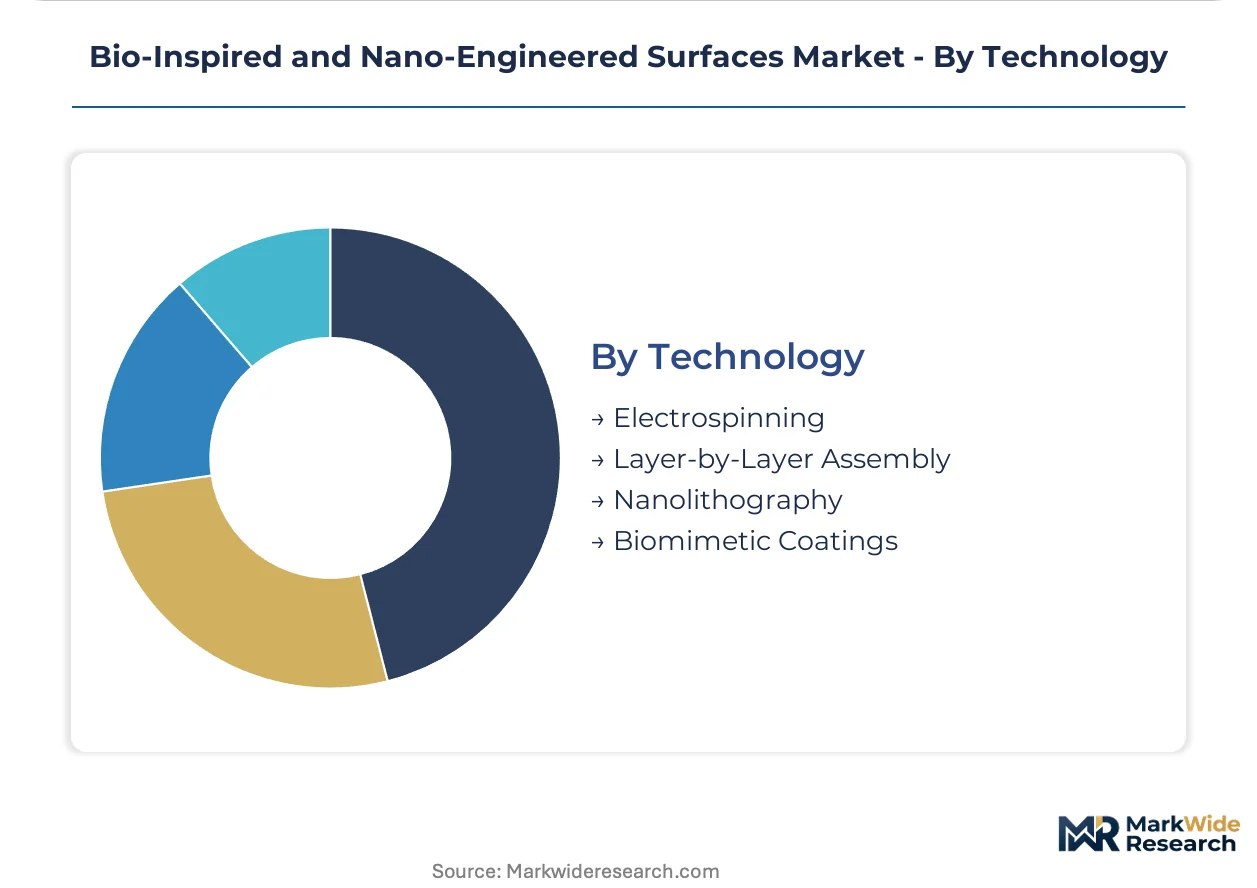
Technology:
Volume scalability separates continuous fabrication methods from batch precision processes.
- Electrospinning:Nanofiber mesh production achieves mechanical durability in anti-microbial catheter applications. Manufacturing scale economies emerge from Fraunhofer institute licensing programs in Germany.
- Biomimetic Coatings:Gecko-foot adhesion and lotus-effect wetting architectures replicate natural structures through polymer chemistry. Patent-protected synthesis routes sustain margin premiums against commodity formulation competition.
- Layer-by-Layer Assembly:Sequential deposition enables precise control over film thickness and functional properties for optical and barrier applications.
- Nanolithography:Patterning precision serves semiconductor and advanced optical device segments with high-value, low-volume production economics.
Electrospinning holds installed capacity. Biomimetic coatings are rotating up the share rankings as natural-structure patents mature into commercial production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement departments prioritize anti-microbial catheter coatings with bundled lifecycle contracts, while United States medical device OEMs concentrate on FDA 510(k) clearance velocity. Chinese battery manufacturers exploit water-repellent nano-surfaces for thermal management in ways that diverge from healthcare-centric European demand patterns.
Germany
Fraunhofer institute technology transfers and Stuttgart-Dresden industrial clusters drive electrospun nanofiber commercialization for infection-resistant medical devices. EU MDR sterilization mandates harden procurement specifications for catheter and stent surface coatings. The Baden-Württemberg region anchors biomimetic coating R&D expenditure through integrated OEM development programs.
United States
FDA 510(k) clearance requirements for implantable devices accelerate validated anti-microbial surface adoption in hospital-acquired infection prevention protocols. EPA oversight of nano-material toxicity classifications shapes reformulation priorities for coating formulators targeting commercial access. The Boston-Cambridge corridor concentrates liquid-infused surface architecture development for reduced bacterial adhesion applications.
China
Electric vehicle battery enclosure manufacturers exploit water-repellent nano-engineered surfaces for thermal management efficiency gains in platform-scale production. NMPA medical device regulations govern surface coating commercialization for domestic healthcare procurement. The Yangtze River Delta industrial belt hosts integrated precursor synthesis capabilities serving automotive OEM development programs.
Japan
PMDA biocompatibility standards and METI industrial technology roadmaps shape nano-surface adoption in precision medical device manufacturing. Layer-by-layer assembly fabrication methods achieve optical and barrier application precision for advanced device segments. The Kansai region around Osaka concentrates electrospinning manufacturing scale economies from technology licensing programs.
Switzerland
Swissmedic regulatory frameworks and precision engineering heritage sustain premium positioning for biomimetic coating formulations in implantable device applications. Patent-protected synthesis routes from academic-industry partnerships defend margin structures against commodity competition. The Basel-Zurich corridor anchors pharmaceutical packaging barrier enhancement development for oxygen transmission rate control.
Bio-Inspired and Nano-Engineered Surfaces Market Competitive Environment
Capability concentration sits with specialized coating formulators possessing ISO 10993 validation pipelines; scale advantage sits with integrated chemical conglomerates controlling nano-particle precursor supply. The market structures around three archetypes: diversified materials science conglomerates with captive synthesis capabilities, mid-size specialists with regulatory-validated medical-grade portfolios, and technology licensing entities transferring Fraunhofer institute IP. Dominant competitive moves include backward integration into precursor production and strategic technology licensing to compress commercialization timelines.
Among diversified chemical conglomerates, BASF and Henkel occupy positions exemplifying integrated supply chain control over nano-particle feedstocks. BASF leverages its Ludwigshafen-based chemical production network for captive supply of self-cleaning formulation precursors. Henkel anchors European medical device coating demand through Düsseldorf-headquartered adhesive and surface technology platforms. SLIPS Technologies represents the technology licensing archetype, transferring liquid-infused surface architectures from Harvard-origin IP to catheter manufacturers seeking reduced bacterial adhesion performance.
| Leading Market Players |
|---|
| Nanopool GmbH |
| Rolith |
| BASF |
| Magnolia Solar |
| Furukawa Kikou |
| Henkel |
| PolymerPlus |
| SLIPS Technologies |
| Entegris |
| Others |
Value Chain & Pricing Dynamics
Stuttgart-Dresden industrial clusters in Germany anchor nano-particle precursor synthesis capacity, translating upstream concentration into pricing leverage for integrated formulators against spot-market buyers. Contract structures bifurcate between long-term offtake agreements with OEMs and project-based procurement from independent applicators, with the former capturing 12-18 month price stability windows.
Pricing Analysis
Long-term offtake contracts dominate medical device coating procurement, with spot purchasing confined to aftermarket recoating services. Price differentiation hinges on ISO 10993 certification tier and volume scale, with validated medical-grade formulations commanding substantial premiums over architectural commodity tiers. Cost compression in standardized water-repellent coatings is intensifying as Chinese battery manufacturers scale thermal management procurement. Hospital procurement departments in Germany exhibit lowest price sensitivity due to bundled lifecycle management requirements, while textile coating buyers in consumer segments drive hardest bargain.
Supply Chain Analysis
Export-control restrictions on nanolithography equipment limit technology flows from Germany, Japan and the United States into Chinese manufacturing bases. Raw material dependencies center on silver-nanoparticle precursors, silicone backbones and electrospinning polymer feedstocks. Single-source vulnerability concentrates around Fraunhofer-licensed electrospinning equipment manufacturers in Baden-Württemberg. Distribution runs through qualified applicator networks for medical device segments and direct OEM supply agreements for automotive thermal management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital procurement departments in Germany and France consolidate vendor relationships around extended warranty bundles, squeezing margins for non-integrated coating formulators.
For Market Incumbents: Build regulatory certification moats through parallel FDA 510(k) and EU MDR submission pipelines. Deepen backward integration into nano-particle precursor synthesis to defend against qualified-supplier scarcity in Stuttgart-Dresden clusters. Expand ISO 10993 validation capacity to capture aftermarket recoating revenue from independent service providers threatened by OEM lifecycle contracts. For New Entrants and Emerging Players: Build out food packaging barrier enhancement capabilities where oxygen transmission rate performance demands outpace established supplier capacity. Target active packaging segments in processed food distribution with faster commercialization timelines than medical device validation cycles. Pursue licensing partnerships with Fraunhofer institutes to compress electrospinning technology transfer timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-size specialists with regulatory-validated medical-grade portfolios over diversified chemical conglomerates facing margin pressure. Long-term viability rests on chemistry reformulation capabilities responding to ECHA REACH substitution mandates. Watch for inflection signals in PFAS phase-out compliance deadlines forcing accelerated silicone and polysaccharide adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | BASF's Ludwigshafen captive supply secures nano-particle feedstock against qualified-supplier scarcity. |
| Dual-Track Chemistry Development | Parallel silicone and fluoropolymer pipelines preserve market access through ECHA REACH transition periods. |
| Fraunhofer Technology Licensing | Electrospinning IP transfers from Baden-Württemberg compress infection-resistant surface commercialization cycles. |
| Extended Warranty Bundling | Henkel's lifecycle contracts with German hospital procurement displace independent aftermarket service providers. |
| Food Packaging Barrier Expansion | Oxygen transmission rate control addresses shelf-life economics in active packaging distribution networks. |
Study Parameters
The analysis maps anti-microbial coatings, water-repellent surfaces, self-cleaning architectures and electrospinning fabrication methods, each validated through biomedical engineers, hospital procurement managers, GPO contracts directors and coating formulator R&D leads. Primary interviews with these stakeholders triangulate against FDA 510(k) clearance databases, EMA MDR submission records, ECHA REACH restriction notices and ISO 10993 biocompatibility test registries. Bottom-up volume builds from catheter, stent and battery enclosure unit forecasts reconcile with top-down chemical industry revenue allocations.
Assumptions held fixed include EU MDR sterilization mandate compliance timelines and ECHA perfluorinated compound restriction phase-out schedules; variables stress-tested encompass electric vehicle platform adoption rates and hospital-acquired infection protocol stringency. The projection horizon segments by product type, application, end user and fabrication technology, with CAGRs derived from regression analysis against precursor supply capacity expansion and regulatory validation pipeline throughput. Electrospun nanofiber manufacturing scale economies and biomimetic coating patent expiration schedules inform growth trajectory calibration.
Stress conditions across REACH Annex XVII enforcement intensity, FDA 510(k) clearance velocity and Fraunhofer technology licensing throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in ECHA PFAS substitution deadlines or NMPA medical device regulatory alignment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanobody Market