
 Global Biocompatibility Testing Services Market | 2026-2036
Global Biocompatibility Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biocompatibility Testing Services Market Analysis
Contract laboratory networks is tilting toward regional hub-and-spoke models as medical device sponsors seek faster turnaround for regulatory submissions. Eurofins Scientific leverages its European GLP campus network to anchor biocompatibility workflows for active implantable devices. SGS SA competes through dedicated biological evaluation centers in Asia-Pacific manufacturing corridors. Charles River Laboratories dominates North American preclinical toxicology with integrated in-vivo and in-vitro capabilities for pharmaceutical-device combination products.
Biocompatibility testing services encompass the analytical and biological evaluation of materials intended for contact with human tissue, blood, or physiological systems, encompassing cytotoxicity assays, sensitization studies, hemocompatibility panels, and systemic toxicity evaluations performed under GLP and ISO 17025 protocols. These services verify that polymers, metals, ceramics, and biological scaffolds meet safety thresholds before clinical use. Biological evaluation currently leads service revenue as implantable device portfolios expand, while toxicological assessment grows fastest from pharmaceutical firms adopting combination product frameworks. Chemical testing occupies a mature margin pool where extractables and leachables protocols for drug delivery systems sustain steady contract volumes.
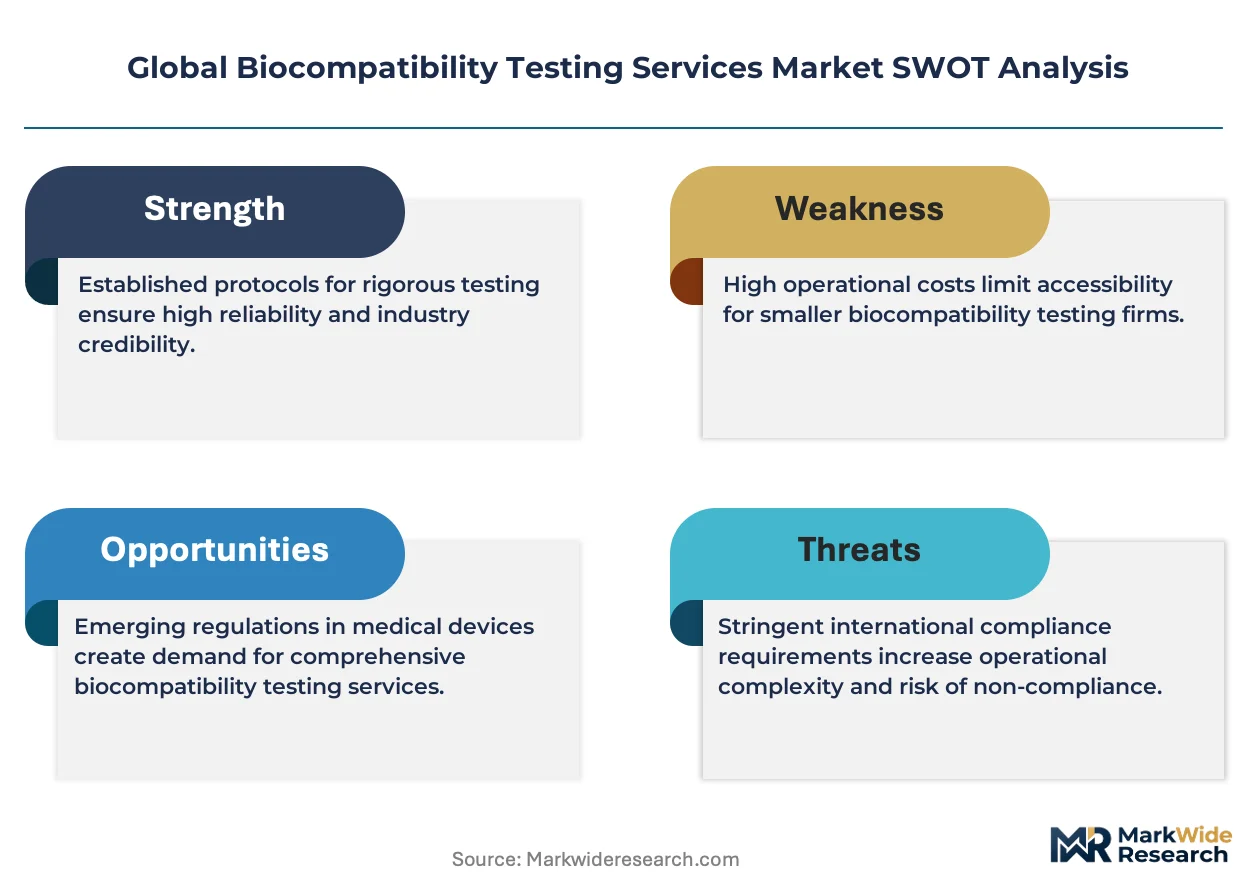
FDA's 21 CFR Part 58 GLP regulations and the European Medicines Agency's MDR clinical evaluation requirements shape testing scope and documentation depth for market access in the United States and European Union, while ISO 10993 series standards provide the technical backbone for biological risk management across jurisdictions. China's National Medical Products Administration now mandates domestic biocompatility data for Class III device registrations, adding regulatory complexity for multinational sponsors. Stakeholders must monitor divergence between FDA's updated ISO 10993-1 use guidance and EMA's evolving expectations for animal testing alternatives when allocating R&D testing budgets across development pipelines.
Market Dynamics
The ISO 10993 revision cycle is compressing traditional animal study timelines while elevating in-vitro method validation requirements, forcing contract laboratories to reconfigure capability portfolios around organ-on-chip and 3D tissue model investments.
Growth Catalysts
- MDR implementation deadlines:European cardiovascular and orthopedic implant manufacturers must complete biological evaluation documentation under the Medical Device Regulation framework, expanding toxicological assessment contracts.
- Combination product proliferation:Pharmaceutical-device hybrids incorporating drug-eluting stents and sustained-release implants require integrated biocompatibility and extractables-leachables testing protocols.
- Switzerland and Singapore:Specialized toxicological assessment providers in these jurisdictions attract outsourced work from multinational sponsors seeking ISO 17025-accredited alternatives to traditional GLP sites.
Market Restraints
- ISO 10993-2 animal testing constraints:The European Union's restrictions on in-vivo studies for sensitization and systemic toxicity limit method options for certain material categories.
- GLP facility concentration:North American and Western European laboratory networks control the majority of FDA- and EMA-recognized study execution capacity.
- Qualified pathologist scarcity:Histopathological evaluation of implant tissue responses requires board-certified veterinary pathologists with device-specific experience.
Strategic Opportunities
- China's NMPA domestic data mandate:Class III device registrations now require in-country biocompatibility studies, creating demand for joint-venture laboratory construction.
- Organ-on-chip convergence:Microfluidic tissue models paired with computational toxicology platforms enable predictive screening before formal GLP study initiation.
- Digital pathology workflows:Whole-slide imaging and AI-assisted histomorphometry accelerate turnaround for chronic implantation studies.
Industry Challenges
- Study director qualification gaps:FDA and EMA both require documented experience in device-specific biological evaluation, constraining workforce expansion.
- Legacy equipment integration:Automated liquid handling and high-content imaging systems must interface with validated 21 CFR Part 11 data environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biocompatibility Testing Services Market |
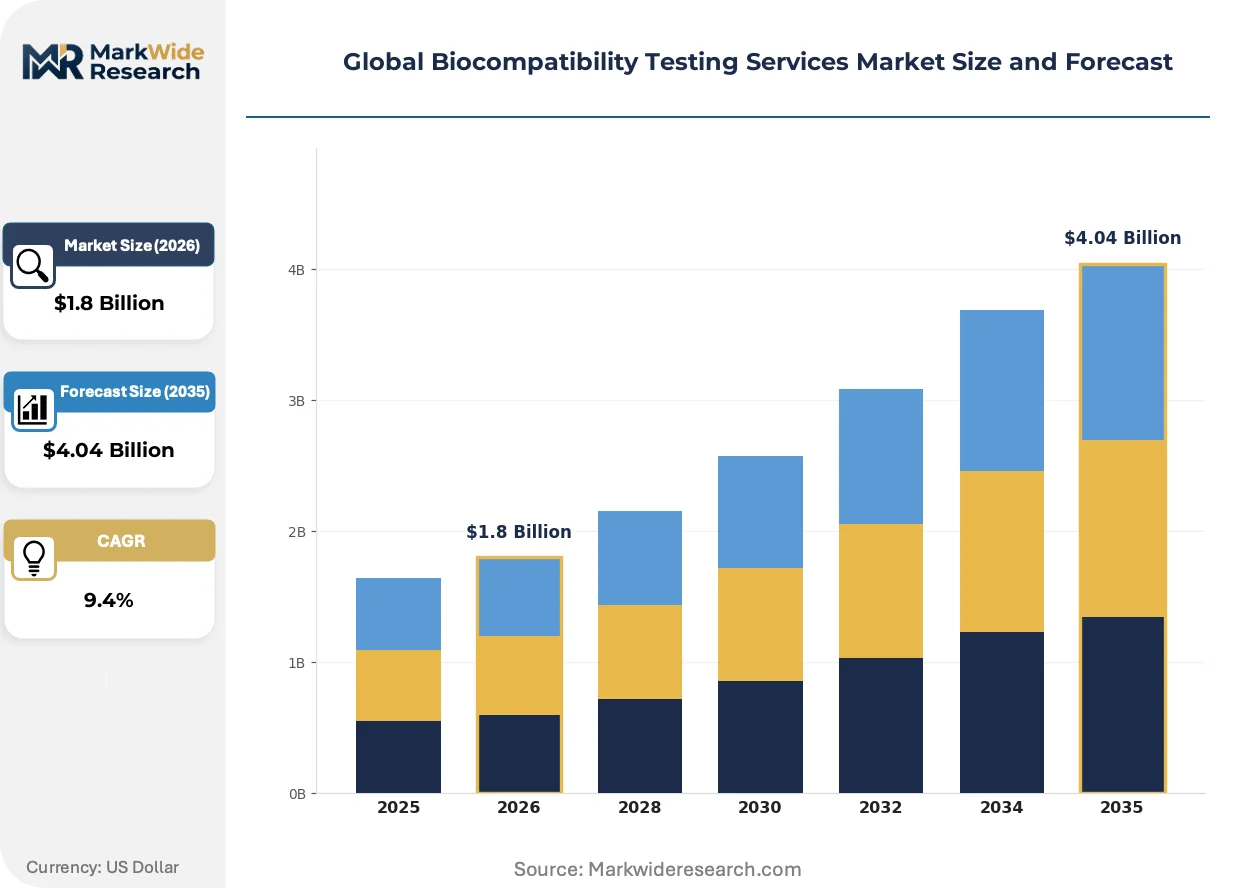
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Testing, Chemical Testing, Biological Evaluation, Toxicological Assessment Product Type: Medical Devices, Pharmaceuticals, Implants, Tissue Engineering End User: Biotechnology Companies, Pharmaceutical Firms, Research Institutions, Contract Research Organizations Method: In Vitro Testing, In Vivo Testing, Simulation Testing, Risk Assessment |
| Companies Covered | Eurofins Scientific, SGS SA, Charles River Laboratories, WuXi AppTec, Nelson Laboratories, Toxikon Corporation, North American Science Associates Inc. (NAMSA), Intertek Group plc, Pace Analytical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biocompatibility Testing Services Market Emerging Trajectories
Methodological substitution is accelerating across the biocompatibility testing value chain, with computational and engineered tissue approaches displacing traditional in-vivo protocols while regulatory frameworks scramble to validate equivalence.
Microphysiological systems integrating human-derived organoids with continuous perfusion platforms now replicate systemic immune responses to implant materials with greater translational fidelity than rodent models. Active implantable device manufacturers in Germany and the United States have adopted these platforms for early-phase material screening, compressing lead candidate selection from months to weeks. The technology is rendering obsolete the standard 72-hour direct contact cytotoxicity assay as a gatekeeping step in development pipelines.
EMA's evolving expectations for animal testing alternatives under the MDR framework now explicitly reference OECD Test Guidelines and ISO 10993-6 histopathological scoring harmonization. This policy shift forces contract laboratories to maintain dual-method capability portfolios while awaiting formal validation acceptance. Cardiovascular implant sponsors face the highest documentation burden, as hemocompatibility endpoints lack standardized in-vitro correlates for thrombogenicity assessment.
Device sponsors now unbundle biological evaluation contracts across specialized providers rather than consolidating with full-service CROs, fragmenting purchasing authority between regulatory affairs and procurement functions. This pattern concentrates contract value with niche toxicological assessment laboratories possessing specific ISO 10993 part-standard accreditation. The shift is most visible in Swiss and Singaporean hubs where mid-size providers compete on turnaround velocity rather than scope breadth.
Global Biocompatibility Testing Services Market Segmentation
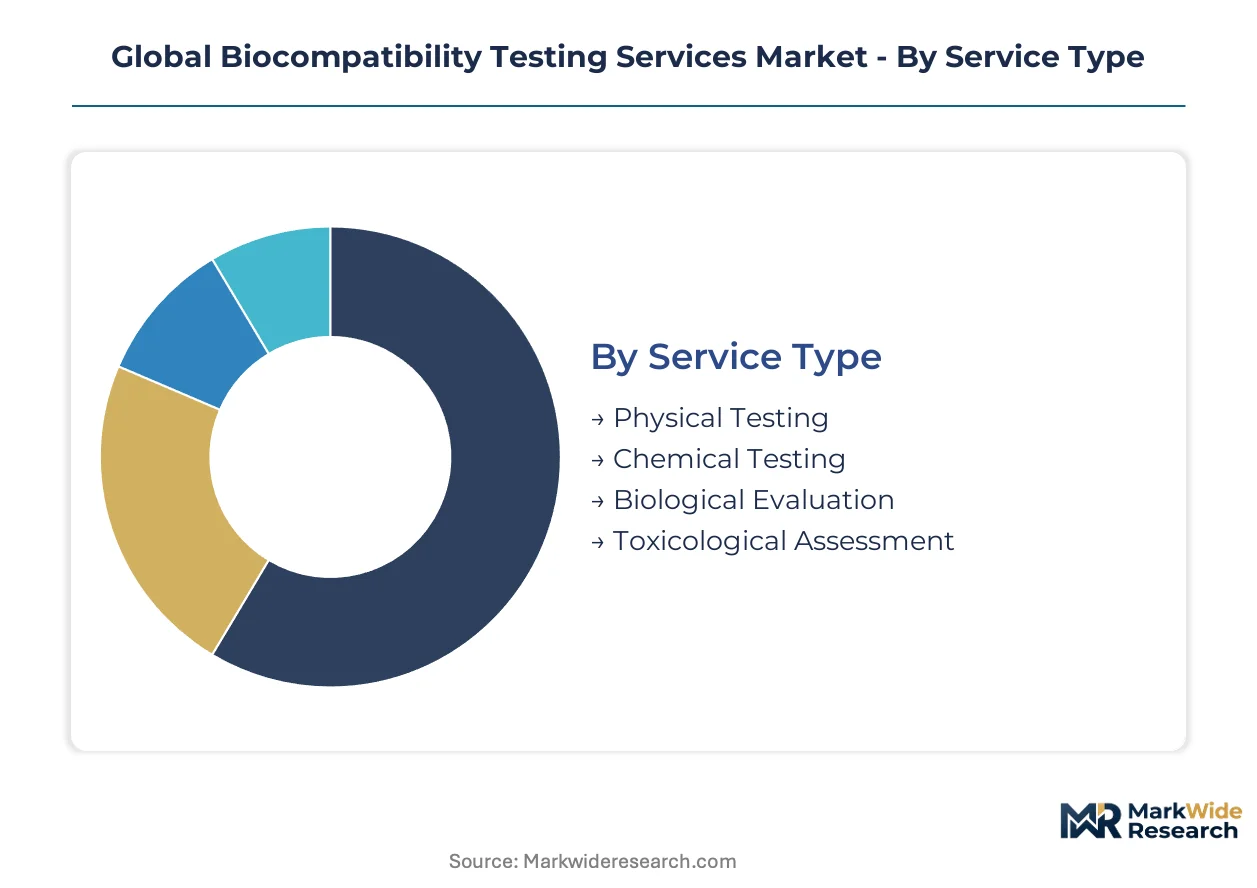
Biocompatibility testing services fragment across technical, regulatory, and customer dimensions that dictate contract value, margin structure, and capability requirements. Each segmentation axis reveals distinct competitive dynamics: service type determines accreditation intensity, product type shapes study complexity, end user governs procurement authority, and method selection constrains regulatory acceptance.
Service Type:
Chemical testing cycles compress to weeks while toxicological assessment timelines stretch across quarters as validation requirements intensify.
- Physical Testing:Mechanical property verification and surface characterization for metals, ceramics, and polymers under ISO 17025 protocols. Orthopedic implant manufacturers in Germany and the United States drive contract volume for fatigue and wear resistance documentation ahead of MDR and FDA submissions.
- Chemical Testing:Extractables and leachables quantification using chromatographic and spectroscopic methods for drug-device combination products. Pharmaceutical sponsors in Switzerland outsource these protocols to specialized laboratories seeking faster turnaround than full-service CRO networks.
- Biological Evaluation:Cytotoxicity, sensitization, and irritation screening per ISO 10993-5, -10, and -23 standards.
- Toxicological Assessment:Systemic toxicity and carcinogenicity evaluation for long-term implantable devices.
Biological Evaluation anchors the volume base while Toxicological Assessment gains share at the steepest rate.
Product Type:
Implant portfolios command premium pricing tiers against commoditized pharmaceutical screening as regulatory documentation depth diverges.
- Medical Devices:Surface and blood-contacting device evaluation spanning Class I through Class III regulatory categories. Cardiovascular and neurological device sponsors in the United States concentrate demand for hemocompatibility and chronic implantation studies under FDA 21 CFR Part 58.
- Implants:Orthopedic, dental, and soft-tissue implant biological evaluation with extended follow-up protocols. German manufacturers face compressed MDR transition timelines that expand outsourcing to Swiss and Singaporean assessment providers.
- Pharmaceuticals:Container closure and delivery system biocompatibility for parenteral and ophthalmic formulations.
- Tissue Engineering:Scaffold and regenerative medicine product characterization for novel biological materials.
Medical Devices generates the largest contract flow while Implants deliver the highest margin per study.
End User:
Procurement centralization varies sharply: pharmaceutical firms consolidate authority while biotechnology companies fragment purchasing across functional silos.
- Pharmaceutical Firms:Integrated biocompatibility and extractables-leachables programs for combination product pipelines. Large sponsors in the United States and Germany unbundle contracts across specialized toxicological assessment providers rather than consolidating with full-service networks.
- Contract Research Organizations:Subcontracted biological evaluation capacity for mid-size device sponsors lacking in-house GLP infrastructure. Asia-Pacific manufacturing corridors concentrate demand for regional hub-and-spoke laboratory configurations.
- Biotechnology Companies:Early-stage material screening and regulatory strategy support for novel therapeutic platforms.
- Research Institutions:Academic and government-funded biocompatibility studies for pre-competitive safety databases.
Pharmaceutical Firms commit the largest annual contract values while Biotechnology Companies expand most quickly as novel therapeutic platforms proliferate.
Method:
Regulatory acceptance timelines separate validated in-vivo approaches from emerging alternatives still awaiting formal equivalence recognition.
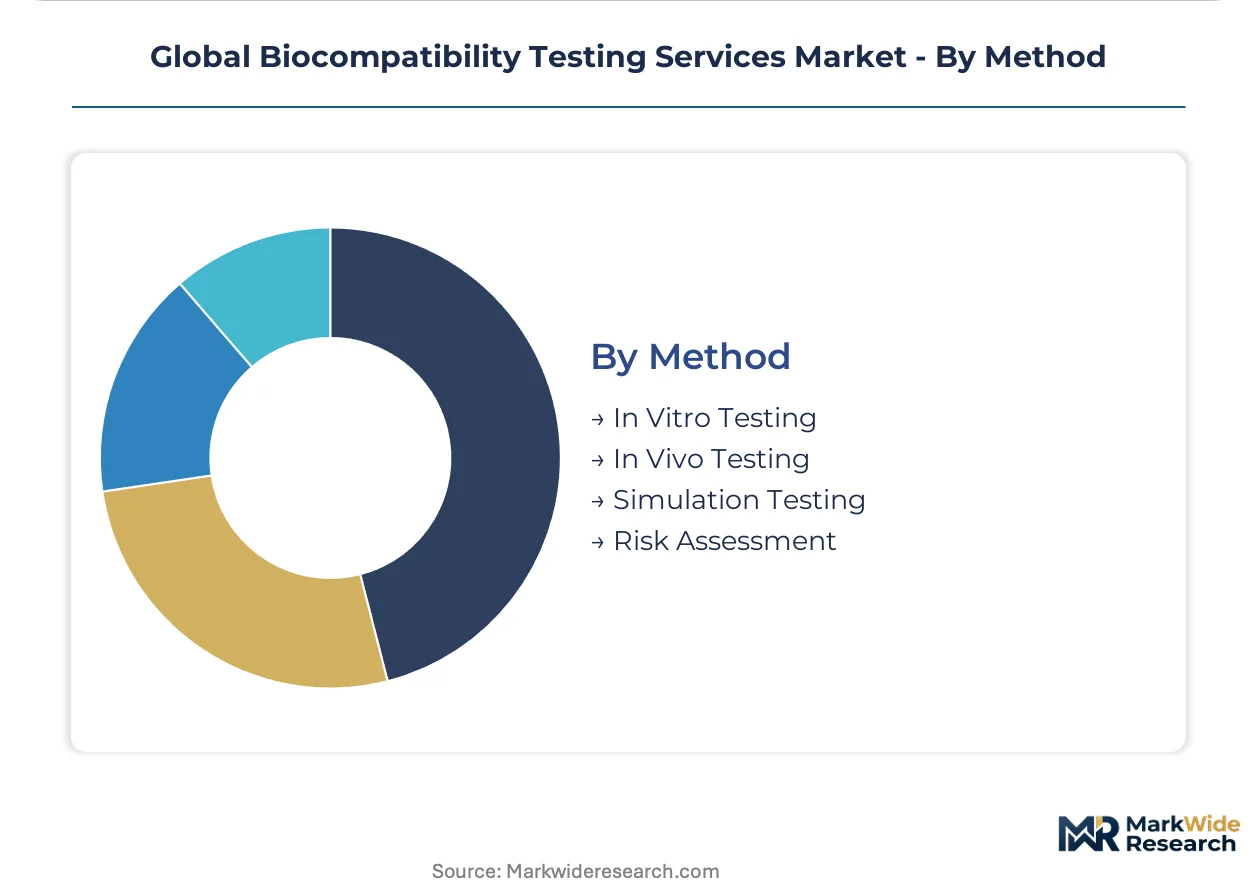
- In Vitro Testing:Cell culture and engineered tissue models for cytotoxicity and irritation endpoints. Microphysiological systems integrating human-derived organoids now compress lead candidate selection from months to weeks for active implantable device manufacturers.
- In Vivo Testing:Animal study protocols for sensitization, systemic toxicity, and implantation responses under GLP conditions. EMA restrictions on animal testing for certain endpoints constrain method availability for European Union market submissions.
- Simulation Testing:Computational toxicology and finite element modeling for preliminary risk screening.
- Risk Assessment:Biological evaluation plan development and gap analysis per ISO 10993-1 frameworks.
In Vivo Testing retains the largest regulatory submission footprint while In Vitro Testing climbs the fastest as OECD Test Guidelines gain formal acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 21 CFR Part 58 GLP regulations anchor the United States as the dominant geography for biocompatibility testing demand. The analysis spans five countries where regulatory frameworks and manufacturing concentration drive contract laboratory expansion.
United States
Cardiovascular and neurological device sponsors concentrate demand for hemocompatibility studies in the Minneapolis and Boston corridors. FDA's updated ISO 10993-1 use guidance shapes documentation requirements for pharmaceutical-device combination products. The Research Triangle Park cluster in North Carolina anchors preclinical toxicology capacity for active implantable devices.
Germany
Orthopedic implant manufacturers in Baden-Württemberg and Bavaria face compressed MDR transition timelines through 2026. The German Federal Institute for Drugs and Medical Devices enforces biological evaluation documentation standards for Class III device registrations. Swiss contract laboratories near the Basel-Zurich corridor capture overflow demand from German sponsors seeking faster turnaround.
Switzerland
Specialized toxicological assessment providers in Basel and Zurich attract outsourced work from multinational sponsors seeking ISO 17025-accredited alternatives. Swissmedic's alignment with MDR requirements streamlines European market access documentation. The Basel biotech cluster concentrates niche providers competing on turnaround velocity rather than scope breadth.
China
NMPA's domestic data mandate for Class III device registrations forces multinational sponsors to construct joint-venture laboratory capacity in Shanghai and Suzhou. The Yangtze River Delta manufacturing corridor concentrates demand for regional biocompatibility testing infrastructure. Domestic contract laboratories in the Beijing-Tianjin-Hebei cluster expand GLP capabilities to serve local pharmaceutical-device sponsors.
Singapore
Asia-Pacific manufacturing corridors route biological evaluation contracts to Singaporean laboratories with ISO 10993 part-standard accreditation. The Health Sciences Authority's recognition of OECD Test Guidelines accelerates in-vitro method validation acceptance. The Tuas biomedical manufacturing cluster anchors specialized toxicological assessment providers serving regional device sponsors.
Global Biocompatibility Testing Services Market Vendor Landscape
Full-service CRO networks and specialized toxicological assessment laboratories split the market along capability breadth versus turnaround velocity. The vendor base concentrates in North American and Western European laboratory networks controlling FDA- and EMA-recognized study execution capacity. Three archetypes dominate: integrated preclinical toxicology providers with in-vivo and in-vitro capabilities, regional hub-and-spoke contract laboratory networks, and niche ISO 17025-accredited specialists. Competitive moves center on M&A to fill capability gaps and strategic partnerships to access organ-on-chip platforms.
Within the integrated preclinical toxicology tier, Charles River Laboratories exemplifies the North American anchor position through combined pharmaceutical and device testing infrastructure. Eurofins Scientific represents the European hub-and-spoke model leveraging GLP campus networks across multiple jurisdictions. SGS SA occupies the Asia-Pacific specialist position through dedicated biological evaluation centers in manufacturing corridors.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Charles River Laboratories |
| WuXi AppTec |
| Nelson Laboratories |
| Toxikon Corporation |
| North American Science Associates Inc. (NAMSA) |
| Intertek Group plc |
| Pace Analytical Services |
| Others |
Supply Flow & Price Mechanics
The Basel-Zurich corridor's specialized toxicological assessment capacity creates asymmetric pricing power for ISO 17025-accredited laboratories serving German cardiovascular implant manufacturers under compressed MDR timelines. Contract value concentrates with providers offering validated in-vitro alternatives, while full-service CROs absorb margin compression from extended study director qualification requirements.
Pricing Analysis
Price spreads between Swiss specialist laboratories and North American GLP campuses widen as EMA animal testing restrictions elevate in-vitro method premiums. Three-tier pricing structure across premium GLP, standard ISO 17025, and economy screening tiers differentiates by certification level and regulatory submission jurisdiction. Cost compression in standard-tier chemical testing intensifies because pharmaceutical sponsors unbundle extractables-leachables contracts for faster turnaround. Biotechnology companies exhibit highest price sensitivity due to constrained early-stage budgets, while cardiovascular device sponsors prioritize documentation depth over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning as NMPA domestic data mandates force joint-venture laboratory construction in Shanghai and Suzhou. Laboratory capacity concentrates in the United States, Germany, and Switzerland, with raw material dependencies spanning validated reagent suppliers, pathologist training programs, and organ-on-chip platform partnerships. Single-source vulnerability in qualified study director pools constrains workforce expansion across FDA and EMA submission pipelines. Distribution runs through regional hub-and-spoke networks anchored by Eurofins Scientific's European GLP campuses and SGS SA's Asia-Pacific biological evaluation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biocompatibility testing market sits at a platform-economics inflection where microphysiological system interoperability creates winner-take-most dynamics among laboratories with validated organ-on-chip partnerships. Ecosystem convergence between computational toxicology platforms and GLP documentation workflows will determine competitive survival.
For Market Incumbents: Insulate core GLP revenue streams by acquiring ISO 10993-6 histopathological scoring capabilities ahead of EMA formal validation acceptance for in-vitro alternatives. Deepen backward integration into organ-on-chip platform partnerships to secure early-phase screening lock-in with active implantable device manufacturers. The threat of Swiss and Singaporean specialists capturing premium turnaround contracts demands capacity addition in Basel-Zurich corridor proximity. For New Entrants and Emerging Players: China's Yangtze River Delta manufacturing corridor offers the most penetrable geography as NMPA domestic data mandates outpace local GLP infrastructure development. Target joint-venture laboratory construction serving multinational sponsors with Class III device registration pipelines. The go-to-market angle centers on OECD Test Guidelines validation status paired with Health Sciences Authority recognition for Singapore-based regional hub operations. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ISO 10993 revision cycles and MDR implementation deadlines create durable demand asymmetries for accredited providers. Acquisition targets should display dual-method capability portfolios bridging in-vivo GLP and in-vitro validation pipelines. The signal to watch is FDA guidance updates on computational toxicology equivalence acceptance, which would accelerate method substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Organ-on-Chip Platform Partnership | Microphysiological systems compress lead candidate selection timelines for German implant manufacturers. |
| ISO 10993-6 Histopathological Accreditation | EMA scoring harmonization requirements elevate specialized tissue evaluation premiums. |
| China Joint-Venture Laboratory Construction | NMPA domestic data mandates create captive demand for Shanghai-Suzhou regional capacity. |
| Digital Pathology Workflow Investment | AI-assisted histomorphometry accelerates chronic implantation study turnaround for cardiovascular sponsors. |
| Swissmedic-Aligned Certification Expansion | Basel-Zurich corridor positioning captures German MDR transition overflow demand. |
Methodological Framework
The analysis maps biological evaluation, toxicological assessment, chemical testing, and physical testing sub-sectors, each validated through contract laboratory directors, regulatory affairs executives at cardiovascular device sponsors, and GLP study directors. Primary interviews with biomedical engineers, hospital purchasing committees, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, ISO 10993 revision drafts, and Swissmedic guidance documents. Bottom-up service-type segmentation triangulates against top-down regional demand aggregation.
Assumptions held regulatory framework evolution and OECD Test Guidelines adoption timelines fixed while varying pharmaceutical-device combination product penetration and in-vitro method validation acceptance rates across the projection horizon. Segmentation dimensions modeled span service type, product category, end-user procurement authority, and method selection constraints. CAGRs derive from installed base expansion of active implantable devices and outsourcing intensity shifts among German orthopedic manufacturers. Industry-specific inputs include MDR transition deadline clustering and NMPA Class III registration volume trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asia-Pacific specialists or accelerated FDA computational toxicology guidance would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Biochips Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Macrophage Marker Market