
 Life Science Instrumentation Market | 2026-2036
Life Science Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Life Science Instrumentation Market Intelligence
Market Context with Strategic Players
Pharmaceutical labs are restructuring their capital expenditure priorities toward integrated analytical platforms that compress drug development timelines. Thermo Fisher Scientific dominates the chromatography-mass spectrometry workflow segment through its captive supply of consumables and service contracts. Danaher anchors its position in molecular diagnostics instrumentation via stringent quality systems that sustain premium pricing across clinical and research channels. Agilent Technologies differentiates through specialized spectroscopy portfolios that serve environmental testing agencies and food safety regulators.
Technical Definition and Structural Segments
Life science instrumentation encompasses analytical and measurement systems operating at detection limits ranging from picomolar to femtomolar concentrations, utilizing optical, electrical, or magnetic signal transduction to characterize biological molecules and cellular structures. These systems serve primary industrial purposes in quality control, research discovery, and regulatory compliance verification across pharmaceutical manufacturing and clinical diagnostics. Mass spectrometry technology leads the instrument category in average selling price and service attach rates, while PCR instruments occupy the highest unit volume tier driven by infectious disease surveillance and personalized medicine expansion. Chromatography systems generate the most substantial recurring revenue streams through column and solvent consumables, and genomics applications within the application dimension command premium instrument configurations as nucleic acid sequencing throughput requirements intensify.
Regulatory Frame and Forward-Looking Close
FDA 21 CFR Part 11 compliance mandates and EMA's ICH Q2(R1) analytical validation guidelines shape instrument software architecture and data integrity architectures across North American and European installations. China's NMPA revised medical device classification rules are accelerating local type-testing requirements for imported clinical diagnostics platforms. ISO 13485 quality management certification has become a non-negotiable market access threshold for vendors serving European clinical laboratories. Stakeholders must monitor how evolving EPA environmental testing protocols and WHO prequalification pathways for molecular diagnostics reshape instrument specification requirements and regional competitive dynamics.
Market Dynamics
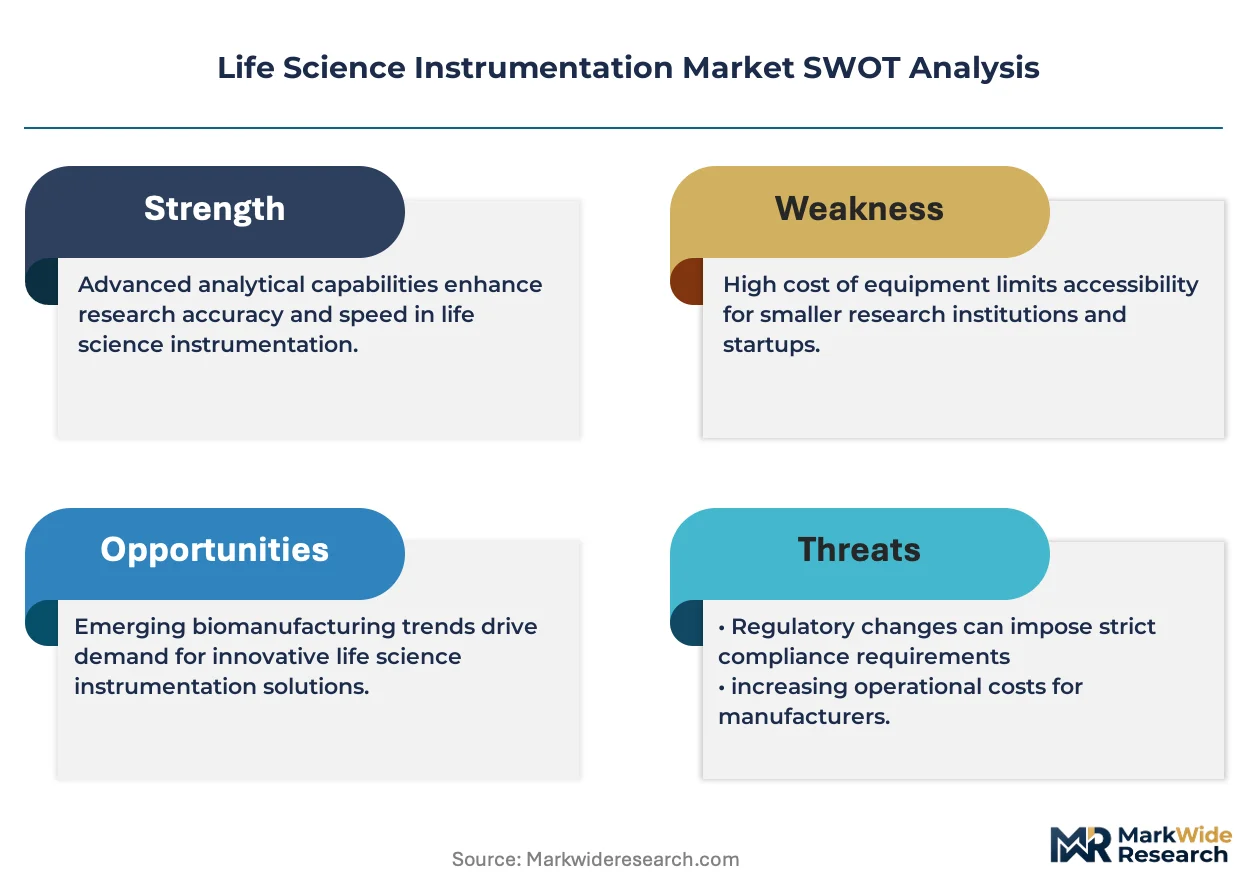
Pharmaceutical laboratories are compressing analytical validation timelines through integrated chromatography-mass spectrometry workflows that collapse method transfer steps between discovery and quality control stages.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates are forcing laboratory information management system upgrades that bundle new instrument purchases with compliance architecture.
- High-throughput screening infrastructure:Contract research organizations in Germany's Rhine-Main biotech cluster are scaling automated liquid handling platforms to service pharmaceutical outsourcing contracts.
- Femtomolar detection thresholds:Orbitrap mass spectrometry resolution improvements are opening peptide quantification applications in biologics manufacturing that previously required bioassay alternatives.
Market Restraints
- Helium supply concentration:US Bureau of Land Management reserve depletion is elevating carrier gas costs for gas chromatography systems across North American pharmaceutical quality control labs.
- Consumables lock-in economics:Proprietary column chemistries from dominant vendors create switching costs that suppress price competition in recurring revenue streams.
- ICH Q14 method development guidelines:Enhanced analytical procedure lifecycle management requirements are extending qualification timelines for multi-attribute monitoring platforms.
Strategic Opportunities
- India's CDSCO medical device rules:Streamlined import registration for in-vitro diagnostics instruments is lowering market access barriers for molecular diagnostics platforms in clinical laboratories.
- AI-driven spectral interpretation:Machine learning deconvolution algorithms are expanding mass spectrometry accessibility to technicians without specialized metabolomics training.
- ISO 13485 certification gaps:European clinical diagnostics vendors lacking quality management credentials face replacement windows as laboratories consolidate supplier bases.
Industry Challenges
- Cross-functional talent scarcity:Analytical chemists with simultaneous expertise in mass spectrometry hardware and GMP documentation command compensation premiums that strain mid-sized CRO operating models.
- Legacy data migration complexity:Pharmaceutical manufacturers with decades of chromatography data in proprietary formats face integration costs when transitioning to cloud-native laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Science Instrumentation Market |
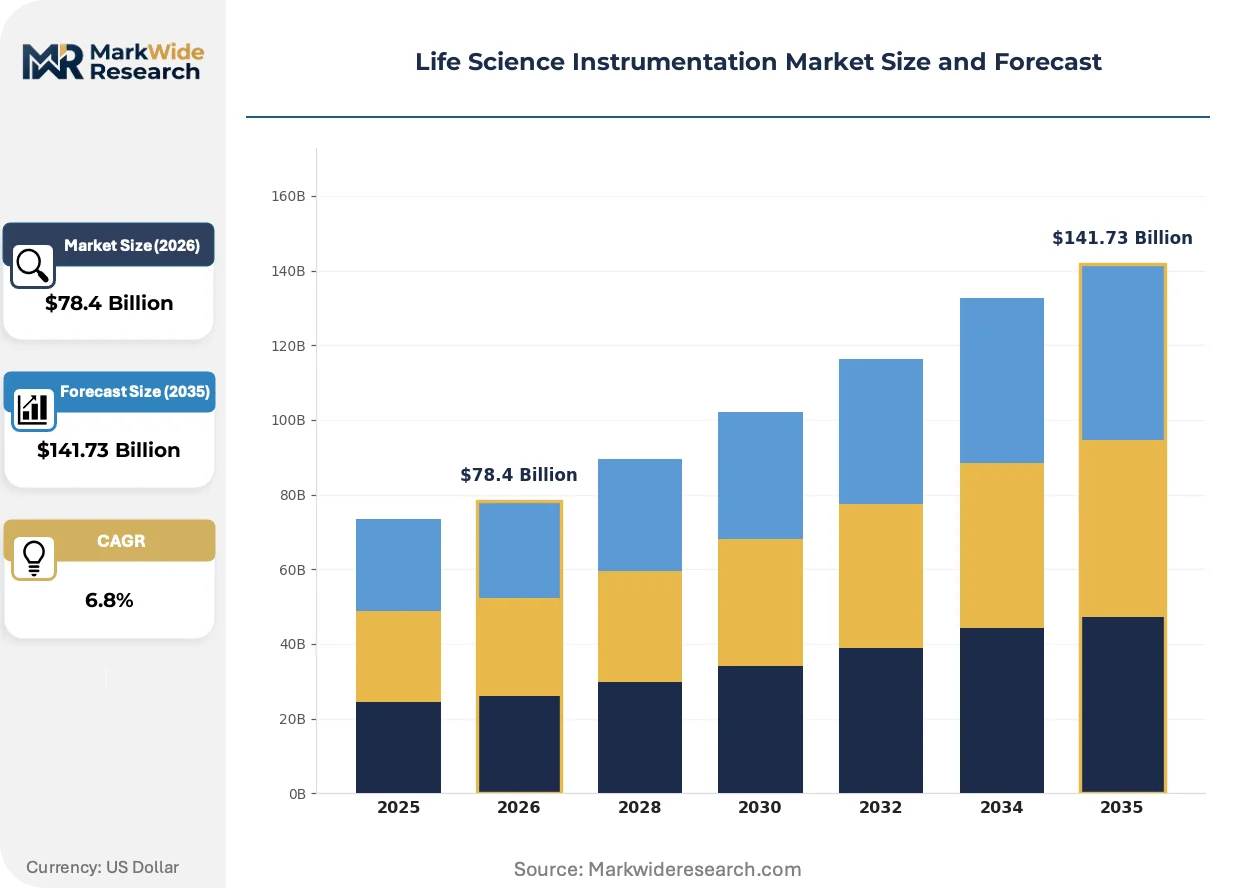
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
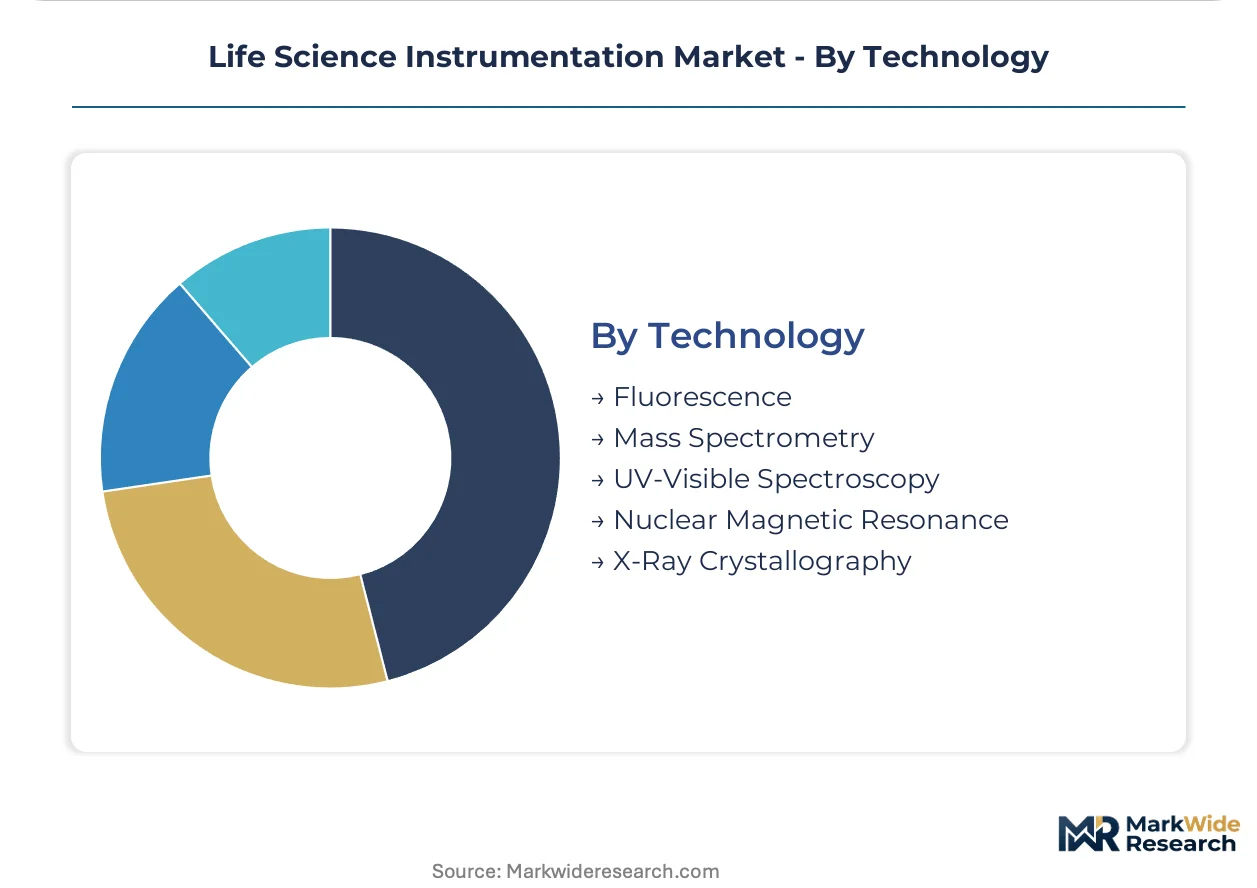
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Devices, Microscopy Equipment, PCR Instruments, Electrophoresis Setups Application: Genomics, Proteomics, Drug Discovery, Molecular Diagnostics, Environmental Testing End User: Biotechnology Firms, Academic Research Centers, Pharmaceutical Labs, Clinical Research Organizations, Forensic Laboratories Technology: Fluorescence, Mass Spectrometry, UV-Visible Spectroscopy, Nuclear Magnetic Resonance, X-Ray Crystallography |
| Companies Covered | Thermo Fisher Scientific, Inc., Danaher, Agilent Technologies, Inc., Merck KGaA, Bio-Rad Laboratories, Inc., PerkinElmer, Inc., Illumina, Inc., Bruker, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Science Instrumentation Market Strategic Shifts & Innovations
Automation architectures are dissolving boundaries between sample preparation, analytical measurement, and data interpretation stages that previously operated as discrete capital expenditure decisions.
Microfluidic sample preparation modules are expanding into high-throughput proteomics workflows by embedding solid-phase extraction on disposable cartridges that eliminate manual transfer steps. Academic core facilities and biopharma discovery groups are adopting these integrated formats to reduce technician touchpoints during overnight instrument runs. The technology is expanding into contract manufacturing quality control applications by compressing method validation documentation for transfer between sites.
EMA's ICH Q5A(R2) viral safety guidance revision is mandating next-generation sequencing as an alternative to in-vivo adventitious agent testing for cell therapy starting materials. This regulatory shift is accelerating nucleic acid platform purchases by European gene therapy developers who previously relied on outsourced polymerase chain reaction testing. Contract testing laboratories in Switzerland and the Netherlands are responding by qualifying long-read sequencing chemistries to capture viral integration site analysis contracts.
Service contract unbundling is fragmenting traditional instrument vendor revenue models as pharmaceutical procurement teams negotiate separate agreements for preventive maintenance, software updates, and regulatory qualification support. Large molecule manufacturers with captive metrology groups are driving this disaggregation to match service spend with actual instrument utilization rates. The pattern is most visible in US and German facilities where multi-site instrument fleets exceed fifty units and internal service capabilities justify selective vendor relationship termination.
Life Science Instrumentation Market Segmentation

Life science instrumentation purchasing follows distinct decision hierarchies across product categories, with capital intensity and consumables economics diverging sharply between analytical platforms. Procurement teams weight detection sensitivity specifications against service contract structures when segmenting vendor evaluations.
Product Type:
Capital allocation priorities separate instruments by recurring revenue potential and method transfer complexity across pharmaceutical quality control workflows.
- Chromatography Systems:Liquid and gas chromatography platforms separate complex biological mixtures through differential partitioning between stationary and mobile phases. Demand concentrates in German pharmaceutical manufacturing corridors where FDA 21 CFR Part 11 compliance mandates are forcing upgrades to integrated data integrity architectures.
- Spectroscopy Devices:These instruments measure light-matter interactions across ultraviolet, visible, and infrared wavelengths to characterize molecular structure. Academic core facilities in Switzerland and the Netherlands are expanding UV-Vis and FTIR capacity to support cell therapy viral safety testing under revised EMA guidance.
- Microscopy Equipment:Optical and electron microscopy systems visualize cellular and subcellular structures with resolution spanning micrometers to angstroms.
- PCR Instruments:Thermal cyclers amplify nucleic acid sequences through repeated temperature-controlled denaturation and extension cycles.
- Electrophoresis Setups:Gel and capillary systems separate charged biomolecules by size and charge under applied electric fields.
Volume sits with PCR Instruments; growth tilts toward Chromatography Systems.
Application:
End-use requirements fragment by detection threshold demands and regulatory documentation intensity across discovery versus quality control environments.
- Genomics:Nucleic acid sequencing and analysis workflows require femtomolar sensitivity and massive parallel read capacity. European gene therapy developers in the Rhine-Main cluster are accelerating platform purchases to meet EMA ICH Q5A(R2) viral safety mandates for cell therapy starting materials.
- Proteomics:Protein identification and quantification workflows depend on mass spectrometry resolution and chromatographic separation power. Contract research organizations in Germany are scaling high-throughput infrastructure to service pharmaceutical outsourcing contracts requiring peptide quantification at biologics manufacturing scale.
- Drug Discovery:Target identification and lead optimization workflows integrate multiple analytical modalities.
- Molecular Diagnostics:Clinical nucleic acid testing for infectious disease and personalized medicine applications.
- Environmental Testing:Contaminant detection and regulatory compliance verification for water, soil, and air matrices.
Revenue concentrates in Drug Discovery; steepest expansion trajectory belongs to Genomics.
End User:
Customer procurement sophistication varies by internal metrology capability and multi-site instrument fleet scale.
- Biotechnology Firms:Emerging and established biopharma companies prioritize platform flexibility and method transfer speed. Mid-sized gene therapy developers in Switzerland are consolidating supplier bases around vendors with ISO 13485 credentials to streamline European clinical diagnostics market access.
- Academic Research Centers:University core facilities balance capital cost constraints against publication-grade data quality requirements. Facilities in the Netherlands are adopting microfluidic sample preparation modules to reduce technician touchpoints during overnight instrument runs.
- Pharmaceutical Labs:Large molecule manufacturers with captive metrology groups drive service contract unbundling to match spend with utilization rates.
- Clinical Research Organizations:Outsourced testing providers scale automated platforms to meet pharmaceutical sponsor timelines.
- Forensic Laboratories:Government and private testing facilities require chain-of-custody documentation and validated protocols.
Instrument density peaks in Pharmaceutical Labs; fastest share gains come from Biotechnology Firms.
Technology:
Detection modality selection hinges on analyte class, concentration range, and information content requirements.
- Mass Spectrometry:Ionization and mass-to-charge ratio measurement delivers molecular weight and structural information at femtomolar thresholds. Orbitrap resolution improvements are opening peptide quantification applications in biologics manufacturing that previously required bioassay alternatives.
- Fluorescence:Excitation-emission spectroscopy enables sensitive detection of labeled biomolecules in cellular and solution contexts. Real-time PCR applications in infectious disease surveillance are driving highest unit volume deployment across clinical and research channels.
- UV-Visible Spectroscopy:Electronic transition measurement quantifies nucleic acid and protein concentrations rapidly.
- Nuclear Magnetic Resonance:Magnetic resonance phenomena reveal molecular structure through chemical shift and coupling patterns.
- X-Ray Crystallography:Diffraction pattern analysis determines three-dimensional protein and small-molecule structures at atomic resolution.
Average selling price leadership belongs to Mass Spectrometry; expanding most quickly is Fluorescence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision manufacturing corridors of Germany, Switzerland, and the United States, while consumption growth accelerates in clinical diagnostics expansion zones across India and China. Instrument assembly and consumables fabrication anchor in mature industrial clusters with established metrology supply chains. Demand generation shifts toward emerging biopharma manufacturing regions with tightening regulatory compliance requirements.
United States
FDA 21 CFR Part 11 electronic records mandates are forcing laboratory information management system upgrades that bundle new instrument purchases with compliance architecture. Large molecule manufacturers with captive metrology groups in Massachusetts and North Carolina drive service contract unbundling to match spend with utilization rates. The FDA's updated guidance on analytical method validation tightens compliance requirements for chromatography and mass spectrometry systems nationwide.
Germany
Contract research organizations in the Rhine-Main biotech cluster are scaling automated liquid handling platforms to service pharmaceutical outsourcing contracts. EMA's ICH Q2(R1) analytical validation guidelines shape instrument software architecture and data integrity architectures across European installations. Bavarian pharmaceutical manufacturing corridors anchor demand for integrated chromatography-mass spectrometry workflows that compress method transfer steps.
Switzerland
Gene therapy developers are consolidating supplier bases around vendors with ISO 13485 credentials to streamline European clinical diagnostics market access. Swissmedic oversight of medical device quality systems reinforces premium positioning for instrumentation serving cell therapy viral safety testing. Contract testing laboratories in Basel and Zurich are qualifying long-read sequencing chemistries to capture viral integration site analysis contracts.
China
NMPA revised medical device classification rules are accelerating local type-testing requirements for imported clinical diagnostics platforms. Domestic biopharma manufacturing expansion in the Yangtze River Delta and Pearl River Delta generates demand for high-throughput screening infrastructure. The country's national pharmaceutical regulator is tightening software validation requirements for nucleic acid sequencing platforms in clinical applications.
India
CDSCO streamlined import registration for in-vitro diagnostics instruments is lowering market access barriers for molecular diagnostics platforms in clinical laboratories. Maharashtra and Karnataka biotech corridors are scaling proteomics infrastructure to support contract research outsourcing from European pharmaceutical sponsors. The national pharmaceutical regulator's harmonization with ICH guidelines is accelerating method validation documentation requirements for quality control laboratories.
Life Science Instrumentation Market Key Industry Players
Top-tier vendors anchor the chromatography-mass spectrometry workflow segment through captive supply of consumables and service contracts, while mid-tier specialists compete on modular platform flexibility and regional service proximity. The vendor base stratifies across three archetypes: diversified conglomerates with integrated analytical portfolios, precision instrumentation specialists with premium spectroscopy offerings, and clinical diagnostics platforms with infectious disease surveillance focus. Consolidation pressure intensifies through strategic partnerships between hardware manufacturers and AI-driven spectral interpretation software providers, alongside backward integration into proprietary column chemistries and microfluidic consumables.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher exemplify scale-driven positioning through bundled service architectures and multi-site fleet management capabilities. Agilent Technologies occupies a position among precision instrumentation specialists with differentiated spectroscopy portfolios. These three entities represent distinct competitive vectors: consumables lock-in economics, clinical channel premium pricing, and specialized regulatory compliance verification respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Danaher |
| Agilent Technologies, Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| PerkinElmer, Inc. |
| Illumina, Inc. |
| Bruker |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
Analytical chemists with mass spectrometry hardware expertise concentrated in Germany's Rhine-Main cluster command compensation premiums that widen pricing spreads between premium and economy-tier instrument configurations. Labor-cost differentials between Swiss precision manufacturing corridors and emerging assembly zones in India feed directly into three-tier pricing stratification across chromatography and molecular diagnostics platforms.
Pricing Analysis
Margin tightening in mid-tier spectroscopy reflects helium supply depletion forcing carrier gas cost pass-through to pharmaceutical quality control labs. Three-tier pricing structure across premium, standard, and economy levels separates vendors with ISO 13485 credentials from uncertified competitors, with brand premium and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from consumables lock-in economics suppressing price competition in recurring revenue streams. Biotechnology firms with consolidated supplier bases demonstrate lowest price sensitivity; academic core facilities face highest budget constraints.
Supply Chain Analysis
China's NMPA revised medical device classification rules are accelerating local type-testing requirements that reshape sourcing patterns for imported clinical diagnostics platforms. Precision manufacturing concentrates in Germany, Switzerland, and the United States, with critical component dependencies on specialized optical detectors, rare-earth magnets for mass spectrometry, and high-purity chromatography solvents. Single-source vulnerability in helium reserves creates structural risk for gas chromatography supply chains. Distribution runs through authorized dealer networks serving multi-site pharmaceutical fleets and direct procurement channels for academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The life science instrumentation sector sits in a technology-transition phase where AI-driven spectral interpretation displaces manual metabolomics expertise requirements. Next-generation sequencing platforms are supplanting polymerase chain reaction methods for viral safety testing in European gene therapy manufacturing.
For Market Incumbents: Anticipate service contract unbundling by pharmaceutical procurement teams negotiating separate preventive maintenance, software update, and regulatory qualification agreements. Defend consumables lock-in economics through proprietary column chemistry backward integration. Counter AI-driven spectral interpretation entrants by embedding machine learning deconvolution directly into instrument firmware architectures.
For New Entrants and Emerging Players: Capture ISO 13485 certification gaps among European clinical diagnostics vendors facing laboratory supplier base consolidation. India's CDSCO streamlined import registration creates the most penetrable geography for molecular diagnostics platform market access. Lead with modular microfluidic sample preparation modules that compress method validation documentation for contract manufacturing quality control applications.
For Investors and Strategic Acquirers: The window for entry favors precision instrumentation specialists with differentiated spectroscopy portfolios and captive regulatory compliance verification capabilities. Long-term viability hinges on consolidation pressure through strategic partnerships between hardware manufacturers and AI-driven spectral interpretation software providers. Watch EMA ICH guideline revisions as the inflection signal for nucleic acid platform purchase acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Spectral Interpretation Integration | Machine learning deconvolution expands mass spectrometry accessibility to technicians without specialized metabolomics training. |
| ISO 13485 Quality Management Certification | European clinical diagnostics vendors lacking credentials face replacement windows as laboratories consolidate supplier bases. |
| Microfluidic Sample Preparation Module Development | Disposable cartridges embedding solid-phase extraction eliminate manual transfer steps in high-throughput proteomics workflows. |
| Long-Read Sequencing Chemistry Qualification | Swiss and Dutch contract testing laboratories capture viral integration site analysis contracts from gene therapy developers. |
| Service Contract Unbundling Negotiation | Large molecule manufacturers with captive metrology groups match service spend with actual instrument utilization rates. |
Research Approach
Document review covered FDA 21 CFR Part 11 guidance documents, EMA ICH Q-series analytical validation guidelines, and NMPA medical device classification rules, complemented by interviews with laboratory directors at German pharmaceutical quality control facilities, procurement managers at Rhine-Main contract research organizations, regulatory affairs leads at Swiss gene therapy developers, and biomedical engineers at Netherlands academic core facilities. Secondary validation drew from SEC instrument vendor filings, ISO certification registries, and hospital procurement database extracts. Bottom-up instrument shipment tracking and top-down pharmaceutical R&D expenditure analysis enabled triangulation.
Historical instrument replacement cycles were cross-referenced against expert panel input on regulatory compliance timeline compression. The analytical framework modeled demand across product type, application, end user, and technology dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived from weighted average of historical trajectory and forward-looking panel consensus. Forecast inputs incorporated EMA ICH Q5A(R2) viral safety guidance implementation pace and FDA analytical method validation update adoption rates.
The model holds under stable regulatory compliance requirement trajectories; deviation in helium supply disruption severity or AI spectral interpretation accuracy breakthroughs would shift instrument replacement timing and vendor competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market