
 Global Biotechnology Reagents Market | 2026-2036
Global Biotechnology Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biotechnology Reagents Market Analysis
Buyer concentration among pharmaceutical companies is pivoting as large-scale biologics manufacturers consolidate procurement while cell and gene therapy startups fragment demand across specialized reagent portfolios. Thermo Fisher Scientific leverages its end-to-end workflow solutions to anchor supply relationships with top-tier pharma accounts. Bio-Rad Laboratories competes through specialized chromatography resin portfolios that sustain premium positioning in downstream bioprocessing segments.
Biotechnology reagents comprise highly purified biochemical substances including enzymes, antibodies, nucleic acids, and cell culture media formulated to precise activity specifications measured in international units per milligram or endotoxin levels below 0.1 EU/mL, serving as critical inputs for molecular manipulation, detection, and cell propagation in life science research and biopharmaceutical manufacturing. Antibodies command the largest value pool due to their irreplaceable role in therapeutic development and diagnostic assay validation, while nucleic acid reagents represent the fastest-expanding category as CRISPR guide RNA synthesis and mRNA template production scale across clinical and commercial operations. Enzymes maintain mature, high-margin positions in PCR and sequencing workflows where supplier qualification timelines create defensive moats for incumbent vendors.
The FDA enforces current Good Manufacturing Practice guidelines for reagents used in cell and gene therapy manufacturing, while the EMA's ATMP framework imposes comparable traceability and viral safety standards across European manufacturing sites, and China's NMPA implements GB standards for imported biological raw materials that condition market access for foreign suppliers. ISO 13485 certification for diagnostic-grade reagents and the EU AI Act's emerging requirements for algorithm-driven quality control systems will further stratify compliance investments across vendor tiers. Stakeholders must monitor how regulator convergence on raw material characterization standards reshapes qualification timelines and sourcing geography decisions.
Market Dynamics
CRISPR-based therapeutic pipelines are compressing reagent qualification timelines as pharmaceutical manufacturers demand GMP-grade nucleic acid reagents with viral safety documentation that matches accelerated FDA approval pathways.
Growth Catalysts
- FDA Accelerated Approval Pathways:Gene therapy developers in the United States must secure reagent suppliers qualified under current Good Manufacturing Practice guidelines, expanding the addressable market for certified vendors.
- Cell Culture Media:Biologics manufacturers in Germany are scaling serum-free and chemically defined formulations to meet EMA traceability requirements for Advanced Therapy Medicinal Products.
- mRNA Template Production:China's NMPA is driving demand for high-purity nucleotides through GB standards enforcement on imported biological raw materials used in vaccine manufacturing.
Market Restraints
- Supply Concentration Risk:Chromatography resin production clusters among a limited set of European and North American chemical processors, creating vulnerability for downstream bioprocessing operations.
- Regulatory Friction:Divergent viral safety testing protocols between FDA and EMA frameworks extend qualification timelines for multinational reagent suppliers.
- Input Cost Volatility:Purified enzymes and recombinant proteins face price instability tied to fermentation feedstock costs and energy-intensive downstream processing.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's streamlined biosimilar approval pathways and production-linked incentive schemes are attracting contract development organizations seeking qualified reagent partners.
- AI-Driven Quality Control:The EU AI Act's emerging algorithmic transparency requirements create demand for automated endotoxin detection and batch release systems.
- Point-of-Care Diagnostics:Lyophilized reagent formats are penetrating decentralized testing networks in Brazil and Southeast Asia where cold chain infrastructure remains limited.
Industry Challenges
- GMP Certification Timeline:ISO 13485 and FDA facility inspections for diagnostic-grade reagents require 18-24 month preparation cycles that strain mid-cap supplier resources.
- Specialized Talent Scarcity:Bioprocess engineers with dual expertise in viral clearance validation and regulatory documentation command premium compensation that elevates operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biotechnology Reagents Market |
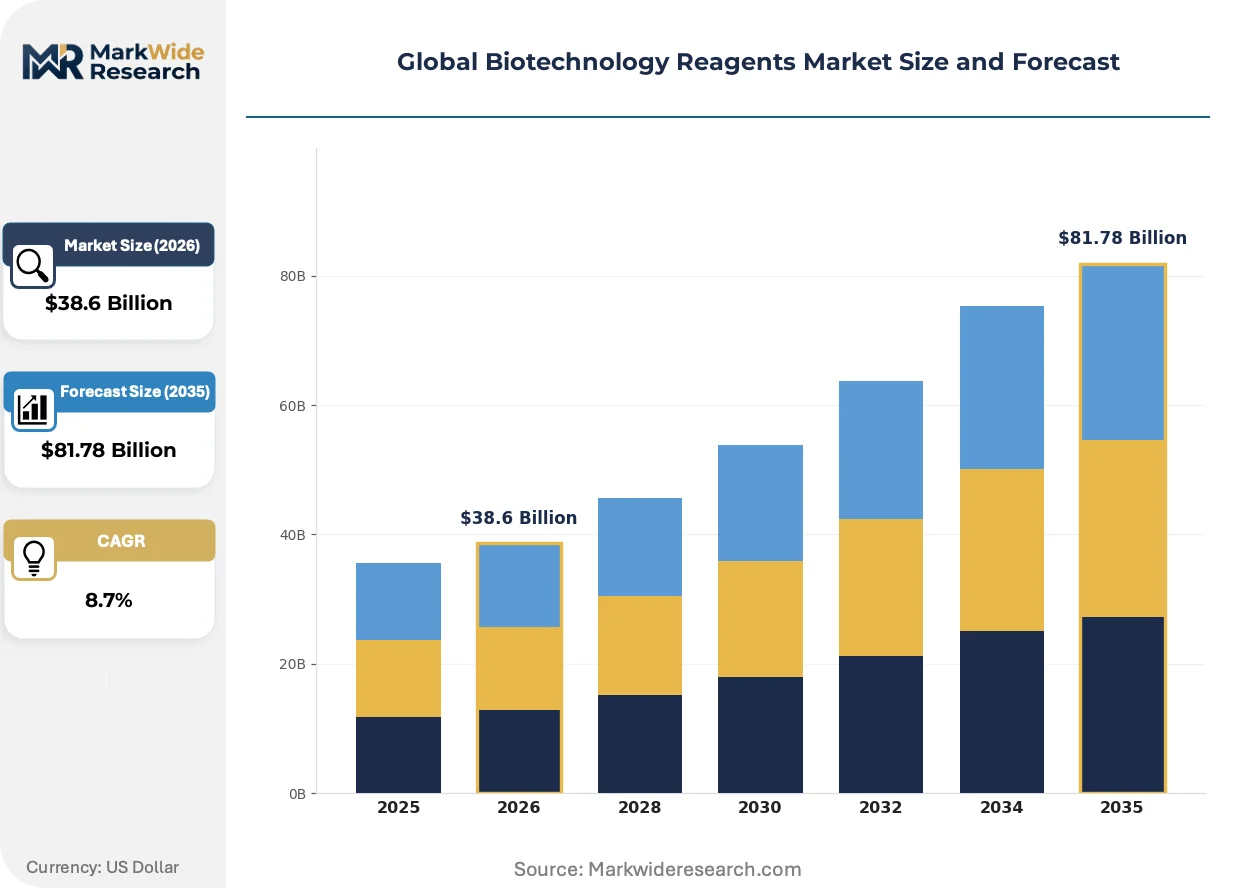
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Antibodies, Nucleic Acids, Cell Culture Media End User: Academic Institutions, Pharmaceutical Companies, Clinical Laboratories, Research Organizations Application: Drug Discovery, Genomic Research, Proteomics, Molecular Diagnostics Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, F. Hoffmann-La Roche, Merck KGaA, QIAGEN, Becton Dickinson, Danaher, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biotechnology Reagents Market Emerging Trajectories
Synthetic biology workflows are collapsing the distinction between research-grade and GMP-grade reagent specifications as therapeutic developers demand single-source suppliers capable of spanning discovery through commercial manufacturing.
Lyophilized master mix formulations are integrating stabilizing excipients and ambient-temperature logistics to eliminate cold chain dependency for distributed CRISPR screening applications. Cell and gene therapy startups in Boston and San Diego are adopting these formats for in-house quality control assays, compressing supplier qualification from multi-vendor qualification to single-source validation.
EMA's revised Annex 1 guidelines for sterile manufacturing are mandating closed-system processing and enhanced environmental monitoring for reagents used in ATMP production. European contract manufacturers are retrofitting filling lines and isolator technology to comply, with German and Swiss facilities investing most aggressively in barrier system upgrades.
Consolidated procurement contracts are displacing project-based purchasing as large pharmaceutical accounts negotiate multi-year supply agreements with built-in volume escalators and dedicated manufacturing slots. This behavior concentrates purchasing power among top-tier biologics manufacturers while fragmenting access for emerging therapy developers in China and South Korea.
Global Biotechnology Reagents Market Segmentation
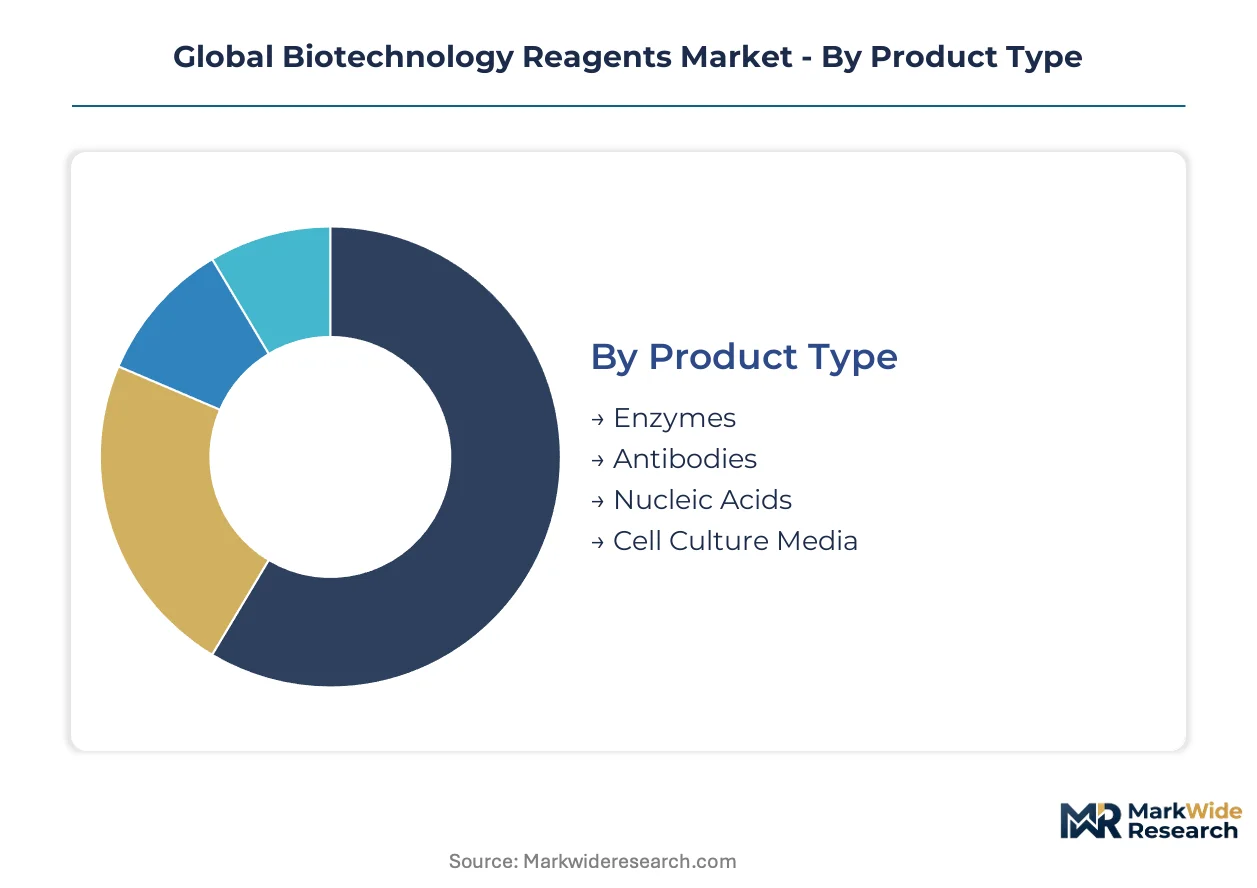
Segmentation in biotechnology reagents reveals how supplier capabilities align with divergent customer requirements across research and manufacturing environments. Procurement patterns differ sharply between discovery-stage flexibility demands and GMP-grade qualification rigor.
Product Type:
Supply concentration varies dramatically across biochemical categories, with some segments dominated by specialized fermentation houses while others fragment across synthetic chemistry providers.
- Antibodies:Polyclonal and monoclonal antibody reagents bind specific protein targets with affinity constants exceeding 10^9 M^-1. Therapeutic developers in the United States and Germany absorb the majority of GMP-grade output as they scale bispecific and antibody-drug conjugate pipelines under FDA and EMA frameworks.
- Nucleic Acids:Synthetic oligonucleotides, plasmid DNA, and guide RNA molecules enable CRISPR editing and mRNA manufacturing with purity thresholds above 95% full-length content. China's NMPA enforcement of GB standards on imported biological raw materials is redirecting procurement toward domestic synthesis capacity.
- Enzymes:Recombinant polymerases, restriction enzymes, and ligases catalyze molecular biology workflows with specific activity measured in units per milligram.
- Cell Culture Media:Serum-free and chemically defined formulations support mammalian cell propagation with endotoxin levels below 0.1 EU/mL.
Antibodies absorb the bulk of installed capacity; nucleic acids are expanding most quickly.
End User:
Customer scale determines pricing power and contract structure, with large manufacturers consolidating procurement while fragmented research buyers accept list pricing.
- Pharmaceutical Companies:Large-scale biologics manufacturers negotiate multi-year supply agreements with dedicated manufacturing slots and volume escalators. These accounts demand end-to-end workflow solutions spanning discovery through commercial production.
- Academic Institutions:University and government research laboratories purchase research-grade reagents through institutional procurement frameworks with limited supplier qualification requirements. Budget constraints favor bundled distributor contracts over direct manufacturer relationships.
- Clinical Laboratories:Diagnostic testing facilities require ISO 13485-certified reagents with lot-to-lot consistency documentation.
- Research Organizations:Contract research organizations and nonprofit institutes operate between academic and commercial standards.
Pharmaceutical companies command the deepest supplier relationships; clinical laboratories are tightening certification requirements fastest.
Application:
Application-specific performance standards create tiered qualification barriers that stratify vendor access across workflow stages.
- Drug Discovery:High-throughput screening and lead optimization consume research-grade reagents in multi-well formats with tolerance for batch variability. Biotechnology startups in Boston and San Diego cluster demand for CRISPR screening panels.
- Molecular Diagnostics:PCR and sequencing-based assays require diagnostic-grade reagents with analytical sensitivity documentation and stability validation. Point-of-care developers in Brazil and Southeast Asia drive lyophilized format adoption where cold chain infrastructure remains limited.
- Genomic Research:Whole-genome sequencing and epigenetic analysis workflows demand high-fidelity enzymes and nucleic acid purification systems.
- Proteomics:Mass spectrometry and protein interaction studies utilize specialized antibodies and affinity resins.
Drug discovery maintains the broadest vendor base; molecular diagnostics is climbing the fastest as decentralized testing networks expand.
Distribution Channel:
Channel selection reflects customer technical sophistication and procurement centralization, with direct relationships correlating to GMP-grade requirements.
- Direct Sales:Manufacturer field organizations serve top-tier pharmaceutical accounts with technical support and custom formulation capabilities. Thermo Fisher Scientific anchors supply relationships through end-to-end workflow solutions.
- Distributors:Regional and specialty distributors aggregate fragmented demand from academic and mid-tier research customers. Bio-Rad Laboratories competes through specialized chromatography resin portfolios with premium positioning in downstream bioprocessing.
- Online Retail:E-commerce platforms enable rapid procurement of catalog reagents with standard specifications.
- Wholesalers:Bulk logistics providers serve high-volume consumables with limited technical content.
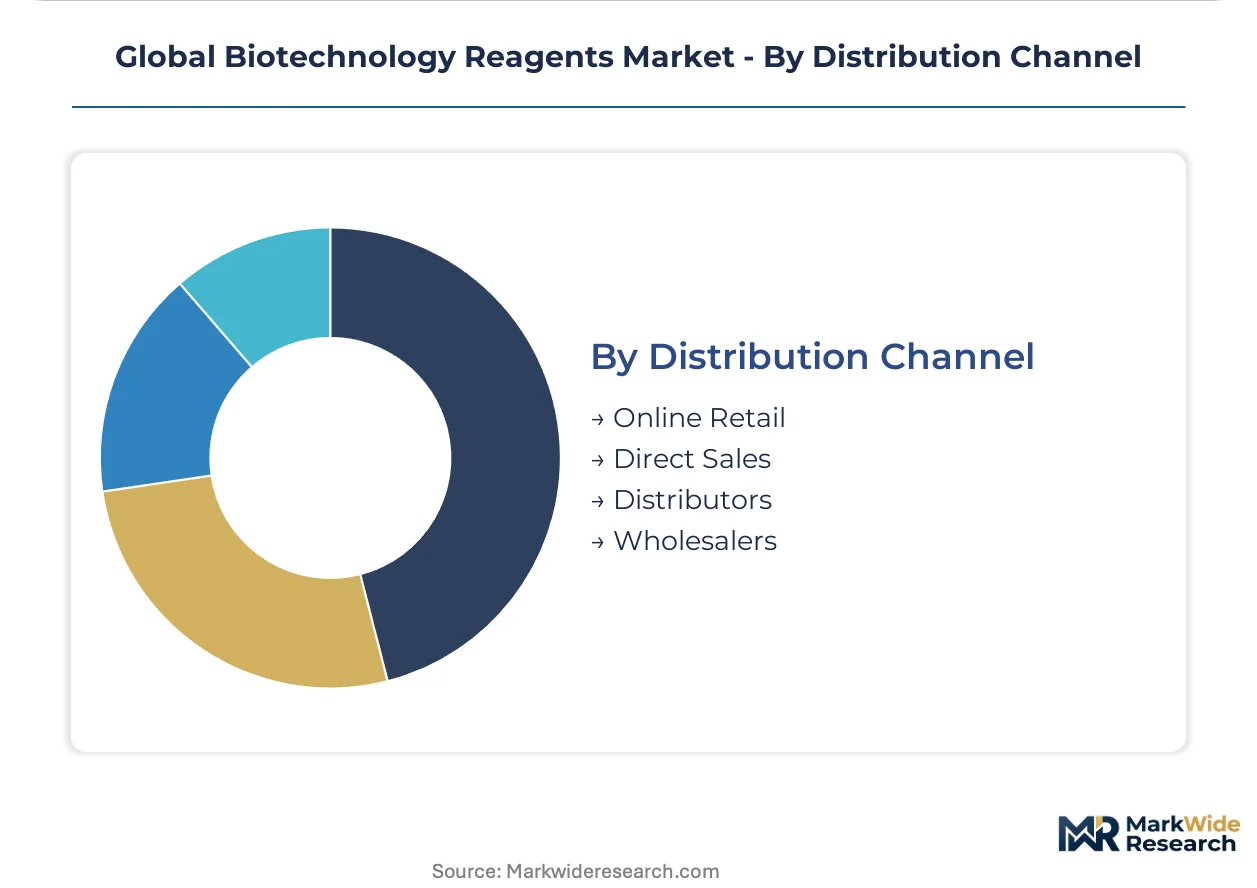
Direct sales captures the highest-margin transactions; distributors are gaining share fastest among emerging therapy developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in the United States, Germany, and China absorb the majority of GMP-grade biotechnology reagent procurement as these markets scale CRISPR-based therapeutic pipelines. FDA accelerated approval pathways, EMA's ATMP framework, and China's GB standards enforcement collectively reshape qualification requirements and sourcing geography decisions.
United States
Gene therapy developers in Boston and San Diego drive concentrated demand for viral safety-documented nucleic acid reagents. The FDA's current Good Manufacturing Practice guidelines for cell and gene therapy manufacturing mandate supplier qualification timelines that favor established vendors with inspection histories. Large-scale biologics manufacturers in the Research Triangle Park cluster negotiate multi-year supply agreements with dedicated manufacturing slots.
Germany
EMA's revised Annex 1 guidelines for sterile manufacturing are mandating closed-system processing upgrades for reagents used in Advanced Therapy Medicinal Products. German contract manufacturers in Bavaria and Baden-Württemberg are retrofitting filling lines with isolator technology to comply with enhanced environmental monitoring requirements. Serum-free and chemically defined cell culture media formulations are scaling to meet traceability mandates.
China
The NMPA's enforcement of GB standards on imported biological raw materials is redirecting procurement toward domestic synthesis capacity for mRNA template production. CRISPR guide RNA manufacturing is concentrating in Shanghai and Suzhou industrial parks as vaccine developers qualify local suppliers. Production-linked incentive schemes are attracting contract development organizations seeking qualified reagent partners.
India
CDSCO's streamlined biosimilar approval pathways are accelerating demand for ISO 13485-certified enzymes and chromatography resins. Biologics manufacturing is expanding in Hyderabad and Bengaluru as multinational pharmaceutical companies establish captive production facilities. The country's national pharmaceutical regulator is aligning viral safety testing protocols with FDA and EMA frameworks to reduce qualification friction.
Switzerland
Swissmedic's alignment with EMA standards supports specialized reagent production for downstream bioprocessing applications. Basel and Zurich host precision fermentation facilities supplying high-purity recombinant proteins to European biologics manufacturers. The country's central location and regulatory equivalence position it as a distribution hub for qualified reagents serving ATMP producers across the continent.
Global Biotechnology Reagents Market Vendor Landscape
United States producers anchor one tier; German and Swiss specialists hold premium positioning in downstream bioprocessing segments. The market structure concentrates among diversified life science conglomerates with end-to-end workflow capabilities and specialized chromatography resin manufacturers with defensive moats in qualification-heavy applications. Three strategic archetypes dominate: integrated platform providers, precision fermentation specialists, and regional synthesis houses. Competitive moves center on multi-year supply agreements with volume escalators and backward integration into fermentation feedstocks.
Within the integrated platform tier, Thermo Fisher Scientific occupies a position exemplifying end-to-end workflow anchoring with top-tier pharmaceutical accounts. Bio-Rad Laboratories represents specialized chromatography resin portfolio positioning that sustains premium placement in downstream bioprocessing segments. Among diversified diagnostics and life science conglomerates, Danaher sits within the multi-brand holding structure archetype serving clinical laboratory and research organization demand.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| F. Hoffmann-La Roche |
| Merck KGaA |
| QIAGEN |
| Becton Dickinson |
| Danaher |
| Illumina |
| Others |
Supply Flow & Price Mechanics
Fermentation feedstock costs and energy-intensive downstream processing anchor pricing tiers across GMP-grade enzyme and recombinant protein portfolios, with purified biochemical inputs flowing from North American and European chemical processors through contract manufacturers in Germany and Switzerland before reaching pharmaceutical accounts negotiating multi-year supply agreements with volume escalators.
Pricing Analysis
High-volume transactional contracts for research-grade reagents compress margins while low-volume GMP-grade certifications sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified suppliers with inspection histories from ISO-certified mid-tier vendors and unqualified catalog distributors. Pricing pressure stems from consolidated procurement contracts among large-scale biologics manufacturers demanding dedicated manufacturing slots. Academic institutions and cell therapy startups exhibit highest price sensitivity; gene therapy developers with accelerated approval timelines absorb premium tier costs without negotiation leverage.
Supply Chain Analysis
Cold chain logistics costs and ambient-temperature stability requirements are reshaping format selection for distributed CRISPR screening applications. Chromatography resin production clusters in Germany, Switzerland, and the United States, with purified enzymes and nucleic acid synthesis capacity concentrating in these same markets. Raw material dependencies include fermentation media, specialty chemicals for resin polymerization, and high-purity water systems. Single-source vulnerability pervades viral clearance validation services. Distribution runs through direct manufacturer field organizations for top-tier pharmaceutical accounts and regional distributors aggregating fragmented academic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors capable of spanning research-grade flexibility through GMP-grade qualification rigor, with ISO 13485 certification timelines and facility inspection preparation cycles forcing weaker players toward acquisition or exit.
For Market Incumbents: Hedge against qualification-heavy segment commoditization by anchoring supply relationships through end-to-end workflow solutions that bundle discovery-stage reagents with commercial manufacturing capacity. Backward integration into fermentation feedstocks defends margin position against input cost volatility. Incumbents should prioritize captive viral clearance validation capabilities to offset emerging entrant competition in nucleic acid synthesis.
For New Entrants and Emerging Players: E-commerce platforms and specialized distributor partnerships offer lower-friction routes to penetrate price-sensitive academic and research organization segments before scaling toward GMP-grade certification. White-space targets include lyophilized reagent formats for point-of-care diagnostics in Brazil and Southeast Asia, plus CDSCO-aligned biosimilar reagent supply for Indian contract development organizations. A digital-first go-to-market angle with rapid catalog fulfillment can displace legacy distributor relationships among mid-tier research buyers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists with existing EMA inspection histories in Bavaria and Baden-Württemberg, where facility retrofit costs for Annex 1 compliance have strained mid-cap balance sheets. Long-term viability centers on suppliers capable of serving both FDA accelerated approval pathways and China's NMPA GB standards enforcement without geographic redundancy. The signal to watch is consolidation velocity among chromatography resin manufacturers as pharmaceutical accounts reduce qualified vendor lists.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | ISO 13485 and FDA facility inspections anchor supply relationships with gene therapy developers in Boston and San Diego. |
| Backward Integration into Fermentation | In-house production of recombinant proteins insulates margin structure from energy-intensive downstream processing cost volatility. |
| Lyophilized Format Development | Ambient-temperature logistics eliminate cold chain dependency for CRISPR screening applications in Southeast Asia. |
| Multi-Year Supply Agreements | Contract structures with volume escalators and dedicated manufacturing slots lock in pharmaceutical account purchasing power. |
| AI-Driven Quality Control Systems | Automated endotoxin detection aligns with EU AI Act algorithmic transparency requirements for diagnostic-grade reagents. |
Methodological Framework
Document review covered FDA current Good Manufacturing Practice guidelines, EMA Advanced Therapy Medicinal Product framework documents, and China's GB standards for imported biological raw materials, complemented by interviews with bioprocess engineers, regulatory affairs specialists at gene therapy developers, procurement directors at large-scale biologics manufacturers, and chromatography resin technical sales leads. Secondary validation drew from ISO 13485 certification databases, ClinicalTrials.gov gene therapy entries, and customs records of purified enzyme imports. Bottom-up reagent category demand modeling and top-down pharmaceutical manufacturing capacity analysis were triangulated against primary fieldwork.
Historical volume trajectories for antibodies, nucleic acids, enzymes, and cell culture media were cross-referenced against expert panel assessments of CRISPR therapeutic pipeline scaling and mRNA template production expansion. The analytical framework segmented by product type, end user archetype, application workflow, and distribution channel across the analysis window. CAGRs were derived from regression analysis of qualification timeline compression effects and regulatory convergence patterns. Industry-specific forecast inputs included FDA accelerated approval pathway adoption rates and EMA Annex 1 sterile manufacturing upgrade capex cycles.
The model holds under sustained regulatory enforcement of viral safety documentation standards and continued pharmaceutical consolidation of procurement; deviation in biologics manufacturing reshoring intensity or fermentation feedstock cost shocks would shift volume and value outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
PCR Consumables Market