
 Global Bioprocess Analyzers Market | 2026-2036
Global Bioprocess Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioprocess Analyzers Market Foresight
Single-use sensor integration with distributed control architectures is rewriting how bioprocess data is captured and acted upon across mammalian cell culture lines. Thermo Fisher Scientific leverages its chromatography and mass spectrometry breadth to anchor multi-modal platform strategies. Sartorius sustains dominance in single-use analytical sensor technologies that reduce cleaning validation burdens. Danaher competes through its Beckman Coulter and Pall operating companies, combining particle analysis with bioreactor-integrated sampling.
Bioprocess analyzers comprise automated instrumentation that measures critical quality attributes and process parameters in real-time or at-line, typically operating at measurement ranges from pH 2-12, dissolved oxygen 0-150%, and cell densities exceeding 10^7 cells per milliliter to enable closed-loop biomanufacturing control. Spectrophotometers and chromatography systems capture the largest installed base where margin pools reflect consumable attachment rates and service contracts. Mass spectrometry segments within technology classification are expanding fastest as multi-attribute monitoring replaces discrete assays. Cell culture monitoring leads application demand while fermentation monitoring follows with accelerating adoption in microbial expression systems for biosimilars.
The FDA's process analytical technology framework and EMA's quality by design guidelines shape instrument validation requirements and data integrity standards across GMP environments. ISO 13485 and GAMP 5 compliance obligations filter vendor participation, favoring suppliers with documented software lifecycle management and audit trail capabilities. Stakeholders must weigh capital deployment toward integrated platform consolidation versus modular best-of-breed architectures as process intensification demands faster analytical feedback loops.
Market Dynamics
Single-use sensor architectures and distributed control systems are compressing analytical feedback loops from hours to minutes, forcing incumbent vendors to re-engineer platform integration strategies or cede share to modular specialists.
Growth Catalysts
- FDA Process Analytical Technology:The framework mandates real-time critical quality attribute monitoring for biologics approval, compelling manufacturers to deploy at-line spectroscopy and chromatography systems throughout upstream and downstream operations.
- Continuous manufacturing adoption:Biologics producers in Germany, Switzerland, and Singapore are retrofitting stainless-steel trains with integrated analyzers to enable closed-loop control and reduce batch failure rates.
- Cell density sensor miniaturization:Dielectric spectroscopy probes now operate at measurement ranges exceeding 10^7 cells per milliliter without offline sampling, accelerating perfusion culture adoption across mammalian expression platforms.
Market Restraints
- Consumable cost concentration:Proprietary sensor cartridges and calibration standards lock users into single-vendor ecosystems, with annual recurring costs often exceeding initial capital outlay by year three.
- Validation timeline friction:GAMP 5 software lifecycle documentation and FDA 21 CFR Part 11 compliance requirements extend qualification periods, delaying revenue recognition for instrument deployments.
- Skilled operator scarcity:Spectroscopic method development and multivariate data analysis expertise concentrates among analytical chemists in Basel, Boston, and Seoul, creating hiring bottlenecks for new manufacturing sites.
Strategic Opportunities
- India biosimilar manufacturing:CDMOs in Hyderabad and Bengaluru are greenfielding multi-product facilities with integrated analyzer suites to capture export contracts requiring EMA and FDA dual compliance.
- Raman spectroscopy convergence:Combining Raman with machine learning-based chemometric models enables simultaneous glucose, lactate, and titer prediction, displacing discrete offline assays in fed-batch monitoring.
- Japan regenerative medicine:METI's national cell therapy infrastructure initiative funds GMP-compliant analytical platforms for induced pluripotent stem cell manufacturing, creating dedicated demand for non-invasive metabolite sensors.
Industry Challenges
- Legacy DCS integration complexity:Brownfield bioreactor installations often rely on proprietary DeltaV or Siemens PCS7 architectures, requiring custom OPC-UA middleware to stream analyzer data into existing batch records.
- Reference standard availability:Cell culture media variability and evolving product quality attribute definitions complicate calibration transfer between sites, forcing redundant method development for each manufacturing location.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioprocess Analyzers Market |
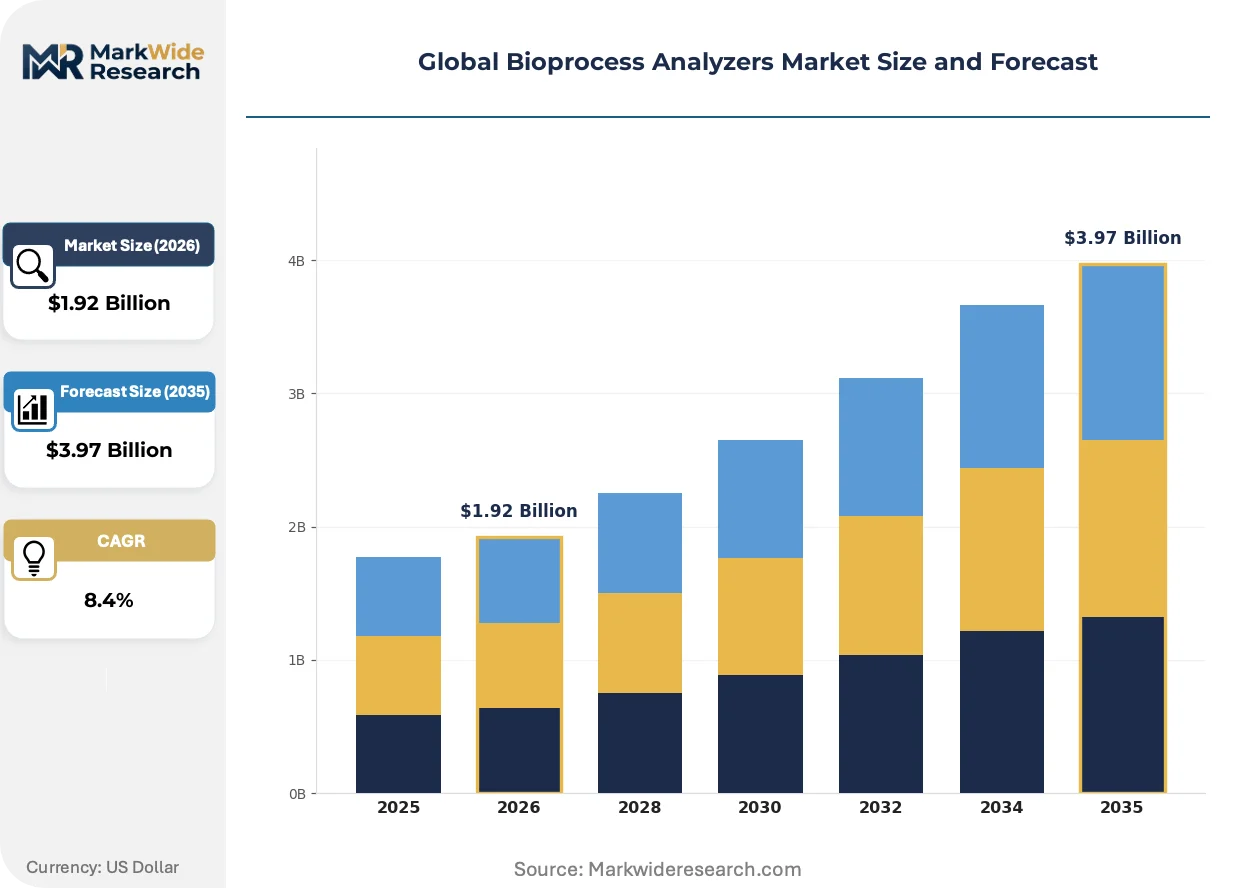
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.97 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Spectrophotometers, Chromatography Systems, pH Meters End User: Biotechnology Firms, Pharmaceutical Companies, Research Laboratories, Contract Manufacturing Organizations Technology: Mass Spectrometry, Capillary Electrophoresis, Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction Application: Cell Culture Monitoring, Fermentation Monitoring, Quality Control, Bioprocess Optimization |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Sartorius, Nova Biomedical, Roche, Danaher, Beckman Coulter, Bio-Rad Laboratories, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioprocess Analyzers Market Shifts & Advancements
Real-time multi-attribute monitoring is displacing discrete at-line testing, compressing analytical cycle times and redefining how biomanufacturers validate process consistency across global production networks.
Raman spectroscopy integrated with chemometric modeling is rendering obsolete traditional high-performance liquid chromatography for titer and critical quality attribute estimation during cell culture operations. Large-molecule CDMOs in Germany and Switzerland are deploying these systems at 500-liter to 2,000-liter scales, eliminating four-hour offline sampling intervals and enabling automated feed control that tightens batch-to-batch variation.
EMA's revised Annex 1 guidelines on sterile manufacturing impose continuous viable and non-viable particle monitoring requirements for Grade A and Grade B environments, accelerating adoption of laser-induced breakdown spectroscopy for real-time environmental monitoring. Aseptic fill-finish suites across Ireland, the Netherlands, and Italy are retrofitting isolators with integrated particle analyzers to eliminate manual intervention during batch operations, with compliance deadlines driving capital deployment through 2027.
Biologics manufacturers are consolidating vendor relationships around platform ecosystems that bundle hardware, consumables, and compliance documentation, displacing modular best-of-breed procurement strategies prevalent through 2020. Contract manufacturers in South Korea and Singapore now prioritize single-source analytical platforms with pre-validated method templates, compressing technology transfer timelines for multi-site production campaigns and reducing qualification overhead for biosimilar filings.
Global Bioprocess Analyzers Market Segmentation
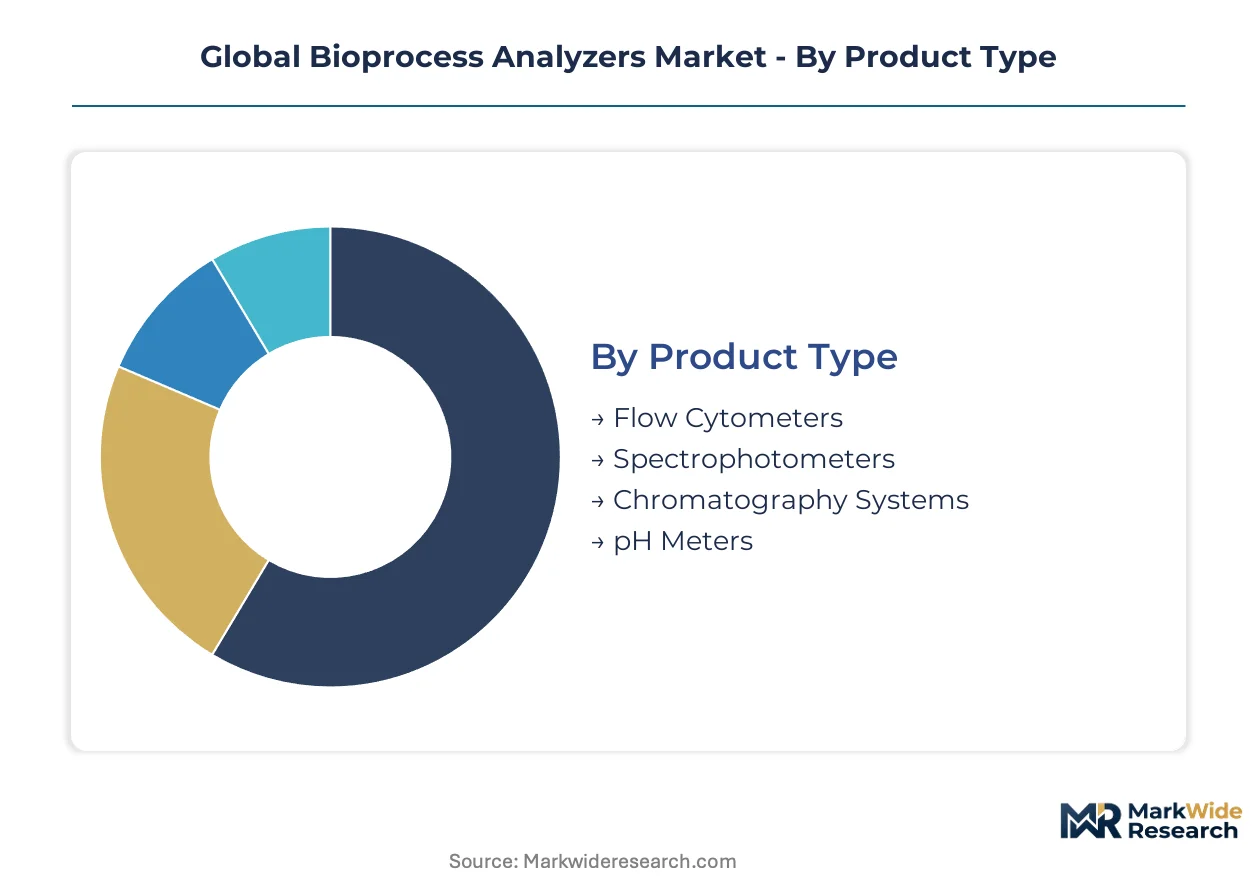
Bioprocess analyzer procurement patterns diverge sharply across product architectures, end-user sophistication, and analytical throughput requirements. Vendor positioning and pricing power concentrate where measurement modality intersects with regulatory validation burden.
Product Type:
Cost tier stratification separates capital-intensive chromatography platforms from portable at-line sensors, with service attachment rates and consumable pull-through determining lifetime value capture.
- Chromatography Systems:High-pressure liquid chromatography and gas chromatography units dominate critical quality attribute verification for monoclonal antibody release testing. Demand clusters in Germany and Switzerland where biosimilar manufacturers require dual FDA-EMA method validation, driving preference for pre-qualified instrument platforms.
- Spectrophotometers:UV-Vis and fluorescence systems measure protein concentration and aggregate formation with minimal sample preparation. Biotechnology firms in Boston and Seoul deploy these for high-throughput clone screening, prioritizing modular optical path configurations that accommodate 96-well plate automation.
- Flow Cytometers:Single-cell analysis platforms quantify viability and productivity in hybridoma and CHO cell lines.
- pH Meters:Electrochemical probes with ISFET architectures enable sterilizable in-line deployment for perfusion bioreactor control.
Chromatography systems command the established base. The steepest expansion runs through spectrophotometers.
End User:
Customer type determines purchasing authority structure, with contract manufacturers prioritizing platform standardization across multi-site networks while research laboratories favor configurability.
- Contract Manufacturing Organizations:CDMOs in Hyderabad, Singapore, and Basel operate under stringent batch-release timelines imposed by originator pharmaceutical clients. These organizations deploy integrated analyzer suites with pre-validated methods to compress technology transfer for multi-product campaigns.
- Biotechnology Firms:Venture-backed developers in Cambridge and South San Francisco prioritize at-line Raman and capacitance probes for process analytical technology compliance during IND-enabling studies. Capital constraints favor lease arrangements and consumable bundling over outright purchase.
- Pharmaceutical Companies:Large-cap innovators maintain captive analytical development groups with dedicated method validation resources.
- Research Laboratories:Academic and government institutes drive early-stage sensor innovation but exhibit irregular procurement cycles dependent on grant funding.
Pharmaceutical companies anchor current revenue concentration. Contract Manufacturing Organizations are gaining share fastest.
Technology:
Measurement modality selection hinges on molecular weight range, detection sensitivity, and throughput requirements for specific biologic classes.
- Mass Spectrometry:LC-MS and MALDI-TOF platforms enable multi-attribute monitoring of glycosylation patterns, charge variants, and host cell proteins in a single analytical run. Adoption accelerates in Ireland and the Netherlands where fill-finish operations require rapid sterility verification without culture-based incubation delays.
- Polymerase Chain Reaction:Quantitative PCR systems detect mycoplasma and viral adventitious agents with specificity exceeding 10^3 copies per milliliter. Cell therapy manufacturers in Japan and California deploy these for regenerative medicine release testing under PMDA and FDA guidance respectively.
- Capillary Electrophoresis:Separation technology resolves charge heterogeneity in antibody therapeutics with minimal sample consumption.
- Enzyme-Linked Immunosorbent Assay:Plate-based immunoassays retain cost advantage for high-volume titer determination in legacy fed-batch processes.
Mass spectrometry captures the premium expansion trajectory. Polymerase chain reaction maintains the broadest installed footprint.
Application:
Process stage determines analyzer placement strategy, with upstream monitoring demanding sterilizable in-line probes while downstream operations tolerate at-line sampling with rapid turnaround.
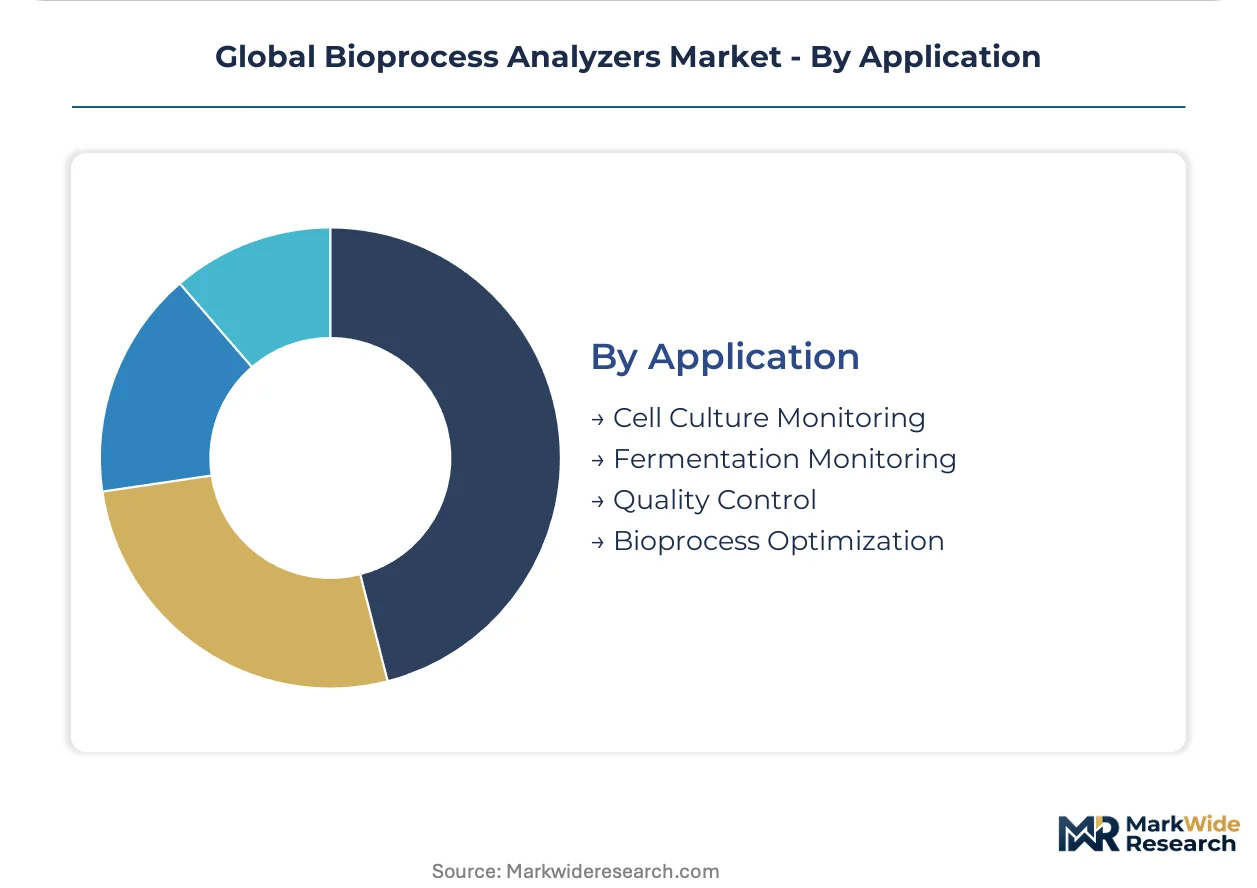
- Cell Culture Monitoring:Dielectric spectroscopy and Raman probes enable real-time viable cell density and metabolite tracking in mammalian perfusion systems. German manufacturers around Heidelberg and Munich lead deployment scale, driven by process intensification initiatives that replace fed-batch with continuous manufacturing architectures.
- Fermentation Monitoring:Microbial expression systems for biosimilar insulin and growth hormone production require dissolved oxygen and off-gas analysis for high-cell-density E. coli and yeast cultures. Indian CDMOs in Bengaluru retrofit stainless-steel fermenters with optical sensor arrays to meet export contract specifications.
- Quality Control:Release testing laboratories operate under ISO 17025 accreditation with enforced analytical method transfer protocols.
- Bioprocess Optimization:Development-scale studies leverage Design of Experiments frameworks with automated sampling systems.
Quality control absorbs the largest capital allocation. Cell culture monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bioprocess analyzer manufacturers export integrated spectroscopy platforms to contract manufacturers in Singapore and South Korea, while Swiss precision instrumentation flows into Irish fill-finish facilities serving FDA-regulated markets.
United States
FDA process analytical technology mandates drive real-time monitoring adoption across mammalian cell culture operations. The agency's quality by design framework shapes instrument validation protocols for IND-enabling studies. Greater Boston biotechnology clusters deploy at-line Raman systems for automated perfusion control, compressing batch-to-batch variation timelines.
Germany
Biosimilar manufacturers around Heidelberg and Munich require dual FDA-EMA method validation for export contracts. The country's national pharmaceutical regulator enforces GAMP 5 software lifecycle documentation across GMP environments. Baden-Württemberg analytical sensor producers supply integrated platforms to CDMOs retrofitting stainless-steel trains for continuous manufacturing.
Switzerland
Basel-based biologics innovators maintain captive analytical development groups with dedicated mass spectrometry resources. Swissmedic guidelines on data integrity shape audit trail requirements for chromatography deployments. The Lake Geneva corridor concentrates dielectric spectroscopy expertise for high-cell-density perfusion monitoring.
India
Hyderabad and Bengaluru CDMOs greenfield multi-product facilities with analyzer suites for EMA-FDA dual compliance. The national pharmaceutical regulator's revised GMP guidelines accelerate automated sampling adoption. Karnataka-based contract manufacturers retrofit legacy fermenters with optical sensor arrays to capture insulin biosimilar export contracts.
Japan
METI's national cell therapy infrastructure initiative funds GMP-compliant analytical platforms for induced pluripotent stem cell manufacturing. PMDA guidance on regenerative medicine release testing shapes non-invasive metabolite sensor specifications. Osaka-Kobe pharmaceutical clusters deploy capacitance probes for closed-loop bioreactor control in autologous therapy production.
Global Bioprocess Analyzers Market Competitive Landscape
On the supply side, the industry is consolidating around platform ecosystems that bundle hardware, consumables, and compliance documentation. Chromatography and mass spectrometry specialists compete with single-use sensor fabricators for upstream monitoring share. Three archetypes dominate: diversified life science conglomerates with chromatography breadth, pure-play analytical sensor specialists, and precision instrumentation groups with particle analysis heritage. M&A activity targets chemometric software capabilities, while strategic partnerships lock in consumable attachment rates through multi-year service contracts.
Among diversified life science groups, Thermo Fisher Scientific and Danaher anchor the premium instrumentation tier through chromatography and mass spectrometry platform breadth. Sartorius occupies a distinct position within single-use analytical sensor technologies, exemplifying how sterilizable probe architectures reduce cleaning validation burdens for perfusion culture operators. These three entities collectively represent the competitive tension between integrated platform consolidation and modular best-of-breed procurement strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Sartorius |
| Nova Biomedical |
| Roche |
| Danaher |
| Beckman Coulter |
| Bio-Rad Laboratories |
| Merck |
| Others |
Supply & Pricing Matrix
Frankfurt-to-Singapore air freight corridors carry high-value chromatography modules and mass spectrometry consumables, with per-kilogram logistics costs compressing margins on entry-level spectrophotometer shipments while amplifying price premiums for GMP-validated analyzer platforms in regulated markets.
Pricing Analysis
Next-generation Raman-chemometric platforms command 40-60% premiums over legacy HPLC systems for titer monitoring, while prior-generation UV-Vis spectrophotometers face commoditization in clone screening applications. Three-tier pricing structure across premium, standard, and economy levels reflects validation burden differentiation, with FDA-pre-qualified systems capturing sustained margin pools. Pricing pressure stems from Indian CDMO procurement teams negotiating multi-site volume discounts for biosimilar contract manufacturing. Biotechnology firms in Boston exhibit lowest price sensitivity due to venture capital funding cushions, while Hyderabad contract manufacturers prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
US export controls on advanced laser and detector components constrain flows of high-resolution mass spectrometry subassemblies to certain manufacturing destinations, forcing vendors to qualify alternative sensor suppliers. Precision optical components concentrate in Germany, Switzerland, and Japan, with fused silica flow cells and diffractive gratings drawing from specialized glassworks in Baden-Württemberg and Nagano prefecture. Single-source vulnerability runs through sterilizable pH probe membranes manufactured at two European facilities. Distribution runs through authorized service organizations that bundle installation qualification with consumable replenishment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of spectroscopic method development chemists and GAMP 5 validation specialists constrain how quickly biomanufacturers can deploy real-time monitoring at greenfield sites, creating arbitrage opportunities for vendors with pre-validated method templates and training academies.
For Market Incumbents: Insulate installed base positions by embedding chemometric software subscriptions into hardware service contracts, raising switching costs for CDMOs operating multi-product facilities. Acquire specialist firms with machine learning-based calibration transfer capabilities to neutralize the threat from modular Raman probe startups. Prioritize backward integration into optical component fabrication to secure supply continuity for dielectric spectroscopy probes. For New Entrants and Emerging Players: Southeast Asian biosimilar manufacturing clusters present underpenetrated demand for at-line fermentation monitoring systems, with Malaysian and Indonesian insulin producers retrofitting legacy stainless-steel trains. Target regenerative medicine contract manufacturers in Japan with non-invasive metabolite sensors designed for iPSC culture compliance. Pursue platform integration partnerships with distributed control system vendors to bypass direct competition with entrenched chromatography incumbents. For Investors and Strategic Acquirers: FDA's advancing process analytical technology enforcement reshapes the acquisition landscape toward vendors with documented 21 CFR Part 11 compliance histories and audit trail software architectures. Long-term viability favors platform ecosystems bundling hardware, consumables, and regulatory documentation over point-solution specialists. Watch for METI funding disbursement velocity as an inflection indicator for Japanese cell therapy infrastructure buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Chemometric Software Acquisition | Machine learning calibration capabilities differentiate Raman platforms from legacy HPLC in titer monitoring. |
| GMP Training Academy Launch | Spectroscopic method development certification programs address skilled operator scarcity in Basel and Boston. |
| Pre-Validated Method Template Expansion | FDA-EMA dual-compliant protocols compress technology transfer timelines for Hyderabad CDMOs. |
| Optical Component Backward Integration | Captive fused silica flow cell production secures supply continuity for mass spectrometry platforms. |
| Regenerative Medicine Sensor Development | Non-invasive metabolite probes capture METI-funded iPSC manufacturing infrastructure deployment. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocess engineering directors, regulatory affairs managers at CDMOs, analytical development scientists, and GMP compliance officers, and refined through secondary validation against FDA warning letter databases, EMA inspection findings, GAMP 5 guidance documents, and instrument vendor service contract disclosures. Bottom-up triangulation across installed base estimates by technology modality converged with top-down expenditure analysis from pharmaceutical capital budgeting surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning measurement technology, end-user sophistication tier, application process stage, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves for real-time monitoring systems. Forecast inputs incorporated continuous manufacturing retrofit timelines at German biosimilar facilities and CDMO greenfield buildout schedules in India.
Practitioners should monitor FDA inspectional observation trends for process analytical technology compliance and EMA Annex 1 revision implementation velocity for early signals of analyzer procurement acceleration. Forecasts reflect documented assumptions regarding skilled labor availability and consumable pricing stability. Material shifts in export control regime stringency or biologics patent cliff timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market