
 Germany Heat Pump Market | 2026-2036
Germany Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Heat Pump Market Analysis
A chronic shortage of certified refrigeration technicians is redrawing competitive dynamics in the Germany heat pump market. Bosch Thermotechnik GmbH leverages its apprenticeship pipeline to sustain installation capacity across southern Germany. Viessmann Climate Solutions SE anchors its position through captive training academies that feed directly into its service network. Daikin Europe N.V. competes by importing specialized field engineers from its broader European operations.
A heat pump extracts thermal energy from ambient air, ground, or water sources and elevates it via vapor-compression refrigeration cycles using refrigerants with low global warming potential to deliver space heating and domestic hot water at coefficients of performance typically ranging from three to five. Air Source systems dominate unit volume due to lower installation complexity, while Ground Source configurations capture premium margin pools where geological conditions permit borehole deployment. Inverter Driven technology leads efficiency benchmarks and now occupies the fastest-growing position within the technology dimension as electricity price volatility intensifies operating cost scrutiny.
The German Building Energy Act (GEG) and KfW federal promotional bank jointly shape demand by mandating renewable heating shares and conditioning subsidized financing on efficiency thresholds. KBA vehicle emission benchmarks and EU F-Gas Regulation refrigerant phase-down rules further constrain product design choices and supply chain configurations. Stakeholders must monitor refrigerant transition timelines and installer certification bottlenecks as decisive variables for capacity planning and margin defense.
Market Dynamics
The chronic scarcity of certified refrigeration technicians is compressing installation capacity across Germany, forcing manufacturers to compete through captive training pipelines rather than product differentiation alone. This labor bottleneck is redrawing competitive boundaries and determining which suppliers can execute the GEG-mandated transition to renewable heating.
Growth Catalysts
- Building Energy Act (GEG):The 2024 mandate requiring renewable heating in new construction creates immediate replacement demand across single-family housing stock. Municipal building authorities enforce compliance through occupancy permitting.
- KfW promotional financing:Federal subsidized loans conditioned on efficiency thresholds accelerate homeowner decisions to retrofit existing oil and gas systems. Approval timelines have compressed from months to weeks.
- Bavaria and Baden-Württemberg:Sparse district heating infrastructure in these southern states concentrates demand for decentralized heat pump solutions. Geological conditions favor ground-source borehole deployment in the Alpine foothills.
Market Restraints
- Refrigerant input volatility:EU F-Gas Regulation phase-down schedules constrain hydrofluorocarbon availability, forcing rapid transition to propane and CO2 alternatives with redesign costs.
- Installation labor concentration:Certified technician pools cluster in western Germany, leaving eastern states underserved and extending project backlogs.
- Electricity price exposure:Residential tariffs determine operating cost competitiveness against gas heating, creating demand sensitivity to wholesale power market swings.
Strategic Opportunities
- Industrial process heat:Temperature lift capabilities above 80°C open commercial and manufacturing applications beyond residential space heating. Food processing and chemical plants represent initial entry points.
- Hybrid system configurations:Integration with existing biomass boilers or solar thermal arrays allows staged retrofit of older buildings without full envelope renovation.
- Service network unbundling:Independent maintenance providers can capture recurring revenue streams as installed base expands beyond manufacturer-affiliated channels.
Industry Challenges
- Meister certification throughput:The dual apprenticeship system produces fewer refrigeration specialists than replacement demand requires. Training durations of 3.5 years cannot compress to match policy timelines.
- Legacy heating system interoperability:Hydronic integration with 1970s-era radiator designs demands flow temperature optimization that degrades heat pump efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Heat Pump Market |
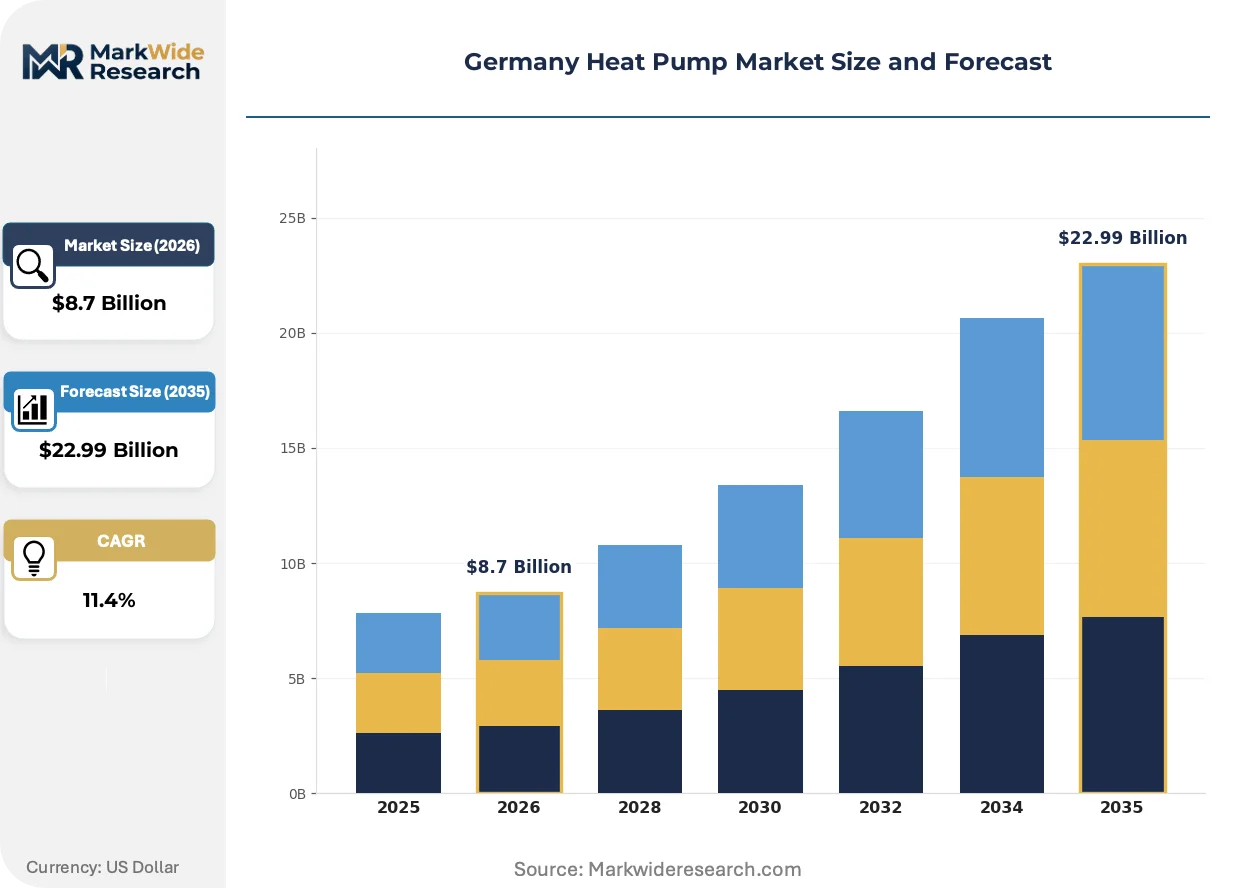
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid Application: Residential Heating, Commercial Heating, Industrial Heating, Domestic Hot Water Technology: Inverter Driven, Single Stage, Multi Stage, Advanced Controls End User: Homeowners, Property Developers, Industrial Facilities, Public Sector |
| Companies Covered | Bosch Thermotechnik GmbH, NIBE Energy Systems, Viessmann Climate Solutions SE, Alpha-InnoTec GmbH, Mitsubishi Electric Corporation, Vaillant Group, Daikin Europe N.V., Wolf GmbH, Stiebel Eltron GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Heat Pump Market Emerging Trajectories
Technology trajectories in the Germany heat pump market center on refrigerant chemistry transitions, inverter control sophistication, and installation workflow digitization. These shifts are compressing product lifecycles while elevating service intensity as a competitive differentiator.
R32 and propane refrigerants are supplanting R410A across air-source product lines due to lower global warming potential and reduced charge volumes. Residential installers in North Rhine-Westphalia have accelerated adoption to preempt F-Gas quota restrictions. This chemistry transition is enabling manufacturers to downsize compressor displacement while maintaining thermal output, compressing equipment footprints for urban retrofit applications.
The EU F-Gas Regulation and its German implementation through the Chemicals Climate Protection Ordinance mandate stepped reductions in hydrofluorocarbon production and import quotas. Equipment manufacturers must redesign heat exchangers and safety systems to accommodate flammable propane alternatives. Southern German suppliers with in-house refrigerant testing capabilities are capturing specification authority from component vendors.
Homeowners are bundling heat pump procurement with building envelope upgrades to maximize KfW efficiency tier bonuses. General contractors in Hamburg and Berlin are consolidating trades into single-source retrofit packages that disaggregate equipment-only distributors. This purchasing consolidation is most visible in multi-unit residential buildings where landlord decisions aggregate demand across ten to twenty units simultaneously.
Germany Heat Pump Market Segmentation
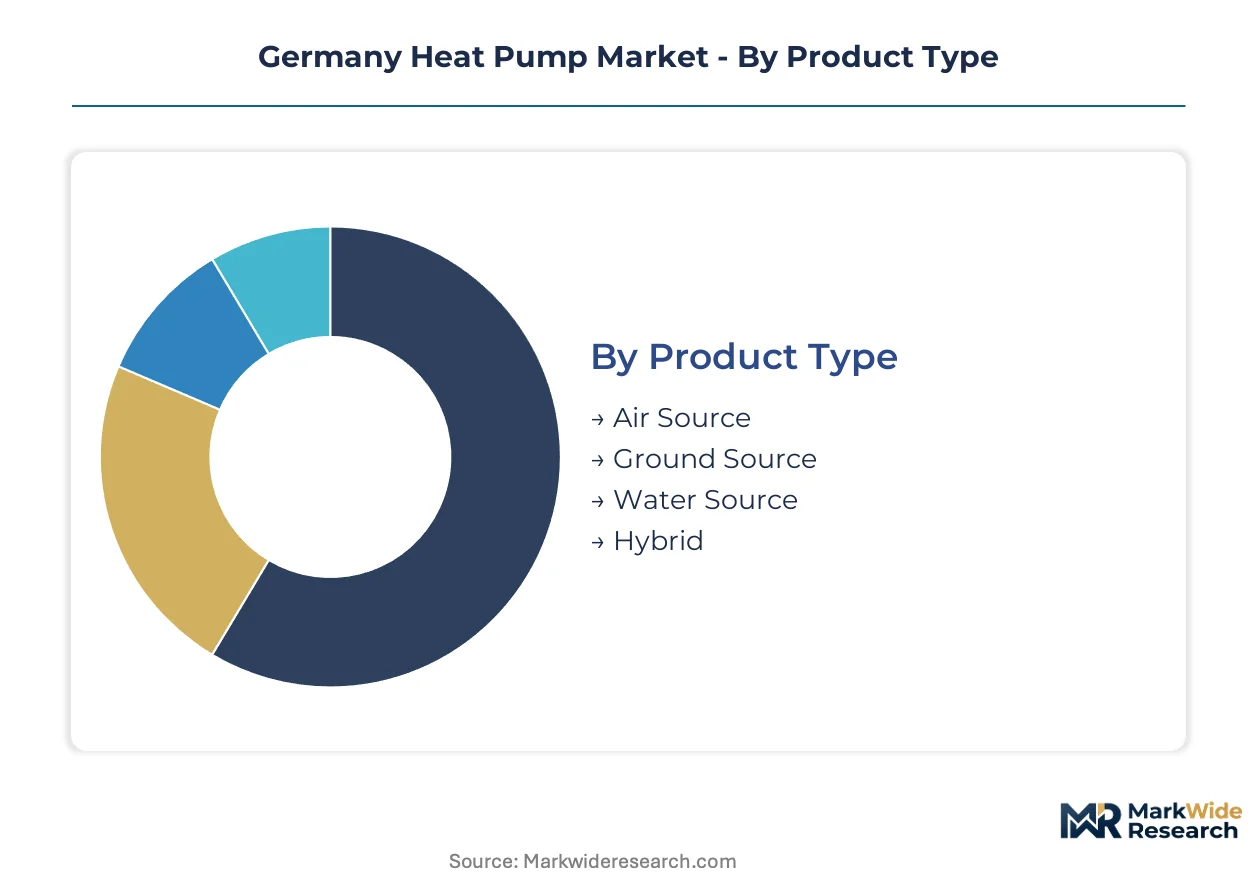
Segmentation in the Germany heat pump market reveals how regulatory mandates and installation constraints reshape competitive boundaries across product categories. Each dimension exposes different vulnerability to substitute heating technologies and divergent paths to margin capture.
Product Type:
Substitution pressure from gas condensing boilers and district heating falls unevenly across thermal source configurations, with some segments enjoying regulatory protection while others compete on pure lifecycle economics.
- Air Source:Ambient air extraction systems deploy vapor-compression cycles with outdoor coil arrays that function across temperature ranges down to minus 20 degrees Celsius. Bavarian single-family retrofits concentrate volume here as borehole drilling faces Alpine topography constraints and municipal permitting delays.
- Ground Source:Geothermal borehole or horizontal collector systems achieve higher coefficients of performance through stable subsoil temperatures. Baden-Württemberg's loess and sandstone formations in the Rhine Valley enable cost-effective drilling depths that anchor premium project economics for this configuration.
- Water Source:Surface water or aquifer extraction delivers superior thermal exchange efficiency where hydrological access permits. Lake Constance shoreline municipalities and Rhine riparian zones represent concentrated addressable demand.
- Hybrid:Dual-source systems combine heat pump operation with auxiliary gas or biomass firing for peak-load coverage. Older building stock with 1970s radiator designs drives uptake where pure heat pump flow temperatures would degrade efficiency below viable thresholds.
Air Source anchors the volume base while Hybrid configurations gain share at the steepest rate as building envelope limitations persist in the retrofit channel.
Application:
Cost tier stratification separates subsidized residential retrofits from self-financed commercial decisions and capital-intensive industrial process heat projects with distinct payback horizons.
- Residential Heating:Space conditioning for single-family and multi-family dwellings dominates unit shipments under GEG compliance deadlines and KfW promotional loan availability. Northern Rhineland cluster installations concentrate where oil heating replacement urgency intersects with installer network density.
- Commercial Heating:Office, retail, and hospitality thermal loads operate across extended duty cycles that favor inverter modulation and part-load efficiency optimization. Berlin and Hamburg commercial property managers aggregate demand across portfolios that justify dedicated maintenance contracts.
- Industrial Heating:Process temperature requirements above 80 degrees Celsius demand high-temperature lift compressors and cascade configurations. Food processing plants in Lower Saxony and chemical operations in the Chemical Triangle represent initial adoption frontiers.
- Domestic Hot Water:Dedicated heat pump water heaters address year-round thermal demand independent of space heating loads. New construction plumbing specifications increasingly mandate this segment as baseline equipment.
Residential Heating commands the revenue base while Industrial Heating applications expand most quickly as temperature lift capabilities mature.
Technology:
Customer type differentiation separates price-sensitive homeowner procurement from developer bulk specifications and industrial engineering-procurement-construction contractor relationships with divergent technical evaluation criteria.
- Inverter Driven:Variable-speed compressor modulation matches thermal output to building load profiles across partial-load conditions that dominate annual operation. Electricity price volatility intensifies scrutiny of seasonal performance factors that favor this technology's efficiency profile.
- Single Stage:Fixed-capacity compression cycles operate at full output or off-state with simpler control architectures and lower capital cost. Rental property landlords in eastern Germany prioritize upfront acquisition cost over operating expense minimization.
- Multi Stage:Dual or triple compressor staging provides discrete capacity steps between full-load and minimum operation. Mid-size commercial applications with variable occupancy patterns favor this intermediate cost-performance positioning.
- Advanced Controls:Integrated building management system connectivity, weather compensation, and predictive demand algorithms optimize system dispatch. Smart home integration requirements in premium new construction specifications drive specification authority toward this tier.
Inverter Driven technology captures the dominant revenue share while Advanced Controls climbs the fastest as grid-interactive flexibility services monetize.
End User:
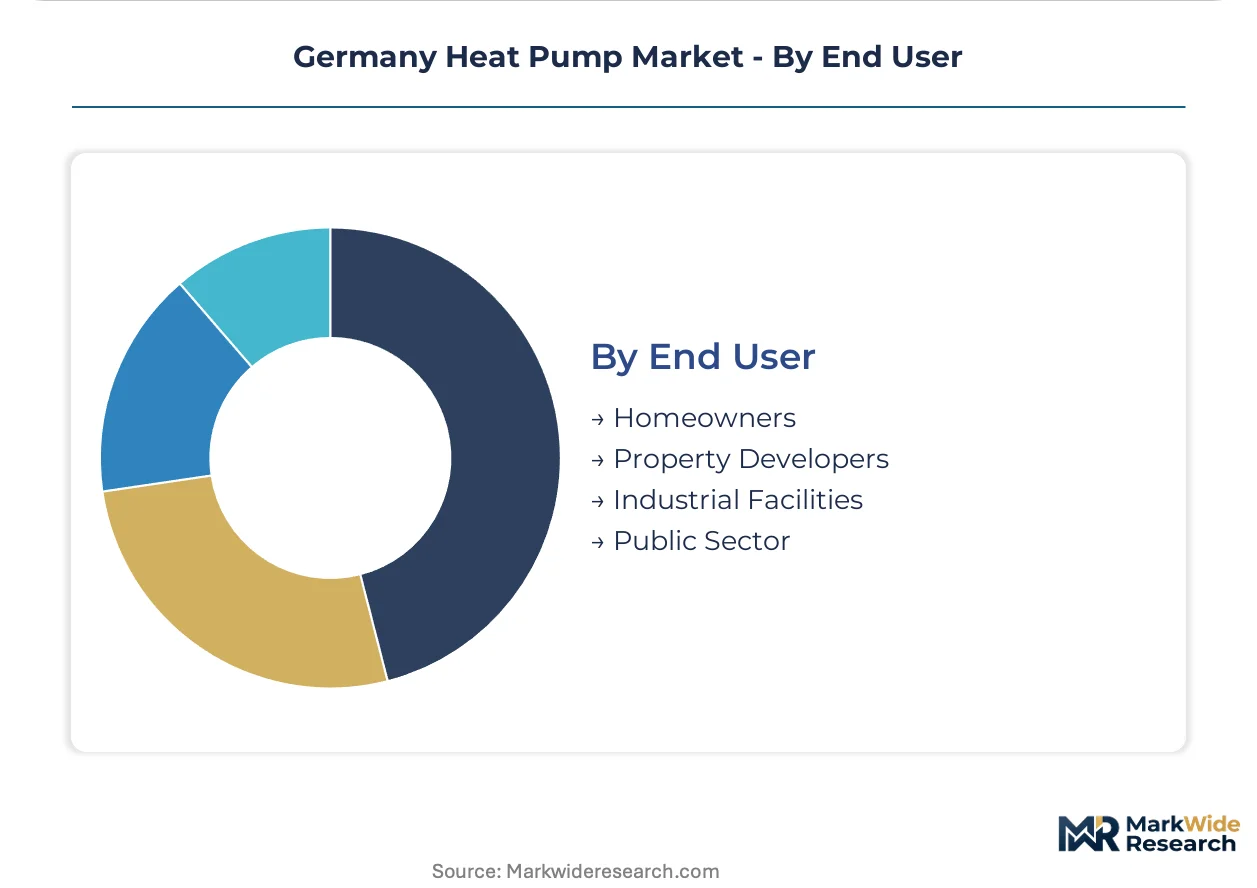
Geographic concentration of decision-making authority varies sharply across end user categories, with some segments aggregating demand through centralized procurement and others fragmenting across millions of individual transactions.
- Homeowners:Individual residential decision-makers navigate KfW application procedures and installer selection with high information asymmetry. Southern Germany's higher disposable income concentrations correlate with ground-source system selection rates.
- Property Developers:Multi-unit residential and commercial project developers specify equipment across standardized building typologies with volume procurement leverage. Hamburg and Berlin general contractors increasingly bundle envelope and mechanical trades into single-source packages.
- Industrial Facilities:Energy managers and process engineers evaluate heat pump integration against combined heat and power and biomass alternatives with complex lifecycle analysis. Chemical Triangle operations prioritize temperature lift capabilities above efficiency metrics.
- Public Sector:Municipal building authorities and federal facility managers face GEG compliance mandates with procurement procedures that favor established supplier relationships and extended warranty terms.
Homeowners sustain the volume foundation while Property Developers are expanding their share most rapidly as multi-unit construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria and Baden-Württemberg deploy ground-source borehole systems at rates exceeding northern states, while North Rhine-Westphalia concentrates air-source retrofits where oil heating replacement urgency intersects with denser installer networks.
Bavaria
Alpine topography constrains district heating penetration across southern Bavaria, elevating decentralized heat pump demand. The German Building Energy Act enforces renewable heating shares through municipal occupancy permitting. Munich and Augsburg suburbs concentrate single-family retrofits where higher disposable incomes correlate with ground-source system selection.
Baden-Württemberg
Loess and sandstone formations in the Rhine Valley enable cost-effective geothermal drilling depths. KfW promotional financing accelerates homeowner decisions with compressed approval timelines. Stuttgart and Karlsruhe manufacturing clusters anchor industrial process heat pilot programs targeting food processing applications.
North Rhine-Westphalia
Oil heating replacement urgency drives retrofit velocity across the Ruhr industrial belt and Cologne-Bonn corridor. The Chemicals Climate Protection Ordinance implements EU F-Gas refrigerant phase-down schedules. Düsseldorf and Dortmund general contractors bundle envelope and mechanical trades into single-source packages.
Lower Saxony
Food processing plants in this agricultural heartland represent initial industrial adoption frontiers for high-temperature lift applications. Federal KfW efficiency tier bonuses condition subsidized financing on building envelope performance thresholds. Hanover and Braunschweig energy managers evaluate heat pump integration against combined heat and power alternatives.
Hesse
Frankfurt-Rhine-Main commercial property managers aggregate demand across portfolios justifying dedicated maintenance contracts. Grid-interactive flexibility services monetize inverter-driven efficiency profiles for part-load optimization. Wiesbaden and Darmstadt smart home integration requirements in premium new construction drive advanced controls specification.
Germany Heat Pump Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding specification authority through captive training pipelines and the lower tier competing on installation responsiveness. The market structure compresses around technician certification scarcity rather than product differentiation alone. Three archetypes dominate: diversified industrial conglomerates with apprenticeship infrastructure, pure-play climate specialists with regional service density, and Japanese electronics multinationals importing pan-European technical capacity. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as firms race to secure installation labor before GEG compliance deadlines.
Among German industrial conglomerates, Bosch Thermotechnik GmbH and Viessmann Climate Solutions SE exemplify the integrated-leader archetype through their respective apprenticeship and training academy infrastructures. Daikin Europe N.V. occupies a position representing the multinational electronics vector, drawing specialized field engineers from broader European operations to address technician concentration gaps in eastern states.
| Leading Market Players |
|---|
| Bosch Thermotechnik GmbH |
| NIBE Energy Systems |
| Viessmann Climate Solutions SE |
| Alpha-InnoTec GmbH |
| Mitsubishi Electric Corporation |
| Vaillant Group |
| Daikin Europe N.V. |
| Wolf GmbH |
| Stiebel Eltron GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale economies in compressor production anchor price floors across the Germany heat pump market, concentrating bargaining power among vertically integrated producers while compressing margins for assembly-only competitors. The KfW efficiency tier system conditions subsidized financing on performance thresholds, creating discrete price bands that separate certified premium configurations from economy alternatives.
Pricing Analysis
Project-based contracting dominates residential procurement, with homeowners receiving bundled quotes covering equipment, installation, and commissioning rather than component-only transactions. Price differentiation rests on Meister certification status and ground-source drilling complexity, with Bavarian borehole deployments commanding substantial premiums over standard air-source retrofits. Cost compression in the air-source tier is intensifying because refrigerant transition costs and technician scarcity squeeze installer margins. Rental property landlords in eastern Germany exhibit highest price sensitivity, prioritizing capital cost minimization over lifecycle operating expense.
Supply Chain Analysis
Refrigerant import quotas under EU F-Gas Regulation implementation constitute the critical chokepoint, constraining hydrofluorocarbon availability and forcing accelerated transition to propane and CO2 alternatives. Component sourcing draws from China for compressor motors, Italy for heat exchangers, and Poland for sheet metal enclosures. Single-source vulnerability concentrates in semiconductor-based inverter drives, where automotive sector demand competes for foundry capacity. Distribution runs through manufacturer-affiliated installer networks in western Germany, with independent wholesalers serving eastern territories where captive channels remain underdeveloped.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany heat pump market sits in cyclical recovery phase, with installation capacity constraints creating temporary supply inelasticity that will ease as apprenticeship pipelines mature. The KfW promotional cycle and GEG compliance deadlines generate predictable demand waves that favor prepared suppliers.
For Market Incumbents: Compound service network density through captive training academy expansion before competitor apprenticeship pipelines mature. Deepen backward integration into refrigerant testing capabilities to capture specification authority from component vendors as propane transition accelerates. The emerging threat of independent maintenance providers unbundling recurring revenue streams demands preemptive channel control investments.
For New Entrants and Emerging Players: Lead with industrial process heat applications above 80°C temperature lift, where technical differentiation outweighs brand recognition and incumbent service density matters less. Food processing plants in Lower Saxony represent the most penetrable segment, with chemical operations in the Chemical Triangle offering follow-on expansion. A go-to-market angle targeting energy managers with lifecycle cost analysis against combined heat and power alternatives bypasses residential installer network disadvantages.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play climate specialists with regional service density over diversified conglomerates facing capital allocation trade-offs. Long-term viability across the next decade hinges on refrigerant transition execution and installer certification throughput. The signal to watch is eastern German permit approval velocity, which indicates whether labor mobility or training expansion will resolve capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Apprenticeship Pipeline Expansion | Bosch and Viessmann training academies secure installation capacity ahead of GEG deadlines. |
| Refrigerant Testing Capability Investment | In-house propane safety certification captures specification authority from component vendors. |
| Industrial Process Heat Pilot Programs | Baden-Württemberg food processing trials open commercial applications beyond residential heating. |
| Installer Network Unbundling | Independent maintenance providers capture recurring revenue as installed base expands. |
| Hybrid System Configuration Development | Biomolar integration addresses 1970s radiator retrofit limitations without full envelope renovation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association data, and equipment shipment records. Interviews with refrigeration Meister instructors, municipal building authority inspectors, KfW program administrators, and HVAC contractor operations managers provided ground-level validation. Secondary sources include BAFA subsidy disbursement databases, VDMA production statistics, and BDH installer network surveys. Bottom-up unit shipment aggregation and top-down addressable market sizing were cross-validated to establish baseline figures.
Segmentation dimensions modeled span product type, application, technology tier, and end user category across the projection horizon. CAGRs were derived from trend extrapolation adjusted for policy implementation schedules and labor supply constraints. Industry-specific forecast inputs incorporate refrigerant quota phase-down timelines under EU F-Gas Regulation and Meister certification completion rates from the dual apprenticeship system.
The analysis sits within stated boundaries; outcomes outside KfW promotional continuity or GEG enforcement intensity would require recalibration. Forecasts reflect assumptions regarding technician training throughput and electricity price trajectory stability. Practitioners should keep alternative scenarios live as F-Gas quota allocations and federal coalition energy policy priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
GCC Portable Air Conditioners Market