
 North America Ceiling Cassette Market | 2026-2036
North America Ceiling Cassette Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceiling Cassette Market Analytics
The DOE's regional efficiency standards is restructuring the cost-of-entry calculus for ceiling cassette manufacturers serving the North American market. Daikin North America LLC leverages its captive compressor manufacturing to absorb regulatory cost shocks more efficiently than import-dependent rivals. Mitsubishi Electric Trane HVAC US LLC anchors its position through deep VRF engineering expertise and extensive contractor certification programs. Carrier Global Corporation competes by extending its building automation ecosystem into integrated ceiling cassette controls.
A ceiling cassette is a ductless indoor HVAC unit recessed into a suspended ceiling grid, typically housing a centrifugal fan, heat exchanger coil, and multi-directional air discharge louvers engineered to distribute conditioned air across open floor plates without exposed ductwork. The unit serves commercial and light industrial spaces where overhead infrastructure must remain concealed and zone-level climate control takes priority over central air handling. Multi-split systems command the largest installed base among product types due to their balance of first cost and per-zone flexibility, while VRF systems capture the fastest expansion as developers pursue electrification pathways and decarbonization targets. Wi-Fi enabled controls are pulling margin pools away from basic wired configurations as building owners prioritize remote diagnostics and utility demand-response integration.
DOE regional efficiency standards, ASHRAE 90.1 building energy codes, and Canada's NRCan equipment regulations collectively shape product certification requirements and minimum performance thresholds across the North American ceiling cassette market. Mexico's CONUEE labeling program adds a third compliance layer for manufacturers seeking unified product platforms across the trade bloc. Stakeholders must monitor how refrigerant phase-down schedules under the AIM Act interact with state-level building electrification mandates to determine whether next-generation equipment investments align with emerging installation demand patterns.
Market Dynamics
The DOE's regional efficiency standards are compressing replacement cycles across the ceiling cassette market while simultaneously elevating the capital threshold for manufacturer participation. Equipment buyers in Texas and California commercial corridors now face accelerated obsolescence timelines that favor modular, refrigerant-ready platforms over legacy fixed-speed units.
Growth Catalysts
- Multi-Split System Demand:Mixed-use developers across the United States, Canada, and Mexico specify these configurations for zone-level climate control without exposed ductwork. The format balances first cost against per-zone flexibility in open floor plate designs.
- AIM Act Phase-Down Schedules:Refrigerant transition mandates are pulling forward replacement demand as building owners preempt stricter hydrofluorocarbon restrictions. Contractors report compressed bidding windows for equipment with lower global warming potential ratings.
- Wi-Fi Control Integration:Utility demand-response programs in California and Texas are incentivizing connected ceiling cassettes. Remote diagnostics capability is shifting specification criteria away from basic wired configurations.
Market Restraints
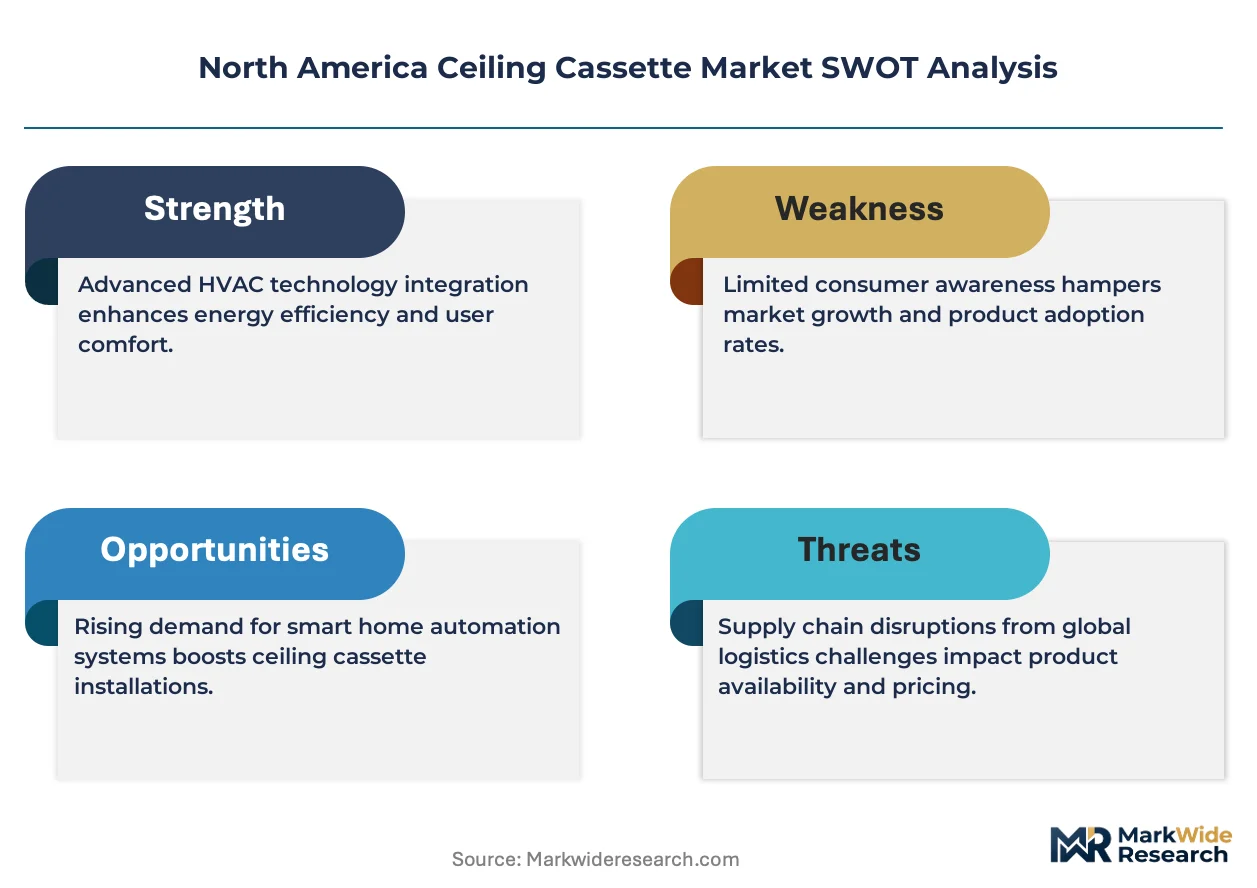
- Copper and Aluminum Input Volatility:Heat exchanger coil manufacturing faces margin pressure from commodity price swings. Compressor castings and refrigerant-grade tubing constitute concentrated cost exposure for domestic assembly operations.
- Mexico CONUEE Labeling Complexity:Unified product platforms across the USMCA trade bloc require third certification layer duplicating DOE and NRCan testing protocols. Small-batch manufacturers lack economies of scale to absorb redundant compliance overhead.
- VRF System Skill Scarcity:Refrigerant piping installation and commissioning demands specialized technician certification. The contractor base trained in variable refrigerant flow engineering remains thinner than conventional split system capacity.
Strategic Opportunities
- Canadian Electrification Mandates:Provincial building codes in British Columbia and Ontario are accelerating fossil fuel heating displacement. Cold-climate heat pump ceiling cassettes command specification premiums in these jurisdictions.
- Building Automation Convergence:BACnet and Modbus protocol integration with ceiling cassette controls creates stickier specification relationships. Developers pursuing LEED certification prioritize native interoperability over standalone equipment.
- Texas Commercial Retrofit Channel:Independent rep firms and mechanical contractors in Dallas-Fort Worth and Houston corridor are consolidating procurement authority. Direct manufacturer engagement with these intermediaries bypasses traditional wholesale markup structures.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:EPA Section 608 technician credentialing delays are constraining installation crew expansion. The 18-month training pipeline cannot match current project backlog velocity.
- Legacy Control System Integration:Pneumatic and proprietary thermostat networks in 1980s-1990s commercial stock resist digital retrofit. Ceiling cassette deployments require parallel infrastructure upgrades that balloon project scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceiling Cassette Market |
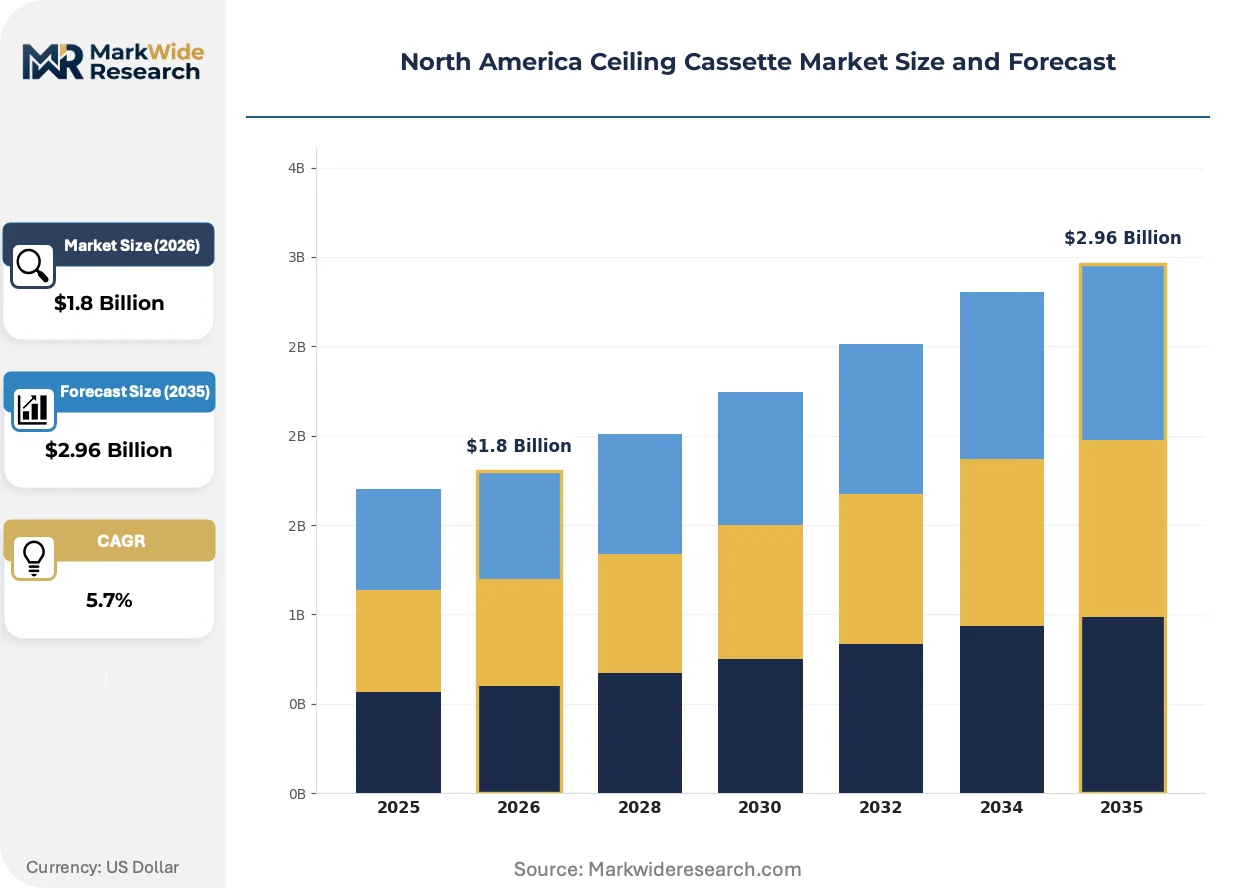
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Multi-Split System, VRF System, Package Unit Installation Type: Residential, Commercial, Industrial, Retrofit End User: Building Owners, Contractors, Architects, Facility Managers Control Mechanism: Remote Control, Wi-Fi Enabled, Wired Controller, Manual Control |
| Companies Covered | Daikin North America LLC, Commercial Systems North America (Carrier), Mitsubishi Electric Trane HVAC US LLC, Lennox International, Inc., Nortek North America HVAC, Carrier Global Corporation, Johnson Controls International PLC, Rheem Manufacturing Company, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceiling Cassette Market Evolving Landscape
Refrigerant chemistry transitions and connected control architectures are restructuring equipment value pools across the North American ceiling cassette market. Manufacturers must now engineer for compliance velocity rather than static efficiency optimization.
Variable refrigerant flow technology is absorbing the bulk of engineering investment as developers pursue electrification pathways and decarbonization targets. Large-scale mixed-use projects in California and Texas specify VRF ceiling cassettes for their part-load efficiency advantages over fixed-capacity alternatives. The technology is absorbing margin pools from conventional multi-split configurations by bundling zone-level metering with utility interconnection capability.
The DOE's regional efficiency standards are forcing manufacturer platform consolidation across cooling-dominated and heating-dominated climate zones. Equipment lines must now satisfy divergent minimum performance thresholds without SKU proliferation that would strain distributor inventory systems. The multi-split segment faces the steepest compliance cost escalation as its price-sensitive buyer base resists premium absorption.
Building owners are unbundling after-sales service contracts from original equipment procurement, treating maintenance as a separate competitive bid category. Mechanical contractors in the Texas Triangle and Southern California corridor now compete against independent service aggregators for long-term ceiling cassette upkeep revenue. The disintermediation is most visible in Class B office retrofits where capital and operating budgets sit under separate ownership structures.
North America Ceiling Cassette Market Segmentation
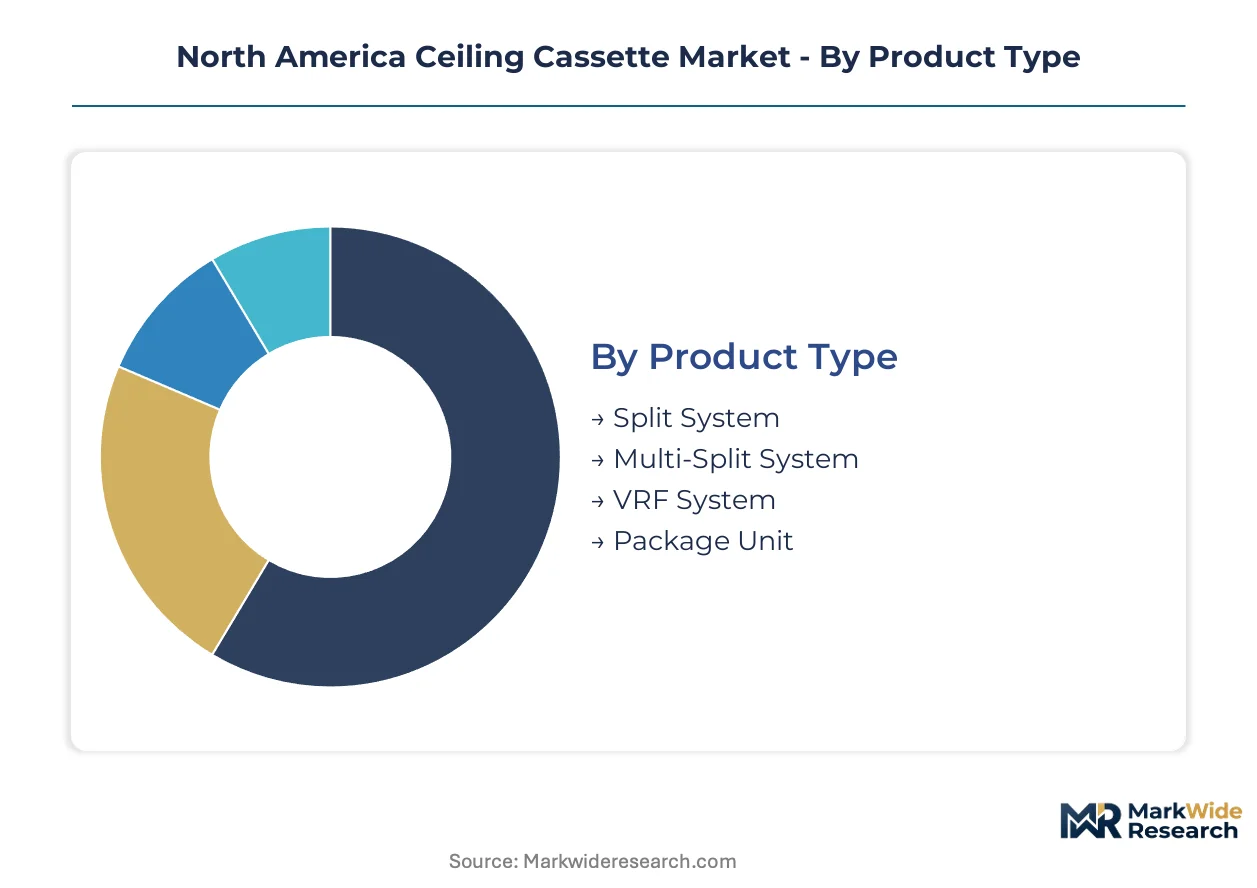
Ceiling cassette procurement patterns diverge sharply across building typologies and control architectures. Specification authority sits with different stakeholders depending on whether the deployment serves new construction or retrofit channels.
Product Type:
Refrigerant distribution architecture determines first cost, zone flexibility, and compliance trajectory across climate zones.
- Multi-Split System:One outdoor unit serves two to five indoor ceiling cassettes through discrete refrigerant lines. Mixed-use developers in Dallas-Fort Worth and Houston specify these configurations for per-zone metering without full VRF investment.
- VRF System:Variable refrigerant flow platforms modulate capacity across 20+ indoor units from a single outdoor chassis. California electrification mandates and Texas commercial retrofits are accelerating specification as developers pursue decarbonization pathways and utility demand-response integration.
- Split System:Single indoor-outdoor pairings dominate residential and small commercial footprints where zoning complexity remains minimal.
- Package Unit:Self-contained systems with integrated compressors serve industrial and specialized applications requiring rapid deployment without refrigerant piping infrastructure.
Mature deployment sits with Multi-Split System configurations. Newer deployment is concentrated in VRF System specifications.
Installation Type:
Project delivery mode dictates equipment selection criteria and margin absorption capacity.
- Commercial:Open floor plate offices, retail pods, and hospitality lobbies drive specification volume. Building automation integration requirements and ASHRAE 90.1 code compliance filter equipment selection toward connected, high-efficiency platforms.
- Retrofit:Equipment replacement in 1980s-1990s commercial stock across Texas and California corridors accelerates as DOE regional efficiency standards compress obsolescence timelines. Contractors face compressed bidding windows for refrigerant-ready platforms.
- Residential:High-end custom homes and multi-family common areas specify ceiling cassettes for aesthetic concealment, though volume trails ducted alternatives.
- Industrial:Light manufacturing and warehouse applications prioritize durability and rapid service access over control sophistication.
Volume concentrates in Commercial new construction. Margin expansion is strongest in Retrofit deployment.
End User:
Procurement authority fragments across the project lifecycle, with specification influence shifting from design through operations.
- Building Owners:Institutional investors and REITs driving Class B office retrofits in Texas and California now unbundle capital and operating budgets. These stakeholders prioritize lifecycle cost modeling and utility incentive capture over first-cost minimization.
- Contractors:Mechanical contractors in the Dallas-Fort Worth and Houston corridor consolidate procurement authority through direct manufacturer relationships. EPA Section 608 credentialing bottlenecks constrain crew expansion velocity.
- Architects:Design-phase specification authority centers on aesthetic integration and ceiling grid coordination, though control architecture decisions often transfer to MEP engineers.
- Facility Managers:Operations-phase stakeholders increasingly demand Wi-Fi enabled diagnostics and BACnet interoperability for remote monitoring and predictive maintenance scheduling.
Early-phase influence rests with Architects. Long-term specification stickiness depends on Facility Manager priorities.
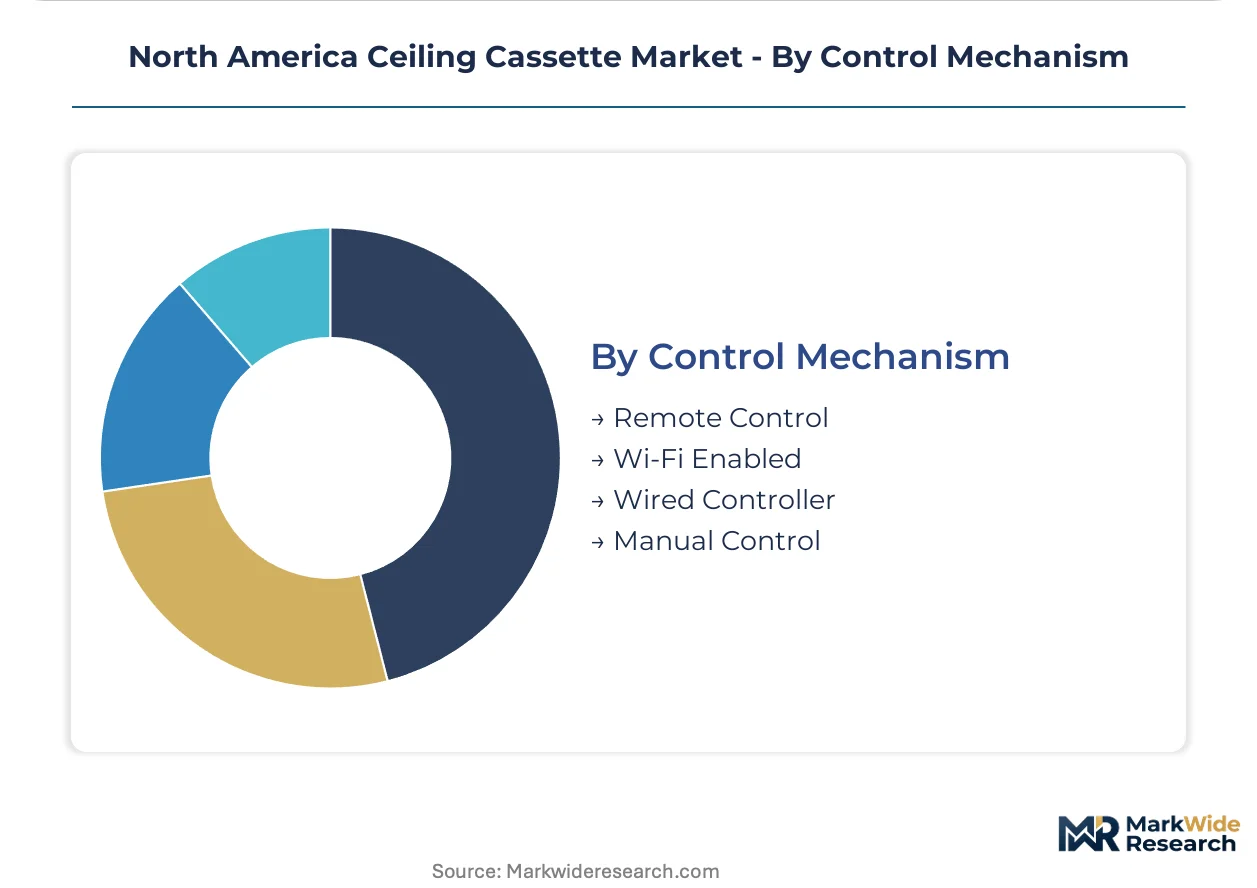
Control Mechanism:
Connectivity architecture is restructuring margin pools and competitive differentiation.
- Wi-Fi Enabled:Native cloud connectivity supports utility demand-response programs in California and Texas, plus remote diagnostics that reduce truck-roll frequency. Specification premiums reflect software integration depth rather than hardware cost.
- Wired Controller:BACnet and Modbus protocol integration serves building automation convergence requirements. LEED-certified developments prioritize native interoperability over standalone operation.
- Remote Control:Infrared handheld units persist in cost-sensitive segments and legacy replacement scenarios.
- Manual Control:Basic dial or button interfaces occupy minimal specification share, limited to industrial and temporary applications.
Specification gravity is shifting from Wired Controller toward Wi-Fi Enabled platforms as utility programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across Texas and California commercial corridors are concentrating ceiling cassette deployment capital. Federal tax incentives accelerate retrofit velocity in designated census tracts. State-level electrification mandates layer additional compliance requirements onto equipment selection criteria.
United States
Texas and California commercial corridors drive replacement demand as DOE regional efficiency standards compress equipment lifecycles. The EPA's AIM Act refrigerant phase-down schedules pull forward procurement timelines for lower-GWP platforms. Dallas-Fort Worth and Houston mechanical contractors consolidate procurement authority through direct manufacturer relationships.
Canada
British Columbia and Ontario provincial codes accelerate fossil fuel heating displacement in commercial stock. Natural Resources Canada equipment regulations impose third certification requirements on USMCA-integrated product platforms. Toronto and Vancouver mixed-use developers specify cold-climate heat pump ceiling cassettes for electrification compliance.
Mexico
CONUEE labeling programs add compliance overhead for manufacturers seeking unified North American product architectures. The USMCA trade framework enables integrated supply chains but duplicates testing protocols across three regulatory jurisdictions. Mexico City Metro and Nuevo León industrial zones absorb equipment flows for commercial and light manufacturing deployment.
North America Ceiling Cassette Market Competitive Landscape
Japanese and American producers anchor one tier; European-heritage specialists hold adjacent positions through building automation integration. The vendor base clusters around three strategic archetypes: captive compressor manufacturers absorbing regulatory cost shocks, VRF engineering specialists with deep contractor certification programs, and building automation integrators extending control ecosystems. Consolidation pressure favors M&A activity among mid-scale fabricators lacking refrigerant-ready platforms. Technology licensing agreements proliferate as smaller players seek compliance velocity without internal R&D scale.
Within the integrated-manufacturing tier, Daikin North America LLC and Mitsubishi Electric Trane HVAC US LLC exemplify divergent approaches to regulatory adaptation. Daikin leverages captive compressor production to internalize cost pressures from DOE efficiency standards. Mitsubishi Electric Trane HVAC US LLC occupies a position defined by VRF engineering depth and extensive technician certification infrastructure. Carrier Global Corporation represents the building-automation convergence archetype, with controls integration rather than hardware differentiation driving specification stickiness.
| Leading Market Players |
|---|
| Daikin North America LLC |
| Commercial Systems North America (Carrier) |
| Mitsubishi Electric Trane HVAC US LLC |
| Lennox International, Inc. |
| Nortek North America HVAC |
| Carrier Global Corporation |
| Johnson Controls International PLC |
| Rheem Manufacturing Company |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
The EPA's AIM Act refrigerant phase-down gates qualified supply and premium-tier pricing access, compressing procurement timelines for lower-GWP platforms while elevating capital thresholds for manufacturers lacking refrigerant-ready engineering pipelines. Buyers now face accelerated obsolescence cycles that favor modular equipment architectures over legacy fixed-speed configurations.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent retrofit procurement from planned new construction deployment, with Texas and California commercial corridors commanding premiums for compressed delivery windows. Three-tier pricing structure across premium Wi-Fi-enabled VRF, standard multi-split, and economy wired-controller configurations reflects certification depth and control sophistication. Cost compression in the multi-split tier is intensifying as commodity input volatility and redundant CONUEE compliance overhead squeeze import-dependent fabricators. Small-batch manufacturers exhibit highest price sensitivity, while institutional REITs driving Class B retrofits absorb specification premiums for lifecycle cost optimization.
Supply Chain Analysis
Copper and aluminum coil supply rests on Chilean mining operations, Chinese semi-finished metal processing, and domestic US tubing fabrication for refrigerant-grade distribution networks. Compressor castings draw from Mexican foundries serving USMCA-integrated assembly plants, while electronic control modules source from Taiwanese semiconductor packaging facilities. Single-source vulnerability concentrates in specialty refrigerant handling equipment and EPA Section 608 certification infrastructure. Distribution runs through consolidating mechanical contractor networks in Dallas-Fort Worth and Houston that bypass traditional wholesale markup structures through direct manufacturer engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DOE's regional efficiency standards construct a formidable barrier-to-entry moat, elevating compliance capital requirements beyond mid-scale fabricator capacity and consolidating competitive advantage among refrigerant-ready platform holders.
For Market Incumbents: Extend captive compressor manufacturing advantages into cold-climate heat pump variants for Canadian electrification mandates, while deepening technician certification infrastructure to constrain contractor base expansion by import-dependent rivals. Refrigerant handling credentialing bottlenecks and legacy control integration complexity defend installed base stickiness against emerging building-automation convergence threats from adjacent ecosystem players. For New Entrants and Emerging Players: The mid-tier pricing gap between Daikin-Mitsubishi premium positioning and economy wired-controller alternatives opens specification traction in Texas commercial retrofit channels where independent rep firms consolidate procurement authority. Target Dallas-Fort Worth mechanical contractor direct relationships with refrigerant-ready multi-split platforms priced below VRF alternatives, leveraging utility demand-response program eligibility as the primary go-to-market wedge against established distribution networks. For Investors and Strategic Acquirers: EPA Section 608 training pipeline expansion velocity is the leading indicator that installation crew scarcity will persist, favoring acquisition targets with captive service infrastructure over pure equipment fabricators. Five-to-ten year viability centers on refrigerant chemistry transition readiness and BACnet-native control architectures. Watch California Title 24 building code amendment timing as the signal for accelerated electrification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Consolidation | Unified USMCA-compliant product architectures reduce redundant CONUEE, DOE, and NRCan testing overhead for cross-border equipment flows. |
| Technician Certification Infrastructure | EPA Section 608 credentialing pipelines constrain installation capacity expansion, creating defensive moats for incumbent service networks. |
| Building Automation Protocol Integration | Native BACnet and Modbus interoperability captures LEED-certified development specifications and utility demand-response program eligibility. |
| Cold-Climate Heat Pump Engineering | British Columbia and Ontario electrification mandates command specification premiums for low-ambient performance ceiling cassette variants. |
| Direct Contractor Channel Development | Bypassing wholesale distribution in Texas Triangle corridors captures margin compression from consolidating mechanical rep firm procurement authority. |
Research Methodology
Multi-period observation of DOE efficiency standard implementation timelines, refrigerant phase-down schedules, and utility incentive program maturation anchored the trend analysis, supplemented by interviews with mechanical contractors, MEP engineers, facility managers at Class B office REITs, and HVAC distributor procurement leads. Secondary validation drew from EPA AIM Act regulatory filings, Natural Resources Canada equipment certification databases, CONUEE labeling protocols, and USMCA trade flow customs records. Bottom-up equipment shipment tracking and top-down construction spending allocation triangulated market sizing across the analysis window.
Segment-weighting applied product type, installation mode, end user procurement authority, and control mechanism connectivity as primary analytical dimensions throughout the forecast period. CAGRs were derived from regression analysis against construction spending indices, regulatory compliance cost trajectories, and electrification mandate adoption curves. Input variables included Texas and California commercial retrofit permit velocity, Canadian provincial building code amendment timing, and Mexican industrial zone absorption capacity.
Inputs from EPA regulatory filings, DOE efficiency standard dockets, and provincial code development proceedings were available through the study window; gaps in real-time contractor backlog data and refrigerant price forward curves introduce uncertainty bands around replacement cycle velocity assumptions. Forecasts reflect documented analytical assumptions with sensitivity analysis around commodity input volatility and credentialing pipeline expansion scenarios. Refrigerant chemistry transition timing and state-level electrification mandate enforcement intensity warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
North America Bus HVAC Market