
 Dental Etching Liquid Market | 2026-2036
Dental Etching Liquid Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Etching Liquid Market Outlook
Phosphoric acid is recalibrating product economics as manufacturers reformulate around concentration gradients that balance enamel demineralization with controlled depth profiles. Ultradent Products leverages its Utah-based manufacturing infrastructure to sustain North American supply continuity. Dentsply Sirona anchors European distribution through specialized dental dealer networks. Ivoclar Vivadent differentiates via integrated adhesive system bundling that extends beyond standalone etchant sales.
Dental etching liquid is an aqueous acidic preparation, typically containing 35-37% phosphoric acid by weight, designed to create microporous enamel and dentin surfaces through controlled demineralization to enable micromechanical retention of resin-based restorative and orthodontic materials. The formulation may incorporate buffering agents, dyes for visual placement control, and viscosity modifiers to prevent uncontrolled flow onto adjacent soft tissues or prepared surfaces. Phosphoric acid formulations dominate volume due to decades of clinical validation and predictable etch patterns, while maleic acid and polyacrylic acid alternatives occupy niche positions where gentler substrate interaction is clinically indicated. Orthodontics and restorative dentistry represent the largest application segments, with preventive care emerging as a faster-growing channel as resin sealant protocols expand in pediatric and public health dentistry programs.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and labeling requirements for dental etching liquids across major markets. ISO 10993 biocompatibility testing and country-specific pharmacopeial standards further constrain formulation flexibility and supplier qualification. Stakeholders must monitor evolving regulatory convergence between FDA and notified body expectations as both jurisdictions intensify scrutiny of chemical constituent disclosure and post-market surveillance obligations.
Market Dynamics
Resin-based adhesive protocol standardization across dental specialties is compressing formulation margins while expanding volume throughput, as clinicians consolidate around fewer supplier ecosystems to reduce chairside complexity and inventory carrying costs.
Growth Catalysts
- CE marking under EU MDR:Harmonized biocompatibility testing requirements under ISO 10993 are accelerating supplier qualification cycles, reducing regulatory fragmentation for cross-border dental product distribution.
- Orthodontic bracket bonding:Self-ligating bracket systems and clear aligner attachment protocols are consuming higher etchant volumes per patient as treatment plans lengthen and refinement stages multiply.
- Domestic manufacturing in China:NMPA registration pathway streamlining and provincial medical device cluster incentives are expanding local phosphoric acid formulation capacity for Asia-Pacific supply.
Market Restraints
- Phosphoric acid feedstock volatility:Fertilizer industry demand fluctuations and sulfuric acid supply chain constraints are transmitting price instability into etchant raw material costs.
- Supplier concentration in specialty chemicals:Three German and Chinese chemical houses control high-purity phosphoric acid grades suitable for dental applications, creating single-source vulnerability.
- Self-etch adhesive substitution:Seventh-generation universal adhesives with integrated acidic monomers are displacing separate etch-and-rinse protocols in select restorative indications.
Strategic Opportunities
- Pediatric preventive programs:School-based resin sealant initiatives in India and Indonesia are opening high-volume, price-sensitive channels distinct from private practice procurement.
- Digital workflow integration:CAD/CAM chairside milling and 3D-printed indirect restorations are creating demand for etchants optimized for hybrid ceramic and composite resin substrates.
- PLI scheme alignment:India's production-linked incentive framework for medical devices is attracting contract manufacturing investment for export-oriented dental chemical production.
Industry Challenges
- ISO 13485 quality management implementation:Small-formulation specialists face capital requirements for cleanroom expansion and batch record digitization to serve tier-one dental distributors.
- Dye and viscosity modifier sourcing:FDA color additive regulations and REACH SVHC candidate list evolution are forcing reformulation cycles that compress product lifecycle economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Etching Liquid Market |
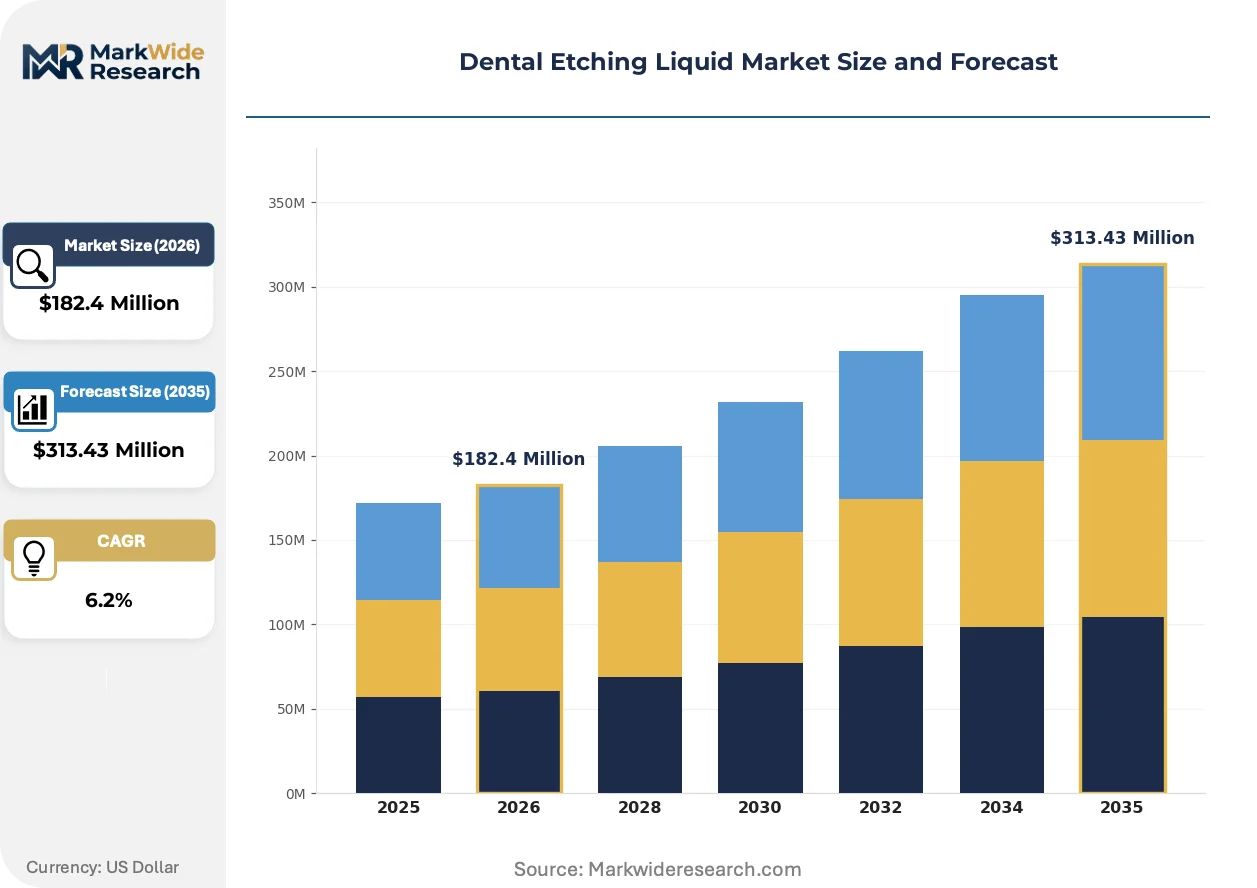
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $313.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphoric Acid, Maleic Acid, Polyacrylic Acid, Citric Acid, Lactic Acid Application: Orthodontics, Prosthodontics, Restorative Dentistry, Preventive Care, Endodontics End User: Dental Clinics, Specialty Dental Hospitals, Dental Laboratories, Academic Institutions Packaging Type: Dropper Bottles, Syringes, Pump Bottles, Single-Use Ampoules, Tube Packs |
| Companies Covered | Ultradent Products, GC Orthodontics, 3M, SDI Limited, Kerr Corporation, Dentsply Sirona, Ivoclar Vivadent, VOCO GmbH, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Etching Liquid Market Strategic Shifts
Etchant delivery systems are fragmenting into application-specific formats as clinicians reject one-size-fits-all viscosity and concentration profiles, while regulatory disclosure requirements intensify scrutiny of formulation chemistry.
Self-etching primer technology is modularizing the traditional etch-rinse-bond sequence into fewer procedural steps. Pediatric and geriatric practices with high patient turnover are adopting these streamlined systems to compress chairtime without sacrificing retention rates. This consolidation is compressing standalone etchant SKUs into bundled adhesive system configurations.
REACH SVHC candidate list expansion is forcing disclosure of residual monomer content and trace metal contaminants in phosphoric acid feedstocks. German and French dental distributors are now requiring extended safety data sheets from suppliers, compressing formulation flexibility for legacy products. Manufacturers are responding with dedicated analytical chemistry capabilities for impurity profiling.
Group purchasing organization consolidation among US dental service organizations is compressing supplier negotiation cycles and unbundling traditional dealer markup structures. Large multi-location practices in Texas and Florida are negotiating direct manufacturer contracts, bypassing regional dental distributors. This channel compression is visible wherever DSO penetration exceeds 30% of local practice volume.
Dental Etching Liquid Market Segmentation
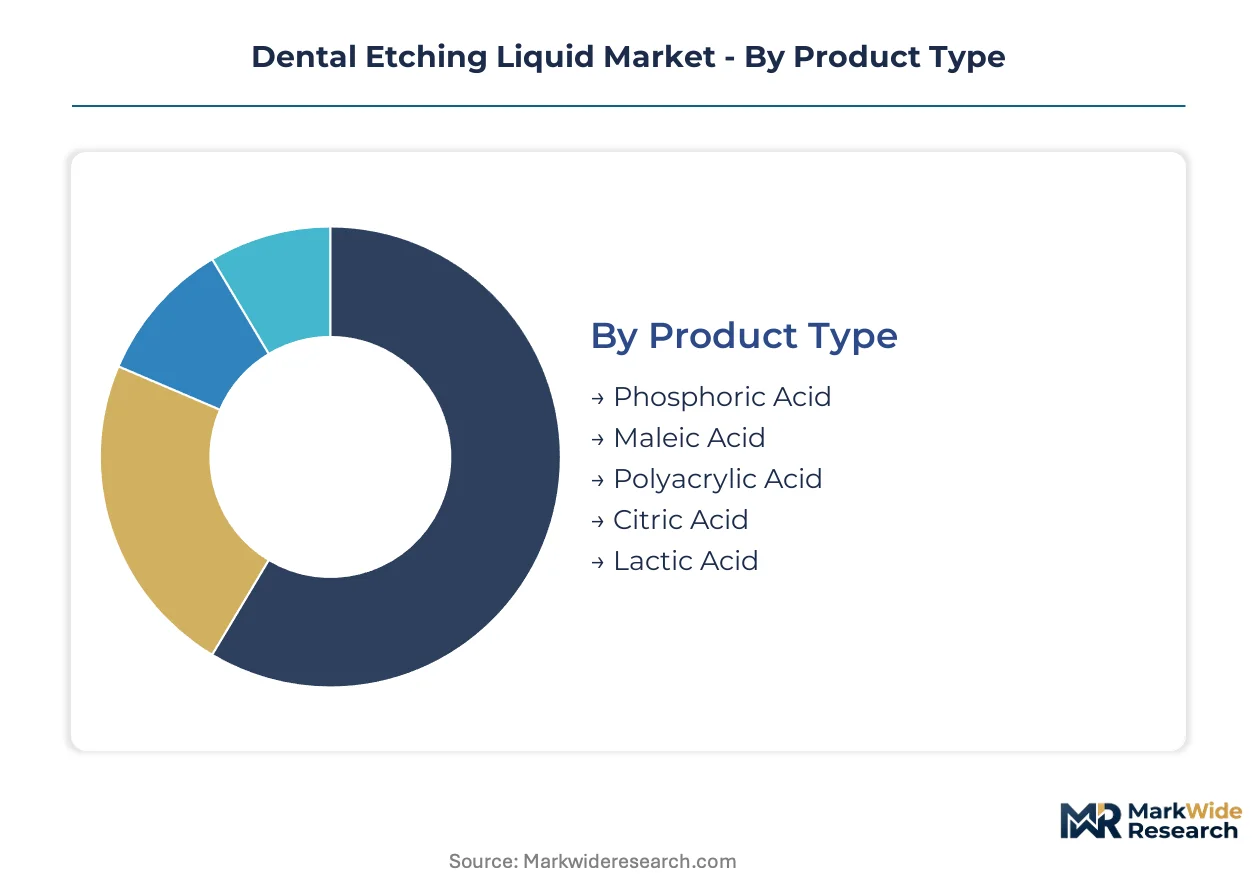
Dental etching liquid segmentation reveals how formulation chemistry, clinical workflow integration, and procurement channel economics create distinct competitive arenas. Manufacturers must align R&D investment with the upgrade cycles driving each category's replacement demand.
Product Type:
Reformulation cycles accelerate as clinicians balance etch depth precision against substrate sensitivity and regulatory disclosure burdens.
- Phosphoric Acid:Standard 35-37% aqueous formulations deliver predictable microporous enamel surfaces through controlled demineralization. Demand concentrates in China and India where resin sealant protocols expand in public health dentistry, constrained by feedstock price volatility from fertilizer industry competition.
- Maleic Acid:Gentler demineralization kinetics suit dentin-sensitive applications and pediatric cases requiring reduced penetration depth. South Korean orthodontic practices favor maleic systems for self-ligating bracket bonding where patient comfort protocols prioritize minimal invasive preparation.
- Polyacrylic Acid:Chelating properties enable selective enamel conditioning without deep substrate erosion.
- Citric Acid:Biodegradable profile aligns with emerging green chemistry procurement criteria in European dental service organizations.
- Lactic Acid:Mild acidity suits provisional restoration protocols and temporary cement conditioning.
Phosphoric acid sits at the top of the volume ranking, with maleic acid climbing the fastest as orthodontic sensitivity protocols proliferate.
Application:
Procedure volume economics reshape procurement patterns across dental specialties with diverging chairtime constraints and reimbursement structures.
- Orthodontics:Bracket bonding and clear aligner attachment protocols consume substantial etchant volumes per patient as treatment plans extend across multiple refinement stages. German and US orthodontic chains negotiate direct manufacturer contracts, bypassing traditional dental distributors.
- Restorative Dentistry:Direct composite restorations and CAD/CAM chairside milling drive demand for etchants optimized across enamel, dentin, and hybrid ceramic substrates. Japanese clinics adopt seventh-generation universal adhesives that compress standalone etchant SKUs into bundled configurations.
- Prosthodontics:Crown and bridge cementation requires controlled etching for resin cement micromechanical retention.
- Preventive Care:School-based sealant programs in India and Indonesia open high-volume, price-sensitive channels.
- Endodontics:Post space preparation and fiber post bonding utilize etchants for resin cement adhesion.
Orthodontics commands the largest procedure volume, with preventive care gaining share fastest as government-funded pediatric programs scale.
End User:
Procurement sophistication varies sharply across practice types, from inventory-light single operators to centralized purchasing at multi-location platforms.
- Dental Clinics:General and specialty practices represent the dominant consumption channel, with group purchasing organization consolidation compressing supplier negotiation cycles. Texas and Florida DSOs with 30%+ local market penetration negotiate direct manufacturer contracts.
- Specialty Dental Hospitals:Academic medical centers and large hospital-based dental departments prioritize ISO 13485-certified suppliers with batch record digitization capabilities.
- Dental Laboratories:Indirect restoration fabrication drives etchant demand for crown and bridge cementation protocols.
- Academic Institutions:Training programs and research centers consume formulation diversity for educational and clinical validation purposes.
Dental clinics absorb the highest absolute volume, while specialty dental hospitals show the steepest expansion trajectory as hospital-based dentistry consolidates.
Packaging Type:
Delivery format selection reflects infection control protocols, waste reduction mandates, and chairside workflow efficiency priorities.
- Syringes:Controlled extrusion and precise placement control dominate orthodontic and restorative applications where adjacent tissue isolation is critical. French and German distributors now require extended safety data sheets covering dye and viscosity modifier constituents.
- Single-Use Ampoules:Eliminate cross-contamination risk and align with single-patient infection control protocols. Indian school-based sealant programs favor unit-dose formats for field deployment logistics.
- Dropper Bottles:Cost-efficient for high-volume practices with established infection control workflows.
- Pump Bottles:Reduce repetitive strain injury risk in high-throughput clinical environments.
- Tube Packs:Compact format suits mobile dentistry and outreach program supply kits.
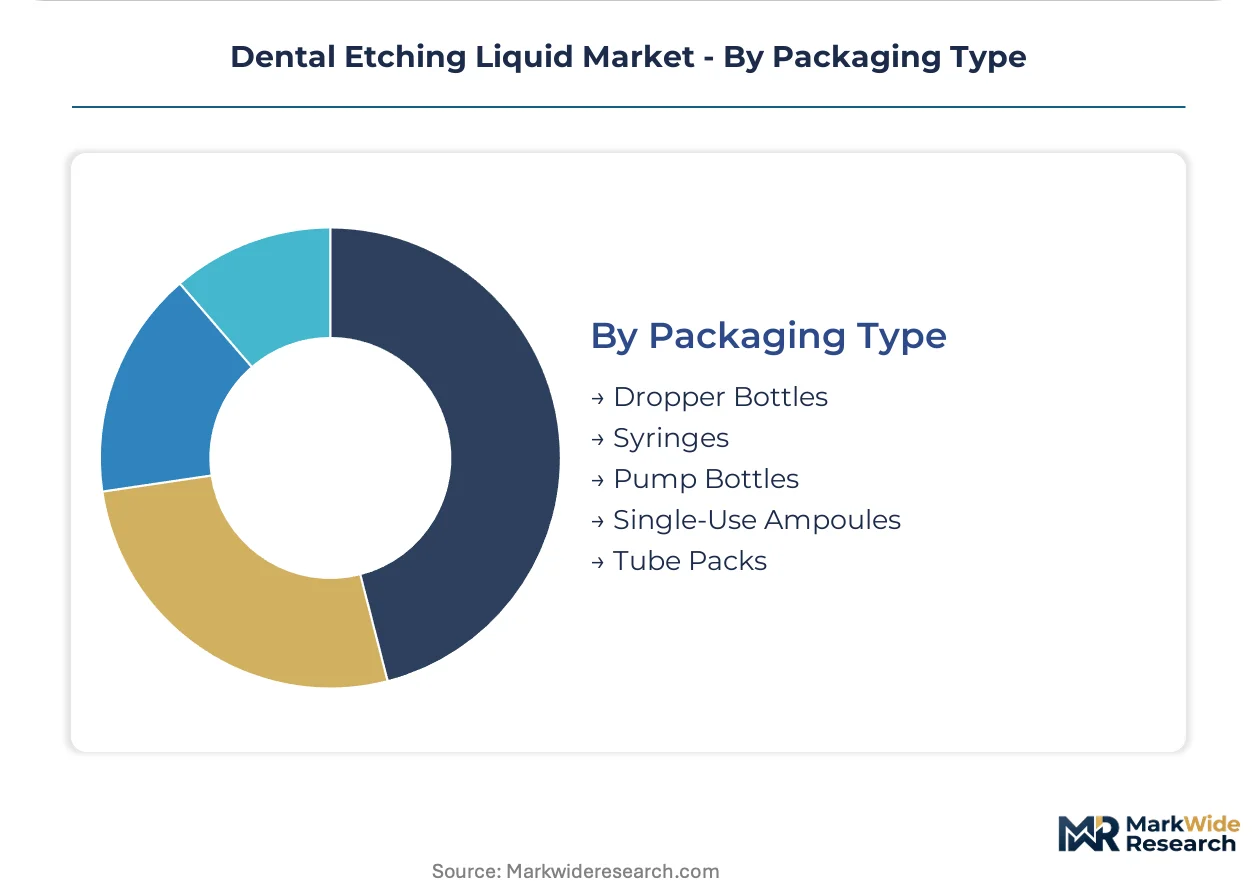
Syringes lead in revenue contribution, with single-use ampoules expanding most quickly as infection control standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta manufacturing corridor anchors dental etching liquid production capacity, with Guangdong province chemical clusters supplying phosphoric acid feedstocks to NMPA-registered formulation facilities serving domestic and export markets.
United States
DSO consolidation in Texas and Florida drives direct manufacturer contracting, bypassing traditional dental distributors where multi-location platforms exceed 30% local market penetration. FDA 510(k) clearance timelines shape product launch sequencing, with Utah-based manufacturing infrastructure sustaining North American supply continuity for phosphoric acid formulations.
Germany
Specialized dental dealer networks anchor European distribution, with REACH SVHC disclosure requirements forcing extended safety data sheets for dye and viscosity modifier constituents. Bavarian chemical houses control high-purity phosphoric acid grades, creating concentrated feedstock sourcing for CE-marked etchant production under EU MDR harmonized standards.
China
NMPA registration pathway streamlining and provincial medical device cluster incentives expand local phosphoric acid formulation capacity for Asia-Pacific supply. Shanghai and Shenzhen manufacturing bases scale output for resin sealant protocols expanding in public health dentistry programs across domestic and export channels.
India
School-based sealant initiatives in Maharashtra and Gujarat open high-volume, price-sensitive procurement channels distinct from private practice purchasing. PLI scheme alignment for medical devices attracts contract manufacturing investment for export-oriented dental chemical production, with Navi Mumbai clusters hosting ISO 13485-certified formulation facilities.
South Korea
Self-ligating bracket bonding protocols in Seoul metropolitan orthodontic practices favor maleic acid systems prioritizing patient comfort through reduced penetration depth. MFDS biocompatibility testing requirements accelerate supplier qualification cycles for domestic manufacturers serving clear aligner attachment etchant demand.
Dental Etching Liquid Market Competitive Environment
Global majors compete with regional champions across formulation chemistry and distribution reach, producing a tiered structure where integrated adhesive system bundling compresses standalone etchant margins. Three strategic archetypes dominate: multinational dental conglomerates with broad portfolio leverage, mid-cap specialists concentrating on application-specific viscosity profiles, and domestic chemical houses exploiting feedstock proximity. Competitive moves center on direct DSO contracting to bypass dealer markups and ISO 13485 certification investment to qualify for tier-one distributor supply.
Within the multinational tier, Dentsply Sirona and Ivoclar Vivadent exemplify divergent bundling strategies, with the former anchoring European distribution networks and the latter extending beyond standalone etchant sales into integrated adhesive ecosystems. Ultradent Products occupies a position among North American manufacturing-centric players leveraging Utah-based infrastructure for supply continuity. These three entities represent the spectrum from distribution-heavy to manufacturing-integrated competitive positioning across phosphoric acid and alternative chemistry segments.
| Leading Market Players |
|---|
| Ultradent Products |
| GC Orthodontics |
| 3M |
| SDI Limited |
| Kerr Corporation |
| Dentsply Sirona |
| Ivoclar Vivadent |
| VOCO GmbH |
| Kuraray Noritake Dental |
| Others |
Value Chain & Pricing Dynamics
REACH SVHC disclosure mandates gate qualified supply and premium-tier pricing access, as German and French distributors now demand extended safety data sheets covering dye and viscosity modifier constituents before contract qualification. This regulatory filter separates ISO 10993-certified suppliers commanding formulation premiums from uncertified competitors confined to price-sensitive procurement channels.
Pricing Analysis
Phosphoric acid feedstock pass-through from fertilizer industry demand fluctuations transmits cost volatility directly into etchant raw material economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and batch record digitization capabilities. Pricing pressure stems from self-etch adhesive substitution compressing standalone etchant SKU volumes. Pediatric preventive programs in India and Indonesia represent the most price-sensitive buyer segment, while German orthodontic chains demonstrate lowest sensitivity due to bundled adhesive system procurement.
Supply Chain Analysis
Container freight rate normalization from Asia-Pacific manufacturing hubs to European and North American distribution centers has reduced landed cost variance for phosphoric acid formulations. Supply concentrates in China, Germany, and India, with Guangdong province chemical clusters and Bavarian specialty chemical houses anchoring high-purity phosphoric acid production. Formulation depends on sulfuric acid derivatives, buffering agents, and REACH-compliant dye inputs. Single-source vulnerability persists as three German and Chinese chemical houses control dental-grade phosphoric acid feedstocks. Distribution runs through specialized dental dealer networks in Europe and direct manufacturer contracts with US dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by the demand-shift toward seventh-generation universal adhesives that privilege suppliers with integrated formulation ecosystems over standalone etchant specialists.
For Market Incumbents: Acquire ISO 13485-certified formulation facilities in India to capture PLI scheme benefits and export-oriented production capacity. Consolidate around direct DSO contracting in Texas and Florida to bypass dealer markups where multi-location platforms exceed 30% local penetration. Defensive moves must address self-etch adhesive substitution threatening standalone etchant volumes through bundled system displacement. For New Entrants and Emerging Players: Launch via school-based sealant program tenders in Maharashtra and Gujarat, exploiting high-volume, price-sensitive channels distinct from entrenched private practice procurement. Target maleic acid formulations for South Korean orthodontic practices prioritizing patient comfort protocols. White-space exists in citric acid biodegradable profiles for European dental service organizations adopting green chemistry procurement criteria. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialists with application-specific viscosity capabilities because DSO consolidation compresses supplier ecosystems and rewards scale. Long-term viability hinges on adhesive system bundling integration rather than standalone etchant positioning. Acquisition target archetype: ISO 13485-certified regional formulators with NMPA or MFDS registration pathways. Watch MFDS biocompatibility testing requirement acceleration as inflection indicator for supplier qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR harmonization accelerates cross-border distribution for notified body-qualified suppliers. |
| Backward Integration into Feedstock | Captive phosphoric acid supply insulates margin pressure from fertilizer industry demand cycles. |
| Pediatric Program Partnership | School-based sealant initiatives in India and Indonesia open high-volume procurement channels. |
| Digital Workflow Integration | CAD/CAM-optimized etchants capture hybrid ceramic substrate demand from chairside milling adoption. |
| DSO Direct Contracting | Bypassing dealer markups in Texas and Florida improves net pricing for multi-location platforms. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade flow databases, and primary stakeholder interviews — were reconciled to construct demand estimates. Conversations with dental product procurement managers, GPO contracts specialists, biomedical engineers at academic medical centers, and formulation chemists at NMPA-registered facilities informed volume assumptions. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registers, NMPA medical device approval records, and phosphoric acid trade statistics. Bottom-up procedure volume modeling and top-down chemical consumption estimates were triangulated to constrain forecast variance.
Historical consumption patterns were cross-referenced against panel input from distribution channel partners to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include acid chemistry type, application specialty, end-user procurement sophistication, and packaging format preference. CAGRs were derived from procedure volume elasticity analysis and adhesive protocol substitution rate modeling. Forecast inputs incorporated orthodontic treatment plan extension trends and school-based sealant program expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphoric acid feedstock price spikes or accelerated self-etch adhesive adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Digital Facebow Market
Dental Devices
Dental Needle Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental Crown Removal Market