
 Dental Units Market | 2026-2036
Dental Units Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Units Market Analysis
Market Context
Dental equipment distribution through dealer networks is rewriting how manufacturers reach chairside installations. Dentsply Sirona leverages direct sales teams to control pricing and service attachment across major metropolitan markets. Planmeca anchors Nordic and Baltic markets through exclusive distributor partnerships that limit competitive access. A-dec sustains premium positioning by specializing in custom-configured delivery systems for high-volume group practices.
Technical Definition and Segments
A dental unit integrates a patient chair, instrument delivery system, oral evacuation, and operating light into a single electromechanical workstation typically rated for continuous duty cycles exceeding ten years. Operatory units dominate installed base value while portable units represent the fastest-growing product category as mobile dentistry expands into underserved communities. Digital imaging technology commands premium margins within the technology segment, whereas pneumatic systems retain cost-sensitive share in emerging markets. Dental clinics absorb the majority of end-user demand, though academic institutions drive specification standards that cascade into private practice procurement.
Regulatory Frame
The FDA regulates dental units as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence for powered instrumentation. ISO 7494 sets dimensional and performance baselines for dental unit waterlines and patient safety interfaces. Stakeholders must monitor evolving MDR technical documentation requirements and state-level dental board infection control mandates that increasingly specify waterline testing protocols as a condition of licensure.
Market Dynamics
Digital operatory integration is compressing replacement cycles as chairside CAD/CAM and imaging convergence forces capital redeployment toward connected workstation ecosystems.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for powered dental equipment reduces commercialization timelines. Device manufacturers leverage this to introduce electromechanical upgrades faster than full PMA routes permit.
- Mobile dentistry expansion:Portable unit demand concentrates in federally qualified health centers serving rural catchment areas. These deployments address access gaps while creating secondary equipment markets.
- Reimbursement-aligned capital investment:German statutory health insurance framework rewards dental infrastructure modernization. Practice groups exploit depreciation schedules to accelerate fleet upgrades.
Market Restraints
- Stainless steel and copper input volatility:Electromechanical chassis fabrication depends on metal commodity markets. Foundry capacity concentration in East Asian supplier networks amplifies price transmission lag.
- EU MDR technical documentation burden:Enhanced clinical evidence requirements for powered instrumentation strain smaller manufacturers. Notified body bottlenecks extend recertification timelines beyond historical baselines.
- Extended duty cycle expectations:Ten-year rated lifespans for operatory units suppress replacement frequency. Capital durability becomes a competitive disadvantage for equipment vendors.
Strategic Opportunities
- Underserved Indian dental infrastructure:Per-capita dentist ratios in tier-2 and tier-3 cities lag metropolitan benchmarks. Modular unit configurations address power reliability and space constraints in these expansion markets.
- AI-assisted diagnostic convergence:Chairside radiography integration with machine learning algorithms creates premium positioning. Early adopters in Japanese university hospitals are establishing procurement precedents.
- Subscription-based service attachment:Predictive maintenance and waterline compliance monitoring convert capital sales into recurring revenue. United States group practices demonstrate willingness to unbundle service contracts from hardware.
Industry Challenges
- Biomedical equipment technician scarcity:Electromechanical servicing competence lags installation growth. Training pipelines for pneumatic-digital hybrid systems remain underdeveloped across dealer networks.
- Legacy waterline integration complexity:Retrofit digital monitoring into existing ISO 7494-compliant installations demands custom engineering. Field service teams face elongated commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Units Market |
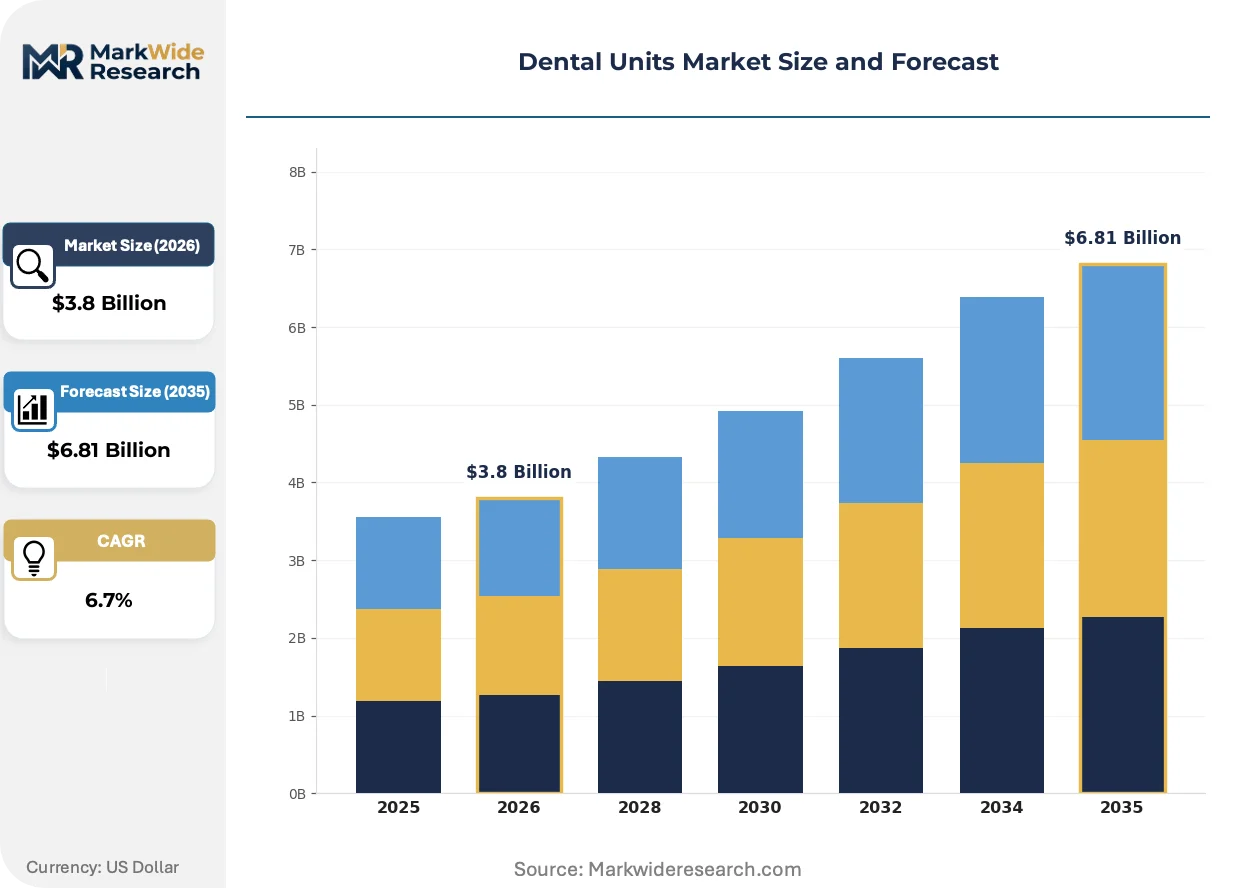
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operatory Units, Surgical Units, Portable Units, Mobile Units Technology: Digital Imaging, Electric Motors, Pneumatic Systems, LED Lighting End User: Dental Clinics, Hospitals, Laboratories, Academic Institutions Supply Channel: Direct Sales, Dealers, Online Retailers, Distributors |
| Companies Covered | Planmeca, Morita, Dentsply Sirona, Gnatus, Midmark, A-dec, KaVo, Fedesa, Belmont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Units Market Emerging Trajectories
Chairside digital workflow convergence is fragmenting the traditional equipment-vendor relationship as interoperability demands force open-architecture commitments from historically proprietary systems.
Intraoral scanner integration with mill-and-sinter chairside units is hybridizing the restorative workflow. High-volume group practices in Texas and Florida are standardizing on same-day crown delivery. This compression of lab-dependent turnaround is eroding the standalone laboratory equipment market while elevating operatory footprint requirements.
EU MDR Article 10 post-market surveillance mandates now require systematic clinical follow-up for powered dental handpieces. Manufacturers must maintain vigilance databases that track device performance across installed bases. German and French dental schools are driving specification standards that cascade into private practice procurement through graduate training preferences.
Buying committees at United States dental service organizations now unbundle equipment specification from dealer relationships. Direct manufacturer engagement for imaging and CAD/CAM components displaces traditional full-line distributor loyalty. This disintermediation concentrates in California and New York metropolitan markets where DSO consolidation is most advanced.
Dental Units Market Segmentation
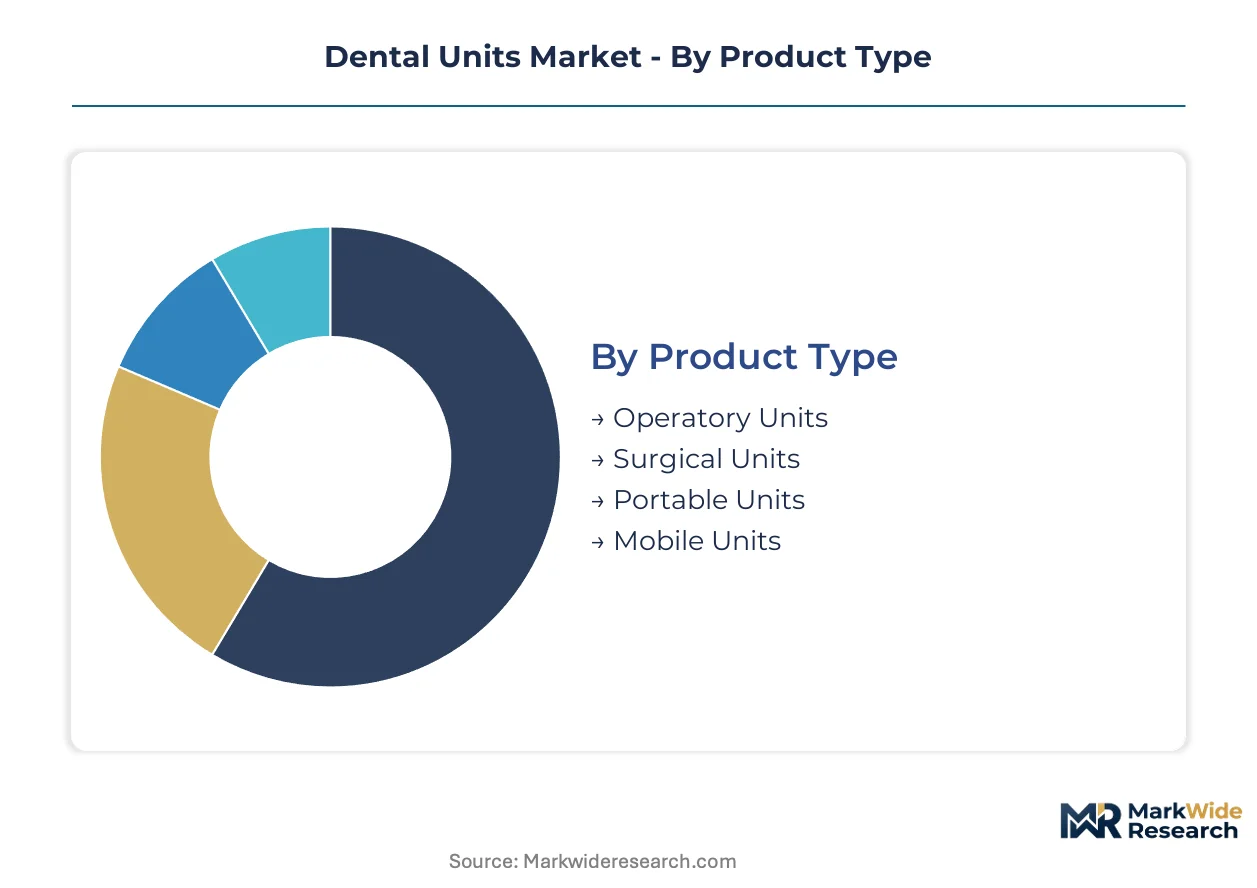
Dental unit procurement patterns diverge sharply across clinical settings and technology tiers. Equipment specification standards cascade from academic medical centers into private practice purchasing decisions.
Product Type:
Cost tier stratification separates capital-intensive fixed installations from mobility-optimized configurations.
- Operatory Units:These electromechanical workstations integrate patient positioning, instrument delivery, and evacuation systems into permanent clinical infrastructure. German statutory health insurance depreciation schedules accelerate fleet replacement in high-volume group practices.
- Portable Units:Compact configurations with independent power and water reservoirs enable deployment in non-traditional settings. Federally qualified health centers in rural United States catchment areas drive procurement for mobile dentistry programs addressing access gaps.
- Surgical Units:Specialized configurations support implantology and oral surgery with enhanced suction capacity and specialized instrument mounts.
- Mobile Units:Self-contained systems mounted on wheeled chassis serve outreach programs and temporary clinical setups.
Operatory units command the established base. The steepest expansion runs through portable units.
Technology:
Application requirements determine technology stack selection, with diagnostic convergence favoring digital integration.
- Digital Imaging:Chairside radiography and intraoral scanning modules embed directly into unit architecture. Japanese university hospitals establish procurement precedents for AI-assisted diagnostic convergence.
- Electric Motors:Brushless DC drive systems deliver precise torque control for restorative and endodontic procedures.
- Pneumatic Systems:Compressed air turbine handpiece drives retain cost-sensitive share in emerging markets with unreliable electrical infrastructure.
- LED Lighting:Solid-state operatory illumination reduces heat emission and extends service intervals versus halogen alternatives.
Digital imaging claims premium positioning. Pneumatic systems maintain volume footholds in price-sensitive procurement.
End User:
Customer type dictates specification complexity and service attachment expectations.
- Dental Clinics:Private and group practices generate the majority of installed base demand. United States dental service organizations now unbundle equipment specification from traditional dealer relationships.
- Hospitals:Integrated health systems require enterprise-grade interoperability with electronic medical records and centralized sterilization workflows.
- Laboratories:Standalone prosthetic facilities purchase secondary units for technician training and quality verification.
- Academic Institutions:Dental schools drive specification standards that cascade into private practice procurement through graduate training preferences.
Dental clinics absorb dominant volume. Academic institutions exert disproportionate influence on specification trajectories.
Supply Channel:
Geography and customer scale determine channel selection, with direct engagement displacing traditional distribution in consolidated markets.
- Direct Sales:Manufacturer-controlled teams serve metropolitan markets with complex configuration requirements. California and New York dental service organization consolidation accelerates disintermediation.
- Dealers:Full-line distributors retain loyalty in fragmented markets requiring localized service response.
- Distributors:Exclusive territorial partnerships anchor Nordic and Baltic market access for selected manufacturers.
- Online Retailers:E-commerce channels concentrate in consumables and replacement components rather than capital equipment.
Dealers retain established relationships. Direct sales channels are expanding most quickly in consolidated metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European dental equipment distribution into Central and Eastern European catchment areas. Japanese manufacturing clusters around Nagoya supply precision electromechanical components to assembly plants worldwide. Dubai's Jebel Ali Free Zone serves as a re-export hub for Middle Eastern and African markets.
United States
Federally qualified health centers in rural Texas and Florida drive portable unit procurement for mobile dentistry expansion. The FDA's 510(k) clearance pathway accelerates commercialization timelines for powered dental equipment. California dental service organizations in Los Angeles and San Francisco metropolitan areas unbundle equipment specification from traditional dealer relationships.
Germany
Statutory health insurance depreciation schedules reward dental infrastructure modernization in high-volume group practices. The EU Medical Device Regulation mandates enhanced clinical evidence for powered instrumentation through notified body certification. Manufacturing concentration in Baden-Württemberg and Bavaria supplies precision electromechanical systems to European and export markets.
Japan
University hospitals in Tokyo and Osaka establish procurement precedents for AI-assisted diagnostic convergence with chairside systems. The Pharmaceuticals and Medical Devices Agency oversees Class II medical device registration with streamlined review for electromechanical dental equipment. Industrial clusters in Aichi Prefecture around Nagoya manufacture brushless DC drive systems and precision handpiece components.
India
Tier-2 and tier-3 cities across Maharashtra and Gujarat present infrastructure gaps that modular unit configurations address. The Central Drugs Standard Control Organization regulates medical device import and manufacturing licensing with phased implementation of quality management system requirements. Dental equipment distribution concentrates in Mumbai and Ahmedabad dealer networks serving expanding private clinic penetration.
Brazil
Private dental clinic chains in São Paulo and Rio de Janeiro drive replacement demand for operatory units with digital imaging integration. The National Health Surveillance Agency oversees medical device registration with convergence toward international harmonization standards. São Paulo state manufacturing assembles pneumatic systems for cost-sensitive domestic and Latin American markets.
Dental Units Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision electromechanical subassemblies. Market structure consolidates around full-line manufacturers with integrated service networks while fragmenting across regional specialists serving price-sensitive procurement. Three archetypes dominate: premium custom-configured delivery system specialists, scale-driven portable unit fabricators, and precision component suppliers. Competitive moves concentrate on exclusive distributor partnerships for territorial anchoring and predictive maintenance service unbundling to capture recurring revenue.
Among Nordic and Baltic market specialists, Planmeca occupies a position exemplifying exclusive distributor partnership strategies. German-origin precision manufacturers including KaVo and Dentsply Sirona represent the platform integrator archetype with direct sales team deployment in metropolitan markets. These entities anchor the premium tier through control of pricing and service attachment rather than component supply relationships.
| Leading Market Players |
|---|
| Planmeca |
| Morita |
| Dentsply Sirona |
| Gnatus |
| Midmark |
| A-dec |
| KaVo |
| Fedesa |
| Belmont |
| Others |
Supply Flow & Price Mechanics
Nagoya's precision manufacturing clusters feed brushless DC motor and handpiece component production that underpins premium-tier pricing power for integrated system vendors. Stainless steel and copper commodity volatility transmits directly into electromechanical chassis costs, compressing margins for fabricators without captive foundry relationships or long-term metal offtake contracts.
Pricing Analysis
Volume-discount tiering separates dental service organization fleet procurement from single-practice spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 7494 certification grade and after-sales service bundling intensity. Cost compression in pneumatic system tiers is intensifying because Brazilian and Indian domestic assemblers compete on stripped-down configurations. Federally qualified health centers in rural United States catchment areas demonstrate highest price sensitivity, while Japanese university hospitals show lowest sensitivity due to research grant funding flexibility.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese and Indian foundry networks, while precision electromechanical components source from Japanese and German industrial clusters. Brushless DC drives, LED illumination modules, and intraoral scanning sensors rest on semiconductor supply chains concentrated in Taiwan and South Korea. Single-source vulnerability for rare-earth magnet materials in motor assemblies presents structural risk. Distribution runs through exclusive territorial dealer partnerships in fragmented markets and direct sales teams in metropolitan dental service organization consolidation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The widening gap between electromechanical servicing competence and installation growth rates constrains market expansion. Biomedical equipment technician training pipelines for pneumatic-digital hybrid systems remain underdeveloped, creating a binding bottleneck across dealer service networks.
For Market Incumbents: Build switching-cost moats through predictive maintenance subscription unbundling that converts capital sales into recurring revenue streams. Deepen backward integration into brushless DC motor production to insulate margin structures from East Asian component price transmission. Defend against disintermediation threat by embedding software companion development for chairside CAD/CAM interoperability.
For New Entrants and Emerging Players: Build out modular unit configurations targeting tier-2 and tier-3 Indian cities where power reliability and space constraints exclude premium operatory installations. Mobile dentistry programs at federally qualified health centers present the most penetrable demand segment. Pursue exclusive distributor partnerships in Nordic and Baltic markets where territorial anchoring limits competitive access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision component suppliers with captive electromechanical subassembly capabilities over pure-play system integrators. Long-term viability hinges on AI-assisted diagnostic convergence integration depth. Target acquisition archetypes include brushless DC drive specialists and waterline compliance monitoring software developers. Watch FDA 510(k) clearance velocity for powered handpiece innovations as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Converts Dentsply Sirona and KaVo capital sales into recurring revenue across United States group practices. |
| Brushless DC Motor Backward Integration | Reduces dependency on Nagoya-area precision component suppliers for electromechanical drive systems. |
| AI Diagnostic Software Companion Development | Captures Japanese university hospital procurement precedents for chairside radiography integration. |
| Exclusive Distributor Partnership Expansion | Replicates Planmeca's Nordic territorial anchoring model in Baltic and Central European catchment areas. |
| Modular Unit Configuration for Emerging Markets | Addresses power reliability gaps in Maharashtra and Gujarat tier-2 city clinic penetrations. |
Methodological Framework
Cross-validation between primary interviews with dental equipment procurement managers and secondary validation through FDA 510(k) clearance databases anchors the qualitative findings. Stakeholder input drew from biomedical equipment technicians, dental school curriculum directors, GPO contracts managers, and dealer network service heads. Secondary sources encompassed ISO 7494 technical documentation, EU MDR notified body certification records, and hospital procurement database extracts. Bottom-up unit installation tracking and top-down capital expenditure flow analysis provided triangulation across market sizing approaches.
Calibration against historical replacement cycle patterns and depreciation schedule exploitation rates shaped the analytical framework. Segmentation dimensions spanned product type, technology stack, end-user category, and supply channel configuration across the projection horizon. CAGRs derived from installed base evolution modeling and fleet upgrade intensity correlations. Forecast inputs incorporated metal commodity price trajectory assumptions and EU MDR recertification timeline elasticity.
Stress conditions across stainless steel input costs, notified body bottlenecks, and dental service organization consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions regarding reimbursement framework stability and infection control mandate stringency evolution. Cross-checking against CMS Medicare dental expenditure benchmarks and German statutory health insurance capital investment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
China Dental Devices Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental 3D Printing Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Global Dental Burs Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Splints Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
3D Printed Clear Dental Aligners Market