
 Brazil Bunker Fuel Market | 2026-2036
Brazil Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Bunker Fuel Market Insights
Physical bunker supply chains in Brazilian ports is fragmenting as new entrants challenge legacy distributors. Petrobras leverages its refinery network and coastal storage to sustain volume leadership at Santos and Rio de Janeiro. Monjasa Holding A/S competes through floating storage and barge operations that bypass congested terminal queues. Raízen differentiates via its ethanol-blending expertise and biofuel pilot programs targeting coastal shipping.
Bunker fuel denotes heavy residual oil and marine distillates burned in vessel main engines and auxiliary power units, with sulfur content capped at 0.50% mass under IMO 2020 unless scrubber-equipped. HSFO retains structural dominance among scrubber-fitted bulk carriers calling Brazilian iron ore terminals, while LSFO commands premium pricing from container lines seeking operational simplicity. MGO consumption is accelerating among offshore platform supply vessels operating under Petrobras charter due to stricter local emissions enforcement.
ANVISA and the country's national environmental regulator enforce port-level sulfur testing protocols that shape product acceptance criteria. MARPOL Annex VI implementation through Brazilian maritime authorities drives scrubber adoption versus low-sulfur fuel switching economics. Stakeholders must monitor biofuel blending mandate proposals and carbon intensity indicator adjustments that will redefine bunker procurement strategies.
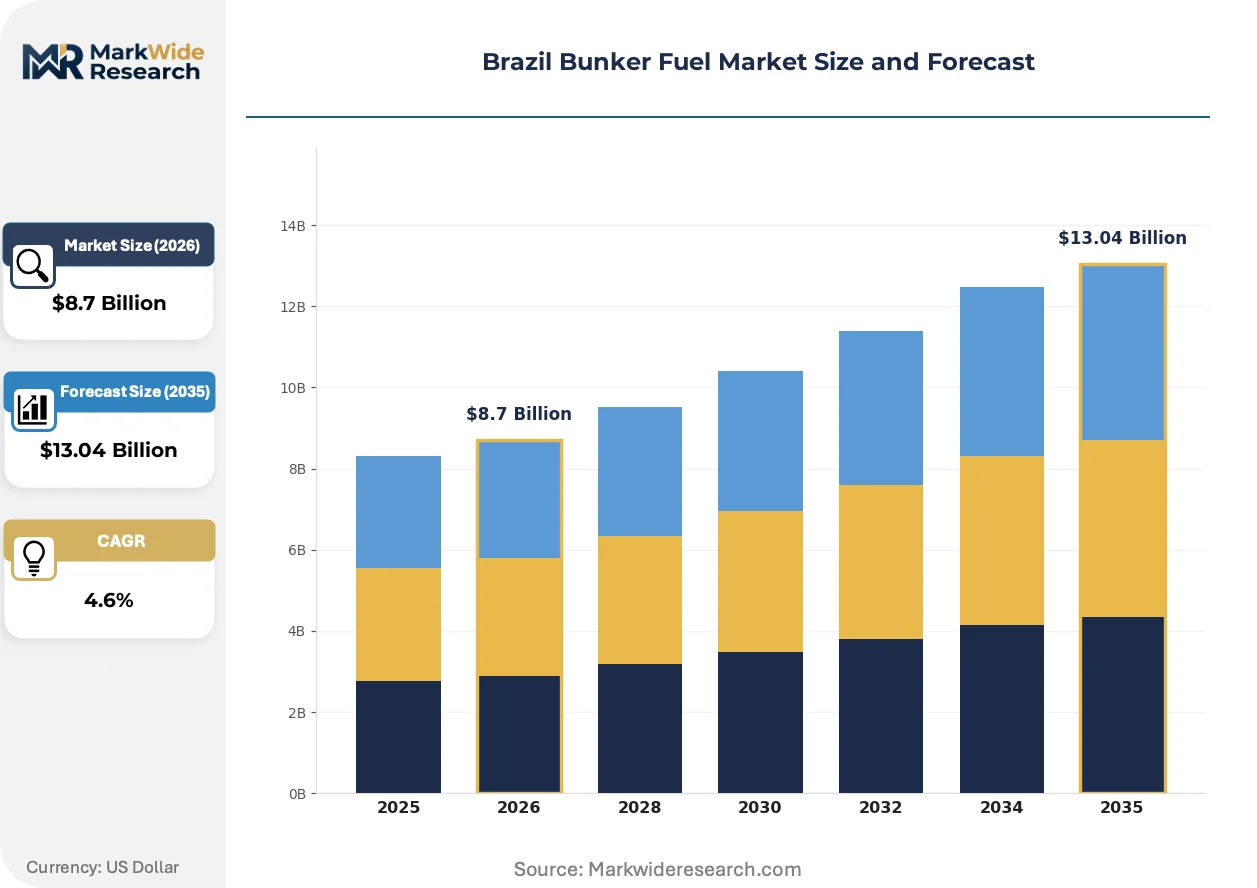
Market Dynamics
IMO 2020 sulfur caps have permanently restructured Brazilian bunker procurement, splitting demand between scrubber-equipped bulk carriers and distillate-dependent container fleets while ANVISA testing protocols add compliance friction at Santos and Rio de Janeiro.
Growth Catalysts
- Deep-sea container expansion:Mediterranean Shipping Company and Maersk have added weekly Brazilian port calls, driving LSFO demand at Santos terminal complexes. Terminal operators are expanding storage to match vessel size escalation.
- Offshore platform electrification:Petrobras charter requirements now mandate MGO for platform supply vessels operating within 12 nautical miles of coastal production facilities. ANVISA emissions enforcement has accelerated this fuel switch since 2021.
- Biofuel blending mandates:Proposed legislation from Brazil's national biofuel regulator would require 10% renewable content in coastal marine fuels by 2028, positioning Raízen's ethanol infrastructure for supply chain capture.
Market Restraints
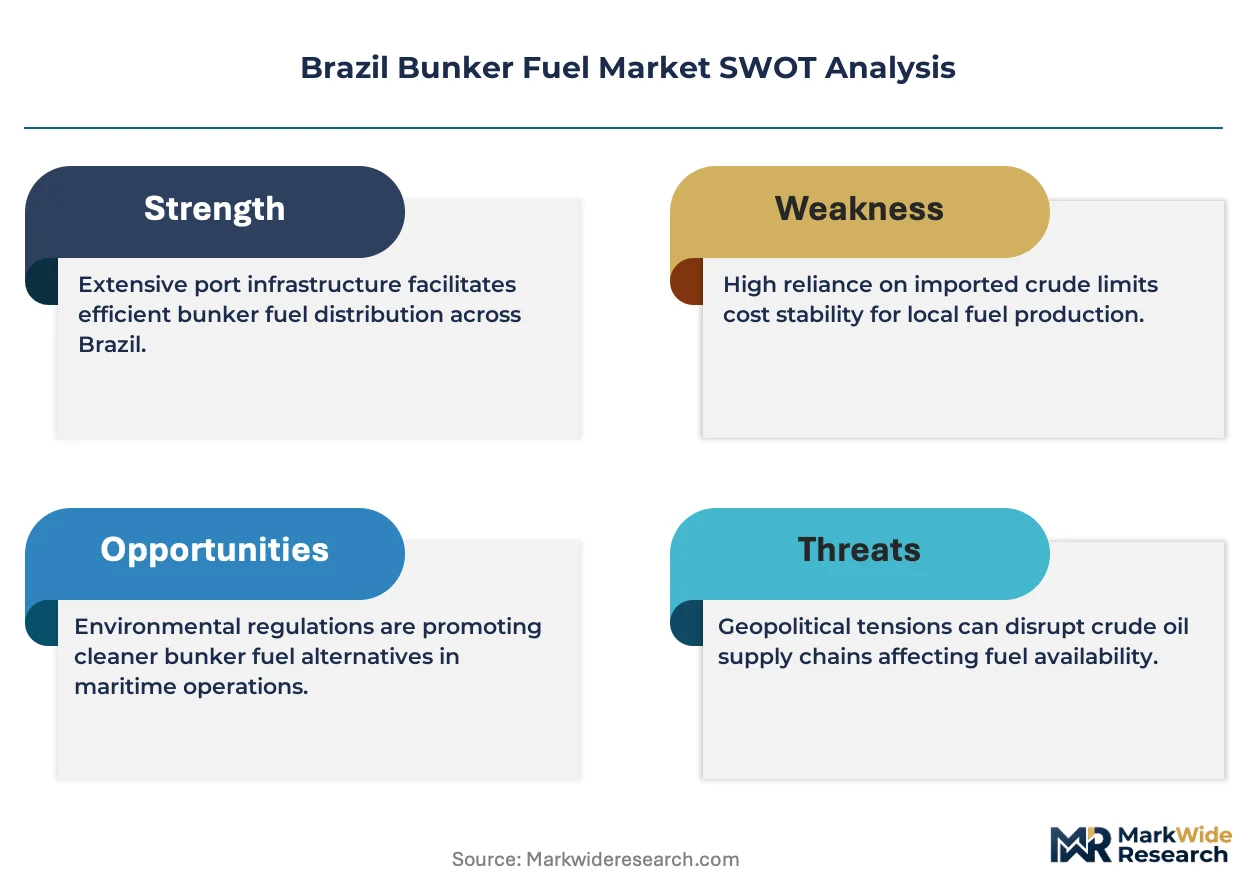
- Refinery concentration:Petrobras controls 85% of domestic residual fuel production, creating single-source dependency for HSFO at iron ore terminals. Any operational disruption at Paulínia or Presidente Bernardes refineries immediately tightens Santos availability.
- Import cost volatility:Brazilian bunker pricing tracks Singapore 380 CST differentials plus dollar-real exchange exposure, compressing distributor margins when currency swings exceed 8% monthly.
- Scrubber capex recovery:Capesize bulk carriers require 18-24 month payback periods for exhaust gas cleaning systems, delaying fleet-wide adoption despite HSFO's $80-120 per ton discount to LSFO.
Strategic Opportunities
- Pará state corridor:Vale's iron ore expansion at Ponta da Madeira terminal creates unserved HSFO demand as scrubber-fitted capesize tonnage rises. No floating storage currently operates north of Salvador.
- Digital bunkering platforms:Blockchain-based mass flow meter verification and automated BDN issuance are digitizing transaction workflows, reducing dispute resolution from weeks to hours.
- Methanol pilot pathways:MAN Energy Solutions and Wärtsilä engine retrofits enable dual-fuel methanol operation, positioning Santos for green methanol import infrastructure if European carbon border adjustments extend to maritime.
Industry Challenges
- Marine chemist certification backlog:ANVISA-accredited laboratories face 6-8 week testing queues for sulfur content verification, delaying cargo discharge at Rio de Janeiro and Itajaí when spot checks trigger disputes.
- Barge fleet modernization:Brazilian coastal bunker barges average 22 years of age, requiring $40-60 million in replacement investment to meet IBAMA spill containment standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Bunker Fuel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: HSFO, LSFO, MGO, ULSFO End User: Shipping Companies, Ports, Offshore Platforms, Industrial Operators Distribution Channel: Bunkering Services, Retail Outlets, Direct Supply, Bulk Suppliers Compliance Standard: IMO 2020, MARPOL Annex VI, Local Regulations, Environmental Standards |
| Companies Covered | Bunker Holding A/S, Monjasa Holding A/S, World Fuel Services Corp, AP Moeller Maersk A/S, Peninsula Petroleum Ltd, Petrobras, Ipiranga, Raízen, Vibra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Bunker Fuel Market Trends and Innovations
Digital infrastructure and regulatory stringency are converging to compress transaction friction and accelerate fuel quality verification across Brazilian port complexes.
Mass flow meter (MFM) technology is digitizing bunker delivery measurement by replacing manual sounding and temperature correction with continuous coriolis-based mass calculation. Container lines at Santos now require MFM-equipped barges as a chartering precondition, with Mediterranean Shipping Company and Hapag-Lloyd leading adoption. This compression of measurement uncertainty is digitizing dispute resolution and accelerating payment settlement cycles from 30 days to 72 hours.
ANVISA's 2023 update to Portaria 482 tightened sulfur testing protocols from 0.50% to 0.48% maximum with mandatory third-party laboratory verification. The industrial consequence is a 15% increase in rejected bunker lots at Rio de Janeiro, forcing distributors to maintain dual product streams. Container segments are responding by contracting directly with international traders holding ISO 8217:2017 certification, bypassing legacy Brazilian distributors lacking accredited testing partnerships.
Charterers are consolidating procurement through integrated supply agreements that bundle fuel, lubricants, and technical services under single-vendor frameworks. This consolidation is displacing spot-market purchasing at São Paulo state industrial corridors, where Cargill and Bunge now contract 18-month bunker commitments with fixed-price collars. The shift is most visible among grain exporters at Santos, where operational simplicity outweighs spot-market savings amid volatile LSFO differentials.
Brazil Bunker Fuel Market Segmentation
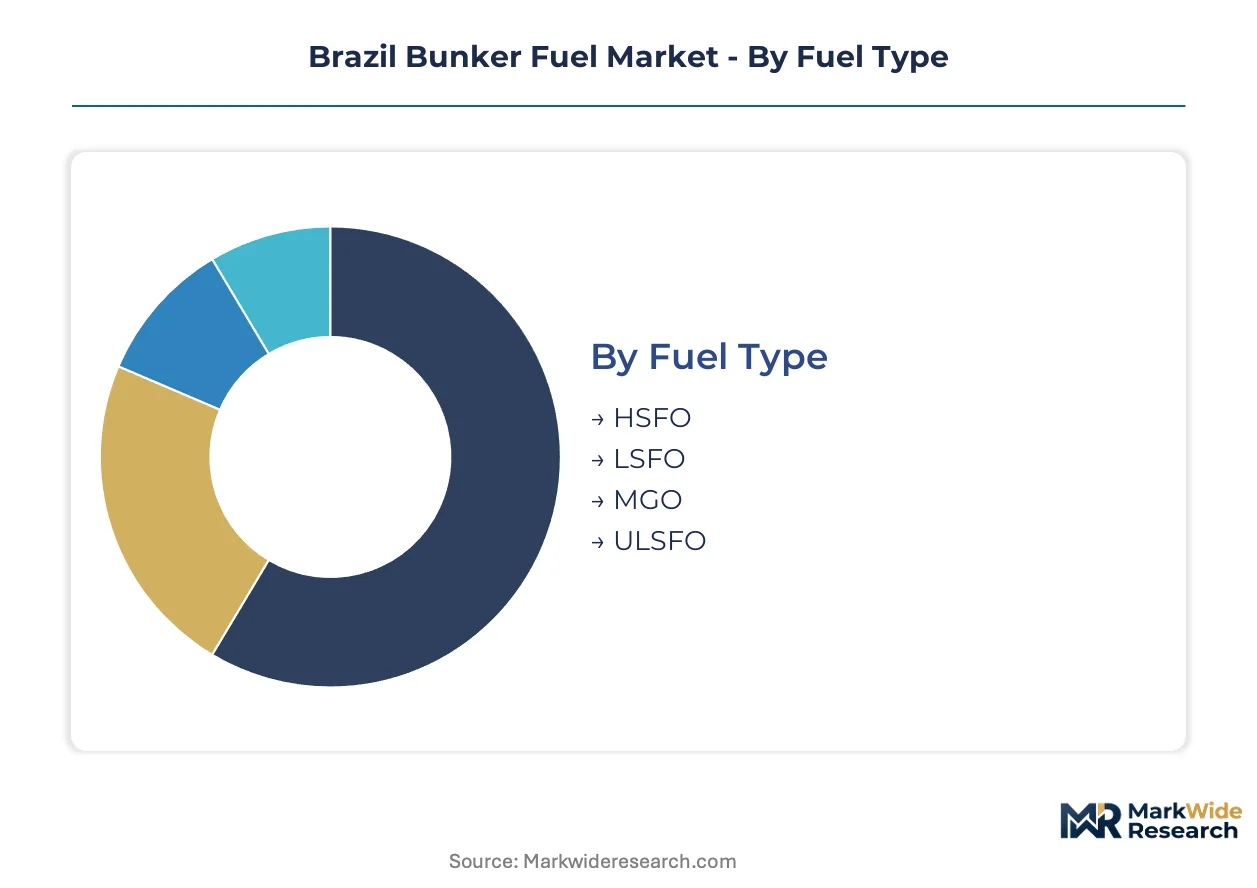
Brazilian bunker procurement splits across fuel specifications, vessel types, and compliance pathways that reshape supplier economics at Santos and Rio de Janeiro. Understanding these segment boundaries clarifies where Petrobras retains pricing power versus where traders and biofuel entrants can capture share.
Fuel Type:
Vessel engine configurations and scrubber investments create distinct demand tiers across the Brazilian coast.
- HSFO:High-sulfur fuel oil remains the dominant specification for scrubber-fitted bulk carriers calling Vale's iron ore terminals at Ponta da Madeira and Itaqui. The $80-120 per ton discount to LSFO sustains demand despite upfront scrubber capital requirements.
- LSFO:Low-sulfur fuel oil commands premium positioning among container lines seeking operational simplicity at Santos terminal complexes. Mediterranean Shipping Company and Maersk have standardized LSFO procurement for their expanded Brazilian port calls.
- MGO:Marine gas oil consumption is accelerating among offshore platform supply vessels operating under Petrobras charter within 12 nautical miles of coastal production facilities. ANVISA emissions enforcement since 2021 has mandated this fuel switch.
- ULSFO:Ultra-low-sulfur fuel oil serves specialized coastal shipping routes facing the strictest local emissions protocols. Limited availability at Brazilian ports constrains segment expansion.
The dominant share belongs to HSFO, while LSFO is closing the gap fastest.
End User:
Customer scale and chartering structure determine procurement sophistication and contract duration.
- Shipping Companies:Deep-sea container lines and bulk operators drive volume concentration at Santos and Rio de Janeiro. Integrated supply agreements now displace spot purchasing as Cargill and Bunge lock in 18-month bunker commitments with fixed-price collars.
- Ports:Terminal operators at Santos, Paranaguá, and Itajaí function as both demand aggregators and storage landlords. Their infrastructure investments in expanded tank capacity directly enable vessel size escalation.
- Offshore Platforms:Petrobras charter requirements mandate MGO for platform supply vessels, creating a captive demand segment with limited supplier competition.
- Industrial Operators:São Paulo state industrial corridors generate residual demand from captive power generation and process heating applications.
Shipping companies hold the volume base, though offshore platforms deliver the steadiest contract terms.
Distribution Channel:
Physical delivery infrastructure separates incumbent networks from challenger models.
- Bunkering Services:Specialized barge operations at Santos and Rio de Janeiro handle the majority of vessel refueling. Monjasa Holding A/S competes through floating storage that bypasses congested terminal queues.
- Retail Outlets:Coastal fuel stations serve smaller craft and fishing fleets with limited storage requirements.
- Direct Supply:Large industrial consumers and grain exporters contract directly with international traders holding ISO 8217:2017 certification, bypassing legacy Brazilian distributors lacking accredited testing partnerships.
- Bulk Suppliers:Petrobras leverages its refinery network and coastal storage to sustain volume leadership, with Paulínia and Presidente Bernardes refineries supplying 85% of domestic residual fuel production.
Bunkering services anchor coastal delivery, but direct supply is expanding most quickly among container segments.
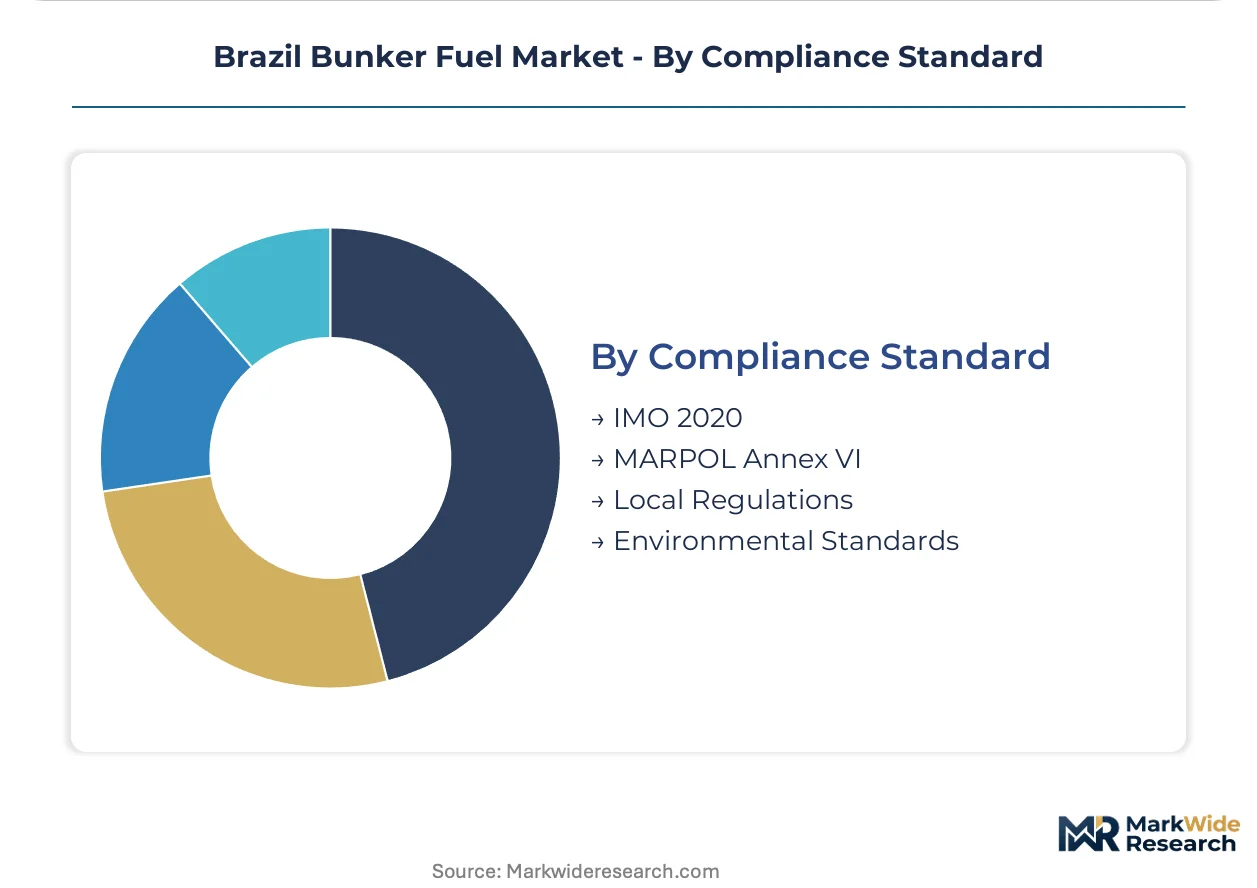
Compliance Standard:
Regulatory layering creates product acceptance criteria that filter supplier participation.
- IMO 2020:The 0.50% sulfur mass cap permanently restructured Brazilian bunker procurement, splitting demand between scrubber-equipped bulk carriers and distillate-dependent container fleets.
- MARPOL Annex VI:Implementation through Brazilian maritime authorities drives scrubber adoption versus low-sulfur fuel switching economics across the national fleet.
- Local Regulations:ANVISA and IBAMA enforce port-level sulfur testing protocols and spill containment standards that shape barge fleet modernization requirements.
- Environmental Standards:Proposed biofuel blending mandates from Brazil's national biofuel regulator would require 10% renewable content in coastal marine fuels by 2028.
IMO 2020 defines the baseline, yet local regulations impose the operational friction that determines supplier viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA anchors regulatory enforcement across Brazilian port complexes, with sulfur testing protocols tightening procurement standards at Santos and Rio de Janeiro terminals.
São Paulo
Santos port cluster drives LSFO demand as Mediterranean Shipping Company and Maersk expand weekly calls. ANVISA's 2023 Portaria 482 update mandates third-party laboratory verification for all bunker deliveries. Terminal operators are expanding storage capacity to match vessel size escalation at the São Paulo state industrial corridor.
Rio de Janeiro
Petrobras charter requirements mandate MGO for platform supply vessels within 12 nautical miles of coastal production facilities. IBAMA spill containment standards are forcing barge fleet modernization investments. The Rio de Janeiro terminal complex faces 6-8 week testing queues at ANVISA-accredited laboratories.
Pará
Vale's iron ore expansion at Ponta da Madeira terminal creates unserved HSFO demand among scrubber-fitted capesize tonnage. No floating storage currently operates north of Salvador. The Pará state corridor represents the largest geographic gap in Brazilian bunker infrastructure.
Minas Gerais
Paulínia and Presidente Bernardes refineries supply 85% of domestic residual fuel production, creating single-source dependency for HSFO. Any operational disruption immediately tightens Santos availability. The Minas Gerais refinery network sustains Petrobras volume leadership through coastal storage assets.
Brazil Bunker Fuel Market Competitive Landscape
State-affiliated energy majors and independent bunker traders split the market through divergent infrastructure strategies. Petrobras leverages captive refinery output and coastal storage terminals to sustain volume leadership at Santos and Rio de Janeiro. International traders compete through floating storage and barge operations that bypass congested terminal queues. The dominant competitive moves involve refinery network optimization versus third-party logistics partnerships.
Within the state-affiliated tier, Petrobras anchors supply security through its Paulínia and Presidente Bernardes refinery complex. Among independent traders, Monjasa Holding A/S and Bunker Holding A/S exemplify the floating storage archetype, occupying positions that bypass legacy terminal congestion. Raízen sits within the biofuel integration vector, representing ethanol-blending capabilities that align with proposed renewable content mandates.
| Leading Market Players |
|---|
| Bunker Holding A/S |
| Monjasa Holding A/S |
| World Fuel Services Corp |
| AP Moeller Maersk A/S |
| Peninsula Petroleum Ltd |
| Petrobras |
| Ipiranga |
| Raízen |
| Vibra |
| Others |
Pricing and Supply Chain Analysis
Single-source refinery dependency at Petrobras's Paulínia and Presidente Bernardes complex determines both the HSFO-LSFO price spread and the coastal storage network's radial structure. ANVISA's sulfur testing protocols add compliance friction that widens tier differentials at Santos and Rio de Janeiro terminals.
Pricing Analysis
The customization-premium spread separates ISO 8217:2017-certified international traders from legacy Brazilian distributors lacking accredited laboratory partnerships. Price differentiation rests on certification grade and volume scale, with container lines contracting 18-month fixed-price collars while bulk carriers spot-purchase HSFO. Cost compression in the LSFO tier is intensifying as Mediterranean Shipping Company and Maersk consolidate procurement through integrated supply agreements. Grain exporters at Santos show lowest price sensitivity, prioritizing operational simplicity over spot-market savings.
Supply Chain Analysis
Contract-manufacturing concentration at Petrobras's Minas Gerais refineries supplies 85% of domestic residual fuel production. Geographic supply concentration centers on Brazil's coastal storage terminals, with Singapore 380 CST differentials feeding import-dependent distributors. Raw material dependencies include heavy residual oil feedstocks, marine distillates, and ethanol blending components. Single-source vulnerability at Paulínia or Presidente Bernardes immediately tightens Santos availability. Distribution runs through specialized barge operations and direct supply agreements with international traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IMO 2020 compliance costs and ANVISA's tightening sulfur protocols are accelerating procurement consolidation among container lines and scrubber adoption among bulk carriers.
For Market Incumbents: Pre-empt biofuel blending mandates by capturing Raízen's ethanol infrastructure for supply chain integration. Defend position at Santos through floating storage investments that bypass terminal congestion, and secure ANVISA-accredited laboratory partnerships before container lines complete their shift to ISO-certified traders. For New Entrants and Emerging Players: Pursue the Pará state corridor where Vale's iron ore expansion at Ponta da Madeira terminal creates unserved HSFO demand among scrubber-fitted capesize tonnage. Target digital bunkering platforms with blockchain-based mass flow meter verification to compress dispute resolution cycles from weeks to hours. For Investors and Strategic Acquirers: ANVISA's 2023 Portaria 482 update reshapes the acquisition landscape by elevating testing infrastructure to strategic priority. Long-term viability favors distributors with accredited laboratory partnerships and floating storage assets over legacy terminal-dependent operators. Monitor biofuel blending mandate proposals from Brazil's national biofuel regulator as the signal for supply chain capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Storage Deployment | Monjasa Holding A/S bypasses Santos terminal congestion through barge-based supply. |
| ANVISA Laboratory Accreditation | Third-party verification partnerships become table stakes for container line contracts. |
| Biofuel Blending Infrastructure | Raízen's ethanol capabilities align with proposed 10% renewable content mandates. |
| Digital Bunkering Platform | Blockchain-based mass flow meter verification compresses payment cycles to 72 hours. |
| Scrubber-Equipped Fleet Investment | Capesize operators capture $80-120 per ton HSFO discount at iron ore terminals. |
Research Methodology
Desk research of customs trade data, ANVISA regulatory filings, and Petrobras operational disclosures preceded structured interviews with bunker procurement managers at container lines, terminal operators at Santos and Rio de Janeiro, and fuel supply specialists at offshore platform contractors. Primary fieldwork with barge fleet operators and refinery logistics coordinators combined with secondary validation from maritime fuel quality databases and port authority storage capacity reports. Bottom-up volume estimates triangulated against top-down market sizing from coastal vessel call data.
The analytical framework held exchange rate volatility and refinery utilization rates as fixed assumptions across the modeling period, while varying biofuel mandate scenarios and scrubber adoption curves. Segmentation dimensions modeled include fuel specification tier, vessel type, distribution channel, and compliance pathway. CAGRs derived from trend extrapolation of vessel size escalation and terminal storage expansion, with inputs from dollar-real exchange exposure and Singapore 380 CST differential movements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by international traders with ISO certification or biofuel-integrated distributors would shift outcomes beyond projected ranges. Quarterly review of ANVISA testing queue lengths, refinery operational disruptions, and container line procurement consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Biobutanol Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Mobile Fuel Delivery Market
Fuels
South America Aviation Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
Gasoline As a Fuel Market
Fuels
Europe Gas Market
Fuels
India Bunker Fuel Market
Fuels
Europe Black and Wood Pellets Market
Fuels
South Africa Bunker Fuel Market
Fuels
Bunker Fuel Market
Fuels
Wood Charcoal Market
Fuels
Gas Feed System Market
Fuels
Renewable Heating Fuels Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Bituminous Coal Market