
 Biobutanol Market | 2026-2036
Biobutanol Market Size, Share, and Industry Trends Forecast 2026-2036
Biobutanol Market Intelligence
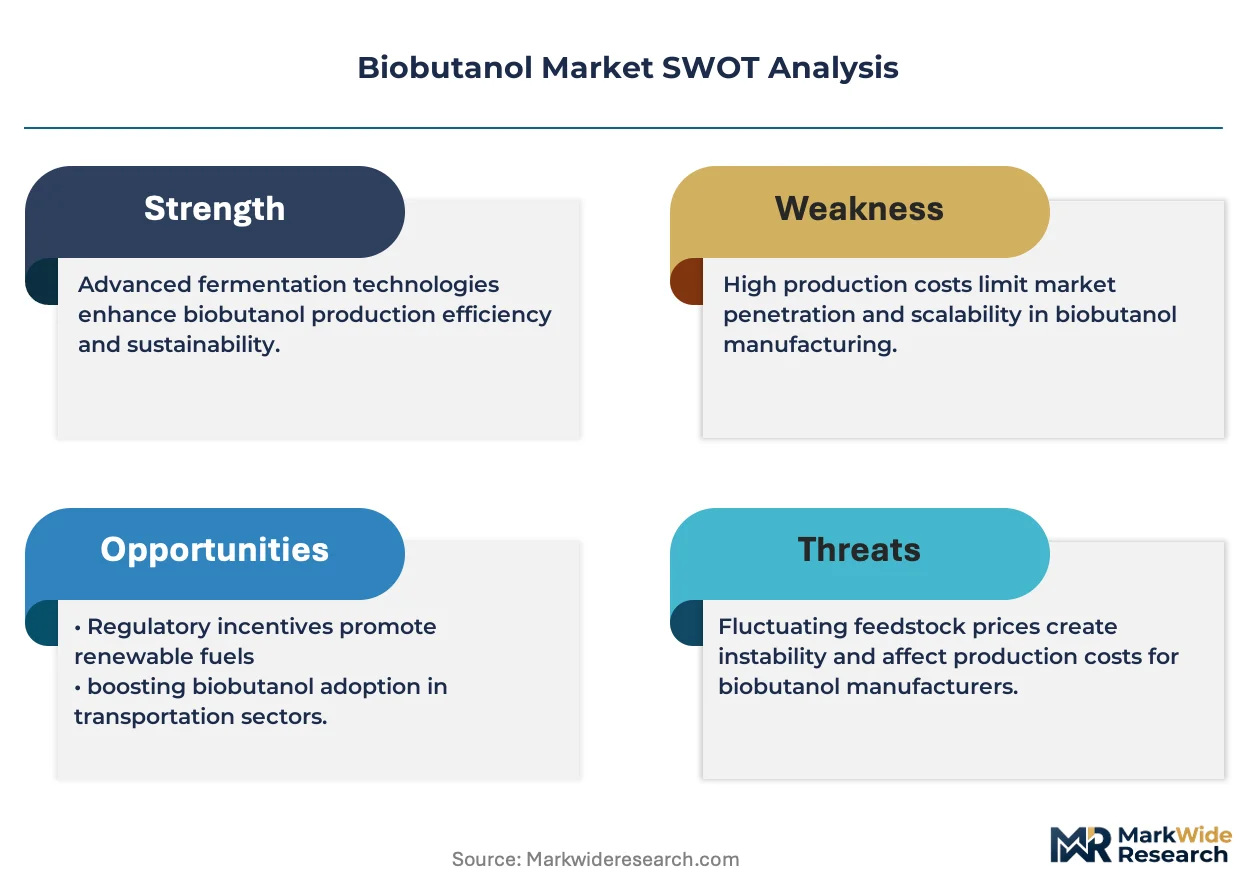
Specialized fermentation engineering talent is rotating toward lignocellulosic biorefinery projects, tightening the labor pool for conventional ethanol operations. Gevo, Inc. anchors its position through backward integration into corn feedstock supply and proprietary yeast strain development. Butamax Advanced Biofuels LLC leverages DuPont's industrial bioscience heritage to dominate patent-protected isobutanol pathways. BASF SE extends its chemical manufacturing scale into biobased butanol derivatives for coatings and solvents.
Biobutanol is a four-carbon alcohol produced primarily via microbial fermentation of sugars or starches, yielding a higher energy density than ethanol with lower vapor pressure and superior blending characteristics for gasoline applications. Its primary commercial purpose centers on fuel additive markets where it enhances octane ratings while reducing emissions, alongside solvent and chemical intermediate roles in industrial formulations. The fuel additive application leads current volume absorption as refiners seek drop-in compatibility with existing pipeline infrastructure. Fermentation technology occupies the dominant process position, though catalytic process routes from syngas are gaining R&D investment for feedstock flexibility. Chemical intermediate demand sustains margin pools in pharmaceutical and cosmetics end-user segments where purity specifications command premium pricing.
The U.S. EPA renewable fuel standard and California Air Resources Board LCFS program shape domestic demand thresholds and credit economics for biobutanol producers seeking fuel market access. REACH registration requirements in Europe and China's GB standards for fuel alcohols impose compositional testing burdens that favor producers with integrated analytical capabilities. Stakeholders must monitor feedstock cost divergence between corn, sugarcane bagasse, and woody biomass as cellulosic technology maturation determines which process routes achieve commercial breakeven.
Market Dynamics
Cellulosic feedstock technology maturation is redirecting capital away from first-generation corn-based fermentation, compressing project timelines and reshaping supplier qualification criteria across automotive OEM fuel additive supply chains.
Growth Catalysts
- California LCFS Credit Mechanisms:California Air Resources Board's Low Carbon Fuel Standard generates tradable credits that improve project economics for cellulosic biobutanol producers targeting West Coast refiners.
- Fuel Additive Demand:Automotive OEMs require higher-octane blending components compatible with existing pipeline infrastructure, positioning biobutanol as a drop-in ethanol alternative.
- Brazilian Sugarcane Belt Concentration:Bagasse-to-butanol projects in São Paulo and Minas Gerais leverage existing ethanol distillation infrastructure and established logistics networks.
Market Restraints
- Feedstock Cost Divergence:Corn price volatility in the U.S. Midwest creates margin compression for first-generation producers lacking cellulosic technology access.
- REACH Registration Burdens:European Chemicals Agency compositional testing requirements favor integrated analytical capabilities, raising barriers for smaller fermentation operators.
- Petrochemical Butanol Substitution:Fossil-derived n-butanol from propylene oxidation maintains cost advantages in solvent and coatings applications.
Strategic Opportunities
- Aviation Fuel Pathways:C12 isobutanol dimerization for sustainable aviation fuel opens access to airline offtake agreements under CORSIA eligibility frameworks.
- Pharmaceutical-Grade Purity:Chemical intermediate demand for pharmaceutical and cosmetics formulations commands premium pricing above fuel-grade specifications.
- U.S. EPA Renewable Volume Obligations:Cellulosic waiver credit price dynamics create arbitrage windows for advanced biofuel producers with RIN generation capability.
Industry Challenges
- Fermentation Engineering Talent Scarcity:Specialized microbiologists and process engineers are rotating toward lignocellulosic biorefinery projects, tightening labor availability for conventional ethanol operations.
- Capex Intensity of Cellulosic Pretreatment:Enzymatic hydrolysis equipment and biomass handling systems require substantial upfront investment before achieving commercial yield targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobutanol Market |
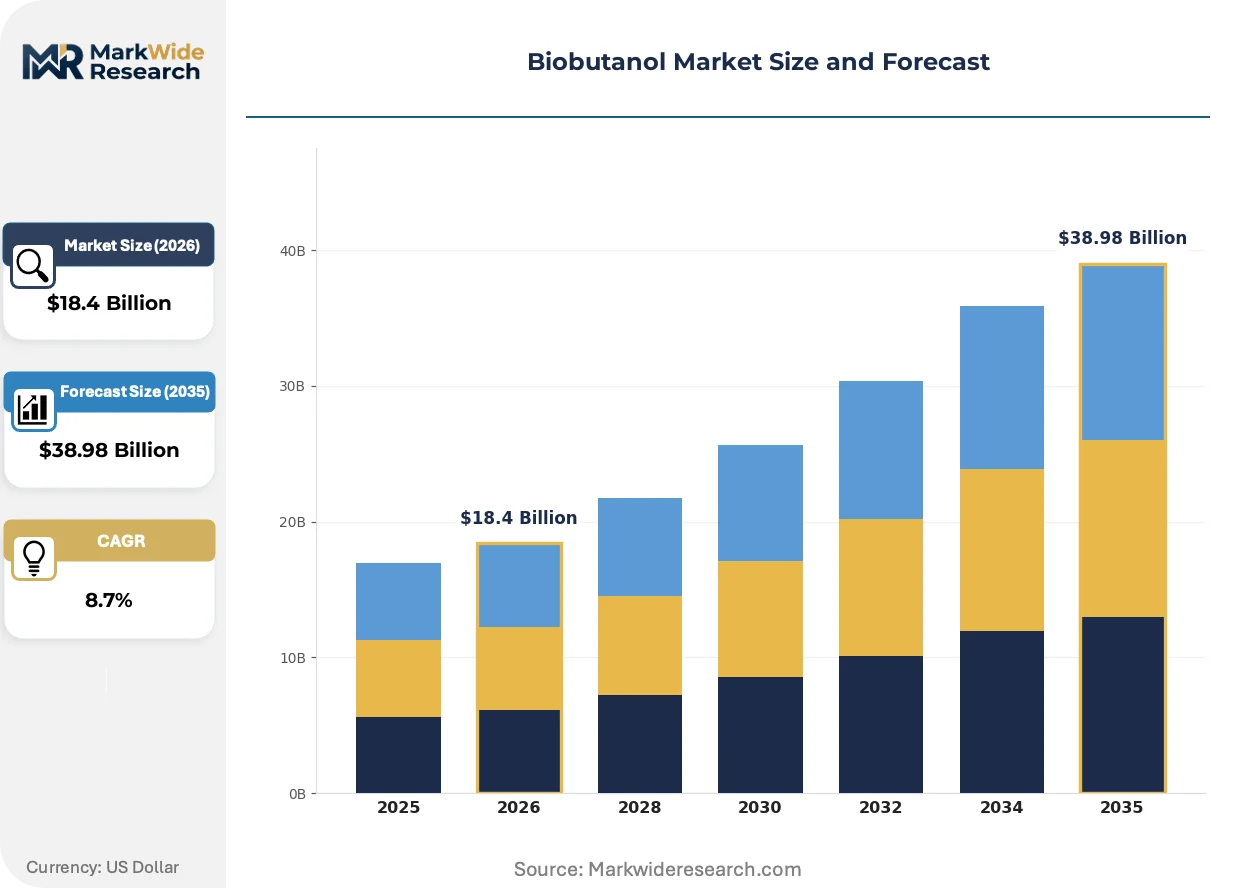
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butanol 1, Butanol 2, Butanol 3, Butanol 4 Application: Solvent, Fuel Additive, Chemical Intermediate, Feedstock End User: Automotive, Chemical Manufacturing, Pharmaceutical, Cosmetics Technology: Fermentation, Catalytic Process, Extraction, Distillation |
| Companies Covered | Cathay Industrial Biotech Ltd, Abengoa, Gevo, Inc., Butamax Advanced Biofuels LLC, GranBio, BASF SE, Eastman Chemical Company, DuPont Industrial Biosciences, Green Biologics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobutanol Market Strategic Shifts & Innovations
Continuous fermentation systems and consolidated bioprocessing are compressing unit capital costs while synthetic biology advances enable engineered yeast strains with higher butanol tolerance and selectivity.
Consolidated bioprocessing using single-organism systems that simultaneously break down cellulose and ferment sugars is supplanting separate hydrolysis and fermentation steps. Refiners in the U.S. Gulf Coast are piloting these integrated configurations to reduce enzyme loading costs. The technology is enabling smaller-scale distributed biorefineries closer to feedstock sources, reducing biomass transportation economics.
REACH registration requirements under the European Chemicals Agency are tightening compositional disclosure standards for fuel alcohols imported into EU member states. Producers must document impurity profiles and biodegradation pathways to maintain market access. German and Dutch chemical distributors are demanding integrated analytical capabilities from supply partners, compressing the qualified supplier base.
Refinery procurement teams are consolidating qualified biobutanol suppliers into multi-year offtake agreements with indexed pricing tied to corn futures and RIN values. Direct contracting between fuel producers and biorefinery operators is replacing merchant market spot purchases in the U.S. Midwest. This concentration is most visible among Ohio and Indiana refiners seeking supply security for summer gasoline blending season.
Biobutanol Market Segmentation
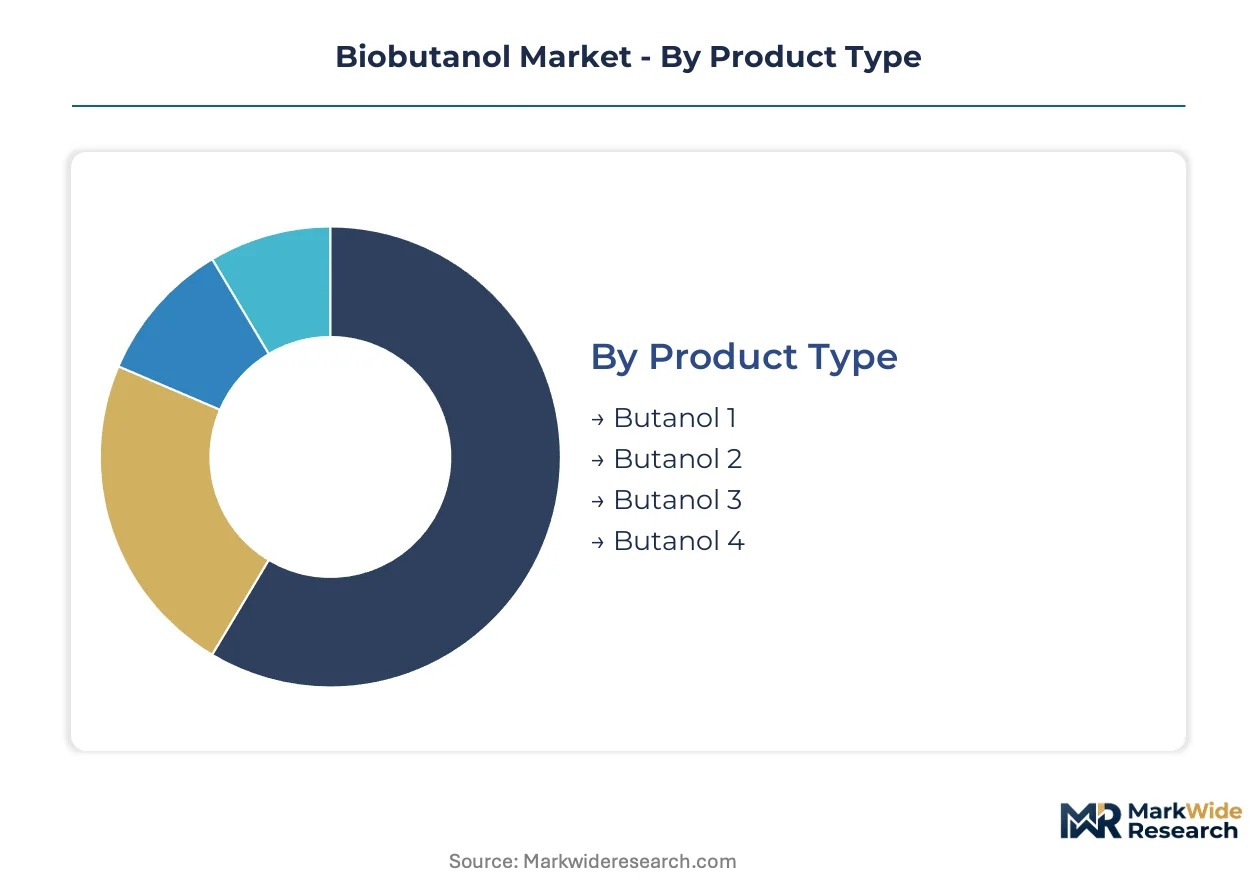
Biobutanol's commercial pathways diverge sharply across product grades and end-use specifications. Channel economics favor fuel additive volumes through refinery procurement, while pharmaceutical and solvent applications command premium pricing through specialized chemical distributors.
Product Type:
Refinery procurement teams source n-butanol and isobutanol grades through distinct supply contracts indexed to different feedstock baskets. Chemical distributors handle specialty grades under tighter purity specifications.
- Butanol 1:Normal butanol (n-butanol) serves as the primary solvent-grade product with established petrochemical competition. Coatings manufacturers in Germany and the Netherlands absorb volumes through BASF SE's integrated supply chains, though cellulosic producers struggle to match fossil-derived cost positions.
- Butanol 2:Isobutanol enables higher-octane fuel blending with superior vapor pressure characteristics versus ethanol. California refiners under CARB LCFS obligations source this grade for West Coast gasoline pools, leveraging RIN generation and credit stacking to improve project returns.
- Butanol 3:Secondary butanol grades target chemical intermediate applications with moderate purity requirements.
- Butanol 4:Specialty butanol variants serve niche pharmaceutical and cosmetics formulations demanding exacting impurity profiles.
By volume, Butanol 1 leads through solvent market penetration. By growth pace, Butanol 2 is expanding most quickly via fuel additive adoption.
Application:
Margin pools stratify across applications based on specification stringency and regulatory credit eligibility. Fuel markets scale through volume, while pharmaceutical and chemical intermediate segments sustain pricing power.
- Solvent:Industrial coatings and adhesives formulations absorb the largest volume share, with petrochemical n-butanol maintaining cost advantages. REACH registration burdens under ECHA favor integrated producers with captive analytical capabilities.
- Fuel Additive:Drop-in gasoline blending compatibility drives refinery procurement, particularly among Ohio and Indiana operators seeking summer gasoline supply security. EPA renewable volume obligations and RIN price dynamics shape sourcing decisions.
- Chemical Intermediate:Butyl acrylate and glycol ether derivatives command intermediate pricing tiers through established petrochemical supply chains.
- Feedstock:Biobased feedstock applications for downstream chemical synthesis remain emergent, constrained by cellulosic technology maturation timelines.
Solvent applications anchor current revenue. Fuel additive volumes are climbing the fastest on LCFS credit mechanics and RIN arbitrage windows.
End User:
Customer concentration patterns reflect divergent procurement sophistication, with automotive OEMs and chemical manufacturers driving standardization while pharmaceutical and cosmetics buyers enforce purity premiums.
- Automotive:OEM fuel system compatibility testing and refinery blending operations dominate volume absorption. Brazilian sugarcane belt projects target this segment through existing ethanol logistics infrastructure.
- Chemical Manufacturing:Butyl acetate and plasticizer producers sustain steady demand through established merchant market relationships.
- Pharmaceutical:USP-grade specifications and impurity documentation requirements compress the qualified supplier base to integrated fermentation operators with GMP capabilities.
- Cosmetics:Natural-derived positioning and preservative applications command modest volumes at elevated pricing tiers.
Chemical Manufacturing leads by volume throughput. Pharmaceutical demand is gaining share fastest on purity premium expansion.
Technology:
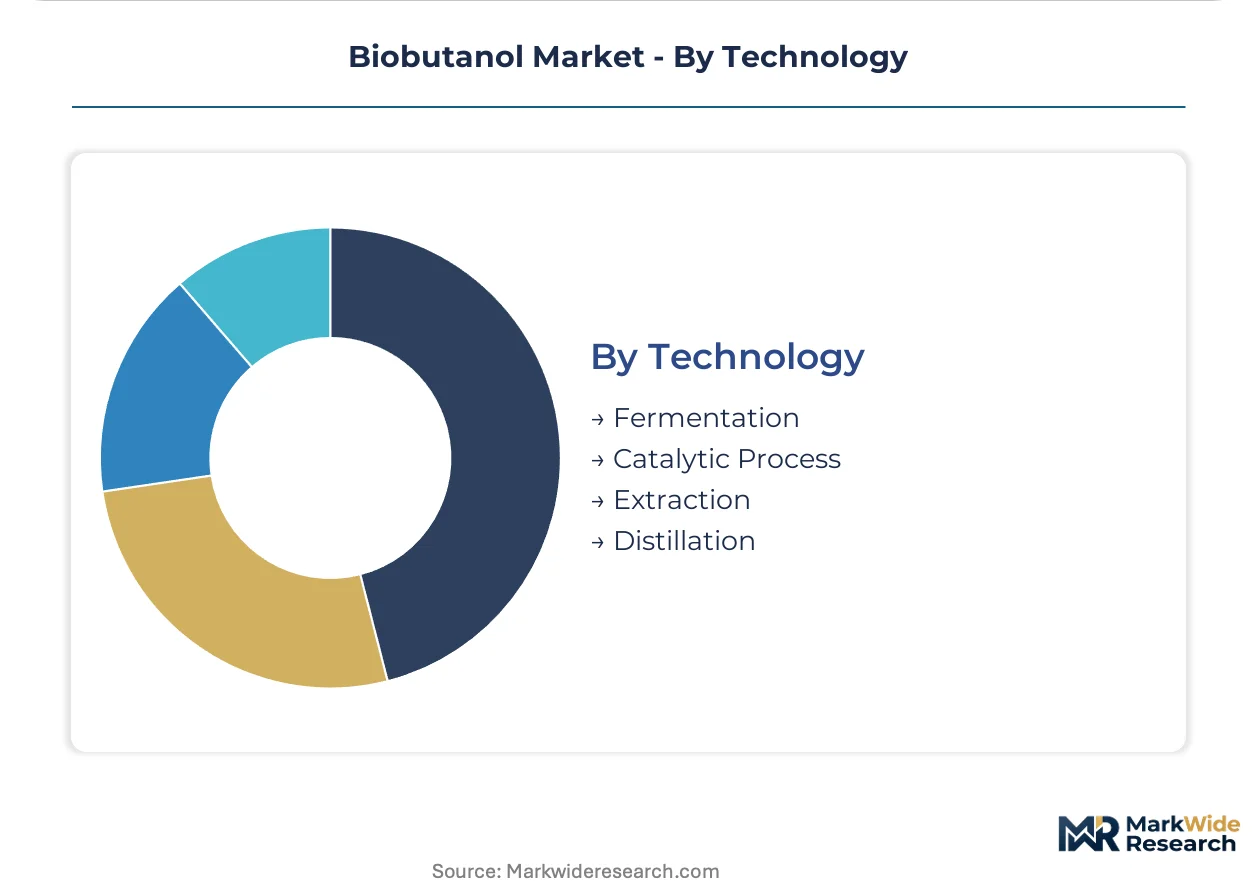
Process selection determines feedstock flexibility, capital intensity, and product slate composition. First-generation fermentation faces displacement pressure as cellulosic routes achieve yield targets.
- Fermentation:Microbial conversion of sugars and starches dominates commercial capacity, with Gevo and Butamax advancing proprietary yeast strain development. Corn feedstock integration in the U.S. Midwest and sugarcane bagasse processing in São Paulo represent the two primary deployment clusters.
- Catalytic Process:Syngas-to-butanol routes via Fischer-Tropsch or modified methanol chemistry attract R&D investment for woody biomass and waste feedstock flexibility. Capex intensity remains prohibitive at commercial scale.
- Extraction:In-situ product removal techniques address butanol toxicity limitations in fermentation broths.
- Distillation:Separation and purification steps integrate across all process configurations with energy consumption shaping unit economics.
Fermentation leads by installed capacity. Catalytic Process development is advancing most quickly on feedstock diversification potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. EPA anchors the dominant geography through renewable fuel standard obligations that redirect capital toward cellulosic biobutanol projects. Brazil's sugarcane belt and California's LCFS credit mechanisms concentrate demand in the Americas, while European REACH registration requirements reshape supplier qualification criteria across the Atlantic.
United States
Refinery procurement teams in Ohio and Indiana seek supply security for summer gasoline blending, driving fuel additive demand through direct contracting. The EPA's renewable volume obligations and RIN price dynamics shape sourcing decisions for cellulosic producers. Corn feedstock integration dominates the Midwest, though capital is shifting toward bagasse-compatible technology.
Brazil
São Paulo and Minas Gerais leverage existing ethanol distillation infrastructure for bagasse-to-butanol project deployment. ANVISA registration pathways and national biofuel policy frameworks support domestic processing capacity expansion. The sugarcane belt's established logistics networks reduce biomass transportation costs for fermentation operators.
Germany
Coatings manufacturers absorb n-butanol volumes through integrated chemical supply chains, though cellulosic producers struggle against fossil-derived cost positions. ECHA REACH registration requirements impose compositional testing burdens that favor producers with captive analytical capabilities. The Rhine-Ruhr industrial corridor concentrates solvent-grade demand from automotive OEM supply chains.
China
GB standards for fuel alcohols and dual carbon policy goals redirect investment toward cellulosic technology maturation. The Yangtze River Delta hosts pilot catalytic process routes from syngas for woody biomass feedstock flexibility. State-backed biorefinery projects target chemical intermediate markets with moderate purity specifications.
California
CARB LCFS credit mechanisms generate tradable credits that improve project economics for cellulosic producers targeting West Coast refiners. RIN generation and credit stacking enable arbitrage windows for advanced biofuel operators. The state's gasoline pool requirements position isobutanol as a higher-octane ethanol alternative with superior vapor pressure characteristics.
Biobutanol Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the biobutanol value chain. The market structure concentrates around integrated chemical conglomerates with captive fermentation capacity and specialized biorefinery operators with proprietary strain development. Three archetypes dominate: backward-integrated agribusinesses controlling feedstock supply, industrial bioscience licensors with patent-protected pathways, and diversified chemical manufacturers extending scale into biobased derivatives. Competitive moves center on multi-year offtake agreements with indexed pricing and cellulosic pretreatment capacity expansion.
Within the industrial bioscience tier, Gevo, Inc. and Butamax Advanced Biofuels LLC exemplify proprietary technology positions, while BASF SE represents the chemical manufacturing scale archetype. These three anchors reflect divergent strategic bets: yeast strain development against integrated supply chain control against derivative manufacturing scale.
| Leading Market Players |
|---|
| Cathay Industrial Biotech Ltd |
| Abengoa |
| Gevo, Inc. |
| Butamax Advanced Biofuels LLC |
| GranBio |
| BASF SE |
| Eastman Chemical Company |
| DuPont Industrial Biosciences |
| Green Biologics Ltd. |
| Others |
Cost & Logistics Intelligence
Cellulosic pretreatment capacity utilization in the U.S. Gulf Coast and São Paulo state shapes price floors across fuel-grade and chemical-grade tiers, concentrating margin capture among operators with backward integration into corn or bagasse feedstock supply. Scale advantages in enzymatic hydrolysis equipment deployment compress unit capital costs for first movers while locking in indexed offtake pricing tied to RIN values and corn futures.
Pricing Analysis
Midwest-U.S. to West-Coast price spreads reflect California LCFS credit stacking and transportation cost differentials for isobutanol fuel additive grades. Three-tier pricing structure across pharmaceutical-grade, fuel-grade, and solvent-grade specifications differentiates margin pools, with USP-grade purity commanding substantial premiums over refinery blending volumes. Cost compression in fuel-grade n-butanol intensifies as petrochemical substitution from propylene oxidation maintains cost advantages in coatings applications. Refinery procurement teams exhibit highest price sensitivity through indexed long-term contracts, while pharmaceutical formulators accept premium pricing for GMP-capable supply security.
Supply Chain Analysis
Enzymatic hydrolysis equipment availability and specialized fermentation engineering talent constitute chokepoints constraining cellulosic capacity expansion timelines. Feedstock supply concentrates in the U.S. Midwest corn belt, Brazil's São Paulo-Minas Gerais sugarcane corridor, and emerging woody biomass clusters in China's Yangtze River Delta. Process configurations draw from corn starch, sugarcane bagasse, and lignocellulosic woody inputs with divergent pretreatment requirements. Single-source vulnerability in proprietary yeast strain supply from industrial bioscience licensors threatens operational continuity for licensed fermentation operators. Distribution runs through direct refinery offtake agreements in fuel markets and specialized chemical distributors for pharmaceutical and solvent segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in fermentation engineering consulting and cellulosic pretreatment technology licensing expand faster than commodity biobutanol production, as capital deployment lags technical capability development across automotive OEM supply chains.
For Market Incumbents: Compound defensive positioning through captive yeast strain development and multi-year refinery offtake agreements with RIN-indexed pricing to neutralize emerging catalytic process competitors. Prioritize capacity addition in bagasse-compatible configurations near São Paulo's established ethanol logistics infrastructure. Invest in integrated analytical capabilities to satisfy ECHA REACH registration burdens compressing the qualified European supplier base. For New Entrants and Emerging Players: Anchor in pharmaceutical-grade purity segments where GMP capabilities and USP documentation requirements sustain premium pricing above fuel-grade commodity competition. Target white-space opportunities in cosmetics natural-derived positioning and preservative applications with modest volume thresholds and elevated margin structures. Pursue direct contracting with German and Dutch chemical distributors demanding integrated supply chain transparency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cellulosic pretreatment equipment suppliers and proprietary strain development platforms over first-generation corn fermentation assets approaching obsolescence. Long-term viability hinges on feedstock flexibility enabling cost position migration from starch-based to lignocellulosic process economics. Acquisition targets should demonstrate commercial yield achievement in consolidated bioprocessing configurations. The signal to watch is EPA cellulosic waiver credit price dynamics creating arbitrage windows for advanced biofuel RIN generation capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn belt acreage control and bagasse sourcing agreements neutralize price volatility for Gevo and Butamax. |
| Cellulosic Pretreatment Capacity Expansion | Enzymatic hydrolysis deployment in the U.S. Gulf Coast compresses unit capital costs for licensed operators. |
| Long-term Refinery Offtake Agreements | Ohio and Indiana direct contracting replaces merchant spot purchases with RIN-indexed supply security. |
| Pharmaceutical-Grade Certification Investment | GMP capabilities and USP documentation unlock premium pricing from cosmetics and drug formulation buyers. |
| Proprietary Yeast Strain Development | Engineered butanol tolerance and selectivity differentiate industrial bioscience licensors from commodity fermentation. |
Research Approach
Cross-validation between primary interviews with biorefinery plant managers, refinery procurement leads, and fermentation engineering specialists and secondary validation through EPA renewable volume obligation filings, ECHA REACH registration databases, and CARB LCFS credit transaction records anchors the qualitative findings. Customs and trade data from U.S. ITA and Brazilian MDIC complement SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up capacity assessments across São Paulo, Ohio, and Indiana production clusters triangulate against top-down demand modeling from automotive OEM fuel additive specifications.
Sensitivity analysis across feedstock price scenarios and cellulosic yield achievement timelines informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, technology process configuration, and regional regulatory framework cluster. CAGRs derive from installed capacity buildout trajectories and offtake agreement visibility rather than demand extrapolation alone. Key forecast inputs incorporate RIN price volatility bands and LCFS credit market depth assumptions.
Material uncertainties — EPA renewable volume obligation rulemaking revisions, cellulosic waiver credit price collapses, and REACH registration requirement escalations — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology maturation timelines and feedstock cost convergence. Practitioners should keep alternative scenarios live as CARB LCFS program amendments and Brazilian ANVISA biofuel policy frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Global Fuel Ethanol Market
Fuels
Mobile Fuel Delivery Market
Fuels
LPG Gas Cylinder Market
Fuels
Diesel As Fuel Market
Fuels
LPG Vaporizer Market
Fuels
United States LNG Bunkering Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Briquette Market
Fuels
Mobile Gas Pumping System Market
Fuels
Anthracite Coal Mining Market
Fuels
Global Methane Hydrate Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Global Charcoal Market
Fuels
Europe Aviation Fuel Market
Fuels
United Kingdom Chemical Logistics Market