
 Hairball Cat Food Market | 2026-2036
Hairball Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Hairball Cat Food Market Foresight
Market Context
The capability gap between mass-market manufacturers and clinical-nutrition specialists is reorganizing competitive dynamics in functional pet nutrition. Royal Canin leverages its veterinary-channel relationships to anchor premium positioning. Nestlé Purina Petcare competes through scaled manufacturing and broad retail distribution. Hill's Pet Nutrition differentiates via prescription-tier formulations developed in collaboration with veterinary professionals.
Technical Definition and Segments
Hairball cat food denotes formulated feline diets engineered with elevated fiber content, typically five to eight percent crude fiber, to facilitate intestinal transit and reduce trichobezoar formation in grooming-prone breeds. These products serve the commercial purpose of mitigating a prevalent feline health concern while reducing veterinary intervention frequency. Dry food occupies the largest volume share due to storage convenience and lower per-serving cost, though high-fiber wet food segments are expanding fastest as palatability-sensitive consumers shift toward moisture-rich formats. Natural and grain-free ingredient categories command margin premiums, while online retail channels are capturing share from traditional pet shops through subscription-based replenishment models.
Regulatory Frame
The FDA's Center for Veterinary Medicine enforces ingredient safety and labeling accuracy for pet food sold in the United States, while the European Union's Feed Hygiene Regulation establishes manufacturing standards across member states. The Association of American Feed Control Officials provides model labeling guidelines that most U.S. states adopt, directly shaping permissible health claims on hairball-control packaging. Pet food manufacturers must monitor evolving scrutiny of functional claims, as regulators in both jurisdictions weigh stricter substantiation requirements for condition-specific marketing.
Market Dynamics
Veterinary-channel consolidation is compressing distribution pathways for functional pet nutrition, forcing manufacturers to secure shelf space through direct clinic partnerships rather than traditional retail intermediaries.
Growth Catalysts
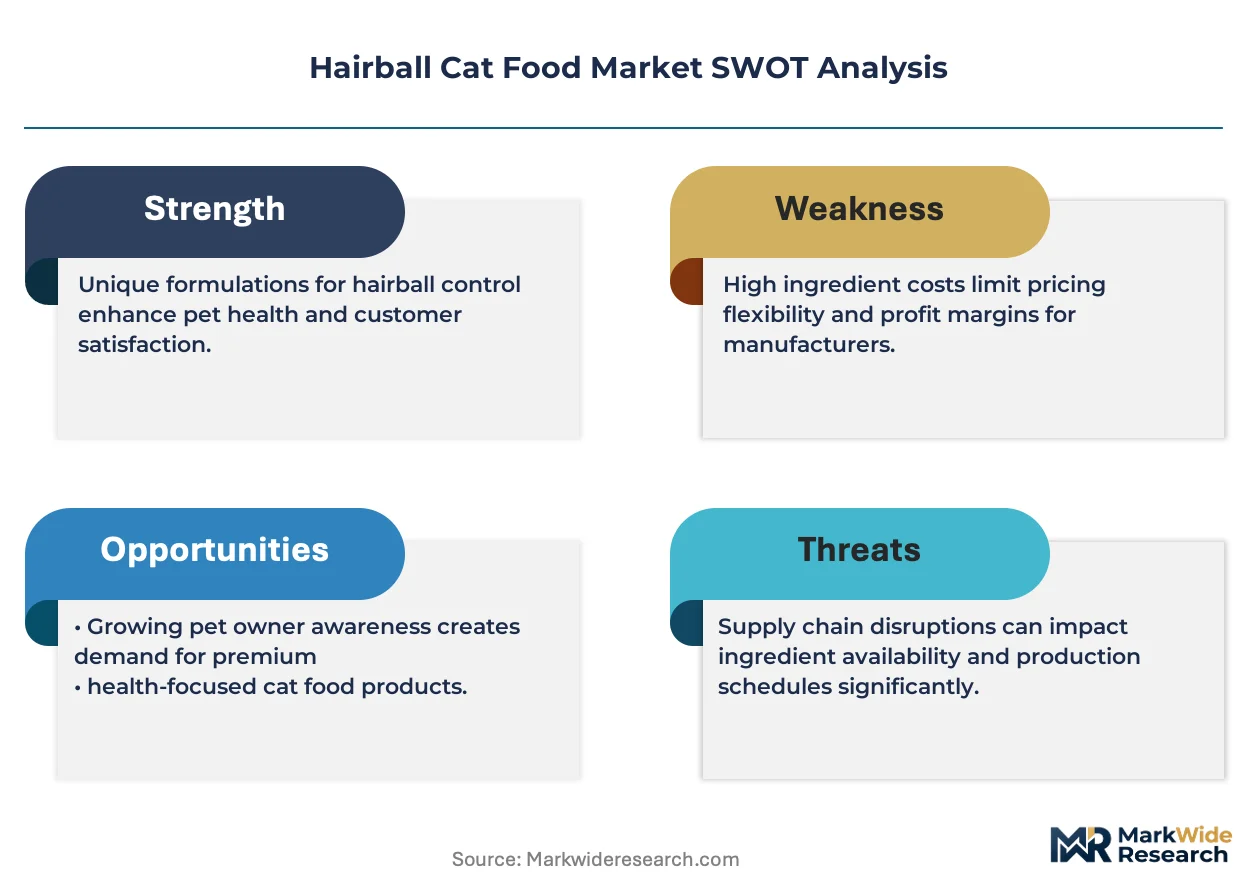
- AAFCO Labeling Guidelines:The Association of American Feed Control Officials' model regulations provide clear substantiation pathways for hairball-control claims, reducing regulatory uncertainty for new entrants.
- Elevated Fiber Formulation:Advances in soluble and insoluble fiber blending achieve palatability thresholds previously unattainable at functional dosage levels.
- Germany:Premium pet food penetration in German households exceeds regional averages, creating concentrated demand for condition-specific nutrition.
Market Restraints
- Chicken Meal Price Volatility:Primary protein input costs fluctuate with avian influenza cycles and feed grain markets, compressing margin stability.
- Midwestern US Rendering Concentration:Over half of domestic animal protein meal supply originates from a three-state processing corridor, creating geographic vulnerability.
- FDA Substantiation Requirements:The Center for Veterinary Medicine's evolving scrutiny of functional claims lengthens pre-market validation timelines.
Strategic Opportunities
- Veterinary Telehealth Expansion:Remote consultation platforms create direct-to-consumer prescription pathways bypassing traditional retail gatekeepers.
- Subscription Replenishment Models:Automated delivery systems capture lifetime value through predictable consumption tracking and personalized portioning.
- France:Underdeveloped functional nutrition penetration relative to total pet food spend offers expansion headroom for condition-specific formulations.
Industry Challenges
- Veterinary Nutritionist Recruitment:Qualified formulators with dual expertise in clinical nutrition and manufacturing scalability command premium compensation.
- ISO 22000 Certification Timelines:Feed safety management system accreditation requires 12-18 month implementation cycles delaying facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairball Cat Food Market |
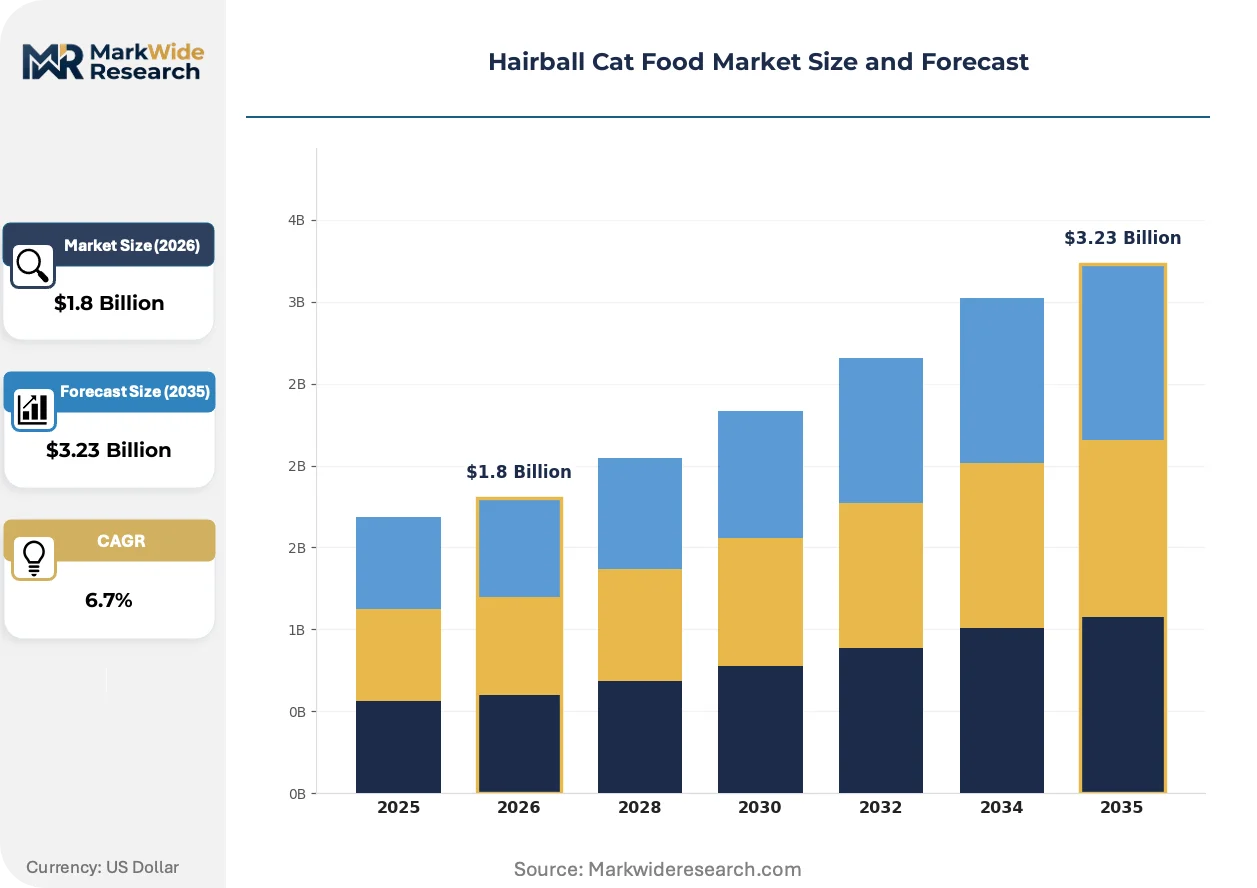
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Ingredient Type: Natural, Organic, Grain-free, High Fiber Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pet Shops Price Tier: Premium, Mid-range, Budget, Discount |
| Companies Covered | Royal Canin, WellPet, Nestlé Purina Petcare, Merrick Pet Care, Iams, Mars Petcare, Blue Buffalo, Orijen, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairball Cat Food Market Shifts & Advancements
Precision nutrition platforms are displacing one-size-fits-all formulations as data-enabled feeding recommendations reshape how owners select functional diets.
Encapsulated fiber technology is miniaturizing delivery systems for hairball-control actives, enabling incorporation into palatability-sensitive wet food matrices without texture degradation. Premium manufacturers in Japan are adopting micro-encapsulation processes licensed from human pharmaceutical applications. This convergence is compressing the historical trade-off between functional efficacy and moisture-rich formats.
REACH chemical registration requirements in the European Union are extending compliance obligations to novel feed additives, elevating documentation burdens for imported functional ingredients. Manufacturers sourcing specialty fibers from outside the EU must now establish complete substance dossiers. Wet food segments containing imported novel ingredients face the steepest adaptation costs.
Subscription-based replenishment is capturing share from impulse-driven retail purchases as algorithmic portioning reduces overfeeding waste. Direct-to-consumer platforms disintermediate pet specialty retailers in urban markets with reliable delivery infrastructure. This pattern concentrates in metropolitan UK and Netherlands corridors where premium pet ownership density supports logistics economics.
Hairball Cat Food Market Segmentation
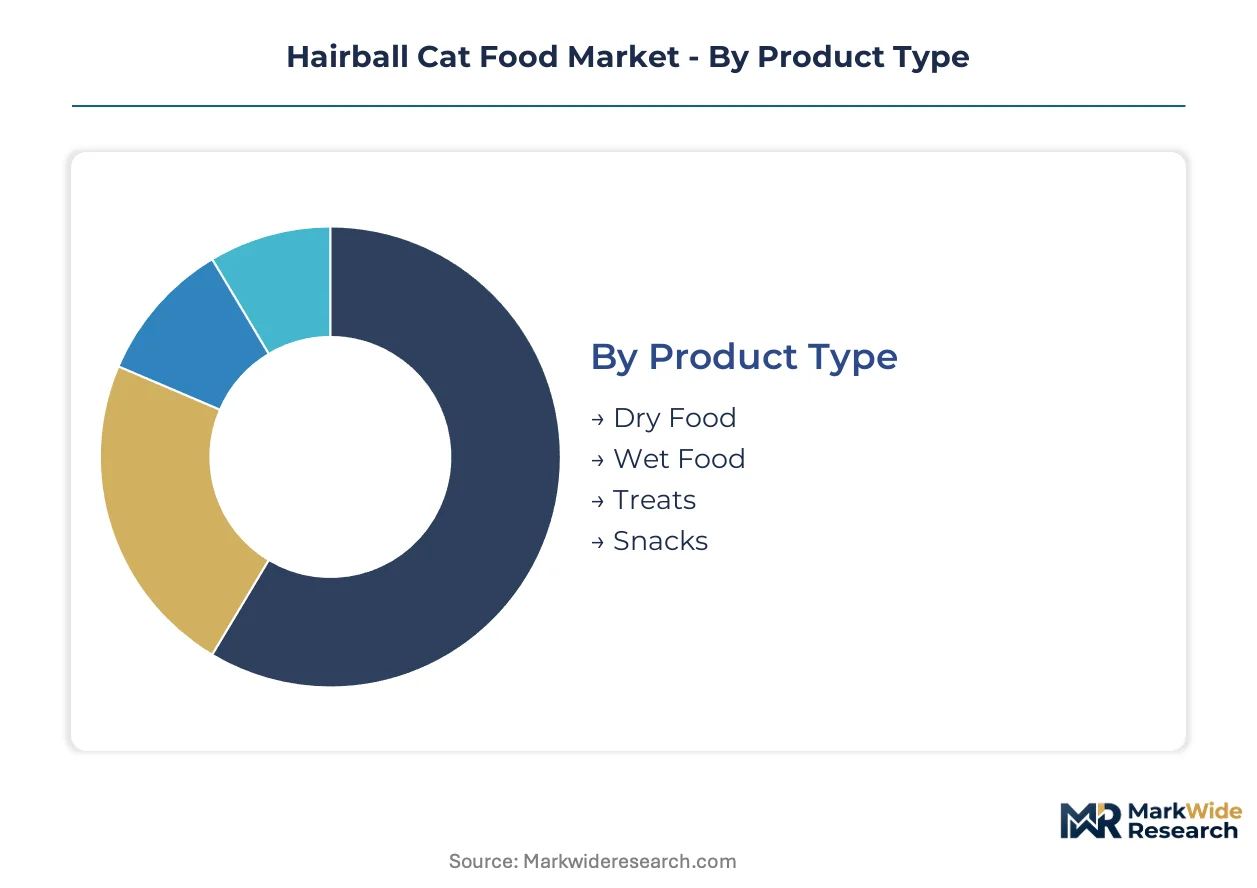
Hairball cat food segmentation reveals how fiber formulation, moisture content, and channel economics partition value capture across distinct buyer profiles. Manufacturers align R&D investment and distribution partnerships to the specific performance and purchasing behaviors each segment rewards.
Product Type:
Dry food dominates domestic manufacturing footprints across the United States and Germany, while wet food expansion relies heavily on imported encapsulation technologies from Japanese pharmaceutical licensors.
- Dry Food:Kibble formulations integrate five to eight percent crude fiber through extrusion processes optimized for shelf stability and portion control. Demand concentrates in suburban United States households where bulk purchasing and storage convenience outweigh palatability concerns. Midwestern rendering corridor proximity secures protein meal supply advantages for domestic producers.
- Wet Food:Moisture-rich matrices require micro-encapsulated fiber delivery to prevent texture degradation, elevating per-unit production costs. German and UK metropolitan markets drive adoption as premium consumers prioritize hydration-sensitive breeds and veterinary moisture recommendations. Japanese-licensed encapsulation technology creates import dependency for European manufacturers.
- Treats:Functional hairball treats occupy impulse-purchase occasions with compressed fiber dosing for intermittent use. Pet specialty retailers in France and Netherlands merchandise these at checkout proximity to capture add-on revenue.
- Snacks:Semi-moist snack formats bridge treat and meal-replacement occasions with moderate fiber inclusion. Limited production scale constrains geographic distribution to premium urban corridors.
Dry food holds the largest share; momentum sits with wet food as encapsulation costs compress and palatability-sensitive consumers migrate toward moisture-rich formats.
Ingredient Type:
Cost tier alignment separates commodity fiber sourcing from certified organic supply chains, with margin premiums expanding fastest in grain-free and natural categories.
- Natural:Minimally processed fiber sources including beet pulp and psyllium husk command ingredient transparency premiums. United States consumers in coastal metropolitan markets verify natural claims through AAFCO model guideline compliance.
- Organic:Certified organic fiber inputs require USDA or EU organic accreditation, extending supplier qualification timelines. German and Austrian households demonstrate highest willingness-to-pay for organic certification in functional pet nutrition.
- Grain-free:Formulations substitute traditional grain fibers with legume and tuber alternatives to address perceived gluten sensitivity. Veterinary skepticism in the United Kingdom moderates growth relative to consumer enthusiasm.
- High Fiber:Clinical-grade fiber concentrations exceeding eight percent target veterinary-diagnosed trichobezoar cases. Prescription-tier positioning restricts distribution to clinic-affiliated channels in the United States and Western Europe.
Natural ingredient positioning captures the broadest volume base; organic certification climbs fastest as supply chain transparency becomes a purchase prerequisite.
Distribution Channel:
Channel selection determines customer acquisition economics, with subscription platforms disintermediating traditional retail in logistics-dense urban corridors.
- Online Retail:Algorithmic replenishment platforms capture lifetime value through consumption tracking and personalized portioning. Netherlands and UK metropolitan markets exhibit highest subscription penetration for functional cat nutrition.
- Supermarkets:Mass-market placement demands price competitiveness and packaging formats suited to self-service retail. Mid-range dry food segments dominate supermarket shelf space in the United States and Germany.
- Specialty Stores:Independent pet retailers provide educated staff consultation for condition-specific nutrition selection. France maintains higher specialty store density relative to online migration than neighboring markets.
- Pet Shops:Chain pet retailers balance breadth of assortment with veterinary-affiliated prescription fulfillment. Clinic partnerships in suburban United States locations anchor premium positioning for functional formulations.
Pet shops and supermarkets retain volume leadership; online retail gains share fastest where delivery infrastructure density supports logistics economics.
Price Tier:
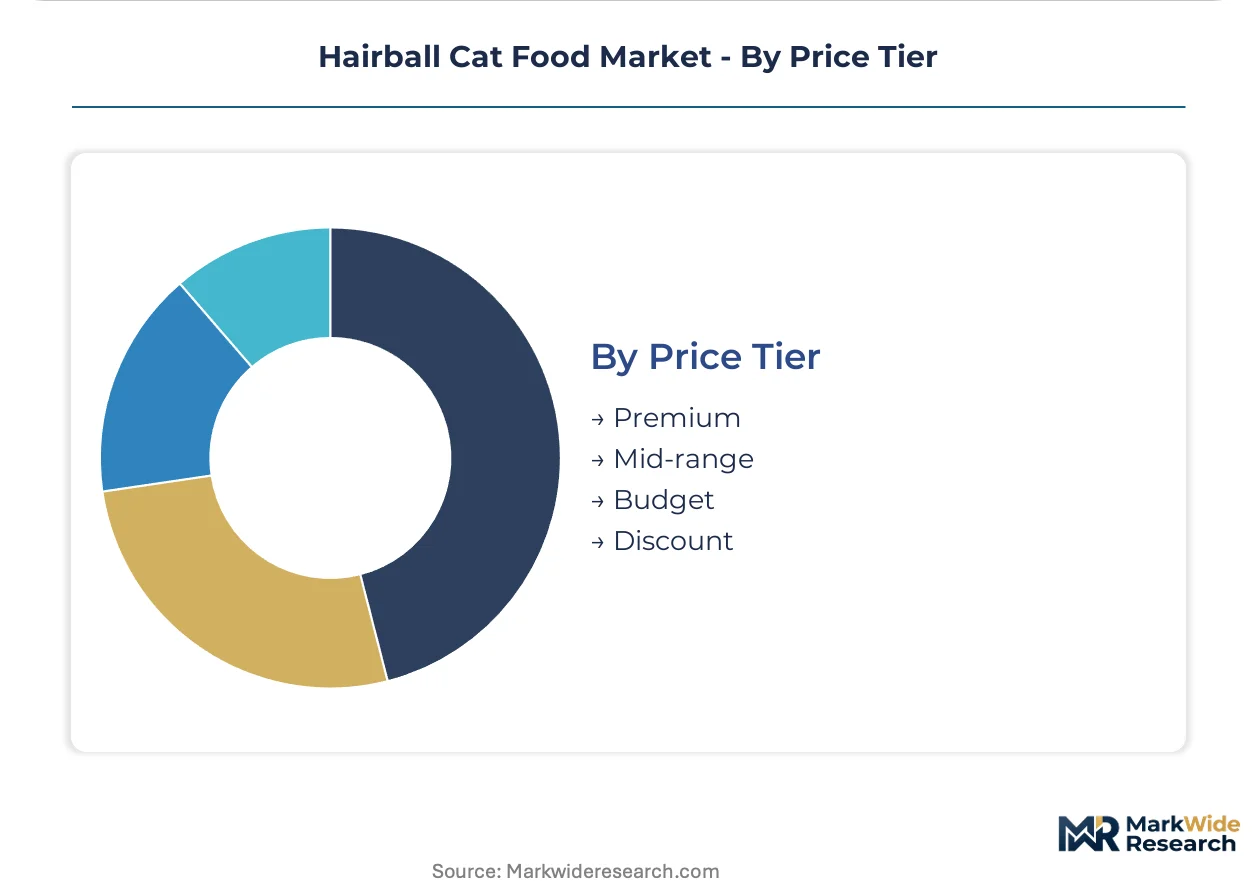
Margin structure stratifies across certification intensity and channel service levels, with premium tiers absorbing regulatory compliance and veterinary consultation costs.
- Premium:Veterinary-channel formulations incorporate clinical validation and prescription-tier positioning. FDA Center for Veterinary Medicine substantiation requirements elevate pre-market investment for United States premium entrants.
- Mid-range:Mass-market functional claims balance efficacy demonstration with accessible pricing. German and UK consumers in this tier prioritize AAFCO-compliant hairball-control labeling over organic certification.
- Budget:Price-competitive fiber inclusion meets baseline hairball-control claims without specialized delivery technologies. Supermarket dominance in this tier compresses manufacturer margins.
- Discount:Value-positioned offerings sacrifice fiber specificity for general digestive health positioning. Limited shelf space allocation in mainstream retail constrains segment development.
Mid-range pricing captures the largest household penetration; premium tier expansion accelerates with veterinary telehealth channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United Kingdom exhibit low price elasticity for functional nutrition, while budget-conscious segments in France and suburban United States markets drive volume through mid-range positioning. This divergence shapes where manufacturers deploy premium versus mass-market formulations.
United States
Veterinary-channel consolidation and subscription platform adoption concentrate demand in metropolitan corridors. The FDA's Center for Veterinary Medicine enforces substantiation requirements for hairball-control claims, elevating compliance costs for new entrants. Midwestern rendering facilities supply protein inputs to dry food manufacturers clustered in Kansas and Missouri.
Germany
Premium pet food penetration exceeds regional benchmarks, with organic certification commanding measurable willingness-to-pay premiums. The EU's Feed Hygiene Regulation establishes manufacturing standards that domestic producers leverage for export credibility. Munich and Hamburg anchor specialty retail density for condition-specific nutrition.
United Kingdom
Algorithmic replenishment platforms capture disproportionate share in London and Southeast England logistics corridors. Veterinary skepticism toward grain-free positioning moderates segment growth relative to consumer enthusiasm. Manchester and Birmingham distribution hubs service subscription fulfillment networks.
France
Underdeveloped functional nutrition penetration relative to total pet food spend creates expansion headroom for condition-specific entrants. ANSM oversight of feed safety aligns with EU-wide harmonization while preserving national notification pathways. Paris and Lyon specialty retailers maintain higher consultation-driven purchase patterns than neighboring markets.
Japan
Micro-encapsulation technology licensing from pharmaceutical applications enables wet food innovation at functional dosage levels. METI industrial policy supports pet food sector R&D through regional innovation clusters. Tokyo and Osaka metropolitan markets demonstrate concentrated demand for palatability-sensitive moisture-rich formats.
Hairball Cat Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Veterinary-channel specialists anchor premium positioning through clinical validation, while mass-market manufacturers compete via scaled production and broad retail distribution. Three archetypes dominate: prescription-tier formulators, scaled consumer goods conglomerates, and natural-positioned independents. M&A activity concentrates veterinary clinic networks, while portfolio diversification moves absorb functional nutrition specialists into broader pet care platforms.
Among diversified consumer goods conglomerates, Nestlé Purina Petcare and Mars Petcare occupy positions defined by manufacturing scale and retail channel breadth. Royal Canin exemplifies the veterinary-channel archetype through clinic-affiliated distribution. Hill's Pet Nutrition anchors prescription-tier positioning with professional collaboration frameworks. These three entities represent the structural poles around which mid-cap specialists and regional independents orbit.
| Leading Market Players |
|---|
| Royal Canin |
| WellPet |
| Nestlé Purina Petcare |
| Merrick Pet Care |
| Iams |
| Mars Petcare |
| Blue Buffalo |
| Orijen |
| Hill's Pet Nutrition |
| Others |
Supply & Pricing Matrix
Midwestern rendering capacity utilization above eighty percent creates asymmetric cost advantages for domestic dry food manufacturers while elevating entry barriers for wet food specialists dependent on Japanese encapsulation imports. Scale concentration in protein meal processing directly shapes price floors across tiered product positioning.
Pricing Analysis
Subscription replenishment revenue drives lifetime value capture as algorithmic portioning platforms lock in predictable consumption patterns. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-channel formulations with FDA substantiation costs from mass-market AAFCO-compliant labels and budget-tier supermarket placement. Cost compression in mid-range dry segments intensifies because chicken meal price volatility transmits directly through Midwestern rendering corridors. Budget-tier supermarket buyers exhibit highest price sensitivity; premium subscription adopters in UK and Netherlands metropolitan corridors demonstrate lowest elasticity.
Supply Chain Analysis
Container availability constraints on transpacific lanes elevate landed costs for European manufacturers sourcing Japanese micro-encapsulation technology. Protein meal supply draws from United States, Argentina, and Brazilian rendering facilities; specialty fiber inputs rest on Indian psyllium husk and Canadian beet pulp cultivation. Single-source vulnerability concentrates in Japanese pharmaceutical-licensed encapsulation patents for wet food matrices. Distribution runs through veterinary clinic networks for prescription tiers, pet specialty retailers for mid-range positioning, and algorithmic subscription platforms for premium urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary nutritionist scarcity constrains formulation capacity expansion as qualified professionals with dual clinical-manufacturing expertise command premium compensation packages. This talent bottleneck shapes competitive dynamics more than capital availability.
For Market Incumbents: Shield prescription-tier positioning through exclusive clinic partnership networks before telehealth platforms disintermediate traditional distribution. Acquire ISO 22000-certified manufacturing assets in Germany to preempt European supply chain fragmentation. Vertical integration into Midwestern rendering capacity secures protein meal cost stability against avian influenza cycles.
For New Entrants and Emerging Players: Algorithmic replenishment service gaps in French and Austrian metropolitan corridors offer white-space entry points where incumbent subscription penetration lags UK benchmarks. Target underdeveloped functional nutrition penetration in France through specialty retail consultation partnerships. Pursue direct-to-consumer veterinary telehealth integration as primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform operators with algorithmic portioning capabilities and consumption-tracking data assets. Five-to-ten-year viability favors acquisition targets combining Japanese encapsulation licensing with European manufacturing footprints. Monitor FDA Center for Veterinary Medicine substantiation timeline extensions as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Integration | Direct-to-consumer prescription pathways bypass traditional retail gatekeepers in metropolitan corridors. |
| Encapsulation Technology Licensing | Japanese pharmaceutical-derived micro-encapsulation enables wet food functional efficacy without texture degradation. |
| Subscription Platform Development | Algorithmic replenishment captures lifetime value through consumption tracking in UK and Netherlands logistics corridors. |
| Organic Certification Investment | USDA and EU organic accreditation commands measurable willingness-to-pay premiums in German and Austrian households. |
| Midwestern Rendering Capacity Control | Upstream protein meal supply secures margin stability against avian influenza and feed grain price volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, EU Feed Hygiene Regulation implementations, and trade customs records for specialty fiber inputs. Veterinary nutritionists, pet specialty retail category managers, subscription platform operations directors, and rendering facility procurement leads provided structured input. Bottom-up segment sizing triangulates against top-down market value reconstruction across product type, ingredient certification, and distribution channel dimensions.
Segmentation dimensions modeled include moisture content format, fiber concentration tier, ingredient certification grade, distribution channel structure, and regional regulatory cluster across the projection horizon. CAGRs derive from consumption pattern elasticity analysis and penetration trajectory benchmarking. Forecast inputs incorporate veterinary consultation frequency data and subscription platform adoption curves in logistics-dense metropolitan corridors.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine substantiation requirements and EU Feed Hygiene Regulation enforcement; material policy shifts affecting functional claim validation or novel feed additive registration would require re-modeling. Avian influenza recurrence patterns and REACH chemical registration timeline extensions represent specific revision triggers for this industry. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Space Food Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Poke Food Market
Specialty Foods
Cultures Market