
 Global Ethnic Foods Market | 2026-2036
Global Ethnic Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethnic Foods Market Analysis
Asset-light licensing and co-manufacturing arrangements is reconfiguring competitive entry in ethnic foods, allowing regional brands to scale without capital-intensive production facilities. Ajinomoto Co. Inc. leverages its fermentation technology leadership to dominate Asian flavor bases in Western retail channels. McCormick & Company Inc. sustains its position through deep control of spice sourcing networks across multiple continents. Nestlé S.A. operates an extensive frozen ethnic meal portfolio that anchors shelf space in European and North American supermarkets.
Ethnic foods comprise prepared and semi-prepared food products formulated with traditional recipes, spices, and ingredient profiles originating from specific cultural or national cuisines, typically requiring controlled thermal processing, pH management, and preservative systems to maintain sensory authenticity under commercial distribution conditions. These products serve both retail consumers seeking convenience-driven cultural dining experiences and food service operators requiring scalable, consistent ethnic menu components. Frozen foods commands the largest volume position within product type segments due to extended shelf stability and meal-kit compatibility, while sauces captures disproportionate margin pools through premium positioning and repeat purchase frequency. Online retail distribution is expanding fastest as direct-to-consumer platforms reduce intermediary costs for specialty and small-batch ethnic producers.
The FDA enforces allergen labeling and facility registration requirements that shape formulation transparency for ethnic foods entering the United States, while the EU Green Deal packaging rules and REACH chemical standards constrain material choices for products distributed across European markets. EFSA and national regulators within Europe are tightening scrutiny on novel ingredient approvals for traditional ethnic additives previously accepted under grandfathered provisions. Stakeholders must monitor evolving border inspection protocols and sustainability certification requirements as these become decisive factors in market access negotiations.
Market Dynamics
Asset-light licensing models are fragmenting production ownership across the Global Ethnic Foods Market, as co-manufacturing networks allow regional brands to scale without fixed-asset commitments. This structural shift redistributes margin capture from capital-intensive processors to IP-holding recipe developers and brand aggregators.
Growth Catalysts
- EU Green Deal packaging mandates:Sustainability certification requirements for imported food products are accelerating biodegradable material adoption among Asian sauce exporters seeking European retail placement.
- Urban middle-class India:Metropolitan consumers in Mumbai, Bangalore, and Delhi are driving demand for authentic Korean, Japanese, and Mexican convenience meals through premium supermarket channels.
- Direct-to-consumer platforms:Online retail distribution is eliminating distributor markups for small-batch ethnic producers, enabling margin retention previously impossible under traditional wholesale structures.
Market Restraints
- Spice supply concentration:Deep control of sourcing networks by established players creates entry barriers for new entrants dependent on volatile turmeric, cardamom, and chili pepper spot markets.
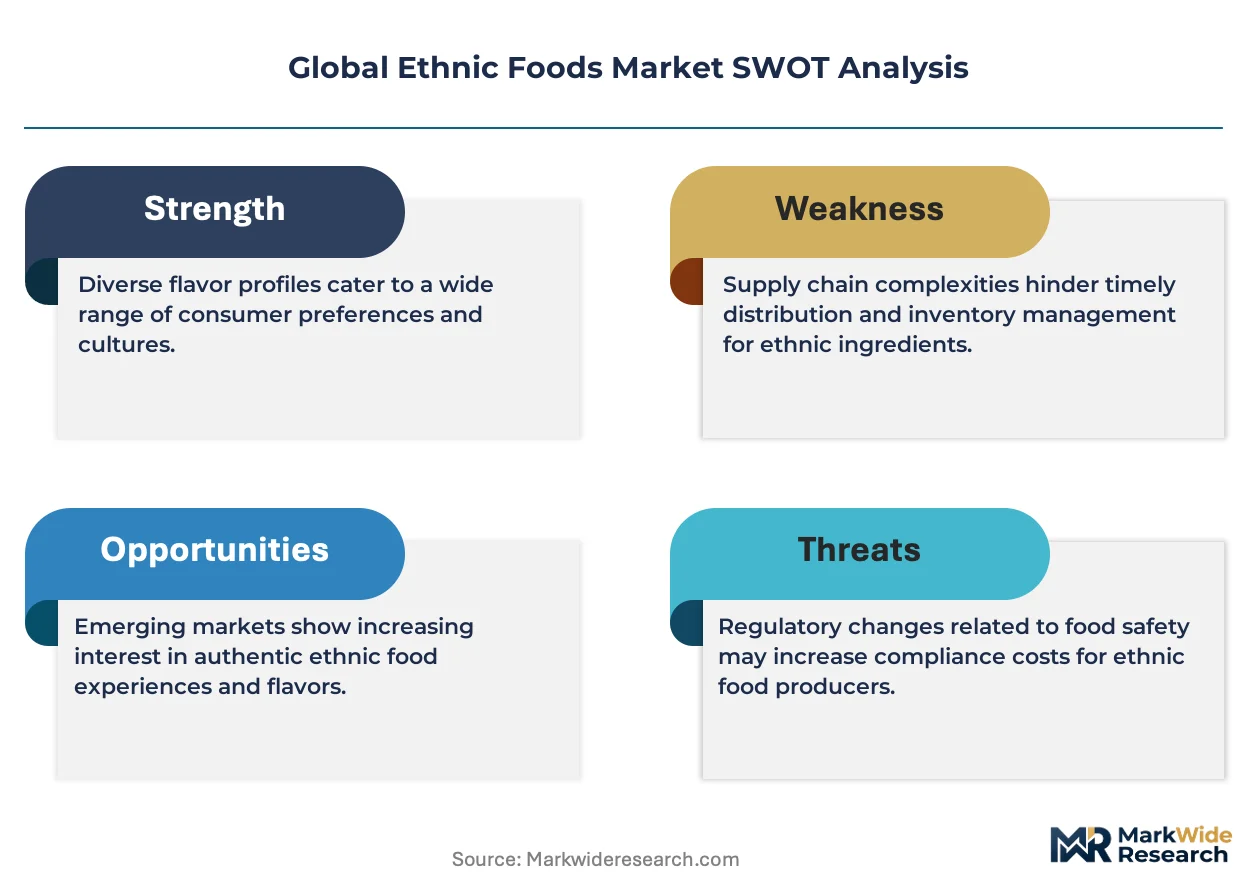
- Allergen labeling complexity:FDA facility registration and disclosure requirements impose formulation transparency costs that disadvantage traditional family-owned ethnic food manufacturers with limited compliance infrastructure.
- Novel ingredient grandfathering expiration:EFSA tightening on traditional ethnic additives previously accepted under legacy approvals forces reformulation of established product lines.
Strategic Opportunities
- Brazilian retail underpenetration:ANVISA regulatory harmonization with Mercosur standards is opening shelf space for frozen ethnic meal portfolios previously excluded by technical barriers.
- Fermentation technology convergence:Integration of precision fermentation with traditional koji and miso production methods is enabling clean-label umami bases without synthetic additive dependencies.
- Meal-kit channel expansion:Frozen foods compatibility with subscription box logistics is creating dedicated SKU development programs targeting urban millennial households in Canada and Australia.
Industry Challenges
- Sensory authenticity standardization:Consistent replication of traditional thermal processing profiles across co-manufacturing networks requires specialized training pipelines that qualified technicians currently lack.
- Cross-border inspection protocol fragmentation:Divergent border documentation requirements between US FDA, EU EFSA, and national regulators in target export markets multiply compliance timeline uncertainty.
- pH management system integration:Legacy production facilities face capital-intensive retrofitting to install automated monitoring equipment required for shelf-stable sauce manufacturing under modern food safety frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethnic Foods Market |
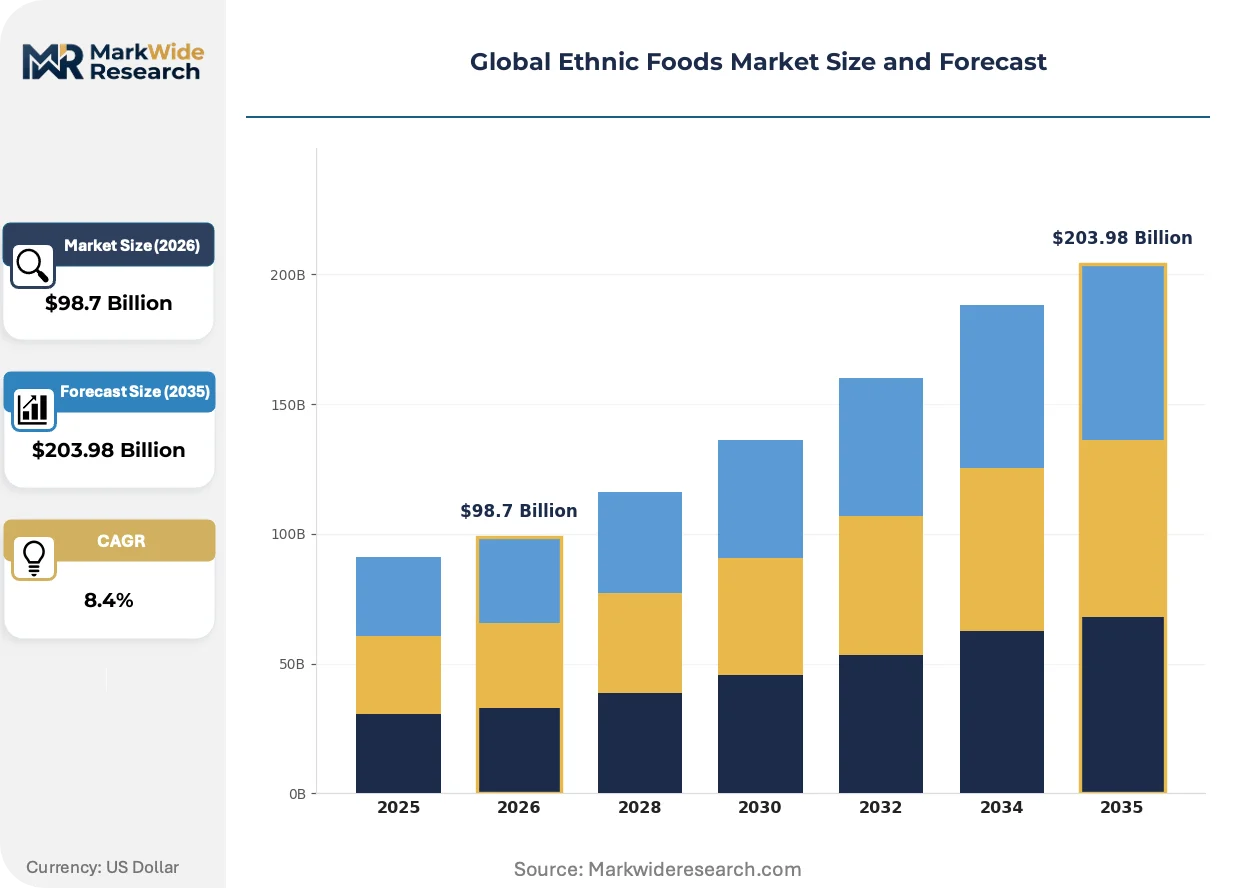
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Foods, Sauces, Snacks, Seasonings Ingredient: Corn, Rice, Lentils, Wheat Packaging Type: Pouches, Tins, Boxes, Bottles Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Ajinomoto Co. Inc., General Mills Inc., McCormick & Company Inc., Associated British Foods PLC, Conagra Brands Inc., Orkla ASA, Paulig Group, ARYZTA AG, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethnic Foods Market Emerging Trajectories
Digital replication of sensory evaluation protocols is compressing product development cycles for ethnic food formulations. Virtual testing environments now simulate consumer taste-panel responses before physical production runs, reducing iteration costs.
Artificial intelligence-driven flavor mapping is virtualizing the traditional chef-led recipe development process. Large ethnic food manufacturers deploy machine learning models trained on molecular gastronomy databases to predict optimal spice compound combinations. Adoption concentrates among frozen meal developers seeking rapid regional cuisine portfolio expansion. This virtualization collapses the 18-24 month traditional development timeline into 6-9 month cycles.
REACH chemical standards revision is constraining preservative system choices for shelf-stable ethnic sauces distributed across European markets. The ECHA restriction roadmap targets specific benzoate and sorbate compounds common in traditional Asian condiment formulations. Manufacturers are accelerating clean-label fermentation-based preservation research. Small-batch producers in South Korea and Thailand face disproportionate compliance burden relative to multinational reformulation resources.
Direct sourcing relationships between retail chains and ethnic food producers are disintermediating traditional import-distributor networks. Supermarket buyers in Germany, the United Kingdom, and the Netherlands now negotiate directly with Malaysian curry paste and Indonesian rendang specialists. This channel compression eliminates 15-25 point margin layers previously captured by regional distributors. The shift is most visible in frozen dim sum and dumpling categories where private-label development demands rapid supplier responsiveness.
Global Ethnic Foods Market Segmentation
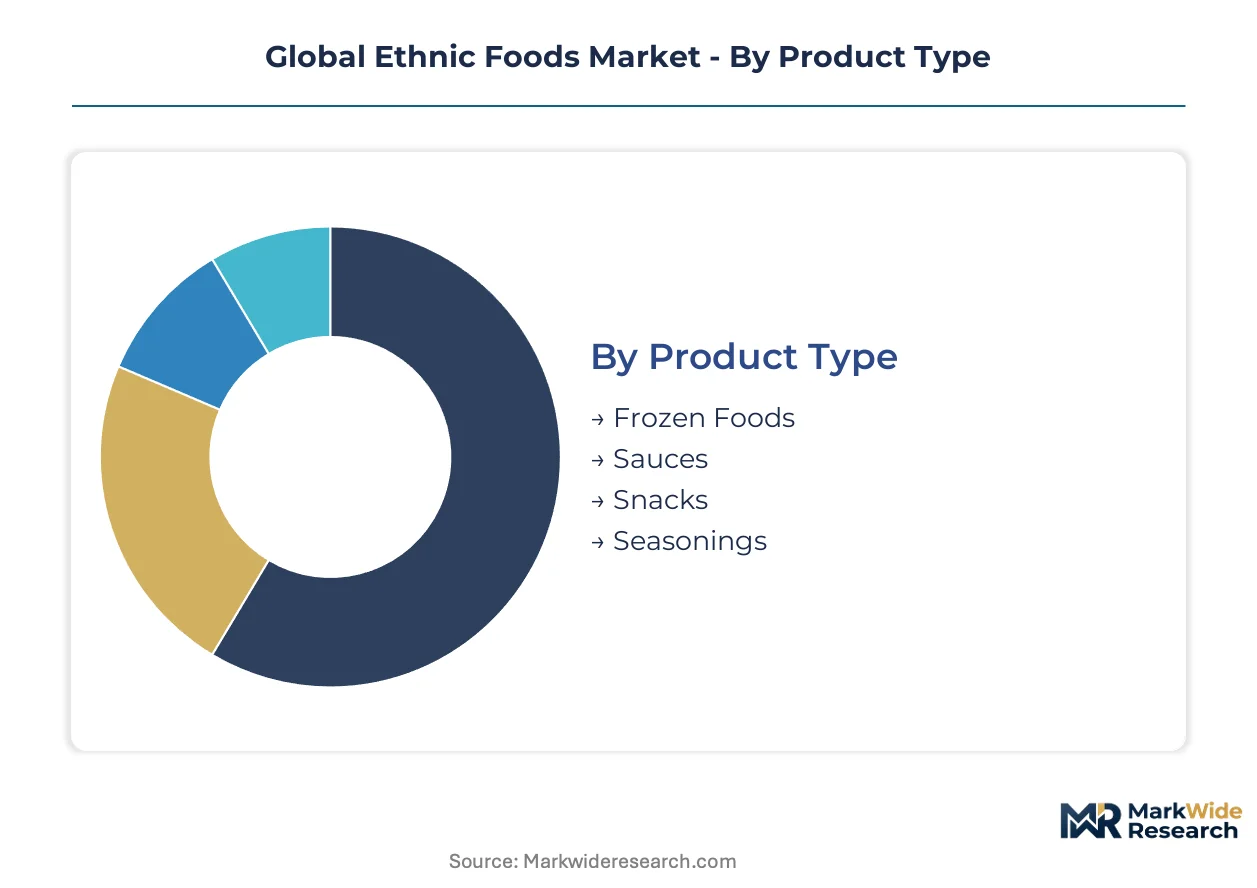
Segmentation in ethnic foods reveals how distinct consumption occasions and supply chain requirements fragment commercial opportunity. Frozen meal solutions compete on logistics efficiency while sauce and seasoning categories extract value through repeat purchase loyalty and formulation complexity.
Product Type:
Demand concentrates across preparation intensity levels, from fully assembled meals to component ingredients requiring consumer assembly.
- Frozen Foods:These comprise fully prepared or semi-prepared meals requiring controlled cold chain distribution to maintain sensory integrity. Demand concentrates in urban millennial households across Canada and Australia where subscription meal-kit compatibility drives SKU proliferation. Extended shelf stability and portion control attributes anchor retail placement.
- Sauces:Concentrated flavor bases and condiments formulated through controlled thermal processing and pH management systems. Premium positioning in German and Dutch supermarket channels extracts disproportionate margin pools through repeat purchase frequency. Clean-label fermentation-based preservation research accelerates amid REACH chemical standard revisions.
- Snacks:Shelf-stable prepared items including chips, crackers, and street-food-inspired formats.
- Seasonings:Dried spice blends and flavor enhancers for home cooking applications.
The dominant share belongs to Frozen Foods, while Sauces is closing the gap fastest.
Ingredient:
Raw material sourcing geography and agricultural processing infrastructure determine cost structures and supply security profiles.
- Corn:Base ingredient for masa-based products, tortilla systems, and fermented beverage applications. Mexican and Central American supply corridors anchor authenticity claims for North American distribution.
- Rice:Foundation grain for Asian cuisine formats spanning sushi, biryani, and congee applications. Japanese and Thai milling standards define quality benchmarks for export markets.
- Lentils:Protein-dense pulse ingredient dominant in South Asian dal and Middle Eastern mezze preparations. Indian and Turkish origin specifications command premium positioning in European specialty retail.
- Wheat:Structural carbohydrate for noodle, dumpling, and flatbread systems across multiple cuisine traditions.
Rice maintains volume leadership through broad cuisine applicability, though Lentils is expanding most quickly amid plant-based protein substitution trends.
Packaging Type:
Material selection reflects EU Green Deal sustainability mandates and shelf-life engineering requirements simultaneously.
- Pouches:Flexible multilayer structures for sauces and wet preparations. South Korean and Thai exporters accelerate biodegradable material adoption to secure European retail placement.
- Tins:Metal containers for shelf-stable prepared meals and condensed sauces.
- Boxes:Paperboard systems for dry mixes and frozen meal outer packaging.
- Bottles:Glass and PET formats for liquid condiments and beverage applications.
Pouches command growth momentum through material lightweighting and logistics efficiency, while Bottles retain premium positioning in gift and specialty channels.
Distribution Channel:
Channel selection determines margin retention, brand control, and consumer relationship depth.
- Supermarkets:Mass retail placement requiring national distribution infrastructure and promotional investment. Direct sourcing relationships between German and Dutch chains and Malaysian or Indonesian producers are compressing traditional import-distributor margins.
- Online Retail:Direct-to-consumer platforms eliminating intermediary markups for small-batch producers. Urban middle-class consumers in Mumbai, Bangalore, and Delhi drive premium Korean and Japanese convenience meal demand through this channel.
- Specialty Stores:Curated ethnic food retailers serving diaspora communities and culinary enthusiasts.
- Food Service:B2B supply to restaurants, catering operations, and institutional kitchens requiring scalable consistency.
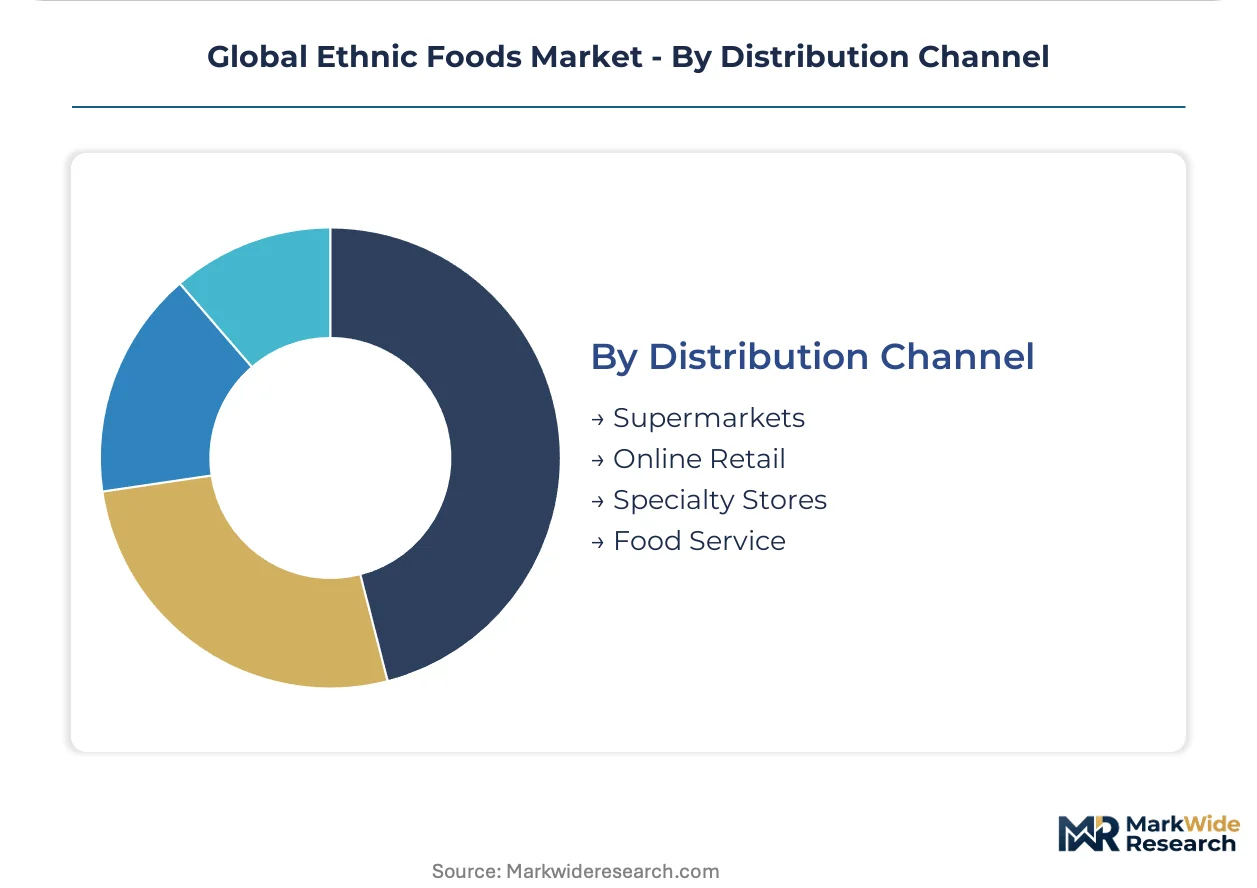
Supermarkets retain volume dominance, though Online Retail is climbing the fastest as platform infrastructure matures across target export markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Global Ethnic Foods Market exhibits pronounced trade asymmetries between production hubs and consumption centers. Export-oriented manufacturing clusters in Asia-Pacific and Latin America supply frozen meal and sauce formats to import-dependent markets across North America and Europe, with regulatory harmonization efforts reshaping cross-border flow patterns.
United States
Urban millennial households in New York, Los Angeles, and Chicago drive demand for Korean, Japanese, and Mexican convenience formats through meal-kit subscription channels. FDA facility registration and allergen disclosure requirements under the Food Safety Modernization Act impose compliance costs on traditional family-owned importers. Direct sourcing relationships between Texas-based retail chains and Thai sauce specialists are compressing traditional distributor margins in the frozen dim sum category.
Germany
Supermarket buyers in Berlin, Munich, and Hamburg negotiate directly with Malaysian curry paste and Indonesian rendang producers, eliminating 15-25 point margin layers previously captured by import distributors. EU Green Deal packaging mandates accelerate biodegradable material adoption among Asian exporters seeking shelf placement. The ECHA restriction roadmap under REACH targets benzoate and sorbate compounds common in traditional Asian condiment formulations.
India
Metropolitan consumers in Mumbai, Bangalore, and Delhi propel demand for authentic Korean, Japanese, and Mexican convenience meals through premium supermarket and online retail channels. FSSAI labeling harmonization with Codex Alimentarius standards streamlines import clearance for frozen ethnic meal portfolios. Domestic co-manufacturing networks in Gujarat and Maharashtra enable regional brands to scale production without capital-intensive facility investments.
South Korea
Seoul-based fermentation technology specialists integrate precision methods with traditional koji and miso production to develop clean-label umami bases. MFDS tightening on novel ingredient approvals forces reformulation of established sauce lines previously accepted under grandfathered provisions. Busan-Ulsan industrial corridors anchor export-oriented manufacturing for European and North American retail placement.
Brazil
São Paulo and Rio de Janeiro retail channels present underpenetrated opportunity for frozen ethnic meal portfolios as ANVISA regulatory harmonization with Mercosur standards opens previously excluded shelf space. Urban middle-class consumers seek authentic Asian and Middle Eastern convenience formats through expanding supermarket infrastructure. Direct-to-consumer platforms reduce intermediary costs for small-batch producers targeting metropolitan households.
Global Ethnic Foods Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in flavor base and spice sourcing. The Global Ethnic Foods Market structures around three distinct competitive tiers: multinational conglomerates with frozen meal portfolios, fermentation technology leaders controlling Asian flavor bases, and spice sourcing network operators. Consolidation pressures concentrate among sauce and seasoning categories where repeat purchase frequency sustains premium positioning. Dominant competitive moves include asset-light licensing arrangements and co-manufacturing partnerships that redistribute margin capture from capital-intensive processors to IP-holding recipe developers.
Within the fermentation technology tier, Ajinomoto Co. Inc. exemplifies platform integration through controlled thermal processing capabilities. McCormick & Company Inc. and Nestlé S.A. occupy positions spanning spice network control and frozen meal portfolio scale respectively. These three entities represent divergent archetypes: technology-led flavor base dominance, upstream agricultural sourcing consolidation, and retail shelf space anchoring through multinational distribution infrastructure.
| Leading Market Players |
|---|
| Ajinomoto Co. Inc. |
| General Mills Inc. |
| McCormick & Company Inc. |
| Associated British Foods PLC |
| Conagra Brands Inc. |
| Orkla ASA |
| Paulig Group |
| ARYZTA AG |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor anchors cost dynamics across the Global Ethnic Foods Market, where container rate volatility feeds directly into frozen meal landed costs and downstream price differentiation between premium and economy tier positioning. Supply concentration in Thai sauce manufacturing and Korean fermentation facilities amplifies freight exposure, compressing margins for distributors lacking direct supplier relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across frozen ethnic meal procurement, with price differentiation driven by certification tier and volume scale. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant biodegradable packaging SKUs from conventional formats. Cost compression in economy tiers is intensifying because co-manufacturing networks fragment production ownership and redistribute margin capture. Quick-service restaurant chains exhibit highest price sensitivity, while premium supermarket buyers in Germany and the Netherlands absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Extended payment terms from South Korean and Thai exporters to European retail chains are financing working capital cycles across the frozen dim sum and sauce categories. Geographic supply concentrates in Thailand, South Korea, and India, with raw material dependencies on Vietnamese rice, Indian turmeric, and Indonesian palm oil. Single-source vulnerability in koji starter culture supply creates bottleneck risk for clean-label umami base production. Distribution runs through direct sourcing relationships between supermarket buyers and Malaysian or Indonesian producers, eliminating traditional import-distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the Global Ethnic Foods Market as diaspora community demand and urban millennial palate diversification create niche entry points for specialized regional brands. Demand-side shift toward authentic convenience formats rewards agile recipe developers over capital-intensive processors.
For Market Incumbents: Harden control over spice sourcing networks through backward integration into Indian cardamom and Thai chili pepper supply corridors. Deepen fermentation technology moats against precision fermentation startups by accelerating clean-label umami base patent filings. Threat from asset-light licensing models demands preemptive co-manufacturing partnership lock-ups in Gujarat and Maharashtra production clusters. For New Entrants and Emerging Players: Pursue Brazilian retail shelf space as ANVISA harmonization opens previously excluded frozen ethnic meal placement. Target urban middle-class households in São Paulo and Rio de Janeiro through direct-to-consumer platforms bypassing traditional distributor markups. Go-to-market angle centers on subscription meal-kit compatibility for Korean and Japanese convenience formats. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core frozen meal portfolios amid portfolio rationalization pressures. Long-term viability frames around fermentation technology convergence and clean-label preservation systems displacing synthetic additive dependencies. Signal to watch: EFSA novel ingredient approval velocity for traditional ethnic additives previously grandfathered.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Manufacturing Partnership | Asset-light scaling enables regional brands to compete without capital-intensive facility investments. |
| Fermentation Technology Licensing | Clean-label umami base patents differentiate against REACH-restricted synthetic preservative systems. |
| Direct-to-Consumer Platform Launch | Eliminates 15-25 point distributor margins for small-batch Korean and Thai sauce producers. |
| Sustainability Certification Investment | EU Green Deal compliance secures shelf placement in German and Dutch supermarket channels. |
| Spice Sourcing Network Control | Deep turmeric and cardamom supply relationships defend against spot market volatility exposure. |
Methodological Framework
A spread of perspectives from brand managers at multinational food conglomerates, category buyers at German and Dutch supermarket chains, fermentation technology R&D directors, and supply planners at co-manufacturing facilities converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, FSSAI and FDA facility registration databases, and EU ECHA restriction roadmap documentation. Bottom-up demand modeling across product type, ingredient, packaging format, and distribution channel segments triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning preparation intensity, raw material sourcing geography, sustainability certification tier, and channel control structure. CAGRs derived from volume trajectory modeling incorporating urban middle-class consumption patterns in India and Brazil, co-manufacturing capacity expansion rates, and regulatory harmonization timelines. Industry-specific forecast inputs included EU Green Deal packaging mandate compliance cost curves and EFSA novel ingredient approval pipeline velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or rapid ANVISA regulatory acceleration would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
White Fungus Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
North America Hummus Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Almond-Based Spreads Market