
 Low Fat and Low Carb Foods Market | 2026-2036
Low Fat and Low Carb Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat and Low Carb Foods Market Foresight
Registered dietitian shortages in food manufacturing is redrawing how brands staff innovation labs and regulatory affairs teams. Nestle S.A. leverages its global R&D network to sustain reformulation pipelines across multiple low-fat dairy platforms. Danone S.A. anchors its competitive position through specialized expertise in fermented protein alternatives. General Mills competes by controlling grain-based ingredient supply chains that support low-carb pasta substitute development.
Low fat and low carb foods comprise formulated consumer products containing reduced lipid content below standard equivalents and carbohydrate levels typically restricted to support glycemic management or ketogenic protocols, achieved through modified starch systems, fiber enrichment, and alternative protein structuring. These products serve commercial purposes spanning weight management support, metabolic health maintenance, and athletic performance optimization. Snack bars lead volume contribution due to portability and meal-replacement positioning, while dairy alternatives capture expanding margin pools as oat and almond protein extraction technologies mature. Protein shakes represent the fastest-growing structural segment as fitness enthusiasts and diabetics converge on ready-to-drink formats with minimal net carbohydrates.
The FDA governs nutrient content claims through standardized definitions for low-fat and reduced-carbohydrate labeling, while the EFSA evaluates novel ingredient safety for plant-based alternatives entering European markets. USDA organic certification and non-GMO verification frameworks further shape market access requirements for premium-positioned products. Stakeholders must monitor evolving front-of-pack warning label mandates and sugar taxation proposals that could reclassify reformulated products across multiple jurisdictions.
Market Dynamics
Clean-label reformulation mandates from the FDA and EFSA are forcing manufacturers to rebuild ingredient decks without compromising taste or shelf stability, compressing R&D timelines and elevating formulation costs across all product tiers.
Growth Catalysts
- Ketogenic Protocol Expansion:Fitness enthusiasts and diabetics are converging on ready-to-drink protein formats with minimal net carbohydrates, expanding addressable demand beyond traditional weight management consumers.
- EU Front-of-Pack Labeling:Nutriscore and mandatory nutritional disclosure requirements in Germany and France are accelerating product renovation cycles as brands preempt regulatory reclassification.
- Oat Protein Extraction:Advances in enzymatic processing are unlocking functional protein concentrates from oat biomass, enabling dairy alternatives with improved mouthfeel and emulsion stability.
Market Restraints
- Alternative Sweetener Cost Volatility:Erythritol and allulose supply concentrates in Chinese fermentation facilities, exposing formulators to input price swings and tariff uncertainty.
- Modified Starch Technical Ceiling:Current resistant starch variants degrade under thermal processing above 120°C, limiting clean-label applications in baked low-carb formats.
- USDA Organic Certification Friction:Three-year transition requirements for conventional farmland block rapid scaling of certified low-fat dairy supply chains.
Strategic Opportunities
- Japan Functional Foods Channel:FOSHU (Foods for Specified Health Uses) approval pathways create premium positioning for glycemic-control products in aging urban populations.
- Precision Fermentation Convergence:Integration of microbial protein production with fiber structuring technologies enables next-generation meat and dairy analogues with authentic texture profiles.
- Direct-to-Consumer Subscription Models:Personalized nutrition platforms in the United States are bypassing conventional retail slotting fees, capturing lifetime value through recurring replenishment algorithms.
Industry Challenges
- Registered Dietitian Talent Scarcity:Food manufacturers compete with clinical healthcare systems for formulation and regulatory affairs expertise, inflating compensation premiums in innovation labs.
- Novel Ingredient GRAS Timeline:FDA Generally Recognized as Safe determinations for emerging plant proteins stretch 18-24 months, delaying product launches and freezing capital in pre-revenue pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat and Low Carb Foods Market |
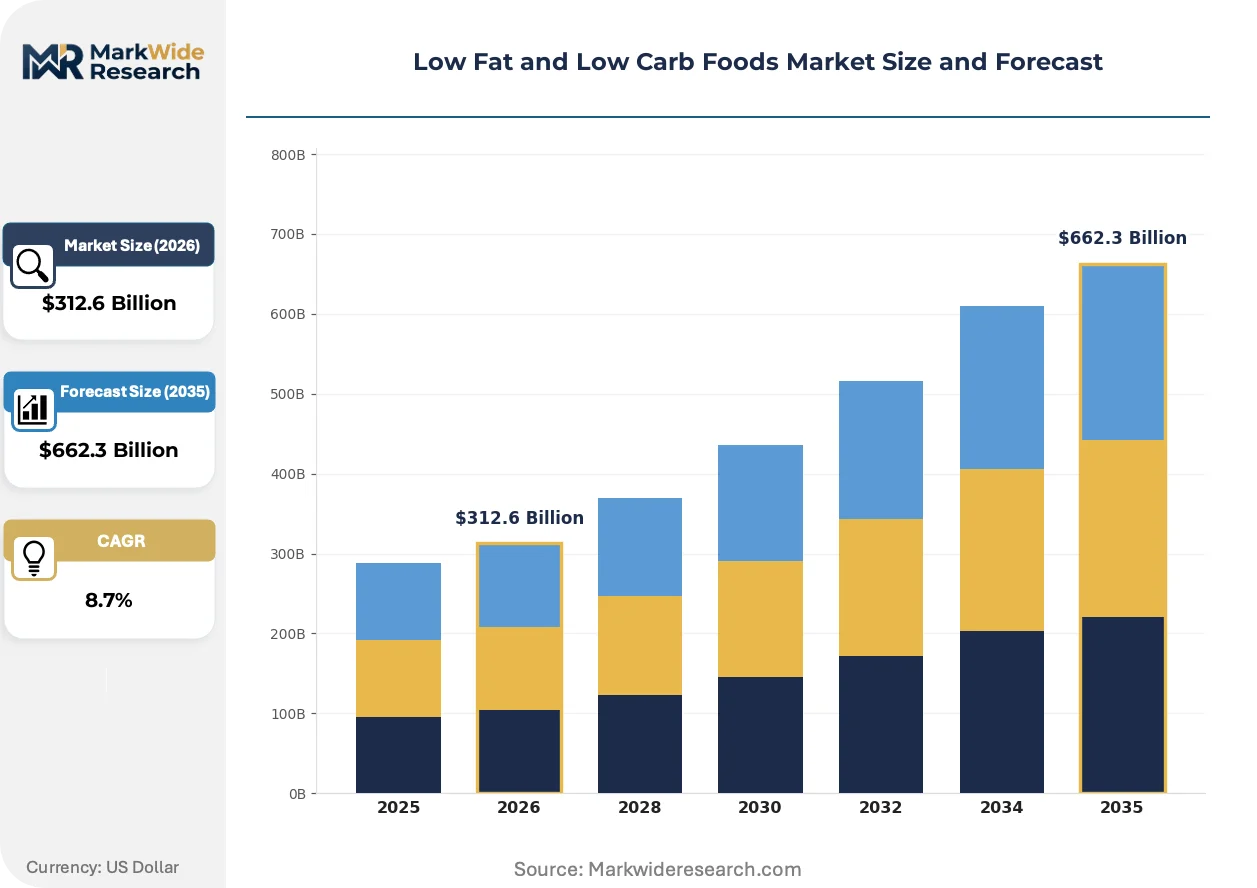
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Dairy Alternatives, Pasta Substitutes, Protein Shakes Ingredient Source: Plant-Based, Animal-Based, Nuts, Seeds Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Consumer Demographics: Fitness Enthusiasts, Weight Watchers, Health-Conscious Individuals, Diabetics |
| Companies Covered | Nestle S.A., Danone S.A., General Mills, Conagra, Atkins Nutritionals, Inc., Quest Nutrition, Cargill Incorporated, PepsiCo, Inc., Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat and Low Carb Foods Market Shifts & Advancements
Enzymatic and microbial processing technologies are deconstructing traditional ingredient hierarchies, while regulatory transparency mandates and shifting procurement behaviors compress competitive moats around established brands.
Precision fermentation is decomposing the conventional protein supply chain by converting sugars directly into functional dairy and egg proteins without agricultural intermediaries. Specialty ingredient divisions at CPG conglomerates are integrating these inputs at pilot scale, while contract manufacturers struggle to retrofit tank infrastructure. The technology is decomposing margin pools previously captured by commodity dairy processors and specialized whey fractionators.
EFSA novel food safety assessments for plant-based alternatives are extending evaluation timelines to 18 months, forcing European entrants to sequence market launches around regulatory windows rather than consumer demand signals. Reformulated products containing enzymatically modified starches face heightened scrutiny for allergenic potential. German and Dutch manufacturers are front-loading toxicology studies to preempt assessment delays.
Health-conscious urban populations in the United States, Germany, and Japan are consolidating purchases through specialized e-commerce platforms that curate products by metabolic protocol rather than brand heritage. Traditional supermarket slotting arrangements lose traction as algorithmic recommendation engines substitute for shelf placement. Subscription-based replenishment models capture highest lifetime value in coastal metropolitan corridors with elevated diabetes prevalence rates.
Low Fat and Low Carb Foods Market Segmentation
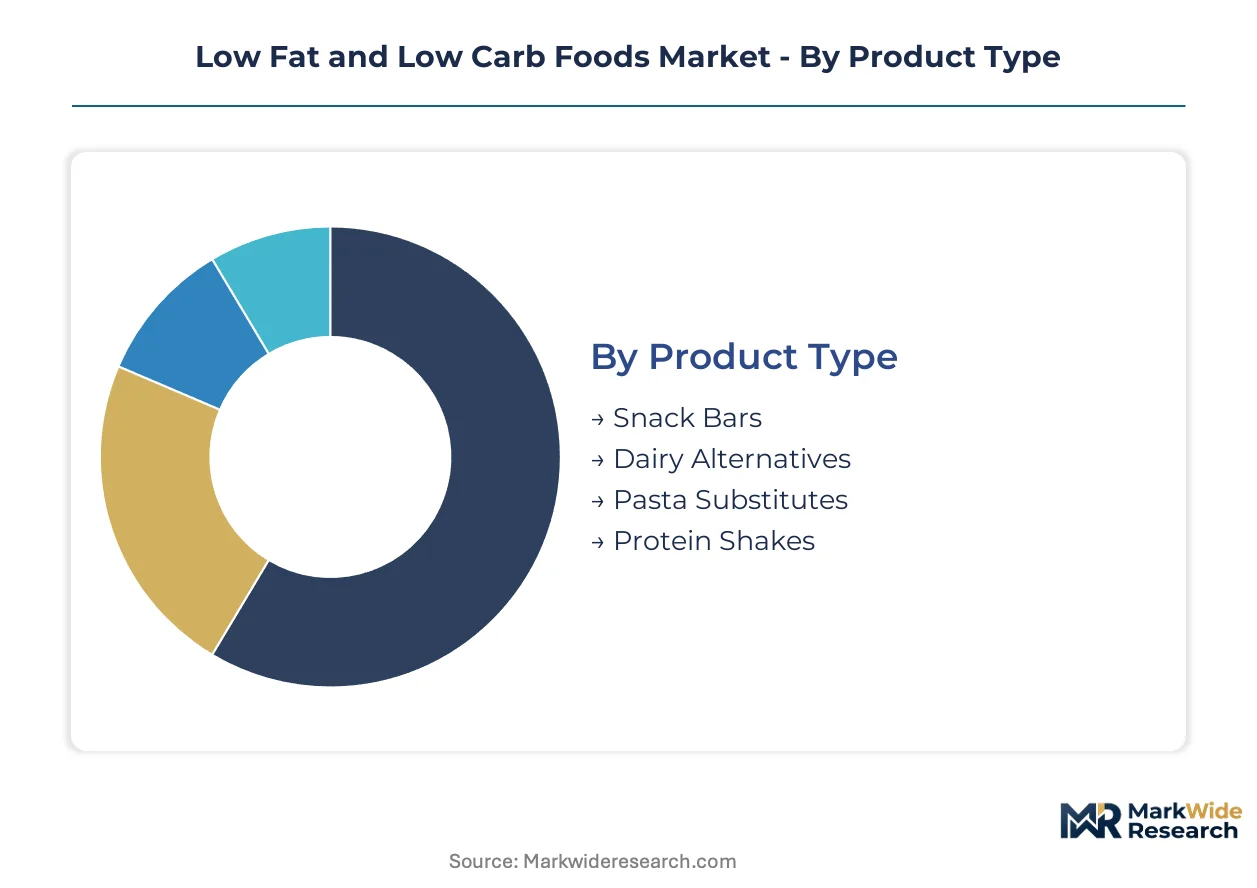
Product differentiation in the low fat and low carb foods market hinges on metabolic protocol alignment and ingredient transparency. Manufacturers compete across four structural dimensions where consumer identity and purchase channel increasingly override traditional brand loyalty.
Product Type:
Domestic production concentrates snack bars and protein shakes in the United States and Germany, while pasta substitutes and dairy alternatives draw heavily on Italian and Nordic export supply chains.
- Snack Bars:Compressed nutrient-dense formulations using modified starch binders and alternative sweeteners achieve portability without refrigeration. Demand clusters in metropolitan United States and Japanese urban corridors where meal replacement protocols dominate commuter behavior.
- Protein Shakes:Ready-to-drink emulsions with sub-5g net carbohydrates per serving rely on microfiltrated whey or oat protein isolates. Fitness enthusiasts and Type 2 diabetics in coastal United States cities drive volume through subscription replenishment models.
- Dairy Alternatives:Oat and almond-based beverages with reduced lipid profiles.
- Pasta Substitutes:Konjac and legume-derived noodles replacing wheat-based carbohydrates.
Snack bars command the established base. The steepest expansion runs through protein shakes.
Ingredient Source:
Cost tiering separates commodity animal proteins from premium-positioned plant extracts, with nuts and seeds occupying a mid-tier functional positioning.
- Plant-Based:Pea, rice, and oat protein concentrates processed through enzymatic fractionation deliver complete amino acid profiles without dairy allergens. German and Dutch manufacturers lead extraction technology, exporting functional isolates to United States formulators facing clean-label pressure from the FDA.
- Animal-Based:Whey and casein fractions from ultrafiltration processes retain superior leucine density for muscle protein synthesis. Supply concentrates in Wisconsin and New Zealand dairy processing cooperatives, with USDA organic certification creating three-year transition friction for expansion.
- Nuts:Almond and cashew bases for alternative dairy and bar applications.
- Seeds:Hemp and pumpkin proteins targeting allergen-free positioning.
Animal-based proteins retain the volume foundation. Plant-based sourcing is climbing the fastest as enzymatic processing matures.
Distribution Channel:
Customer acquisition economics favor direct-to-consumer platforms in diabetes-prevalent United States metros, while European markets sustain specialized retail density.
- Online Retail:Algorithmic curation by metabolic protocol—ketogenic, glycemic control, athletic performance—bypasses conventional slotting fees. Subscription models capture lifetime value in Los Angeles, New York, and Miami corridors where HbA1c screening rates exceed national baselines.
- Supermarkets:Front-of-pack labeling compliance with FDA and EFSA mandates determines shelf placement. German retailers enforce NutriScore thresholds that relegate reformulated products to secondary positioning without renovation.
- Health Food Stores:Staff-guided selection for protocol-specific consumers.
- Specialty Stores:Premium positioning through FOSHU-aligned Japanese functional food channels.
Supermarkets anchor mainstream volume. Online retail is gaining share fastest through personalization algorithms.
Consumer Demographics:
Application intensity varies by metabolic urgency, with diabetics and fitness enthusiasts showing highest per-capita expenditure and subscription retention.
- Fitness Enthusiasts:Protein-centric formulations with leucine-optimized amino acid ratios support resistance training protocols. Demand concentrates in United States coastal metropolitan statistical areas with CrossFit and boutique studio density.
- Weight Watchers:Calorie-controlled portion formats with satiety-enhancing fiber blends. Japanese aging urban populations and United States Midwest suburban markets sustain consistent replenishment cycles.
- Health-Conscious Individuals:Clean-label seekers prioritizing ingredient deck transparency over specific macronutrient targets.
- Diabetics:Clinically validated glycemic index claims with continuous glucose monitoring correlation data.
Weight watchers provide the stable installed base. Fitness enthusiasts are expanding most quickly through social media-fueled protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates in the United States establish the regulatory baseline that European and Japanese authorities subsequently adapt. The United States, Germany, and Japan concentrate the highest per-capita expenditure on reformulated foods. Urban metabolic health crises in these markets accelerate renovation cycles across dairy, snack, and beverage categories.
United States
Fitness enthusiasts in Los Angeles and Miami drive protein shake subscriptions through direct-to-consumer platforms. FDA front-of-pack disclosure requirements compress R&D timelines for reformulated snack bars. Wisconsin dairy processing cooperatives supply ultrafiltrated whey fractions to national formulators facing clean-label pressure.
Germany
Diabetic consumers in Berlin and Hamburg prioritize glycemic-control products with NutriScore A or B ratings. EFSA novel food assessments extend evaluation timelines for oat protein isolates entering European markets. Bavarian enzymatic processing facilities export functional ingredients to United States contract manufacturers.
Japan
Aging urban populations in Tokyo and Osaka sustain demand for FOSHU-approved functional foods targeting metabolic syndrome. METI streamlined approval pathways enable faster market entry for glycemic-control formulations. Kanto region fermentation specialists supply konjac-derived pasta substitutes to domestic retail chains.
France
Health-conscious consumers in Paris and Lyon respond to mandatory nutritional labeling with renovated clean-label portfolios. ANSM evaluates novel ingredient safety for plant-based dairy alternatives entering French distribution. Île-de-France food technology clusters develop precision fermentation capabilities for next-generation protein structuring.
United Kingdom
Weight management consumers in London and Manchester shift purchases toward subscription-curated ketogenic protocols. UK Food Standards Agency enforcement of front-of-pack traffic light labeling accelerates product renovation among incumbent brands. Midlands ingredient suppliers specialize in resistant starch systems for baked low-carb formats.
Low Fat and Low Carb Foods Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational CPG conglomerates controlling reformulation pipelines through captive R&D networks. Mid-sized nutrition specialists compete through metabolic protocol specificity and direct-to-consumer channel capture. Three archetypes dominate: diversified food conglomerates with global dairy platforms, specialized protein nutrition houses with fitness channel expertise, and ingredient technology suppliers with enzymatic processing capabilities. Competitive intensity centers on M&A absorption of fermentation startups and strategic partnerships between CPG brands and precision biotechnology developers.
Among diversified conglomerates, Nestle S.A. and Danone S.A. exemplify the integrated leader archetype through their respective positions in global dairy and fermented protein alternatives. General Mills occupies a position within the grain-based ingredient control tier, anchoring supply chain advantages for low-carb pasta substitute development. These three entities represent distinct competitive vectors: Nestle through R&D network scale, Danone through specialized fermentation expertise, and General Mills through backward integration into grain sourcing.
| Leading Market Players |
|---|
| Nestle S.A. |
| Danone S.A. |
| General Mills |
| Conagra |
| Atkins Nutritionals, Inc. |
| Quest Nutrition |
| Cargill Incorporated |
| PepsiCo, Inc. |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for alternative sweeteners in United States contract manufacturing compress margin buffers when Chinese erythritol fermentation facilities face tariff uncertainty, concentrating pricing power among vertically integrated CPG conglomerates that maintain captive supply relationships.
Pricing Analysis
United States shelf prices for protein shakes run 40-60 percent above German equivalents due to FDA compliance costs and subscription-platform service fees. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-certified Japanese imports from private-label supermarket lines and bulk direct-to-consumer formats. Pricing pressure stems from allulose supply volatility in Shandong province fermentation clusters. Diabetics in coastal metropolitan corridors show lowest price sensitivity; weight watchers in Midwest suburban markets demand economy-tier positioning.
Supply Chain Analysis
China and India anchor alternative sweetener fermentation and enzymatic starch processing, while Wisconsin and New Zealand dairy cooperatives supply ultrafiltrated whey fractions for protein shake emulsions. Formulators draw from oat biomass in Nordic enzymatic facilities, erythritol from Shandong fermentation tanks, and konjac root from Kanto region agricultural processing. Single-source vulnerability concentrates in Chinese allulose production corridors. Distribution runs through direct-to-consumer subscription platforms in diabetes-prevalent United States metros and NutriScore-compliant German retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward algorithmic curation platforms as fitness enthusiasts and diabetics consolidate purchases through metabolic-protocol subscriptions, fragmenting traditional supermarket slotting arrangements.
For Market Incumbents: Compound formulation expertise in fermented protein alternatives with backward integration into oat protein extraction technology to preempt Danone S.A. and Nestle S.A. R&D network advantages. Defend shelf positioning against direct-to-consumer entrants by front-loading toxicology studies for EFSA novel food assessments. Priority lever: captive supply relationships with Bavarian enzymatic processing facilities. For New Entrants and Emerging Players: FOSHU fast-track approval in Japan creates premium positioning for glycemic-control pasta substitutes targeting Tokyo and Osaka aging urban populations. White-space targets include precision fermentation-enabled dairy analogues and ketogenic snack bars for United States CrossFit corridor subscriptions. Go-to-market angle: algorithmic personalization platforms bypassing conventional retail slotting fees. For Investors and Strategic Acquirers: Long-term, this sits as a metabolic health infrastructure play because aging demographics in Japan, Germany, and United States coastal metros sustain structural demand for glycemic-management formulations. Acquisition target archetype: mid-sized enzymatic processing specialists with EFSA pre-submission toxicology portfolios. Signal to watch: FDA GRAS determination timelines for emerging plant proteins as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein production bypasses agricultural intermediaries, decomposing commodity dairy processor margins. |
| EFSA Novel Food Pre-Submission | Front-loaded toxicology studies compress 18-month assessment windows for oat protein isolates entering European markets. |
| Direct-to-Consumer Platform Launch | Subscription algorithms capture lifetime value in Los Angeles and Miami corridors where HbA1c screening rates exceed baselines. |
| Backward Integration into Oat Processing | Captive enzymatic fractionation secures functional protein concentrates against Nordic export supply chain volatility. |
| FOSHU Certification Pathway | METI streamlined approval enables premium positioning for glycemic-control products in Tokyo functional foods channel. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation scientists at CPG innovation labs, regulatory affairs directors navigating FDA GRAS pathways, procurement leads at contract manufacturing organizations, and category buyers at German retailers enforcing NutriScore thresholds. Secondary validation drew from FDA nutrient content claim filings, EFSA novel food assessment registers, USDA organic certification databases, and customs records tracking erythritol and allulose import volumes. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, analytical frameworks modeled volume and value outputs through four segmentation dimensions: product type alignment with metabolic protocol, ingredient source cost tiering, distribution channel customer acquisition economics, and consumer demographic application intensity. CAGRs were derived from regression analysis against diabetes prevalence rates, fitness club density, and regulatory renovation cycle frequencies. Industry-specific forecast inputs included enzymatic processing capacity expansion timelines and FOSHU approval velocity metrics.
Decision-makers should treat outputs as directional under base assumptions of sustained ketogenic protocol adoption and stable FDA labeling mandates; material deviation in alternative sweetener tariff regimes or EFSA assessment timelines would warrant model refresh. Recalibration cycles align with material shifts in precision fermentation commercialization rates and front-of-pack labeling mandate expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Brahmi Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Cultures Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Zhacai Market
Specialty Foods
Poke Food Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Asia Pacific Cat Food Market