
 Low Calorie Chocolate Desserts Market | 2026-2036
Low Calorie Chocolate Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Chocolate Desserts Market Analytics
The EU Green Deal's Farm to Fork strategy is decoupling calorie-reduced confectionery from conventional sugar-heavy portfolios across European retail. Nestle S.A. leverages its plant-based R&D infrastructure to sustain reformulation pipelines for cocoa-dominant desserts with alternative sweetener systems. Mondelez International anchors its competitive position through scaled procurement of responsibly sourced cocoa beans integrated into reduced-calorie product lines. Lindt & Sprungli differentiates via premium positioning in health food store channels where consumers accept higher price points for artisanal low-calorie formulations.
Low calorie chocolate desserts comprise cocoa-based confectionery and bakery items reformulated with non-nutritive sweeteners, sugar alcohols, or fiber-enhanced bases to achieve caloric reductions of 30-50% versus standard equivalents, primarily serving weight management and glycemic control objectives in retail and foodservice channels. Chocolate mousse and chocolate pudding segments lead volume contribution due to their adaptability to aeration and hydrocolloid stabilization techniques that preserve mouthfeel without sucrose load. The online retail distribution channel represents the fastest-growing structural pocket as direct-to-consumer brands bypass traditional supermarket slotting fees and capture subscription-based repeat purchases from fitness enthusiasts and diabetic consumers.
FDA nutrition labeling requirements and the EU's Nutri-Score front-of-pack system jointly constrain permissible health claims while mandating transparent calorie and added sugar disclosures that reshape product development priorities for cross-Atlantic manufacturers. Health Canada and the UK's Food Standards Agency enforce parallel compositional standards that limit artificial sweetener concentrations and require allergen labeling for nut milk derivatives increasingly prevalent in vegan-positioned desserts. Stakeholders must monitor evolving definitions of "low calorie" across jurisdictions where threshold adjustments could force rapid reformulation cycles or delist existing SKUs from compliant product assortments.
Market Dynamics
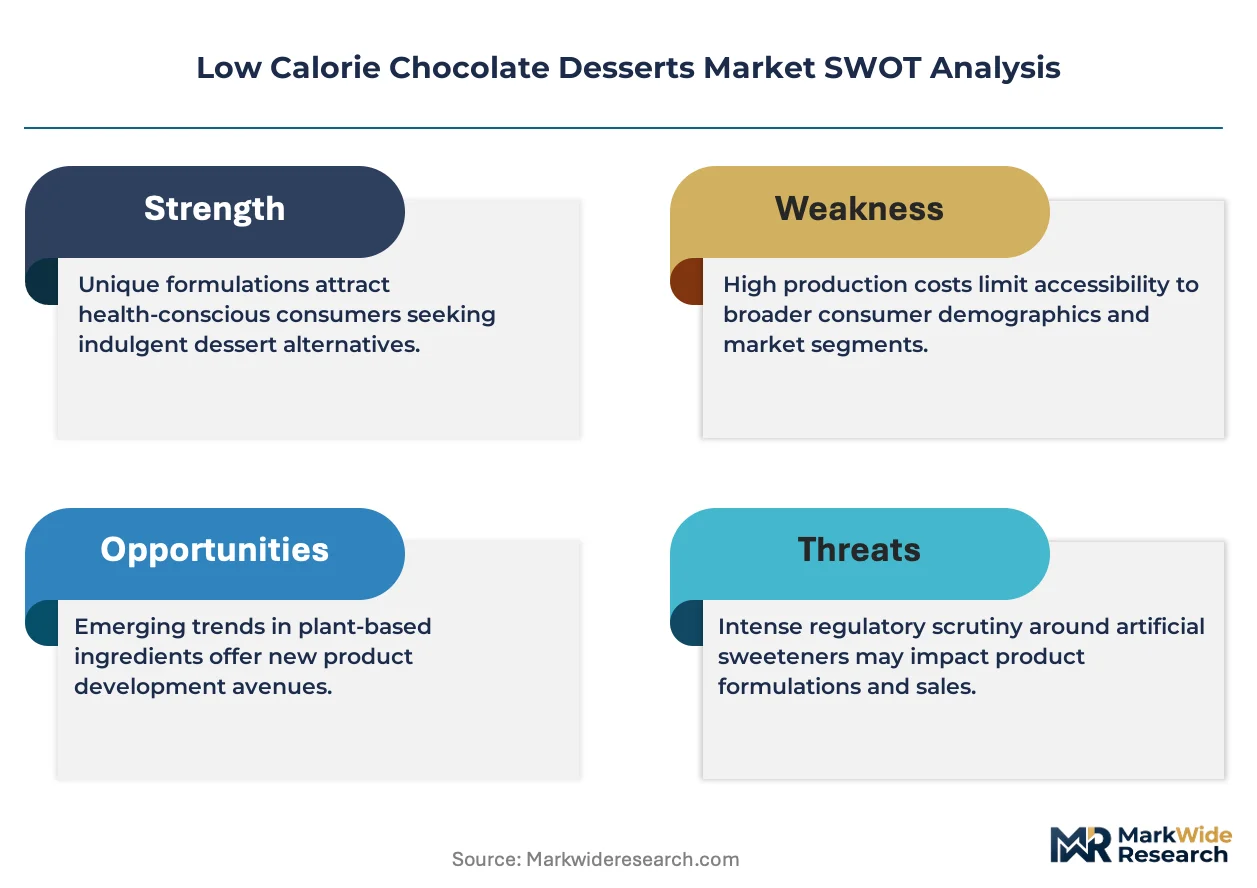
Clean-label reformulation mandates from the FDA and EU's Nutri-Score system are forcing manufacturers to rebuild cocoa-dominant portfolios around alternative sweetener architectures rather than incremental calorie reductions.
Growth Catalysts
- FDA Calorie Disclosure Mandates:Front-of-pack transparency requirements compel legacy brands to accelerate reduced-calorie line extensions, expanding shelf space for reformulated desserts in US premium supermarket channels.
- Gen Z Wellness Demographics:Urban consumers in Germany and the United Kingdom prioritize glycemic control and weight management, driving repeat subscription purchases through direct-to-consumer platforms.
- Aeration Technologies:Hydrocolloid stabilization and controlled aeration methods preserve mouthfeel in chocolate mousse formulations without sucrose load, enabling 30-50% calorie reduction targets.
Market Restraints
- Alternative Sweetener Cost Volatility:Erythritol and allulose prices fluctuate with corn supply chain disruptions, compressing margins on premium-positioned low-calorie lines.
- Cocoa Bean Supply Concentration:West African sourcing dependencies expose manufacturers to climate-induced harvest variability and ethical certification compliance costs.
- EU Additive Concentration Limits:EFSA thresholds for polyol consumption constrain single-serving portion sizes, limiting product format innovation in European markets.
Strategic Opportunities
- Underpenetrated Diabetic Consumer Segments:Type 2 diabetes prevalence in the United States creates unmet demand for clinically positioned low-glycemic chocolate desserts with explicit glycemic index labeling.
- Vegan Positioning Convergence:Nut milk derivatives and oat-based cocoa formulations capture lactose-intolerant and plant-based dietary adopters in UK health food store channels.
- EU Green Deal Procurement Incentives:Farm to Fork sustainability criteria reward responsibly sourced cocoa integration, creating competitive differentiation for compliant reformulation pipelines.
Industry Challenges
- Cross-Jurisdictional Labeling Complexity:Divergent "low calorie" threshold definitions between Health Canada, the FDA, and the UK's Food Standards Agency force SKU fragmentation and regional formulation variants.
- Reformulation R&D Talent Scarcity:Shortages of food scientists specializing in alternative sweetener synergy and flavor masking delay clean-label product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Chocolate Desserts Market |
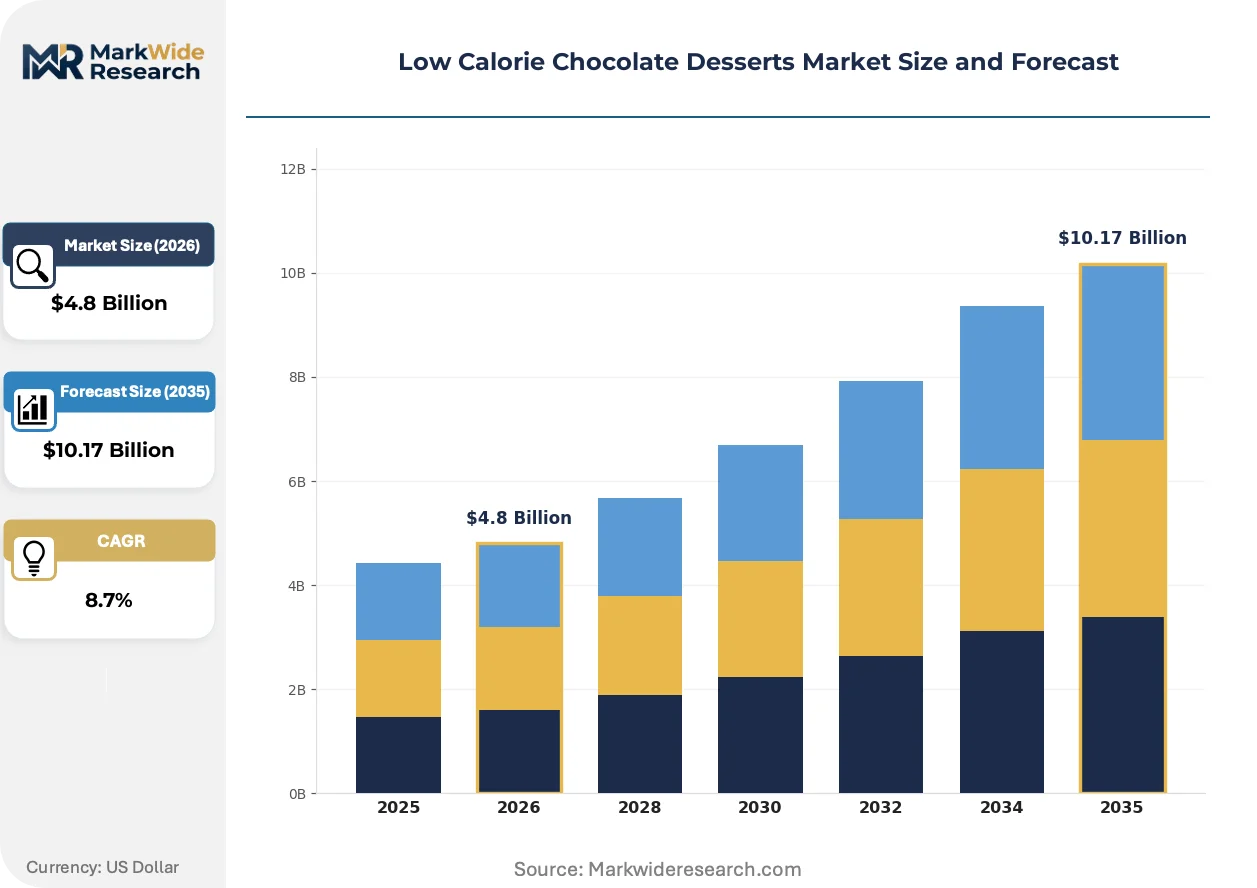
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Mousse, Chocolate Pudding, Chocolate Bars, Chocolate Cake Ingredient Type: Artificial Sweeteners, Cocoa Powder, Nut Milks, Casein Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Consumer Type: Health-Conscious Individuals, Dieters, Fitness Enthusiasts, Vegans |
| Companies Covered | Nestle S.A., The Hershey Company, Barry-Callebaut AG, Mondelez International, Ferrero SpA, Lindt & Sprungli, Danone S.A., Unilever, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Chocolate Desserts Market Evolving Landscape
Reformulation science is migrating from sugar substitution toward structural reconstruction of cocoa matrices, with texture engineering and fermentation-derived flavor compounds displacing conventional additive approaches.
Fermentation-derived cocoa enhancers is expanding into low-calorie chocolate dessert manufacturing as biotech suppliers isolate flavor-active peptides that amplify perceived sweetness without caloric contribution. Functional food brands in Germany and the United Kingdom are piloting these ingredients at commercial scale. This biotechnology is expanding into premium private-label contracts previously reserved for artisanal confectionery, compressing the innovation cycle between laboratory validation and retail placement.
The EU's Nutri-Score front-of-pack labeling system now penalizes added sugar density in chocolate confectionery, compelling manufacturers to restructure entire dessert portfolios around fiber-enhanced bases and sugar alcohol blends. Industrial consequence includes accelerated delisting of conventional high-sugar SKUs from major French and Belgian retail banners. Chocolate pudding and mousse segments are responding fastest, leveraging existing hydrocolloid infrastructure to meet B-grade scoring thresholds.
Subscription-based replenishment models are displacing impulse supermarket purchases among fitness enthusiasts and diabetic consumers seeking consistent portion-controlled inventory. Direct-to-consumer brands bypass traditional slotting fee structures while capturing lifetime value through automated reorder algorithms. This channel migration is most visible in United States metropolitan markets where warehouse logistics density supports cold-chain dessert delivery at competitive unit economics.
Low Calorie Chocolate Desserts Market Segmentation
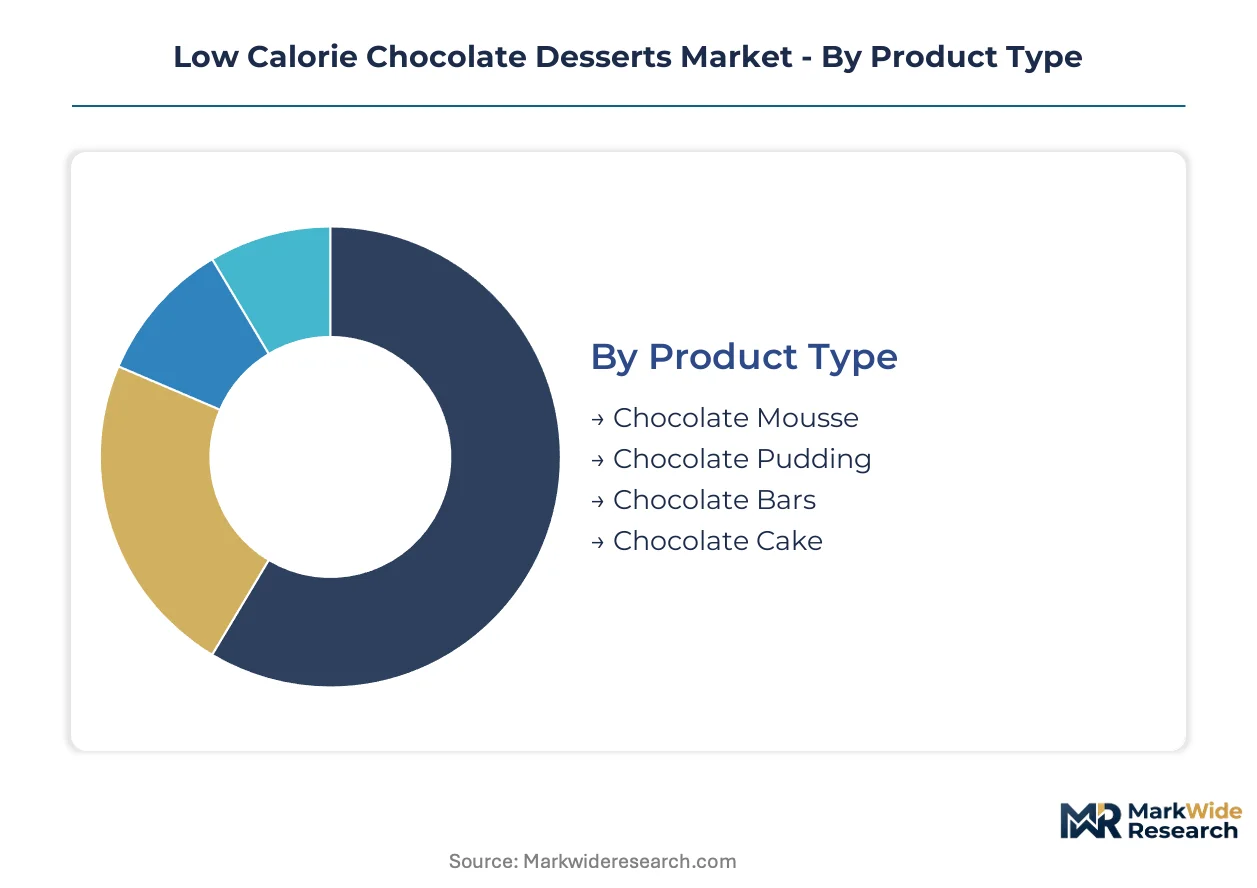
Segmentation in low calorie chocolate desserts determines regulatory exposure, margin structure, and channel strategy. Product format dictates aeration technology requirements, while ingredient sourcing triggers FDA, EFSA, and Health Canada compliance obligations that reshape portfolio economics.
Product Type:
Certification burdens cluster around hydrocolloid stabilization systems and aeration methods, with FDA GRAS determinations for alternative sweetener architectures varying by product density and moisture content.
- Chocolate Mousse:Air-structured cocoa matrices rely on controlled aeration and hydrocolloid stabilization to achieve 30-50% calorie reduction without sucrose. Demand concentrates in premium supermarket channels across Germany and the United Kingdom, where Nutri-Score B-grade positioning commands shelf placement.
- Chocolate Pudding:Gelatin and starch-thickened formulations accommodate fiber-enhanced bases more readily than aerated alternatives. United States metropolitan markets show concentration through direct-to-consumer subscription platforms serving diabetic consumer segments.
- Chocolate Bars:Solid-phase confectionery requires alternative fat systems and sugar alcohol blends to maintain snap and mouthfeel.
- Chocolate Cake:Bakery applications face EFSA polyol concentration thresholds that constrain single-serving portion sizes in European markets.
Chocolate Mousse sits at the top of the volume ranking, with Chocolate Pudding climbing the fastest.
Ingredient Type:
Cost tiers separate commodity cocoa inputs from premium-positioned alternative sweetener systems and plant-derived proteins, with procurement patterns diverging between mass-market and clinical-positioned formulations.
- Artificial Sweeteners:Sucralose and aspartame formulations face declining acceptance in clean-label channels despite lower unit costs. Health Canada and FDA additive concentration limits force regional formulation variants.
- Cocoa Powder:Responsibly sourced cocoa carries EU Green Deal procurement incentives that reward Farm to Fork compliance with retail placement advantages.
- Nut Milks:Almond and oat derivatives capture vegan-positioned demand in UK health food store channels.
- Casein:Dairy protein isolates retain functional advantages in texture engineering despite lactose intolerance constraints.
Cocoa Powder dominates procurement volumes, with Nut Milks gaining share fastest among plant-based dietary adopters.
Distribution Channel:
Margin structures diverge sharply between slotting-fee-burdened retail and subscription-based direct channels, with customer lifetime value economics favoring automated replenishment models.
- Online Retail:Direct-to-consumer platforms bypass traditional supermarket slotting fees while capturing subscription-based repeat purchases. United States warehouse logistics density supports cold-chain dessert delivery at competitive unit economics.
- Supermarkets:Premium banners in Germany and the United Kingdom allocate expanded shelf space to reformulated desserts responding to Nutri-Score mandates.
- Health Food Stores:Artisanal low-calorie formulations command higher price points where consumers prioritize ingredient transparency.
- Specialty Shops:Boutique confectionery channels emphasize premium positioning and limited-batch production.
Supermarkets retain the largest volume position, with Online Retail expanding most quickly through fitness enthusiast and diabetic consumer segments.
Consumer Type:
Application intensity varies by dietary objective, with glycemic control requirements driving clinical-grade formulation standards distinct from general wellness positioning.
- Health-Conscious Individuals:Broad wellness demographics prioritize clean-label claims and transparent calorie disclosure over specific clinical outcomes.
- Dieters:Portion-controlled formats and explicit calorie reduction claims align with weight management program requirements.
- Fitness Enthusiasts:High-protein, low-glycemic formulations concentrate in subscription channels with automated reorder algorithms.
- Vegans:Plant-based certification requirements intersect with low-calorie positioning in UK and German metropolitan markets.
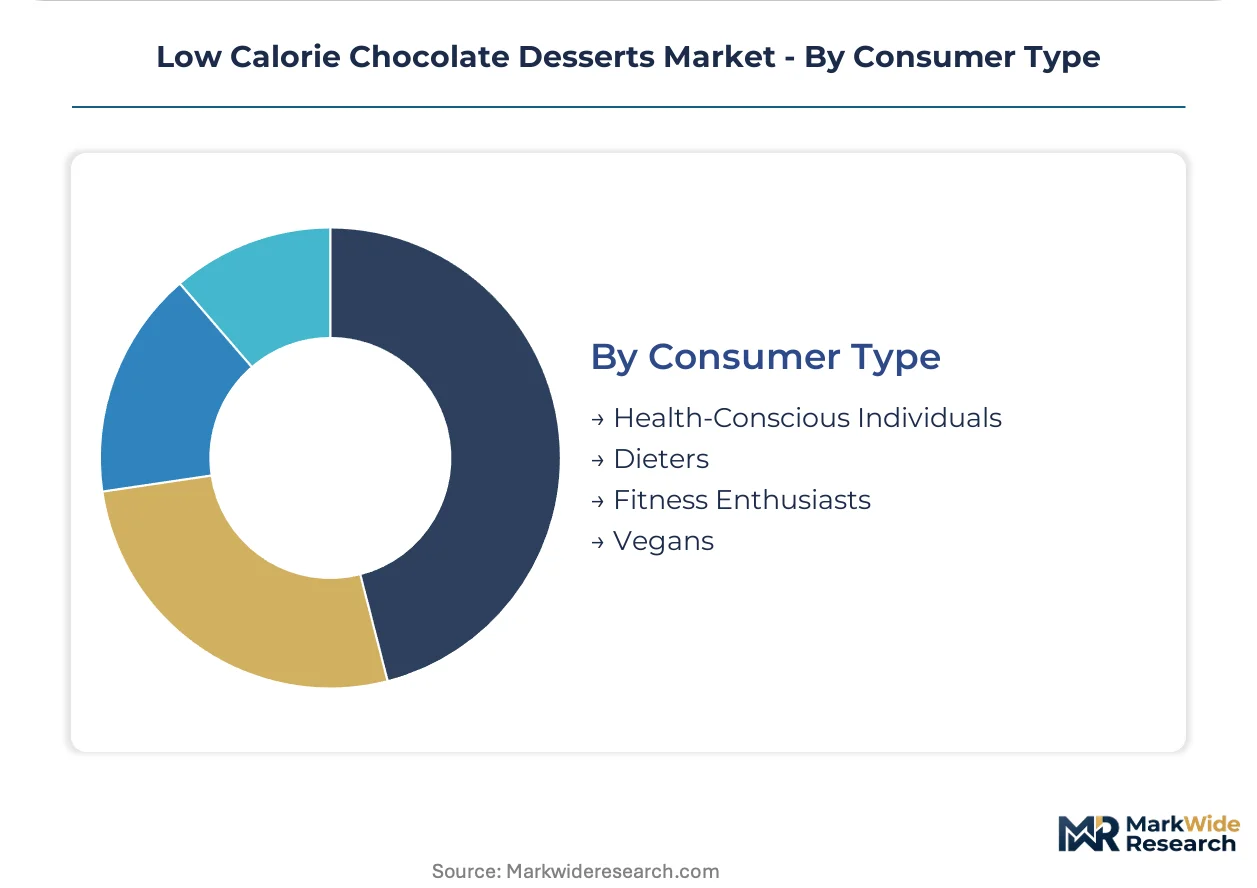
Health-Conscious Individuals represent the largest addressable base, with Fitness Enthusiasts showing the steepest expansion trajectory through direct-to-consumer adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists specializing in alternative sweetener formulation cluster in metropolitan R&D hubs across Germany, the United Kingdom, and the United States, anchoring regional innovation capacity for clean-label dessert development.
United States
Fitness enthusiasts and diabetic consumers in New York, Los Angeles, and Chicago drive subscription-based replenishment through direct-to-consumer platforms. FDA front-of-pack calorie disclosure mandates compel legacy brands to accelerate reduced-calorie line extensions. Warehouse logistics density in the Dallas-Fort Worth metroplex supports cold-chain dessert delivery at competitive unit economics.
Germany
Urban wellness demographics in Berlin, Munich, and Hamburg prioritize glycemic control and weight management, expanding adoption of Nutri-Score B-grade positioned desserts. EFSA polyol concentration thresholds constrain single-serving portion sizes, forcing format innovation. The Stuttgart industrial corridor hosts fermentation-derived cocoa enhancer pilots at commercial scale.
United Kingdom
Vegan-positioned demand concentrates in London, Manchester, and Birmingham health food store channels where consumers accept premium price points for artisanal formulations. The Food Standards Agency enforces allergen labeling requirements for nut milk derivatives prevalent in plant-based desserts. Cambridge-based biotech suppliers isolate flavor-active peptides for low-calorie applications.
France
EU Green Deal Farm to Fork procurement incentives reward responsibly sourced cocoa integration in Paris, Lyon, and Marseille retail banners. Major French supermarkets delist conventional high-sugar SKUs, accelerating portfolio restructuring. The Bordeaux-Toulouse corridor specializes in fiber-enhanced chocolate pudding formulations meeting B-grade Nutri-Score thresholds.
Switzerland
Premium artisanal positioning anchors demand in Zurich, Geneva, and Basel specialty confectionery channels. Swissmedic compositional standards intersect with EU additive regulations for cross-border product development. The Lausanne cluster concentrates hydrocolloid stabilization R&D for aerated cocoa matrices.
Low Calorie Chocolate Desserts Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the low calorie chocolate desserts landscape. Multinational conglomerates with integrated cocoa procurement and plant-based R&D infrastructure dominate shelf placement in regulated European markets. Three strategic archetypes emerge: diversified nutrition conglomerates leveraging cross-category reformulation expertise, premium chocolatiers occupying health food store channels, and direct-to-consumer specialists capturing subscription economics. Competitive intensity centers on clean-label certification acquisition and alternative sweetener supply chain security.
Within the diversified conglomerate tier, Nestle S.A. and Mondelez International exemplify scaled players with global procurement networks and regulatory compliance capabilities across FDA, EFSA, and Health Canada jurisdictions. Lindt & Sprungli occupies a premium-tier position representing artisanal positioning strategies in European health food retail. These three companies anchor the competitive structure, with Nestle and Mondelez exemplifying volume-driven reformulation pipelines and Lindt representing margin-focused specialty positioning.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Hershey Company |
| Barry-Callebaut AG |
| Mondelez International |
| Ferrero SpA |
| Lindt & Sprungli |
| Danone S.A. |
| Unilever |
| Kraft Heinz |
| Others |
Value Network & Pricing Analysis
Food scientists specializing in alternative sweetener formulation cluster in metropolitan R&D hubs across Germany, the United Kingdom, and the United States, with labor-cost differentials between Stuttgart and Cambridge widening the spread between premium artisanal tiers and mass-market economy lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Lindt-positioned artisanal formulations from Mondelez-scale mid-tier lines and private-label economy SKUs. Price differentiation hinges on Nutri-Score certification grade and responsible cocoa sourcing transparency. Cost compression in the standard tier intensifies because erythritol and allulose price volatility compresses reformulation margins. Diabetic consumers in direct-to-consumer channels show least price sensitivity, while supermarket bulk buyers in German metropolitan markets exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with West African cocoa bean procurement, where Côte d'Ivoire and Ghana supply concentration exposes manufacturers to climate-induced harvest variability. Raw material dependencies extend to corn-derived erythritol, Malaysian palm oil alternatives, and hydrocolloid stabilizers from Danish biotech suppliers. Tariff exposure on alternative sweetener imports from China amplifies cost uncertainty for European reformulation pipelines. Distribution runs through cold-chain logistics networks anchored in Dallas-Fort Worth and Rotterdam port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in low calorie chocolate desserts rests on fermentation-derived cocoa enhancer cost curves flattening and premium-tier Nutri-Score A-grade positioning capturing shelf-space premiums.
For Market Incumbents: Cement control over alternative sweetener supply through backward integration into allulose fermentation capacity or long-term offtake agreements with biotech suppliers. Defend against direct-to-consumer subscription specialists by acquiring automated replenishment platform capabilities. Prioritize EFSA-compliant polyol concentration formulations to preserve European market access. For New Entrants and Emerging Players: Enter via underpenetrated Type 2 diabetic consumer segments in United States metropolitan markets where clinical-grade glycemic index labeling commands subscription loyalty. Target fitness enthusiast channels with high-protein, low-glycemic mousse formats. Deploy automated reorder algorithms to capture lifetime value economics unavailable to slotting-fee-burdened retail competitors. For Investors and Strategic Acquirers: Nutrition conglomerates with cross-category reformulation expertise are the most active acquirer in this space, seeking clean-label certification capabilities and alternative sweetener R&D talent. Acquisition targets include fermentation-derived flavor peptide specialists and direct-to-consumer cold-chain logistics platforms. Watch for FDA threshold adjustments on "low calorie" definitions as inflection indicators forcing rapid SKU rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | Nestle and Mondelez leverage plant-based R&D infrastructure to accelerate Nutri-Score compliant dessert launches. |
| Direct-to-Consumer Subscription Launch | Cold-chain logistics density in Dallas-Fort Worth enables automated replenishment capturing diabetic consumer lifetime value. |
| Fermentation-Derived Cocoa Enhancer Scale-Up | Cambridge and Stuttgart biotech clusters isolate flavor-active peptides amplifying perceived sweetness without caloric contribution. |
| Responsibly Sourced Cocoa Integration | EU Green Deal Farm to Fork procurement incentives reward compliant manufacturers with French and Belgian retail placement. |
| Alternative Sweetener Supply Security | Long-term offtake agreements with corn-derived erythritol and allulose producers hedge against commodity price volatility. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with food science R&D directors, supermarket category buyers, direct-to-consumer brand operators, and alternative sweetener procurement leads. Secondary validation draws from FDA GRAS determinations, EFSA additive concentration databases, EU Nutri-Score implementation reports, and Nielsen retail audit data. Bottom-up segment sizing triangulates against top-down category value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions model product format, ingredient architecture, distribution channel, and consumer dietary objective. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs include alternative sweetener cost curves, cocoa bean harvest projections, and subscription platform penetration rates.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time alternative sweetener spot pricing and private-label contract terms introduce uncertainty bands around margin projections. Forecasts reflect assumptions on clean-label threshold stability and cold-chain logistics cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Natto Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
North America Hummus Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Goldenseal Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Cultures Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Middle East and Africa Free-From Food Market