
 Food Flavors Market | 2026-2036
Food Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Food Flavors Market Intelligence
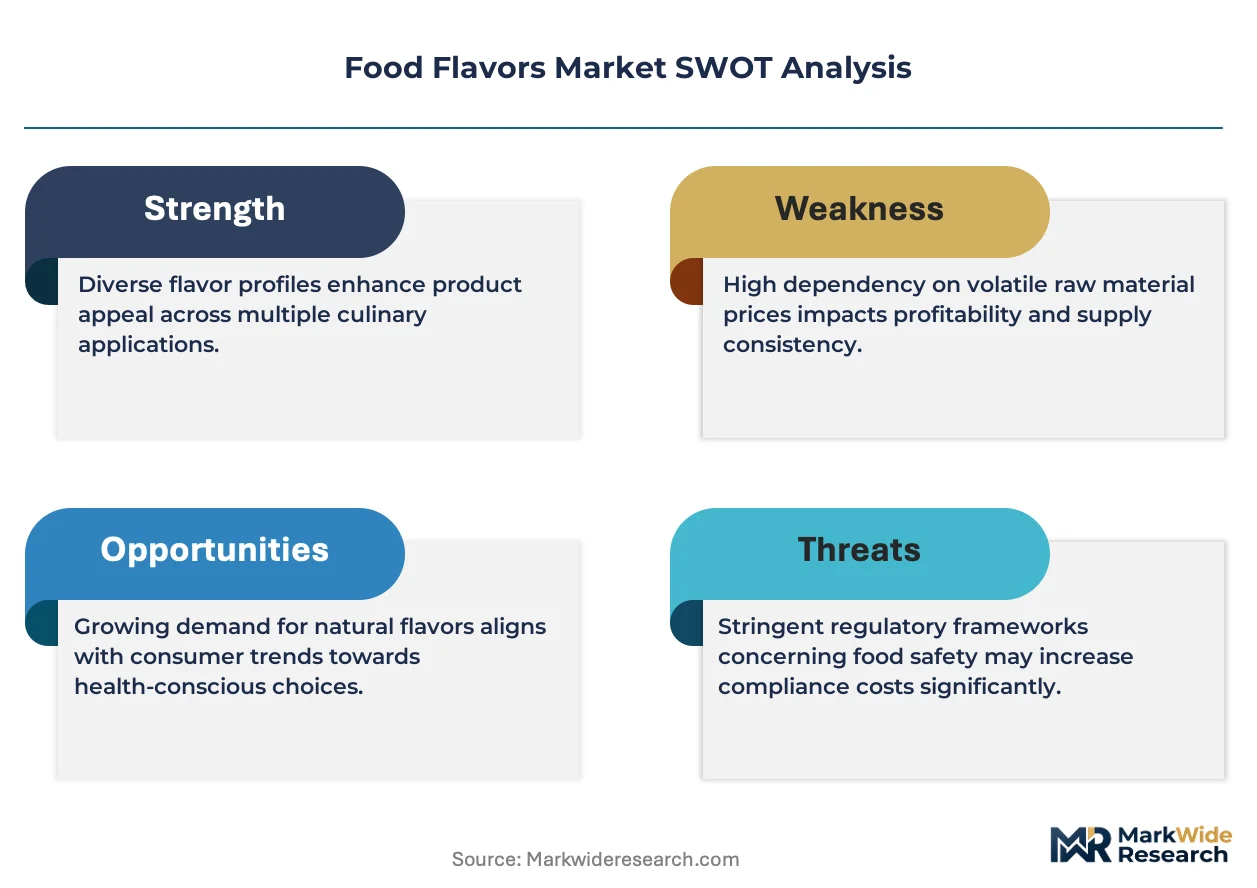
The career path for traditional flavor chemists is collapsing under the weight of data-driven formulation tools and AI-powered discovery platforms. Givaudan leverages artificial intelligence to accelerate new molecule discovery and predict consumer preferences. International Flavors & Fragrances sustains its market position through a vast portfolio of natural and synthetic compounds. Kerry Group differentiates by integrating its flavor systems with its broader nutritional and functional ingredient offerings.
Food flavors are concentrated chemical preparations used to impart or modify the taste and aroma of consumer products. These formulations contain compounds like esters and terpenes, often created through enzymatic conversion to achieve specific sensory profiles. A structural shift towards natural flavors is evident, driven by consumer preferences in the high-volume beverages and savory snacks applications. While liquid forms are standard, encapsulated flavors command premium pricing for their controlled-release properties in bakery products.
Market access and product formulation are governed by a complex web of regulations from bodies like the US FDA, the European Union's EFSA, and China's SAMR. These agencies define criteria for "natural" labeling and enforce strict allergen declaration rules, directly influencing ingredient sourcing and R&D pipelines. Navigating the divergent consumer expectations and regulatory standards for clean label ingredients between geographies remains a central strategic challenge.
Market Dynamics
The rapid convergence of consumer demand for clean label products and stricter regulatory definitions for natural ingredients is the central force shaping the food flavors market. This pressure compels innovation away from synthetic compounds toward more complex, naturally derived formulations.
Growth Catalysts
- Dairy Alternative Expansion:The booming plant-based dairy sector requires sophisticated masking agents and authentic flavor profiles to mimic traditional dairy tastes, creating a specific, high-value demand stream for flavor houses.
- Clean Label Mandates:Stricter labeling requirements from regulators like the US FDA and Europe's EFSA are pushing rapid innovation in natural extraction and enzymatic conversion methods for flavor development.
- Food Processing Hubs:New product development activity in emerging food processing centers within key markets like India and Brazil localizes demand for regionally-specific flavor profiles.
Market Restraints
- Input Cost Volatility:The price and availability of natural raw materials, such as citrus oils and vanilla, are subject to extreme climate-related and geopolitical volatility, impacting formulation costs and supply stability.
- Divergent Regulations:Navigating the conflicting definitions of "natural" flavorings between the US FDA, the EU's EFSA, and China's SAMR creates significant reformulation and compliance burdens for exporters.
- Technical Instability:Many natural flavors exhibit lower stability under thermal stress during processing compared to synthetics, limiting their application in certain bakery and confectionery products without encapsulation.
Strategic Opportunities
- AI-Powered Formulation:Leveraging artificial intelligence platforms to accelerate the discovery of novel flavor molecules and predict consumer sensory preferences offers a path to faster, more targeted R&D cycles.
- Encapsulation for Functional Foods:Developing advanced encapsulated flavors for controlled release in functional beverages and nutraceuticals addresses the need to mask off-notes from active ingredients like proteins and vitamins.
- Savory Profile Expansion:A significant opportunity exists to develop and market complex savory and umami flavor systems tailored to local cuisines in rapidly urbanizing Southeast Asian markets.
Industry Challenges
- Talent Integration Gap:A critical challenge is the scarcity of flavorists who possess both traditional sensory expertise and the data science skills required to operate AI-driven discovery platforms effectively.
- Intellectual Property Ambiguity:Securing and defending intellectual property for complex natural flavor formulations, often created via enzymatic conversion, is more difficult than for single synthetic molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Flavors Market |
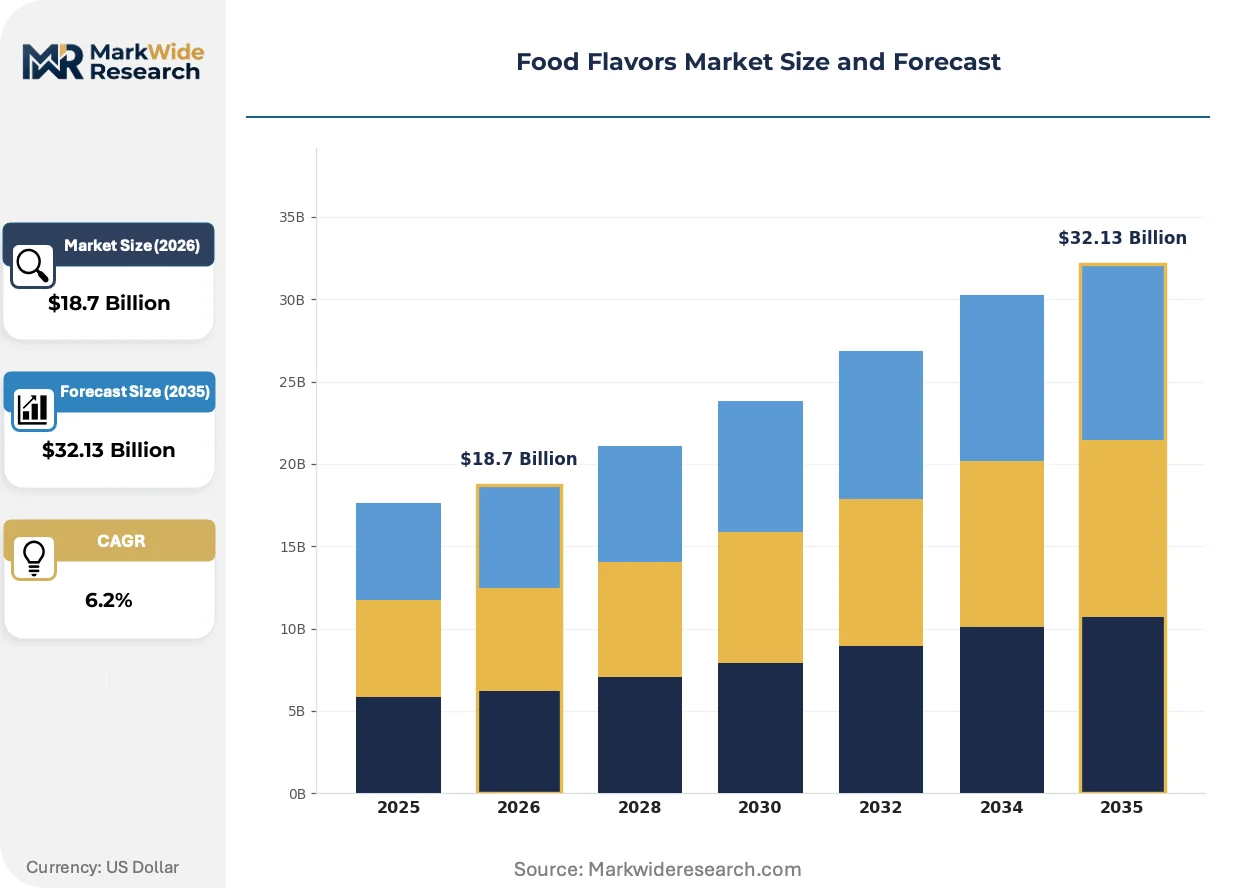
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Nature-Identical Flavors, Organic Flavors, Clean Label Flavors Application: Beverages, Bakery Products, Confectionery, Dairy Alternatives, Savory Snacks End User: Food Manufacturers, Flavor Houses, Ingredient Suppliers, Food Service Providers, Artisan Producers Form: Liquid, Powder, Emulsions, Oleoresins, Encapsulated Flavors |
| Companies Covered | Givaudan, DSM-Firmenich, International Flavors & Fragrances, Symrise, Sensient Technologies, Kerry Group, Archer Daniels Midland, Mane, Robertet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Flavors Market Strategic Shifts & Innovations
The industry's creative core is shifting from the individual flavor chemist's bench to algorithm-driven discovery platforms. This technological pivot is occurring alongside a fundamental re-evaluation of what constitutes an acceptable ingredient by both regulators and consumers.
AI-powered discovery platforms analyze vast datasets to predict novel flavor molecules and their likely consumer reception. Major flavor houses are rapidly adopting these tools for developing new beverage and savory snack profiles. This data-driven approach is supplanting the slower, more intuitive process of traditional bench chemistry, compressing new product development timelines.
Regulatory bodies, including the US FDA and the European Union's EFSA, are enforcing stricter criteria for "natural" and "clean label" product claims. This is forcing a structural shift in R&D investment toward natural sourcing, extraction, and bioconversion technologies. The high-volume beverages and dairy alternatives segments are most affected, often requiring complete product reformulation to maintain compliance and consumer trust.
Food and beverage manufacturers increasingly demand integrated systems that combine flavor with functional and nutritional ingredients. This consultative, solution-oriented sales model disrupts the transactional procurement of standalone flavor compounds. The shift is most pronounced in the functional food and savory snack categories, where sensory profiles must be optimized alongside texture and health attributes.
Food Flavors Market Segmentation
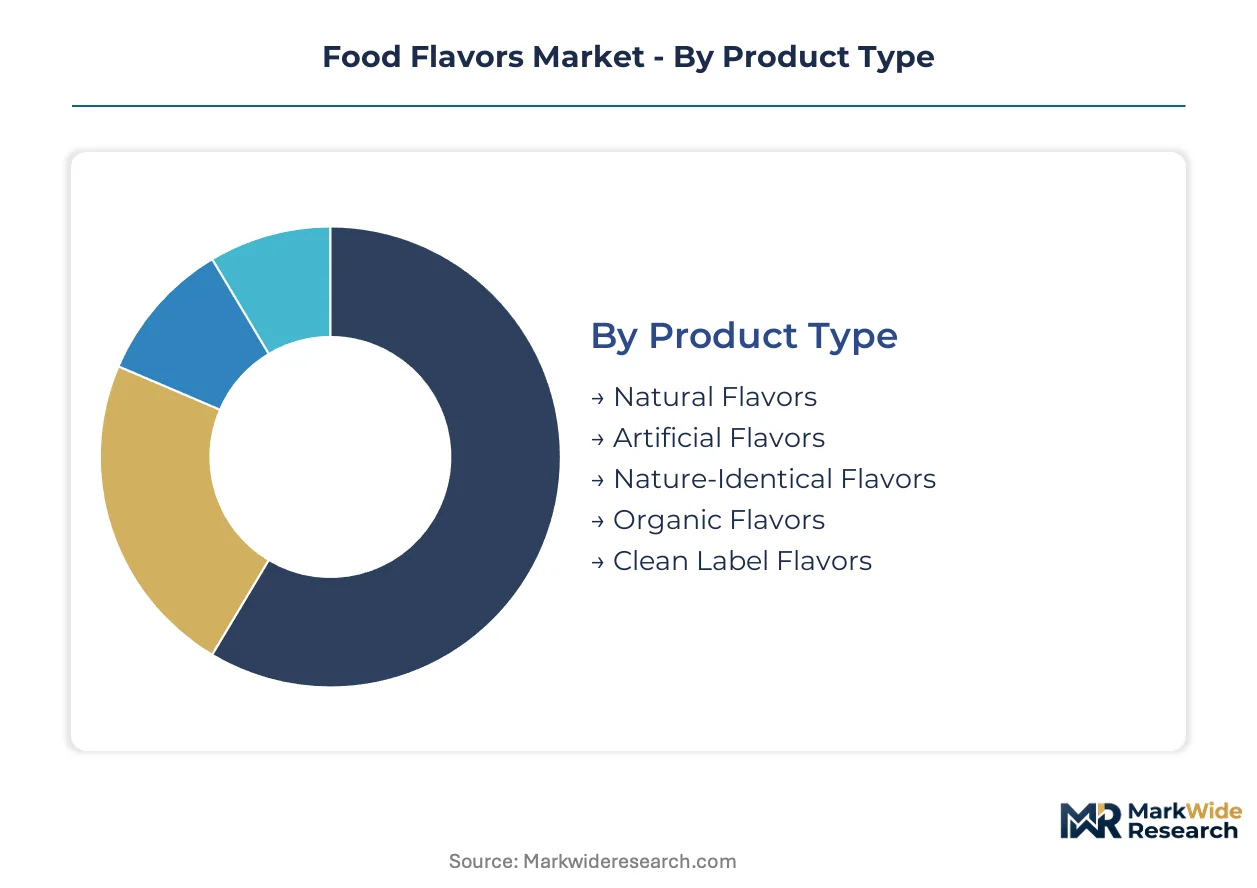
The food flavors market segmentation provides a granular view of diverse product types, application areas, and end-user demands. This detailed breakdown helps stakeholders identify key growth vectors, understand evolving consumer preferences, and pinpoint strategic investment opportunities across the value chain. Analyzing these segments reveals specific technical requirements and regulatory compliance challenges for flavor development.
Product Type:
Margin pools within this category concentrate around complex, naturally derived formulations that command premium pricing due to R&D intensity and sourcing challenges.
- Natural Flavors:These are extracts derived from plant or animal sources through physical, enzymatic, or microbiological processes. Consumer preference for clean labels and perceived health benefits drives demand in high-volume beverage and dairy alternative applications.
- Clean Label Flavors:Formulated to meet stringent "natural" and "no artificial ingredients" criteria, these flavors are often developed using advanced extraction techniques. Regulatory bodies like the US FDA and Europe's EFSA influence their rapid development for everyday packaged foods.
- Artificial Flavors:Synthetically produced compounds offer consistent profiles, cost-effectiveness, and enhanced stability under various processing conditions.
- Nature-Identical Flavors:These are chemically identical to natural compounds but are synthesized, providing consistent quality and availability.
- Organic Flavors:Sourced from certified organic ingredients, these flavors adhere to strict agricultural and processing standards, appealing to niche consumer segments.
The dominant share belongs to Natural Flavors, while Clean Label Flavors is closing the gap fastest.
Application:
Application segments delineate where flavor innovation translates into direct consumer experience and influences product success.
- Beverages:This high-volume sector requires stable, water-soluble flavor systems that deliver consistent taste profiles. Consumer demand for functional and low-sugar options drives innovation in natural and fruit-based profiles.
- Dairy Alternatives:Plant-based products require sophisticated flavor masking agents and authentic taste profiles to mimic traditional dairy experiences. Companies develop specific formulations for soy, oat, and almond bases.
- Bakery Products:Flavors for bakery items must withstand high heat processing and often require encapsulation for stability and controlled release.
- Confectionery:This segment focuses on intense, long-lasting taste perceptions and vibrant flavor profiles for sweets and candies.
- Savory Snacks:This category demands complex umami and regionally specific flavor profiles, driven by global consumer preferences for diverse snack options.
Beverages remain the largest application area, with Dairy Alternatives showing significant expansion.
End User:
Customer type segmentation reveals distinct procurement patterns and value chain relationships within the food flavors market.
- Food Manufacturers:These entities integrate flavors directly into their final product formulations, often seeking custom blends and technical support. They drive demand for consistent quality and regulatory compliance from their suppliers.
- Flavor Houses:Specializing in flavor creation and production, these companies serve as key innovation hubs within the industry. These entities invest heavily in R&D for novel molecules and complex natural extracts.
- Ingredient Suppliers:These companies provide base flavor components or pre-blended systems to other industry players.
- Food Service Providers:Utilize flavors in large-scale food preparation for restaurants, catering, and institutional settings.
- Artisan Producers:Small-batch makers often require specialized, often natural or organic, flavor ingredients for premium products.
Food Manufacturers represent the primary end-user segment, while Flavor Houses drive much of the underlying innovation.
Form:
Form factor dictates application suitability and flavor stability across various processing conditions and product matrices.
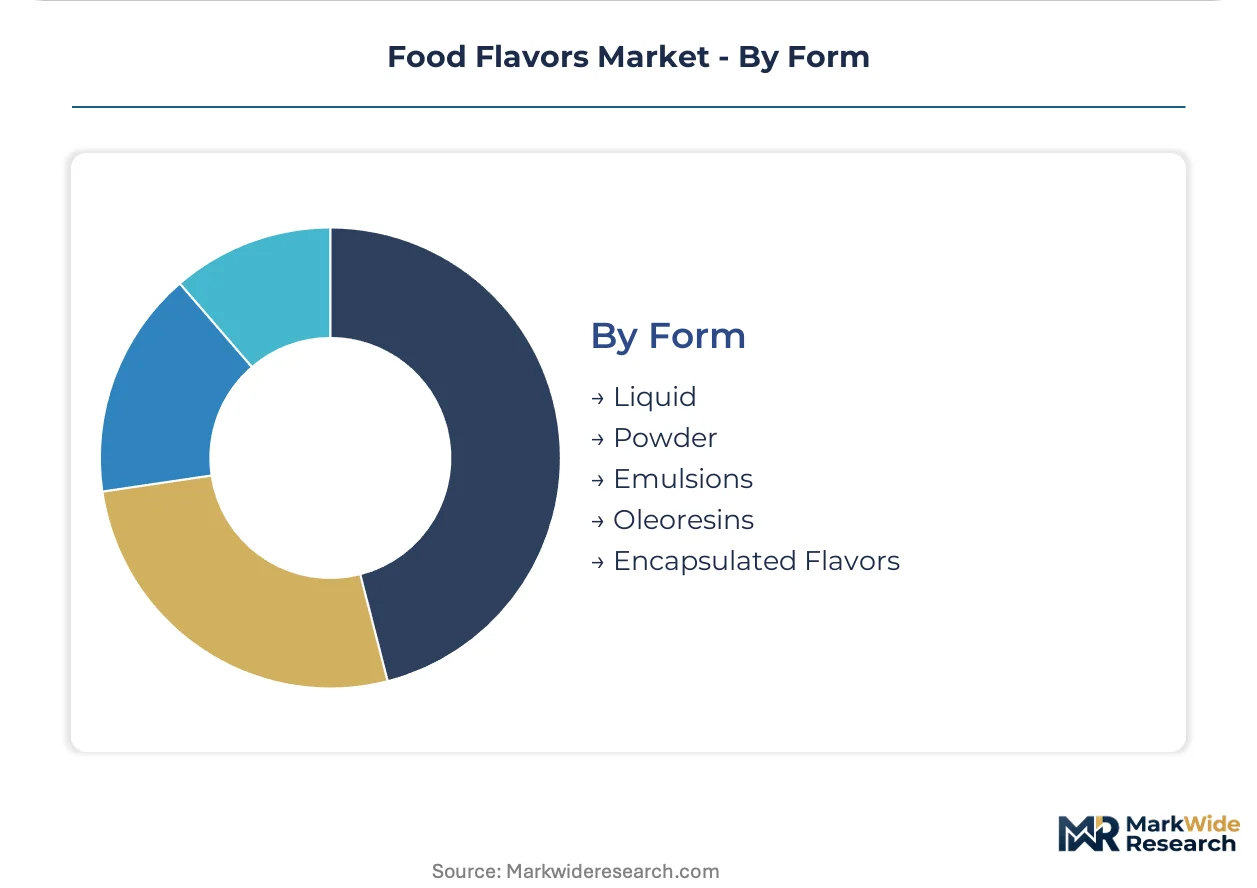
- Liquid:This is the most common and versatile form, offering ease of dispersion in water-based systems. These forms are standard for beverages and many dairy applications.
- Encapsulated Flavors:Advanced delivery systems protect flavor compounds from degradation and provide controlled release. These command premium pricing for stability in bakery and functional food products.
- Powder:Powdered flavors offer extended shelf life and precise dosing, particularly for dry mix applications and seasonings.
- Emulsions:These stabilize oil-soluble flavors in aqueous systems, commonly used in beverages for clarity and stability.
- Oleoresins:Concentrated extracts from spices and herbs, oleoresins deliver intense natural profiles and coloring properties.
Liquid forms dominate the market, yet Encapsulated Flavors are gaining traction for specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for food flavors varies significantly across global geographies. In the United States, demand for natural and clean label flavors dominates, driven by health-conscious consumers. Conversely, emerging markets like India and Brazil prioritize cost-effectiveness and regionally specific profiles.
United States
Demand for natural flavors and functional food applications remains a strong driver in the United States. The US FDA's strict labeling criteria compel manufacturers to invest in transparent ingredient sourcing. Food processing clusters in California and the Midwest innovate in plant-based dairy alternatives and savory snack profiles.
Germany
Germany places a strong emphasis on organic and sustainable sourcing for food flavors. EFSA regulations significantly shape ingredient approvals and clean label mandates across the European Union. The Rhine-Main region hosts major flavor houses developing sophisticated clean label solutions for beverages and confectionery.
India
Localized demand for complex savory and spice profiles is particularly high across India. FSSAI guidelines impact natural ingredient sourcing and product formulation for domestic consumption. Food parks in Maharashtra and Gujarat focus on flavor solutions tailored for traditional snacks and regional cuisine applications.
Brazil
The expansion of dairy alternatives and convenience foods drives flavor innovation in Brazil. ANVISA regulations govern food additive usage and consumer safety standards for packaged goods. São Paulo's vibrant food industry leverages advanced flavors for new product development in functional beverages and plant-based foods.
China
Demand for authentic regional culinary flavors and savory snacks remains robust across China. SAMR enforces strict food safety and labeling standards, influencing ingredient selection. The Yangtze River Delta region sees flavor companies developing innovative solutions for a wide range of processed foods and beverages.
Food Flavors Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the food flavors market. This tiered structure reflects the capital intensity of R&D and the need for global distribution networks. Strategic archetypes include large, diversified flavor houses and niche players focused on specific natural extracts. Dominant competitive moves involve portfolio diversification into adjacent functional ingredients and strategic partnerships for regional market access.
Within the integrated leader archetype, Givaudan exemplifies advanced AI-powered discovery platforms and consumer preference prediction, driving innovation in new molecule discovery. International Flavors & Fragrances occupies a position anchored by its vast portfolio of both natural and synthetic compounds, sustaining its market presence through broad product offerings. Kerry Group represents a strategy of integrating flavor systems with broader nutritional and functional ingredient offerings, addressing the evolving demand for comprehensive solutions from food manufacturers. These major players continuously adapt their strategies to evolving regulatory landscapes and consumer preferences for clean label products.
| Leading Market Players |
|---|
| Givaudan |
| DSM-Firmenich |
| International Flavors & Fragrances |
| Symrise |
| Sensient Technologies |
| Kerry Group |
| Archer Daniels Midland |
| Mane |
| Robertet |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key natural extracts lock in both supply access and price visibility for major flavor houses. This structure helps mitigate the inherent volatility in raw material markets, providing stability for large-scale food manufacturers.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for specialized natural flavors, reflecting R&D intensity and sourcing complexities. Price differentiation stems from the quality grade of natural extracts and the level of clean label certification. Upward pricing pressure arises from input cost volatility for raw materials like vanilla and citrus oils. Food manufacturers in high-volume beverage and savory snack categories exhibit higher price sensitivity compared to niche artisan producers seeking premium organic flavors.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized botanicals, are influenced by shipping lane disruptions and container availability. Geographic supply concentrates in regions like India for spices, Brazil for citrus, and Madagascar for vanilla, alongside European hubs for advanced flavor R&D. Raw material dependencies on specific agricultural commodities introduce supply chain risk through commodity price volatility. Distribution runs through direct sales channels from flavor houses to food manufacturers, supplemented by ingredient suppliers for foundational components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Flavors Market represents an early-cycle expansion story, primarily driven by accelerating penetration of plant-based dairy alternatives and clean label product development.
For Market Incumbents: Consolidate market share by acquiring specialized natural extract producers and advanced bioconversion technology firms. Invest heavily in AI-driven discovery platforms to accelerate new molecule identification and consumer preference prediction. This strategy helps counter the threat from data-driven formulation tools and stricter clean label mandates, leveraging R&D in bioconversion technologies.
For New Entrants and Emerging Players: A service-layer gap exists in providing highly customized, regionally specific savory flavor profiles for rapidly urbanizing Asian markets. Target artisan producers and plant-based protein applications in Southeast Asia, which remain underpenetrated by global players. A consultative solution-selling approach, emphasizing natural and clean label certifications, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward flavor houses demonstrating strong intellectual property in natural bioconversion techniques and robust AI capabilities. Focus on mid-sized firms specializing in advanced extraction methods or those with deep regional flavor expertise as prime acquisition targets. Increased M&A activity for natural ingredient portfolios will signal an inflection point in market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Discovery Acceleration | Speeds new molecule identification and consumer preference prediction for major flavor houses. |
| Bioconversion Technology Investment | Enables more sustainable and compliant natural flavor production for European markets. |
| Encapsulation System Development | Enhances stability and controlled release for functional beverages and bakery products. |
| Regional Flavor Portfolio Expansion | Addresses localized demand for savory profiles in Indian and Brazilian markets. |
| Strategic Partnerships for Sourcing | Secures reliable access to volatile natural raw materials like vanilla and citrus oils. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from flavor chemists, R&D directors, procurement managers, and regulatory affairs specialists across the value chain. Secondary data sources included regulatory filings from US FDA, EFSA, and SAMR, company annual reports, and relevant academic literature. This approach enabled robust bottom-up and top-down triangulation.
Forecasting across the analysis window involved modeling segmentation dimensions including product type, application, end-user, form, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market shifts, incorporating anticipated consumer preference shifts. Forecast inputs included evolving clean label definitions and raw material price projections, shaping future market trajectories.
Forecasts assume regulatory continuity in US FDA, EFSA, and SAMR regimes; material policy shifts would require re-modeling. Unforeseen geopolitical events or severe climate impacts on natural ingredient supply could significantly alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Lemon Extract Market