
 Foie Gras Market | 2026-2036
Foie Gras Market Size, Share, and Industry Trends Forecast 2026-2036
Foie Gras Market Intelligence
California's Proposition 12 is pivoting the cost-of-entry calculus for American distributors and forcing reliance on imported finished goods. Hudson Valley Foie Gras Inc. sustains its position through captive duck breeding and in-house slaughtering operations in New York's Catskill region. M. Rougié SAS dominates French retail and export channels with vertically controlled production in the Landes department. Duc de Gascogne SA differentiates through artisanal terrine and confit preparations aimed at premium European gastronomy buyers.
Foie gras denotes the pathologically enlarged liver of force-fed waterfowl, specifically duck or goose, yielding a fat-laden organ typically weighing 400–800 grams with a buttery texture and distinctive flavor profile prized in haute cuisine. The product serves as a centerpiece ingredient in French gastronomy, terrine preparations, and luxury hotel banquet service. Raw and whole foie gras categories command the deepest margin pools due to chef-driven demand for unprocessed lobes in Michelin-starred kitchens. Prepared formats, including mousses and bloc preparations, occupy the broadest retail penetration through vacuum-sealed and chilled packaging channels. Duck-sourced foie gras leads volume globally, while goose variants retain scarcity pricing in traditional European markets.
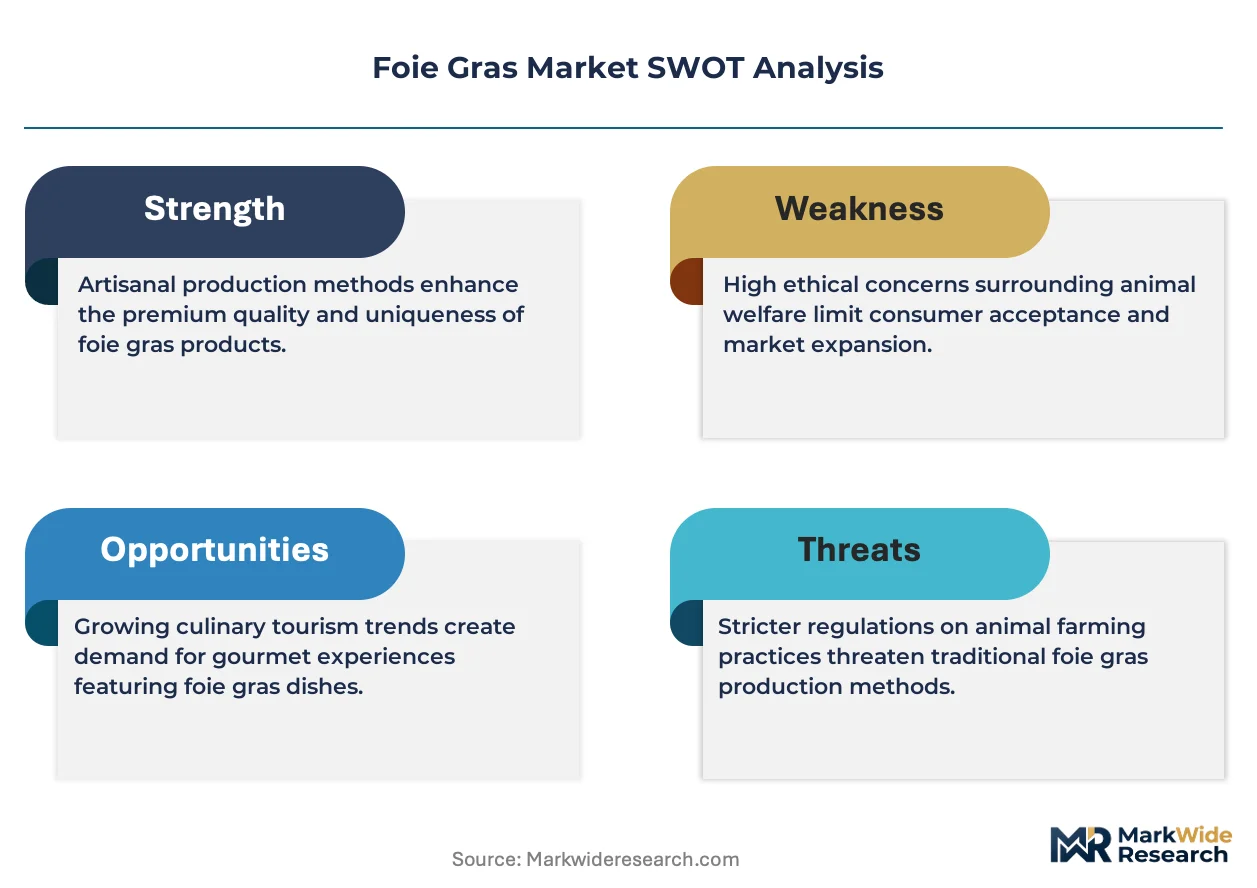
The European Commission's animal welfare directives, France's appellation-aware quality enforcement, and New York City's local production restrictions collectively reshape sourcing geography and compliance investment. EFSA welfare standards and REACH-aligned packaging rules further constrain formulation and labeling for EU-bound products. Stakeholders must monitor municipal ballot initiatives and farm-level welfare certification schemes as these now determine market access faster than traditional trade policy.
Market Dynamics
Force-feeding bans in California and New York City are fragmenting domestic supply chains while French and Spanish producers consolidate export dominance through vertically controlled breeding and processing operations.
Growth Catalysts
- EFSA welfare standards:Harmonized EU animal welfare directives reduce cross-border compliance friction for Landes-department processors exporting to German and Belgian retail channels.
- Michelin-starred kitchen demand:Raw lobe procurement from chef-driven establishments in Paris, Lyon, and Barcelona sustains premium pricing tiers for unprocessed foie gras categories.
- Artisanal terrine specialization:Small-batch confit and bloc preparations from southwestern France capture gastronomy buyers seeking provenance-linked products.
Market Restraints
- Feed grain cost volatility:Corn and wheat input prices fluctuate with Black Sea supply disruptions, compressing margins for duck-rearing operations dependent on carbohydrate-intensive force-feeding protocols.
- Production concentration risk:Over 80 percent of global output originates within 200 kilometers of Sarlat and Périgueux, creating geographic vulnerability to regional disease outbreaks or climate shocks.
- Plant-based analog substitution:Cultured fat and precision-fermented liver mimics from Israeli and Dutch food-tech developers threaten premium positioning among younger European consumers.
Strategic Opportunities
- Japanese luxury hospitality:Ryokan and kaiseki restaurant adoption of foie gras as fusion ingredient remains underdeveloped relative to French culinary influence in Tokyo and Osaka.
- REACH-aligned packaging innovation:Vacuum-sealed biodegradable films compliant with EU chemical regulations open shelf-life extension in premium retail without refrigeration dependency.
- Blockchain provenance tracking:Distributed ledger verification of farm-to-fork welfare compliance addresses sourcing transparency demands from Scandinavian and Benelux procurement officers.
Industry Challenges
- Veterinary pathologist shortage:Force-feeding protocol oversight and liver quality grading require specialized avian health expertise concentrated in aging French agricultural institutes.
- Slaughterhouse certification timelines:EU-approved abattoir status for foie gras-specific processing lines demands 18-24 month regulatory review cycles that delay capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foie Gras Market |
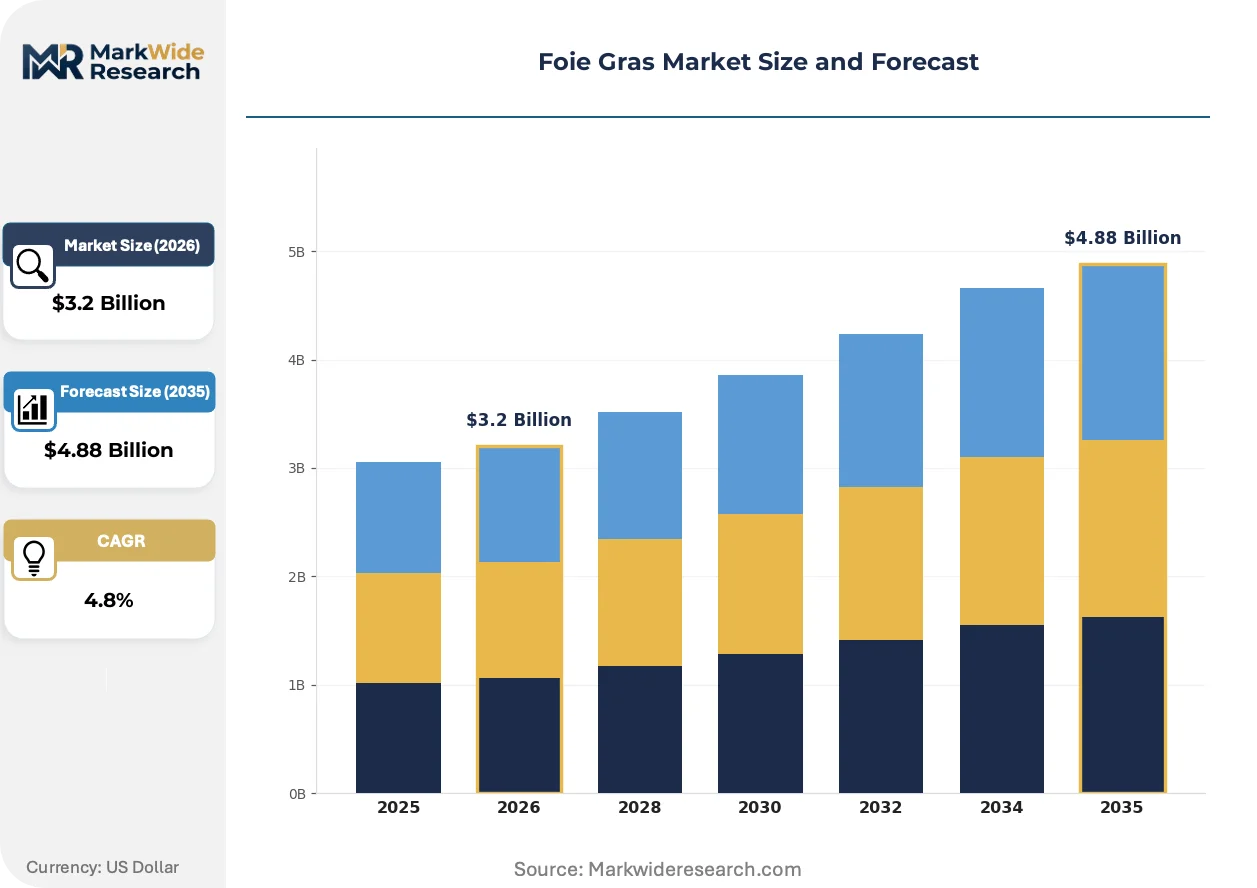
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepared, Raw, Whole, Trimmings Source: Duck, Goose, Mixed, Organic Distribution Channel: Retail, Wholesale, Online, Food Service Packaging Type: Cans, Jars, Vacuum-sealed, Chilled |
| Companies Covered | Comtesse Du Barry, Petrossian SAS, Hudson Valley Foie Gras Inc., Lafitte Foie Gras, Agro-Top Produits S.A., M. Rougié SAS, Duc de Gascogne SA, Jiajia Food Group Co., Ltd, Labeyrie Fine Foods SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foie Gras Market Strategic Shifts & Innovations
Production automation and welfare-compliant alternative feeding methods are displacing manual force-feeding labor while regulatory fragmentation accelerates investment in traceability infrastructure.
Precision-controlled pneumatic gavage systems are automating feed delivery volume and timing in industrial duck barns near Castelnaudary. Landes-based cooperatives deploy these units to reduce labor dependency during peak autumn processing windows. The technology is automating quality consistency across batches previously subject to handler skill variation.
France's appellation-aware quality enforcement and California's Proposition 12 create divergent compliance baselines for exporters serving multiple jurisdictions. Producers now maintain parallel inventory streams: EU-labeled whole livers and US-restricted prepared formats. The regulatory friction most affects mid-size processors lacking dedicated export compliance staff.
Direct-to-restaurant purchasing platforms are bypassing traditional wholesale importers in New York and San Francisco. Chef buyers now source whole lobes through specialized freight forwarders with cold-chain custody documentation. This channel disintermediation concentrates most visibly in California, where restaurant operators circumvent retail distribution entirely to secure product despite production bans.
Foie Gras Market Segmentation
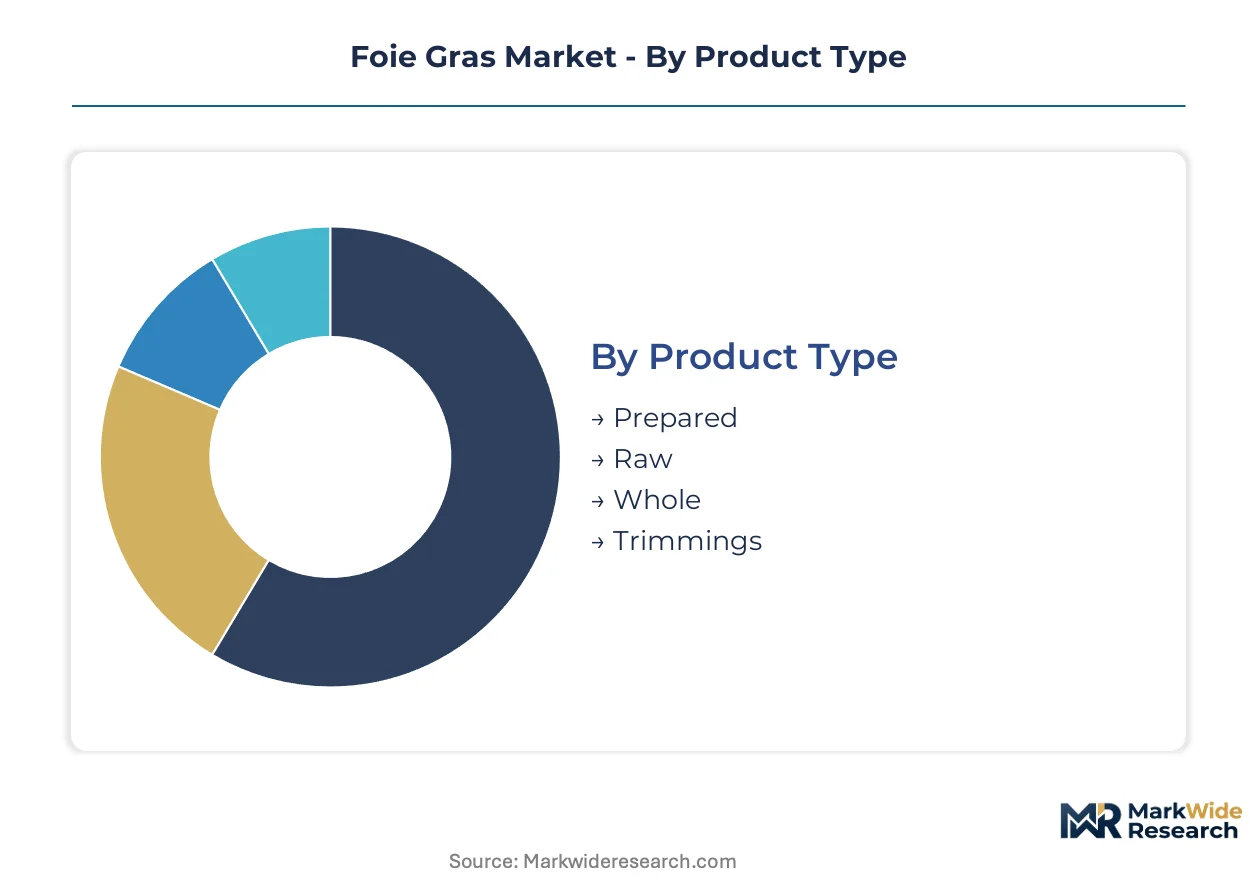
Foie Gras market segmentation reveals how regulatory fragmentation and chef-driven procurement reshape category economics. Each dimension carries distinct compliance burdens and margin structures that determine competitive positioning across jurisdictions.
Product Type:
EFSA welfare documentation and USDA import permits divide segments by processing intensity and destination-market eligibility.
- Prepared:Mousses, blocs, and terrines undergo thermal processing that satisfies extended shelf-life requirements for retail distribution. Vacuum-sealed formats dominate French supermarket channels, while pâté preparations serve hotel banquet operations in Japan and the UAE. Prepared formats absorb the bulk of California and New York City demand through legal import loopholes for finished goods.
- Raw:Unprocessed liver lobes require continuous cold-chain custody from abattoir to kitchen. Michelin-starred establishments in Paris, Lyon, and Barcelona specify raw lobes for precise portion control and texture preservation. This segment demands veterinary health certificates and HACCP documentation at every transit point.
- Whole:Intact lobes weighing 400–800 grams serve traditional roasting and torchon preparations.
- Trimmings:Processing remnants supply mousse manufacturing and industrial foodservice formulations.
Prepared sits at the top of the volume ranking, with Raw climbing the fastest.
Source:
Cost structures stratify sharply by feed conversion efficiency and scarcity premiums attached to traditional breeds.
- Duck:Mulard hybrids dominate industrial production with superior force-feeding tolerance and faster liver enlargement cycles. Southwestern France and Spain's Extremadura region concentrate over 90 percent of global duck foie gras output. Grain input costs and labor-intensive gavage protocols compress margins for smaller producers.
- Goose:Toulouse and Landes breeds yield smaller, denser livers commanding scarcity pricing in traditional European gastronomy. Hungarian and Bulgarian operations preserve artisanal goose production for German and Austrian retail channels. Longer rearing cycles and lower feed conversion ratios limit scalability.
- Mixed:Blended duck-goose preparations serve mid-tier restaurant segments seeking cost optimization.
- Organic:Certified grain and free-range rearing protocols attract Scandinavian and Benelux procurement specifications.
Duck captures the dominant volume share, with Organic expanding most quickly on welfare-certification demand.
Distribution Channel:
Channel selection determines cold-chain investment intensity and regulatory exposure across import-dependent markets.
- Food Service:Direct-to-restaurant purchasing concentrates in California and New York City, where operators circumvent retail distribution through specialized freight forwarders. Chef buyers demand batch-specific welfare documentation and slaughterhouse certificates. This channel commands premium pricing through disintermediation economics.
- Retail:Supermarket and delicatessen distribution depends on REACH-compliant packaging and extended shelf-life formulations. French hypermarket chains and Japanese department store food halls anchor volume.
- Wholesale:Traditional importers and distributors serve secondary markets with consolidated logistics.
- Online:Direct-to-consumer platforms emerge in jurisdictions with permissive shipping regulations.
Food Service leads revenue concentration, with Online gaining share fastest on platform specialization.
Packaging Type:
Packaging innovation focuses on shelf-life extension and refrigeration reduction for export market access.
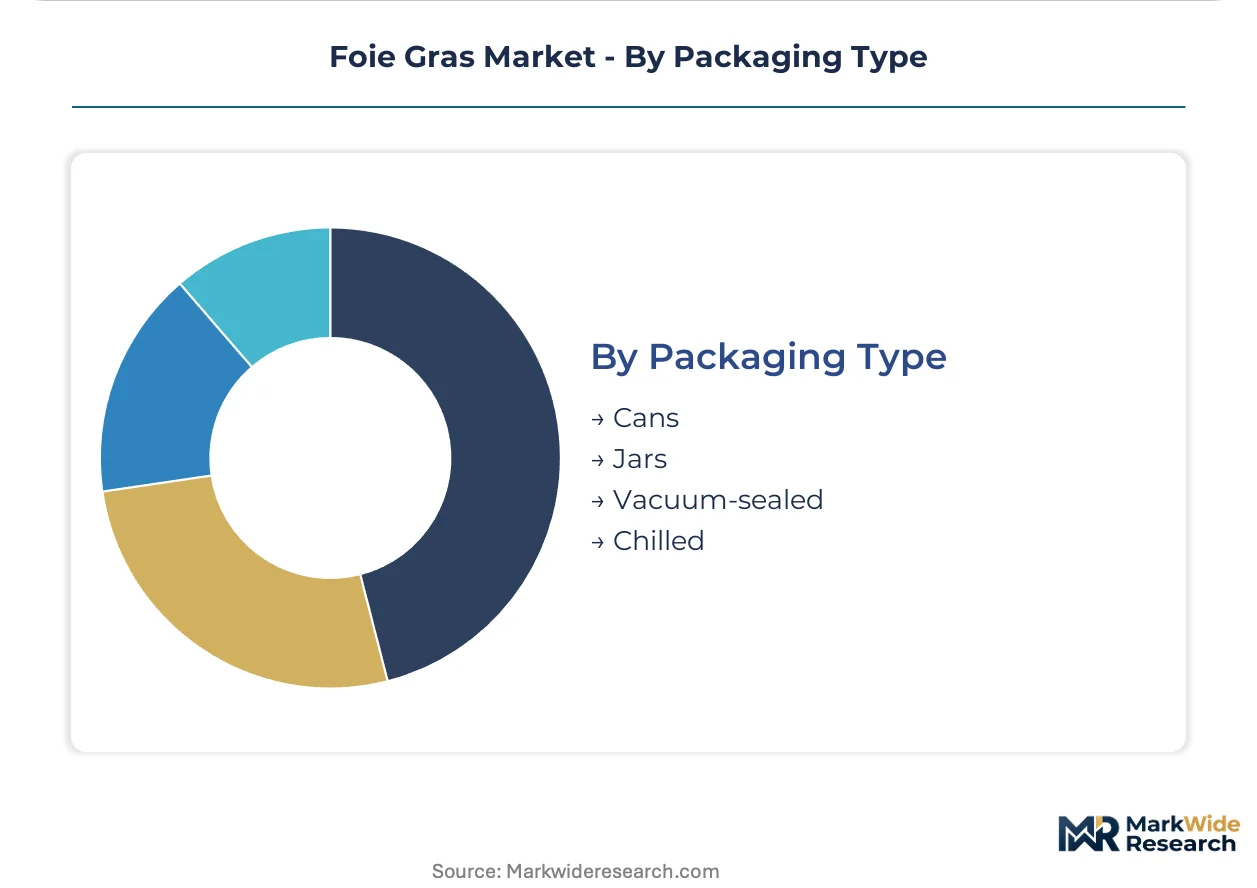
- Vacuum-sealed:Modified atmosphere packaging extends retail shelf life from days to weeks, enabling transatlantic shipment without frozen degradation. Biodegradable film development targets EU single-use plastic directives. This format dominates prepared product exports to North American and Asian markets.
- Chilled:Temperature-controlled logistics preserve raw lobe integrity for chef-procurement platforms. Real-time tracking and custody documentation satisfy insurance and liability requirements for high-value shipments.
- Cans:Thermal sterilization enables ambient distribution in regions with limited cold-chain infrastructure.
- Jars:Glass packaging serves gift and premium retail segments with visual product presentation.
Vacuum-sealed holds the volume lead, with Chilled showing steepest expansion on direct-to-chef platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French agricultural engineers and Spanish veterinary specialists anchor the industry's technical workforce concentration, with southwestern France housing the densest cluster of force-feeding expertise and liver-grading certification programs.
France
Michelin-starred establishments in Paris and Lyon sustain raw lobe procurement at premium tiers. EFSA welfare directives harmonize cross-border compliance for Landes-department processors exporting to German retail channels. The Sarlat-Périgueux corridor concentrates over 80 percent of global output in vertically integrated breeding and processing operations.
Spain
Extremadura's Mulard duck farms supply volume to Japanese hospitality and Middle Eastern duty-free retail. Spanish processors navigate REACH-aligned packaging rules for EU-bound prepared formats. Castelnaudary industrial barns deploy pneumatic gavage systems to reduce labor dependency during peak autumn windows.
United States
California's Proposition 12 and New York City's phased prohibition reshape import-dependent supply chains for finished goods. FDA import inspections and USDA permits govern cross-border movement of prepared mousses and terrines. Hudson Valley operators sustain captive breeding and in-house slaughtering in New York's Catskill region despite municipal restrictions.
Japan
Ryokan and kaiseki restaurants adopt foie gras as fusion ingredient with underdeveloped penetration relative to French culinary influence. METI food safety standards and import documentation requirements structure cold-chain logistics for Tokyo and Osaka procurement officers. Department store food halls in Ginza anchor premium retail distribution.
Hungary
Toulouse and Landes goose breeds yield scarcity-priced livers for German and Austrian traditional gastronomy buyers. Hungarian operations preserve artisanal production methods with longer rearing cycles and lower feed conversion ratios. Small-batch confit preparations from Pannonian plain farms capture provenance-seeking European retail channels.
Foie Gras Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a structure consolidated around vertically controlled breeding operations. The competitive terrain stratifies into three archetypes: integrated producers with captive duck supply, artisanal terrine specialists, and import-dependent distributors serving restricted jurisdictions. Capacity expansion through EU-approved abattoir certification and strategic partnerships with freight forwarders dominate competitive moves.
Within the integrated producer tier, M. Rougié SAS and Duc de Gascogne SA exemplify archetypes of scale-driven export dominance and artisanal premium positioning respectively. Hudson Valley Foie Gras Inc. occupies a position bridging captive supply and restricted-market adaptation. These three anchors illustrate how geographic concentration in southwestern France, regulatory fragmentation in North America, and hospitality-channel specialization in East Asia collectively shape competitive positioning.
| Leading Market Players |
|---|
| Comtesse Du Barry |
| Petrossian SAS |
| Hudson Valley Foie Gras Inc. |
| Lafitte Foie Gras |
| Agro-Top Produits S.A. |
| M. Rougié SAS |
| Duc de Gascogne SA |
| Jiajia Food Group Co., Ltd |
| Labeyrie Fine Foods SA |
| Others |
Cost & Logistics Intelligence
Captive breeding and in-house slaughtering operations in New York's Catskill region and southwestern France anchor both supply security and pricing power for integrated producers. This backward integration insulates margin pools from grain cost volatility and import permit delays that compress returns for distributors dependent on finished goods sourcing.
Pricing Analysis
The bundled service split separates raw lobe procurement with veterinary documentation from unprocessed product sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by welfare certification grade and provenance specificity. Pricing pressure stems from feed grain cost volatility compressing margins for carbohydrate-intensive force-feeding protocols. Food service buyers in Michelin-starred kitchens show least price sensitivity, while retail distributors in import-dependent markets absorb greatest margin compression.
Supply Chain Analysis
Domestic-content mandates in California and New York City reshape sourcing toward prepared formats that circumvent production bans. Supply concentrates in France, Spain, and Hungary, with over 80 percent of global output originating within 200 kilometers of Sarlat and Périgueux. Corn and wheat feed inputs, Mulard duck breeding stock, and EU-approved abattoir certification anchor production dependencies. Single-source vulnerability from geographic concentration risk threatens output continuity. Distribution runs through specialized freight forwarders with cold-chain custody documentation for chef-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier raw lobe positioning and feed cost hedging for integrated producers. Automated gavage systems and welfare-compliant alternative feeding methods enable cost-down capture without quality degradation.
For Market Incumbents: Lock in chef-procurement platform relationships through batch-specific welfare documentation and slaughterhouse certificate transparency. Invest in EU-approved abattoir certification capacity to capture 18-24 month regulatory review timelines before competitors. Defend against plant-based analog substitution from Israeli and Dutch food-tech developers by emphasizing provenance-linked artisanal terrine specialization.
For New Entrants and Emerging Players: Precision-fermented liver mimic technology offers a wedge into Scandinavian and Benelux procurement specifications where welfare-certification demand accelerates fastest. Target Japanese luxury hospitality segments with underdeveloped foie gras penetration relative to French culinary influence. Deploy direct-to-restaurant purchasing platforms with cold-chain custody documentation to bypass traditional wholesale importer margins in California and New York City.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size processors lack dedicated export compliance staff to maintain parallel EU-labeled and US-restricted inventory streams. Long-term viability favors vertically controlled breeding operations with captive duck supply and in-house slaughtering capabilities. Acquisition targets should demonstrate EU-approved abattoir status and established freight forwarder partnerships. Monitor municipal ballot initiative outcomes as faster market access determinants than traditional trade policy.
| Strategic Initiative | Industry Significance |
|---|---|
| EU-Approved Abattoir Certification | 18-24 month regulatory review cycles create capacity expansion barriers for competitors. |
| Blockchain Provenance Tracking | Distributed ledger verification satisfies Scandinavian procurement officer transparency demands. |
| Biodegradable Vacuum-Sealed Packaging | REACH-aligned films extend shelf life without refrigeration dependency for export markets. |
| Pneumatic Gavage Automation | Precision-controlled feed delivery reduces labor dependency during peak autumn processing windows. |
| Direct-to-Restaurant Platform Launch | Chef-procurement disintermediation concentrates in California where retail distribution faces prohibitions. |
Research Approach
Multiple input streams — primary interviews with foie gras producers and chef buyers, trade data reconciliation, and regulatory filing analysis — were reconciled to construct supply and demand estimates. Conversations with veterinary pathologists at French agricultural institutes, procurement officers at Landes-department cooperatives, and freight forwarders specializing in cold-chain custody informed operational assumptions. Secondary validation drew from EFSA welfare directive documentation, REACH-aligned packaging rule filings, FDA import inspection records, and customs data on prepared format shipments. Bottom-up capacity modeling and top-down consumption estimates were triangulated against disclosed production volumes from vertically integrated operators.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory friction and hospitality channel recovery patterns across the analysis window. Segmentation modeling captured product type, source animal, distribution channel, and packaging format dimensions alongside welfare certification tier. CAGRs were derived from slope analysis of reconciled annual estimates. Forecast inputs incorporated feed grain price correlation coefficients, EU abattoir certification pipeline visibility, and municipal ballot initiative tracking.
The model holds under stable regulatory enforcement trajectories and continued chef-driven demand for raw lobe procurement; deviation in force-feeding ban expansion or plant-based analog breakthrough adoption would shift volume and value projections. Forecasts reflect documented assumptions on breeding stock availability, veterinary specialist labor supply, and cold-chain logistics capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sweet Spreads Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Natto Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Honey Spread Market
Specialty Foods
Zhacai Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Super Foods Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Grain Free Dog Food Market