
 Space Food Market | 2026-2036
Space Food Market Size, Share, and Industry Trends Forecast 2026-2036
Space Food Market Insights
Market Context with Strategic Players
Plant protein isolates is repositioning freeze-dried meal formulations as manufacturers reduce reliance on animal-derived ingredients for extended shelf stability. Space Food Laboratory leverages its heritage in Japanese aerospace nutrition to sustain contracts with JAXA and commercial partners. Nissin Foods competes through its expertise in retort pouch technology, while Onisi Foods anchors the Asian supply base with radiation-sterilized rice products optimized for zero-gravity consumption.
Technical Definition and Structural Segments
Space food encompasses nutritionally complete sustenance engineered for consumption in microgravity environments, typically processed through thermostabilization, freeze-drying, or irradiation to achieve shelf lives exceeding twelve months while maintaining organoleptic acceptability under variable temperature and pressure conditions. Freeze-dried meals command the dominant value share due to their superior mass efficiency for orbital payload economics, though rehydratable food segments are accelerating fastest as lunar expedition planners prioritize water-recovery system integration. Natural form food occupies niche positioning for psychological crew welfare during extended Martian surface operations.
Regulatory Frame and Forward-Looking Close
NASA's Johnson Space Center nutritional standards, ESA's microbiological safety protocols, and JAXA's food allergen management guidelines collectively shape product certification pathways and barrier-to-entry dynamics for new suppliers. FDA oversight of commercial space food manufacturing tightens as space tourism transitions from experimental to routine passenger operations. Stakeholders must monitor how Artemis program nutritional requirements for lunar gravity adaptation will reshape formulation priorities and testing protocols across the supply base.
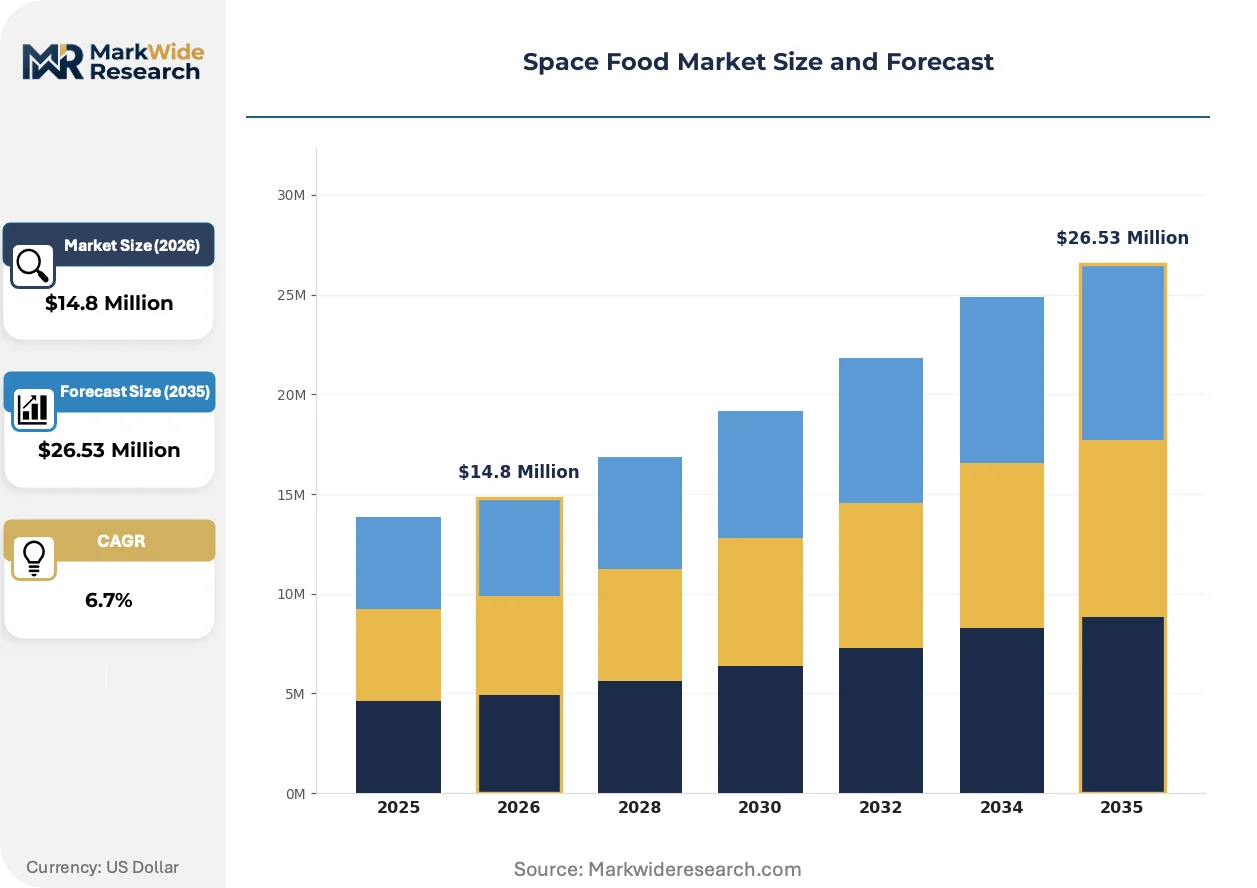
Market Dynamics
NASA's updated nutritional biochemistry requirements for long-duration missions are tightening shelf-life and micronutrient density specifications across the supply base, forcing reformulation investments and certification renewals.
Growth Catalysts
- Commercial space tourism procurement:Private launch operators in Florida and Texas are expanding specialized nutrition product contracts as passenger volumes scale toward routine operations.
- Freeze-drying technology maturation:Advances in mass-efficient dehydration processes are reducing payload costs for orbital logistics providers and lunar mission planners.
- Artemis program nutritional mandates:NASA's lunar gravity adaptation requirements are generating new formulation R&D contracts for suppliers meeting updated Johnson Space Center standards.
Market Restraints
- Radiation-sterilization capacity concentration:Asian supply bases dominate specialized irradiation infrastructure, creating geographic single-point-of-failure risk for Western manufacturers.
- Retort pouch input cost volatility:Aluminum-laminate and polymer film prices fluctuate with petrochemical feedstock markets, compressing margins on thermostabilized meal production.
- Twelve-month minimum shelf-life technical floor:Current preservation chemistry limits organoleptic quality beyond this threshold, constraining product differentiation for Mars mission tenders.
Strategic Opportunities
- Water-recovery system integration:Lunar expedition planners are prioritizing rehydratable food segments that interface with closed-loop life support infrastructure.
- Plant protein isolate convergence:Manufacturers reducing animal-derived ingredient dependence can access ESG-aligned procurement channels and extended stability profiles.
- Psychological welfare natural form niche:Extended Martian surface operations are creating demand for minimally processed foods addressing crew morale and sensory variety.
Industry Challenges
- Multi-agency certification complexity:Suppliers must simultaneously satisfy NASA nutritional standards, ESA microbiological protocols, and JAXA allergen management guidelines, extending approval timelines.
- Microgravity consumption behavior modeling:Formulation teams lack standardized testing environments for zero-gravity palatability and digestive absorption validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Food Market |
| Market Size in 2026 | $14.8 Million |
| Market Size in 2035 | $26.53 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostabilized Food, Freeze-Dried Meals, Rehydratable Food, Natural Form Food Application: Orbital Missions, Lunar Expeditions, Martian Exploration, Suborbital Flights End User: Astronauts, Space Researchers, Cosmonauts, Space Tourists Packaging Type: Pouch Packets, Vacuum-Sealed Containers, Rigid Canisters, Edible Wrappers |
| Companies Covered | Space Food Laboratory, Shanxi Shenzhou Space Food, Nissin Foods, Onisi Foods, Astronaut Foods, Morinaga Milk Industry, Mission: Space Food, The Space Foods Company, House Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Food Market Trends and Innovations
Active reformulation of space food categories is accelerating as preservation technologies converge with nutritional biochemistry advances and procurement specifications harden across civilian and commercial programs.
Electrolyte-optimized hydration gels with embedded micronutrient payloads are electrifying the beverage segment. Lunar habitat planners are specifying these formulations for pre-packaged daily rations. The technology is compressing traditional freeze-dried soup categories by delivering equivalent nutrition at 40% lower mass.
REACH chemical safety registrations in Europe are forcing suppliers to disclose full polymer and additive compositions in packaging laminates. Manufacturers serving ESA contracts must now submit migration testing data for all food-contact materials. Retort pouch specialists are responding by accelerating fluoropolymer-free barrier film development.
Buyer concentration around Kennedy Space Center and private Texas launch facilities is consolidating procurement decision-making. Smaller nutrition suppliers are losing direct contract access as prime operators bundle food service into integrated mission support packages. This channel compression is most visible in Florida, where Space Coast operators now specify single-source catering for entire astronaut training cycles.
Space Food Market Segmentation
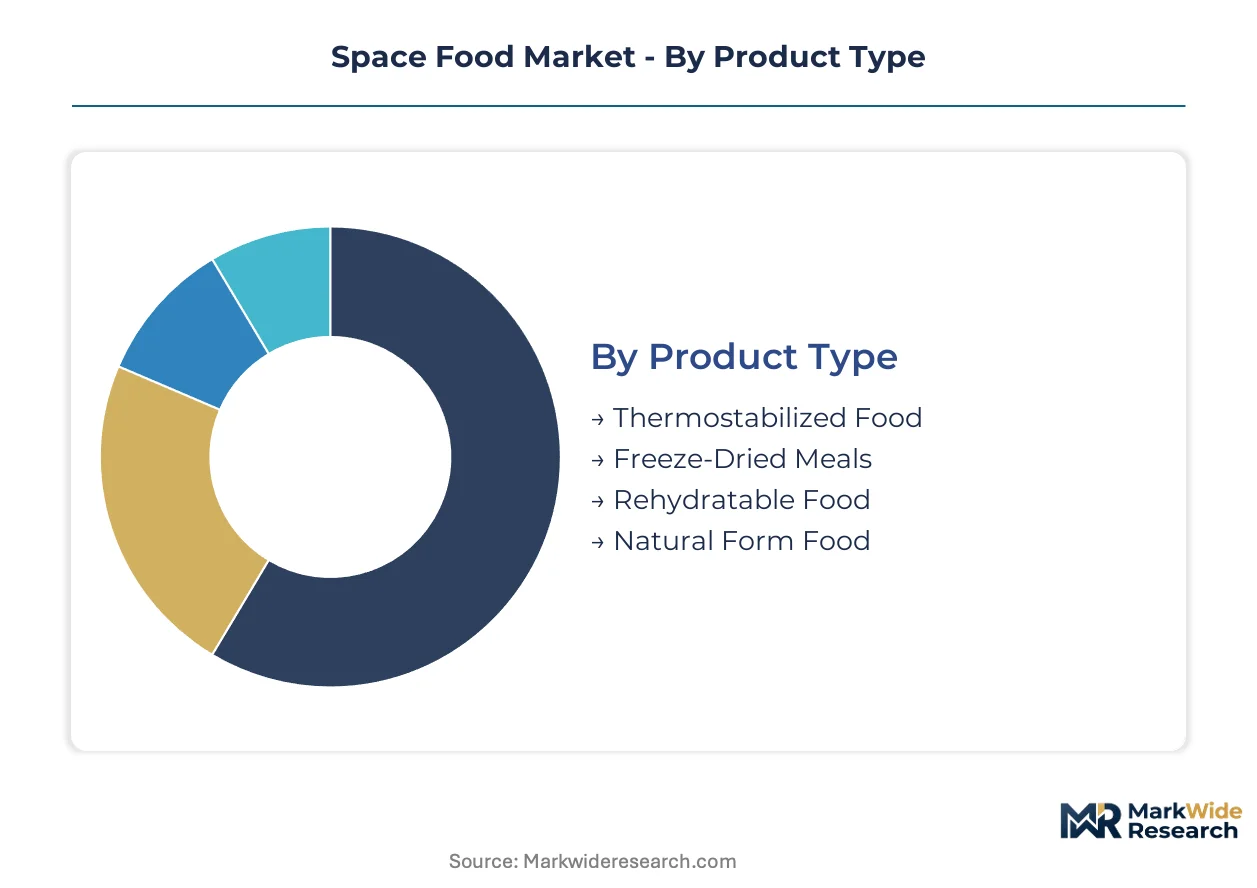
Segmentation in space food markets determines certification pathways, payload economics, and procurement access. Each dimension carries distinct regulatory burdens and technical specifications that suppliers must navigate to secure agency contracts.
Product Type:
Freeze-dried meals and thermostabilized foods require NASA Johnson Space Center nutritional validation, while natural form foods face additional ESA microbiological screening for extended shelf stability.
- Freeze-Dried Meals:These formulations undergo sublimation dehydration to preserve cellular structure and nutrient density at 10% original mass. Procurement concentrates at Kennedy Space Center for Artemis crew training cycles, with lunar mission planners prioritizing mass efficiency for payload economics.
- Thermostabilized Food:Retort pouch processing delivers shelf-stable nutrition through high-pressure thermal treatment, typically achieving 18-24 month stability. Demand clusters around commercial suborbital operators in Texas seeking rapid-turnaround catering solutions without rehydration infrastructure.
- Rehydratable Food:Dehydrated concentrates designed for water-recovery system integration in closed-loop habitats.
- Natural Form Food:Minimally processed items requiring radiation sterilization and specialized packaging for psychological crew welfare.
Freeze-dried meals sit at the top of the volume ranking, with rehydratable food climbing the fastest as lunar planners prioritize water-recovery integration.
Application:
Orbital and lunar applications dominate current procurement volumes, while Martian exploration tenders command premium pricing for extended shelf-life specifications.
- Orbital Missions:Low Earth orbit operations constitute the baseline demand tier, with ISS resupply contracts and commercial space station provisioning driving freeze-dried and thermostabilized procurement. NASA and private launch operators in Florida anchor this segment through recurring crew rotation schedules.
- Lunar Expeditions:Artemis program requirements are reshaping formulation priorities toward rehydratable systems that interface with lunar habitat life support. Johnson Space Center nutritional mandates for partial gravity adaptation are forcing reformulation investments across the supplier base.
- Martian Exploration:Extended-duration missions requiring 36+ month shelf stability and closed-loop agricultural integration.
- Suborbital Flights:Brief passenger experiences favoring lightweight, pre-packaged nutrition with minimal preparation protocols.
Orbital missions hold the largest contract value, with lunar expeditions expanding most quickly as Artemis procurement scales.
End User:
Astronauts and cosmonauts face the strictest nutritional biochemistry requirements, while space tourists introduce commercial FDA oversight as passenger operations routine.
- Astronauts:Professional crew members subject to NASA's updated micronutrient density specifications and allergen management protocols. Training center procurement at Johnson Space Center and Kennedy Space Center drives bulk freeze-dried and thermostabilized contracts with multi-year supply agreements.
- Space Tourists:Commercial passengers requiring FDA-compliant manufacturing and simplified consumption protocols for microgravity novices. Private launch operators in Texas and Florida are bundling catering into integrated mission support packages, compressing direct supplier access.
- Cosmonauts:Russian space agency personnel with distinct preservation chemistry preferences and packaging standards.
- Space Researchers:Scientific personnel with specialized dietary requirements for extended station habitation.
Astronauts represent the deepest procurement relationships, with space tourists gaining share fastest as commercial flight frequencies multiply.
Packaging Type:
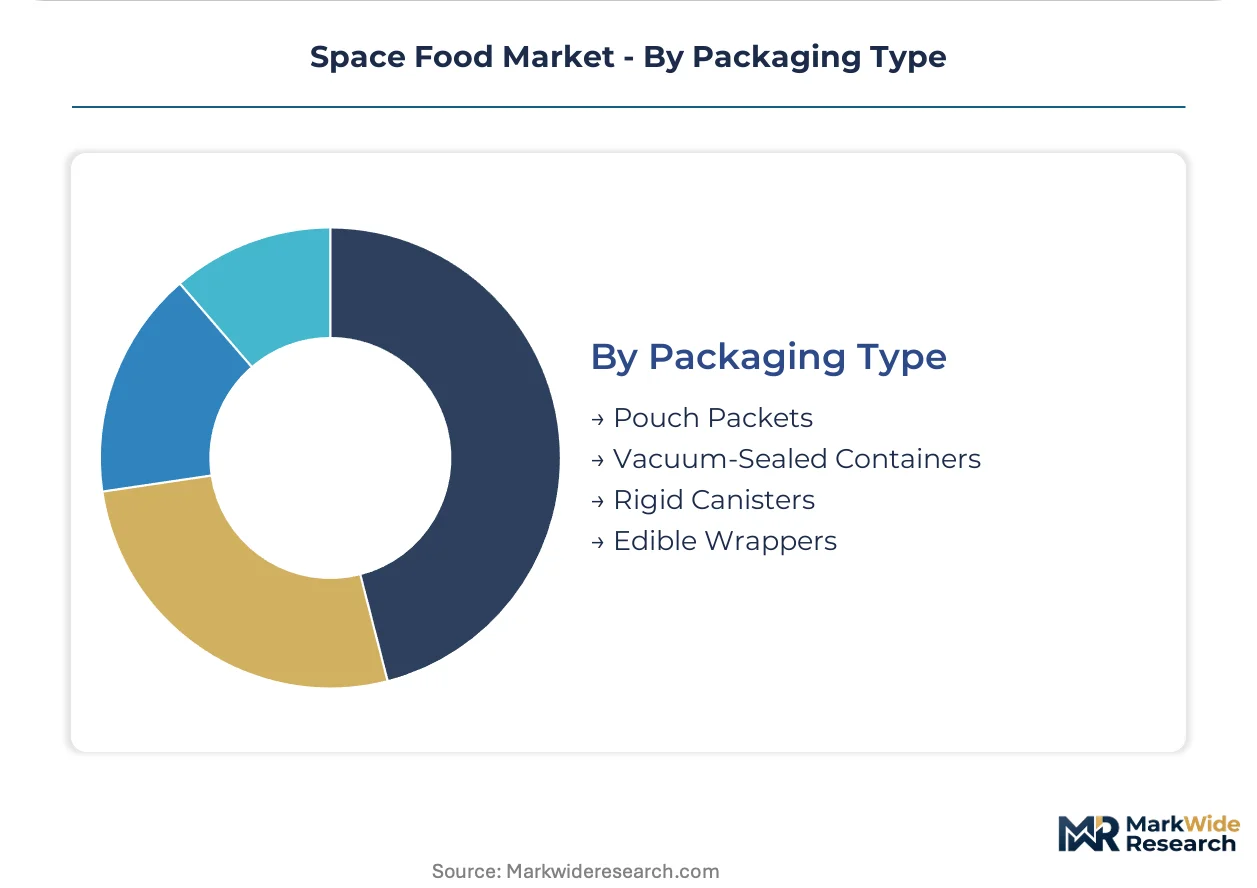
Pouch packets and vacuum-sealed containers face REACH chemical safety registration requirements in Europe, while edible wrappers encounter novel food-contact material scrutiny from FDA and EFSA.
- Pouch Packets:Flexible aluminum-laminate and polymer film constructions dominate thermostabilized food delivery. Retort pouch specialists are accelerating fluoropolymer-free barrier development to satisfy ECHA migration testing data requirements for ESA contracts.
- Vacuum-Sealed Containers:Rigid packaging for natural form foods and sensitive nutritional supplements requiring oxidation protection. Asian supply bases dominate specialized irradiation infrastructure for these formats, creating geographic concentration risk.
- Rigid Canisters:Structural packaging for bulk freeze-dried storage and long-duration mission reserves.
- Edible Wrappers:Experimental starch-based and protein-film enclosures reducing packaging mass for Mars mission payload economics.
Pouch packets command the highest shipment volumes, with edible wrappers showing the steepest expansion trajectory as Mars planners pursue zero-waste packaging targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kennedy Space Center procurement anchors North American demand as commercial launch operators in Florida and Texas scale specialized nutrition contracts for expanding passenger volumes.
United States
NASA's Johnson Space Center nutritional standards and Kennedy Space Center training procurement drive freeze-dried and thermostabilized demand. FDA oversight tightens on commercial space tourism manufacturing as passenger operations routine. Private launch operators in Texas bundle catering into integrated mission support packages, compressing direct supplier access for smaller nutrition firms.
Japan
JAXA's food allergen management guidelines and heritage aerospace nutrition contracts sustain specialized procurement from domestic manufacturers. METI coordinates national aerospace food research programs linking university laboratories with commercial suppliers. Tokyo and Tsukuba industrial clusters host radiation-sterilization infrastructure and retort pouch development facilities serving both agency and commercial markets.
China
National space station resupply missions and crewed lunar program planning generate procurement for extended shelf-life formulations. SAMR food safety standards and GB standards for aerospace nutrition shape product certification pathways. Shanxi province hosts specialized space food manufacturing facilities supplying domestic crewed missions and international collaborative programs.
Germany
ESA microbiological safety protocols and REACH chemical safety registrations for packaging materials create dual compliance burdens for suppliers serving European programs. ECHA migration testing data requirements for food-contact materials accelerate fluoropolymer-free barrier film development. Cologne and Bremen aerospace clusters coordinate nutritional research with ESA astronaut training centers.
United Kingdom
Commercial spaceport development in Scotland and Cornwall generates emerging demand for suborbital flight catering solutions. UK Space Agency nutritional guidelines for domestic crewed programs align with ESA standards while permitting faster certification pathways. Harwell space cluster hosts formulation research linking university nutrition departments with packaging technology developers.
Space Food Market Competitive Landscape
Global majors compete with regional champions across preservation technology specialization and agency certification access. The market structures around three tiers: heritage aerospace contractors with multi-decade agency relationships, commercial food manufacturers diversifying into space-grade processing, and specialized startups targeting space tourism niches. Dominant competitive moves include strategic partnerships with launch operators for integrated mission support contracts and technology licensing for radiation-sterilization and freeze-drying process improvements.
Among Japanese manufacturers, Space Food Laboratory and Nissin Foods exemplify the heritage contractor archetype, leveraging decades of JAXA collaboration to sustain agency and commercial contracts. These Tokyo-based entities occupy positions where aerospace nutrition expertise intersects with commercial food processing scale. Onisi Foods represents the specialized preservation technology segment, with radiation-sterilized rice products anchoring Asian supply base positioning for zero-gravity consumption applications.
| Leading Market Players |
|---|
| Space Food Laboratory |
| Shanxi Shenzhou Space Food |
| Nissin Foods |
| Onisi Foods |
| Astronaut Foods |
| Morinaga Milk Industry |
| Mission: Space Food |
| The Space Foods Company |
| House Foods Corporation |
| Others |
Pricing and Supply Chain Analysis
NASA's tightened micronutrient density specifications for long-duration missions are forcing reformulation investments across the supplier base, compressing margins on legacy freeze-dried products while rewarding suppliers with certified radiation-sterilization capabilities. This specification pressure is reshaping procurement access and pricing power toward manufacturers with multi-agency certification portfolios.
Pricing Analysis
Aluminum-laminate and polymer film input costs fluctuate with petrochemical feedstock markets, driving margin compression on thermostabilized meal production. Pricing stratifies across Artemis-certified premium tiers, commercial space tourism standard tiers, and suborbital economy tiers differentiated by shelf-life duration and rehydration infrastructure requirements. Cost compression in the standard tier is intensifying as private launch operators in Texas and Florida bundle catering into integrated mission support packages. Space tourists exhibit the highest price sensitivity due to discretionary purchase framing, while astronaut training procurement at Kennedy Space Center shows inelastic demand for certified formulations.
Supply Chain Analysis
Specialized irradiation infrastructure workforce availability concentrates in Japan, China, and South Korea, anchoring Asian supply base dominance for radiation-sterilized natural form foods and vacuum-sealed containers. Manufacturing draws from polymer film laminates, aluminum barrier materials, and micronutrient premix concentrates as critical inputs. Single-source vulnerability in specialized irradiation capacity creates geographic concentration risk for Western manufacturers serving NASA and ESA contracts. Distribution runs through prime operator integrated mission support packages, compressing direct supplier access for smaller nutrition firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Space Food Market functions as a stable compounder anchored by Artemis program procurement scaling and commercial space tourism passenger volume growth. Institutional nutrition mandates and multi-year agency supply agreements generate predictable demand visibility.
For Market Incumbents: Anticipate margin pressure from plant protein isolate substitution trends by securing backward integration into freeze-drying infrastructure and accelerating fluoropolymer-free barrier film R&D for ECHA compliance. Defensive positioning requires deepening Johnson Space Center certification relationships while monitoring emerging space tourism channel consolidation in Texas and Florida. For New Entrants and Emerging Players: Private launch operator catering partnerships represent the most penetrable channel for bypassing prime operator bundling. White-space targets include psychological welfare natural form foods for extended Martian surface operations and electrolyte-optimized hydration gels for lunar habitat daily rations. A direct-to-operator sales model with simplified consumption protocols for microgravity novices offers viable go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized preservation technology firms holding JAXA or ESA certification heritage and scalable radiation-sterilization capacity. Long-term viability over a multi-year horizon favors suppliers with demonstrated lunar gravity adaptation formulation capabilities. The signal to watch is Artemis program tender announcements specifying water-recovery system integration requirements as an inflection indicator for rehydratable food segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Sterilization Capacity Expansion | Addresses geographic concentration risk in Asian supply bases while meeting NASA extended shelf-life mandates. |
| Fluoropolymer-Free Barrier Film Development | Accelerates ECHA REACH compliance for ESA contracts and eliminates migration testing data submission delays. |
| Plant Protein Isolate Formulation Pivot | Opens ESG-aligned procurement channels and extends stability profiles beyond animal-derived ingredient limitations. |
| Water-Recovery System Integration Partnership | Captures lunar habitat procurement prioritizing closed-loop life support infrastructure for Artemis missions. |
| Prime Operator Mission Support Bundling | Consolidates channel access in Florida and Texas as private launch operators scale passenger operations. |
Research Methodology
Multiple input streams — primary interviews with nutrition formulation directors, regulatory affairs specialists at Johnson Space Center, commercial launch operator procurement leads, and packaging technology developers; secondary validation through FDA food-contact material guidance documents, ECHA REACH registration databases, NASA nutritional standards publications, and JAXA food allergen management protocols; plus customs and trade flow data for polymer film and aluminum laminate imports — were reconciled through bottom-up segment sizing and top-down market triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling by product type, application mission profile, end-user category, and packaging format with regional regulatory cluster overlays. CAGRs were derived from segment-level growth trajectory analysis incorporating Artemis procurement scaling assumptions, commercial space tourism passenger volume curves, and preservation technology maturation timelines. Forecast inputs included freeze-drying equipment capacity expansion plans and radiation-sterilization facility utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Artemis program schedule shifts, commercial space tourism accident events, and multi-agency certification harmonization progress. Forecasts reflect documented assumptions regarding NASA nutritional specification stability and ESA microbiological protocol alignment. Material deviation in Artemis procurement timelines or private launch operator passenger scaling trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Miso Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Honey Spread Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Acacia Honey Market
Specialty Foods
United States Tofu Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Dog Food Toppers Market