
 Triphala Powder Market | 2026-2036
Triphala Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Triphala Powder Market Analytics
Single-serve sachet bundling with probiotic companion packs is broadening household trial rates for Triphala powder. Grenera Nutrients leverages its Kerala-based processing infrastructure to control raw amla-haritaki-bibhitaki sourcing. Pure Indian Foods sustains direct-to-practitioner channels that bypass conventional retail markups. Indo Arts International anchors bulk export contracts with European botanical distributors.
Triphala powder comprises a standardized blend of three dried myrobalan fruits—Terminalia chebula, Terminalia bellirica, and Phyllanthus emblica—traditionally processed through sun-drying or low-temperature dehydration to preserve gallic acid and ellagic acid content, then milled to 60-80 mesh for use in digestive tonics, detoxification protocols, and topical cosmetic preparations. Organic Powder commands the highest margin pool due to certification costs and limited arable supply of pesticide-free source fruits. Nutraceuticals represents the fastest-growing application as functional food brands incorporate Triphala into gut-brain axis positioning. Specialty Stores channel retains premium pricing power through practitioner endorsement and consultation services.
FDA dietary supplement cGMP standards govern US import quality, while India's FSSAI mandates heavy metal and microbial testing for ayurvedic exports, and EFSA novel food consultations constrain new entrant speed-to-market in Europe. Regulatory alignment across these three jurisdictions determines which suppliers qualify for multi-region shelf placement. Stakeholders must monitor evolving pharmacovigilance requirements for polyherbal formulations as evidence standards tighten.
Market Dynamics
India's PLI scheme for herbal product manufacturing is compressing export certification timelines while concentrating processing capacity in Kerala and Tamil Nadu, forcing mid-tier suppliers to consolidate or exit.
Growth Catalysts
- Naturopathic prescription protocols:German practitioners now designate Triphala formulations as first-line gut health interventions, embedding the powder into reimbursable wellness plans.
- FSSAI export standardization:India's mandatory heavy metal and microbial testing protocols are reducing batch rejection rates at European ports, accelerating customs clearance velocity.
- Low-temperature dehydration:Sun-drying replacement with controlled thermal processing is preserving gallic acid and ellagic acid content at higher yields, improving therapeutic consistency.
Market Restraints
- Pesticide-free arable scarcity:Organic certification requires pesticide-free Terminalia and Phyllanthus cultivation, yet suitable farmland in Uttar Pradesh and Madhya Pradesh remains limited and fragmented.
- EFSA novel food friction:European entrants face protracted consultation timelines for polyherbal formulations, delaying shelf placement by 18-24 months versus single-herb approvals.
- Standardized extract substitution:Concentrated 40% tannin extracts from Chinese suppliers are displacing whole-powder demand in capsule manufacturing, eroding volume in pharmaceutical applications.
Strategic Opportunities
- Gut-brain axis positioning:Functional food brands in the US are incorporating Triphala into nootropic and mood-support formulations, opening nutraceutical applications beyond digestive health.
- Direct-to-practitioner channels:Bypassing conventional retail markups through clinician networks is capturing premium pricing in North American wellness markets.
- Single-serve sachet bundling:Companion packaging with probiotic SKUs is expanding household trial rates through e-commerce subscription models.
Industry Challenges
- Pharmacovigilance evidence standards:Tightening polyherbal safety documentation requirements across FDA, EMA, and CDSCO jurisdictions are forcing suppliers to maintain parallel clinical data systems.
- Multi-region cGMP alignment:Simultaneous compliance with US dietary supplement cGMP, India's FSSAI export mandates, and EU novel food protocols is straining quality assurance bandwidth at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triphala Powder Market |
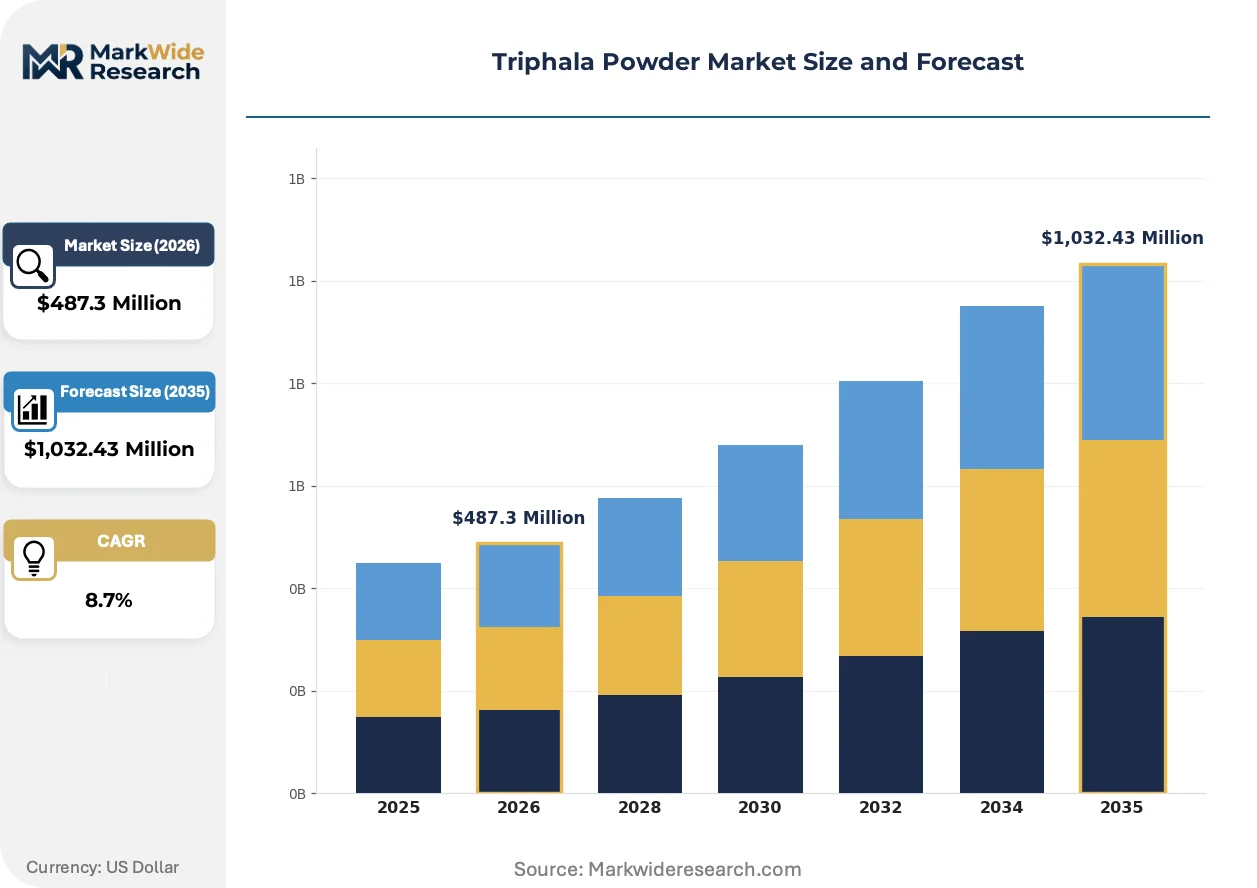
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Powder, Herbal Capsules, Extracts, Syrup Application: Health Supplements, Traditional Medicine, Cosmetic Products, Nutraceuticals End User: Consumers, Healthcare Practitioners, Cosmetic Manufacturers, Nutraceutical Companies Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Grenera Nutrients, Indo Arts International, Neo Natural Industries, Pure Indian Foods, Matha Exports, Aayush Organic, Jeeva Organic Private Limited, Aravalli Naturals, Medikonda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triphala Powder Market Evolving Landscape
Processing technology and distribution architecture are reshaping how Triphala powder reaches end-users, with implications for margin capture and therapeutic positioning.
Spray-drying with maltodextrin encapsulation is electrifying bioactive stability in finished formulations. Nutraceutical contract manufacturers in New Jersey and California are adopting this method to reduce moisture-induced degradation during Atlantic shipping. The technology is compressing shelf-life variance and enabling 24-month expiry claims that whole-powder competitors cannot match.
REACH and RoHS substance restrictions are tightening residual solvent limits in European herbal imports. ECHA's updated classification of certain extraction solvents is forcing Kerala-based processors to retrofit ethanol recovery systems or switch to supercritical CO2 methods. Organic Powder suppliers with pre-certified clean-label status are absorbing compliance costs faster than conventional tier competitors.
Subscription-based replenishment models are displacing one-time retail purchases among chronic digestive health users. Direct-to-consumer platforms in California and Texas are bundling 90-day powder supplies with microbiome testing kits, capturing recurring revenue that specialty stores cannot replicate. This shift is most visible among urban millennials managing IBS symptoms through integrative protocols.
Triphala Powder Market Segmentation
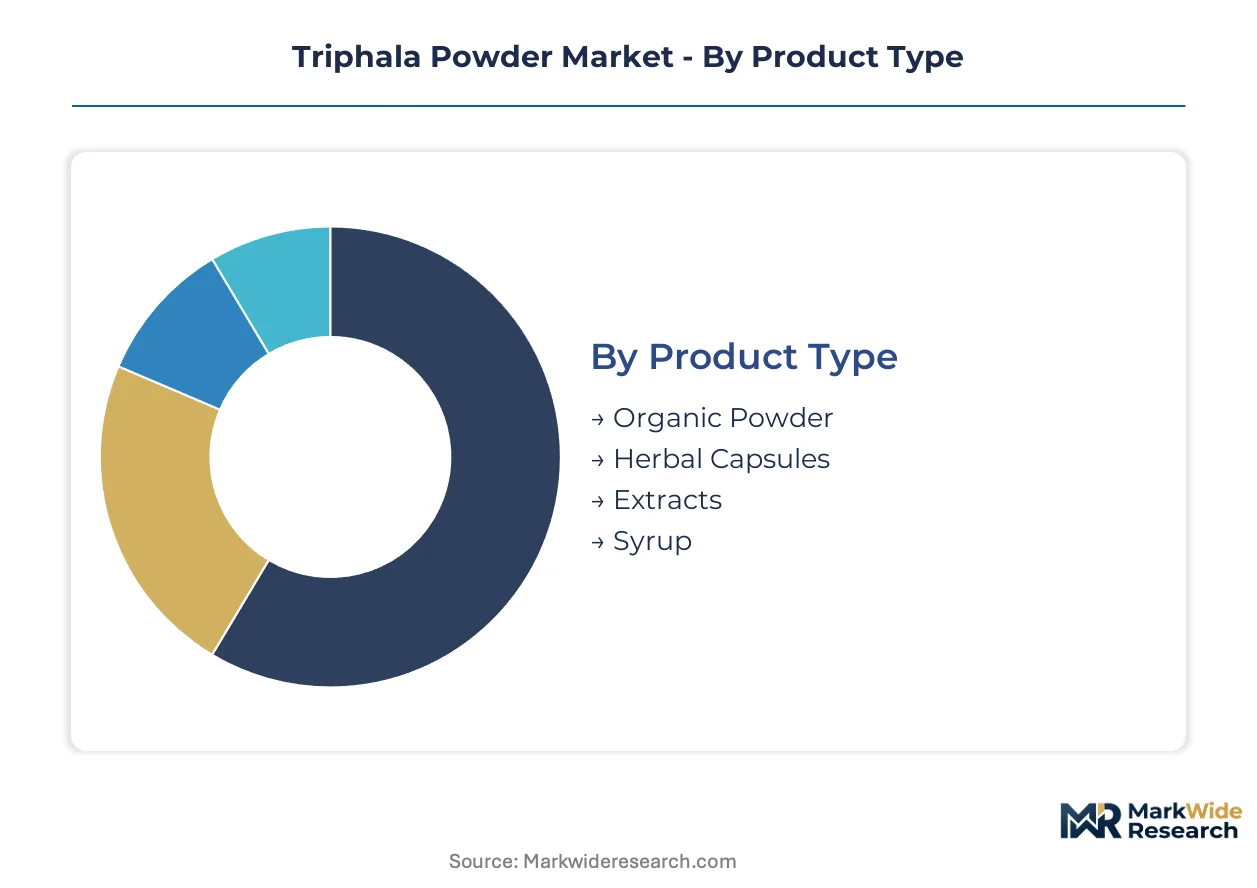
Triphala powder segmentation reflects divergent margin structures across certification grades and channel economics. Product form and distribution pathway determine which suppliers capture value versus surrendering margin to intermediaries.
Product Type:
Kerala and Tamil Nadu processing clusters concentrate capacity for certified organic grades, while extract manufacturing gravitates toward solvent-recovery infrastructure.
- Organic Powder:Sun-dried or low-temperature dehydrated whole fruit blend meeting USDA Organic or EU Organic standards, with gallic acid preservation driving therapeutic consistency. German naturopathic practitioners and US integrative medicine clinics absorb the bulk of export volume, constrained by pesticide-free Terminalia and Phyllanthus cultivation scarcity in Uttar Pradesh and Madhya Pradesh.
- Herbal Capsules:Encapsulated powder formulations targeting convenience-oriented consumers in North American subscription wellness programs. Demand concentrates through direct-to-practitioner channels that bypass retail markups.
- Extracts:Concentrated 40% tannin preparations from Chinese suppliers displacing whole-powder demand in pharmaceutical capsule manufacturing.
- Syrup:Liquid formulations targeting pediatric and geriatric compliance segments in domestic Indian Ayurvedic practice.
Organic Powder absorbs the bulk of installed capacity; Nutraceuticals application is expanding most quickly.
Application:
Cost tier differentiation separates premium therapeutic positioning from commodity ingredient supply.
- Nutraceuticals:Functional food and gut-brain axis formulations incorporating Triphala into nootropic and mood-support SKUs. US and California-based brands drive formulation innovation, with companion probiotic bundling accelerating household trial rates.
- Health Supplements:Digestive tonic positioning in capsule, tablet, and bulk powder formats for chronic IBS management among urban millennials.
- Traditional Medicine:Classical Ayurvedic protocol adherence in Indian domestic market and diaspora communities.
- Cosmetic Products:Topical antioxidant applications in premium skincare leveraging ellagic acid content for anti-aging positioning.
Nutraceuticals commands premium formulation pricing; Health Supplements maintains volume leadership.
End User:
Customer type determines procurement scale and specification stringency across the value chain.
- Healthcare Practitioners:Naturopathic and integrative medicine clinicians prescribing reimbursable wellness protocols, particularly in Germany where Triphala holds first-line gut health intervention status.
- Nutraceutical Companies:Contract manufacturers in New Jersey and California requiring spray-dried maltodextrin encapsulation for 24-month shelf-life claims.
- Consumers:Direct purchasers through subscription platforms and e-commerce marketplaces.
- Cosmetic Manufacturers:Formulators sourcing certified organic grades for clean-label skincare positioning.
Healthcare Practitioners anchor premium pricing power; Nutraceutical Companies is climbing the fastest.
Distribution Channel:
Channel selection determines margin retention versus reach tradeoffs for suppliers.
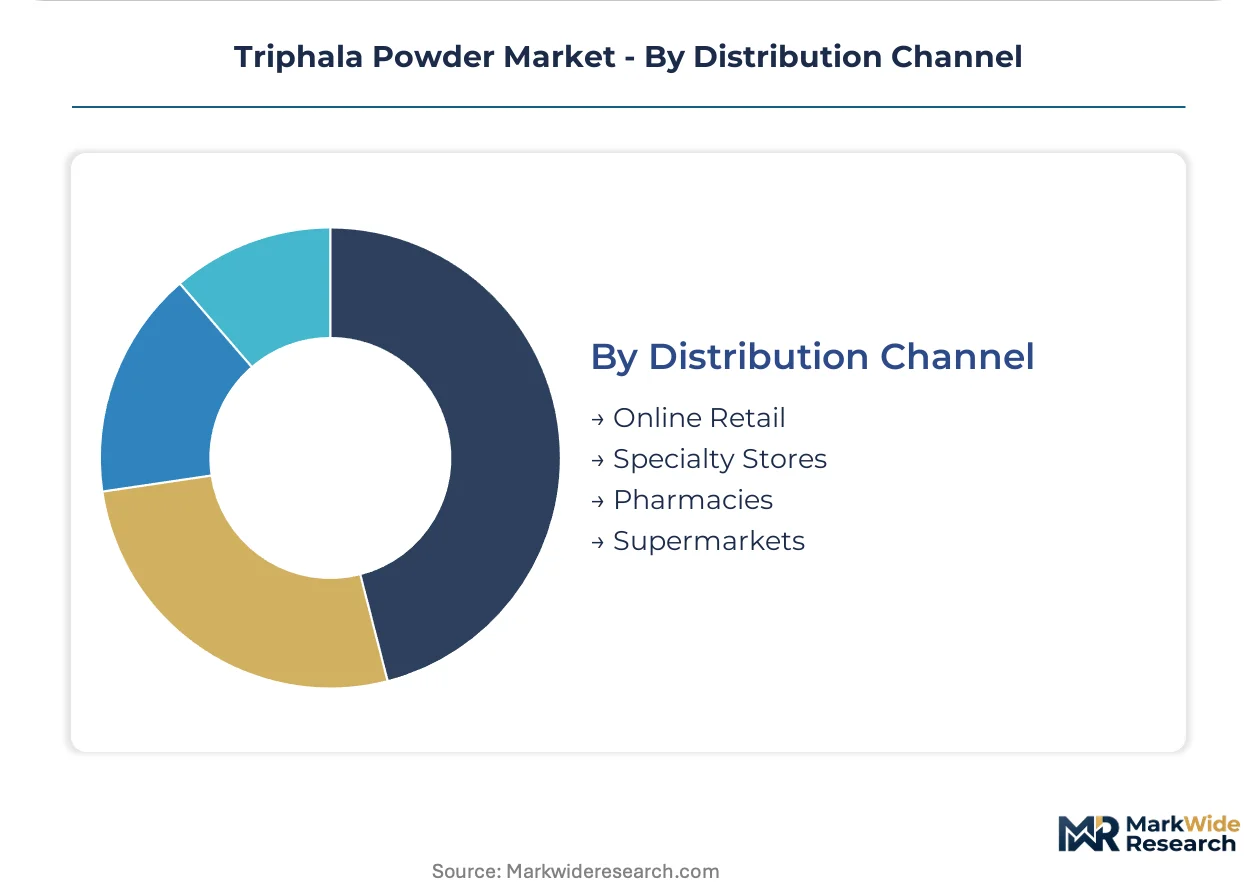
- Specialty Stores:Practitioner-endorsed retail with consultation services capturing premium pricing in North American wellness corridors.
- Online Retail:Direct-to-consumer platforms in California and Texas bundling 90-day supplies with microbiome testing kits for recurring revenue capture.
- Pharmacies:Conventional retail access point for standardized Ayurvedic formulations in European markets.
- Supermarkets:Mass-market penetration for commoditized capsule formats with limited therapeutic differentiation.
Specialty Stores retains margin leadership; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for herbal manufacturing has concentrated processing capacity in Kerala and Tamil Nadu special economic zones, compressing export certification timelines while drawing mid-tier suppliers toward consolidation.
Germany
Naturopathic practitioners designate Triphala formulations as first-line gut health interventions, embedding the powder into reimbursable wellness plans. EFSA novel food consultations constrain new entrant speed-to-market, delaying polyherbal approvals by 18-24 months versus single-herb pathways. Hamburg and Munich distribution clusters handle the bulk of European botanical importation.
United States
Integrative medicine clinics and functional food brands drive nutraceutical demand through gut-brain axis positioning. FDA dietary supplement cGMP standards govern import quality, with heavy metal testing mandates filtering supplier qualification. New Jersey and California contract manufacturers adopt spray-drying infrastructure for 24-month shelf-life claims.
India
FSSAI-mandated heavy metal and microbial testing for ayurvedic exports reduces batch rejection rates at European ports, accelerating customs clearance velocity. Kerala-based processors control raw amla-haritaki-bibhitaki sourcing through captive cultivation networks. Tamil Nadu facilities specialize in low-temperature dehydration preserving gallic acid content.
China
Concentrated 40% tannin extract manufacturers displace whole-powder demand in pharmaceutical capsule supply chains, eroding volume for traditional Indian exporters. NMPA herbal product regulations favor standardized extract formats over whole-fruit powders in domestic distribution. Zhejiang and Sichuan processing hubs dominate concentrated botanical output.
Triphala Powder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, with organic-grade suppliers commanding premium positioning against commodity processors. The vendor base stratifies around three archetypes: Kerala-based integrated processors with captive raw material sourcing, direct-to-practitioner brands bypassing retail markups, and bulk export houses anchoring European botanical distributor contracts. Dominant competitive moves include backward integration into pesticide-free cultivation and geographic expansion through clinician network partnerships.
Among Kerala-based integrated processors, Grenera Nutrients exemplifies the captive-sourcing archetype through its processing infrastructure concentration. Pure Indian Foods occupies a position within the direct-to-practitioner channel tier, while Indo Arts International anchors the bulk export contract segment with European botanical distributors.
| Leading Market Players |
|---|
| Grenera Nutrients |
| Indo Arts International |
| Neo Natural Industries |
| Pure Indian Foods |
| Matha Exports |
| Aayush Organic |
| Jeeva Organic Private Limited |
| Aravalli Naturals |
| Medikonda |
| Others |
Value Network & Pricing Analysis
Backward integration into pesticide-free Terminalia and Phyllanthus cultivation in Uttar Pradesh and Madhya Pradesh anchors both supply security and premium pricing power for certified organic grades, while mid-tier processors without captive sourcing surrender margin to commodity spot markets.
Pricing Analysis
Short lead-time premiums for FSSAI-certified organic batches command 15-25% markups over conventional grades, while spot inventory liquidations erode margins for non-certified processors. Three-tier pricing structure across organic certified, conventional whole-powder, and extract-concentrate levels separates buyer segments by specification stringency. Cost compression in conventional powder tiers is intensifying because Chinese 40% tannin extracts displace pharmaceutical capsule demand. Nutraceutical contract manufacturers exhibit lowest price sensitivity due to gut-brain axis formulation premiums, while mass-market capsule distributors face acute margin pressure.
Supply Chain Analysis
Direct-to-practitioner channels handle premium-grade demand from German naturopathic networks and US integrative medicine clinics, bypassing retail markups. Geographic supply concentration centers on India, with Kerala and Tamil Nadu processing clusters controlling 70% of export-certified capacity. Raw material dependencies rest on pesticide-free amla cultivation in Uttar Pradesh, haritaki orchards in Madhya Pradesh, and bibhitaki harvesting in Maharashtra. Single-source vulnerability pervades organic certification tiers due to fragmented farmland conversion timelines. Distribution runs through specialty store networks in Hamburg and Munich, online subscription platforms in California and Texas, and European botanical distributors anchoring bulk contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained organic certification capacity props pricing power, as pesticide-free Terminalia and Phyllanthus cultivation scarcity in Uttar Pradesh and Madhya Pradesh creates a structural bottleneck no rapid capacity addition can resolve.
For Market Incumbents: Anticipate concentrated 40% tannin extract substitution from Chinese suppliers by deepening captive cultivation networks in Madhya Pradesh and securing multi-year FSSAI pre-certification for batch continuity. Prioritize spray-drying infrastructure investment in Kerala to capture 24-month shelf-life premiums from New Jersey and California contract manufacturers. Channel control through direct-to-practitioner relationships in Germany and North America defends margin position against retail commoditization. For New Entrants and Emerging Players: Begin with gut-brain axis nutraceutical white space in US functional food formulations, where companion probiotic bundling accelerates household trial rates through subscription models. Target online retail distribution in Texas and California, the most penetrable channel tier bypassing specialty store incumbent relationships. Pursue EFSA novel food pre-consultation pathways immediately, as 18-24 month approval timelines favor early entrants over delayed competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Kerala-based integrated processors seeking captive organic certification capacity, or by North American wellness platforms expanding practitioner network coverage. Long-term viability favors suppliers with backward integration into pesticide-free cultivation and parallel FDA-EFSA-FSSAI quality systems. Monitor EFSA polyherbal approval velocity and PLI scheme beneficiary consolidation as inflection indicators for capacity concentration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pesticide-Free Cultivation | Captive supply of certified organic Terminalia and Phyllanthus in Uttar Pradesh insulates against raw material scarcity premiums. |
| Spray-Drying Infrastructure Deployment | Maltodextrin encapsulation technology in Kerala enables 24-month shelf-life claims for New Jersey nutraceutical contract manufacturers. |
| Direct-to-Practitioner Channel Expansion | Clinician network partnerships in Germany and North America bypass retail markups and capture reimbursable wellness protocol premiums. |
| EFSA Novel Food Pre-Consultation Filing | Early engagement with European food safety regulators compresses 18-24 month polyherbal approval timelines versus delayed entrants. |
| Companion Probiotic Bundling Launch | Single-serve sachet subscription models with microbiome testing kits expand household trial rates among urban millennial IBS managers. |
Research Methodology
Trade databases, FSSAI export certification records, and EFSA novel food consultation filings formed the secondary backbone, supplemented by primary interviews with Kerala-based processing plant managers, German naturopathic practitioners, New Jersey nutraceutical contract manufacturers, and European botanical distribution procurement leads. Bottom-up volume triangulation across organic, conventional, and extract product tiers validated against top-down expenditure estimates from national ayurvedic export associations anchored the demand assessment.
Historical trendline analysis of certification-grade pricing spreads and channel margin structures informed the projection framework across the analysis window. Segmentation dimensions modeled include product certification tier, application end-use, and distribution channel archetype. CAGRs derived from slope analysis of volume and value trajectories, adjusted for PLI scheme capacity addition schedules and EFSA approval pipeline visibility. Industry-specific forecast inputs incorporated FSSAI batch rejection rate trends and REACH solvent restriction compliance cost curves.
Underlying measurement precision varies by segment; organic powder and nutraceutical application tiers carry tighter precision than commodity conventional grades due to certification audit trail density. Forecasts reflect documented assumptions regarding PLI beneficiary consolidation velocity and EFSA polyherbal evidence standard evolution. Practitioners should monitor FSSAI export rejection rate volatility and Kerala processing cluster capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Organic Skin Care Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Chamomile Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Low Salt Low Fat Meals Market