
 Natural Food Colors and Flavors Market | 2026-2036
Natural Food Colors and Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Colors and Flavors Market Foresight
Premium-grade certified organic extracts is rotating the competitive landscape toward higher-margin formulations. Givaudan leverages its integrated botanical supply network across multiple continents to secure rare raw material streams. Kerry Group anchors European beverage sector partnerships through specialized extraction facilities in Ireland and continental manufacturing sites. Sensient Technologies Corporation differentiates via advanced encapsulation technologies that stabilize heat-sensitive natural pigments for bakery applications.
Natural food colors and flavors comprise pigments, volatile aromatic compounds, and taste-active molecules extracted from plant, fungal, or mineral sources using solvent extraction, steam distillation, or cold-pressing methods, with specifications typically requiring minimum color intensity values and residual solvent limits below regulatory thresholds. These ingredients serve primarily to replace synthetic additives in packaged foods while meeting consumer clean-label expectations and regulatory purity standards. The colors segment dominates current volume as reformulation mandates from major retailers drive replacement of azo dyes with anthocyanin and curcumin alternatives. Source segmentation reveals vegetables and fruits capturing expanding share as beetroot and spirulina concentrates achieve cost parity with synthetic benchmarks in beverage applications. Application demand concentrates in beverages where transparent ingredient declarations carry the highest consumer willingness-to-pay premium.
The FDA maintains strict identity standards for natural flavoring substances under Code of Federal Regulations Title 21 while the EPA oversees agricultural pesticide residues affecting botanical raw material qualification. EFSA enforces purity specifications through its flavoring group evaluation program and novel food authorization pathways for non-traditional plant sources. India's FSSAI and CDSCO implement increasingly stringent contaminant limits on imported natural colorants under harmonized BIS standards. Stakeholders must monitor evolving positive list revisions across FDA, EFSA, and Asian regulators to anticipate formulation compliance costs and raw material qualification timelines.
Market Dynamics
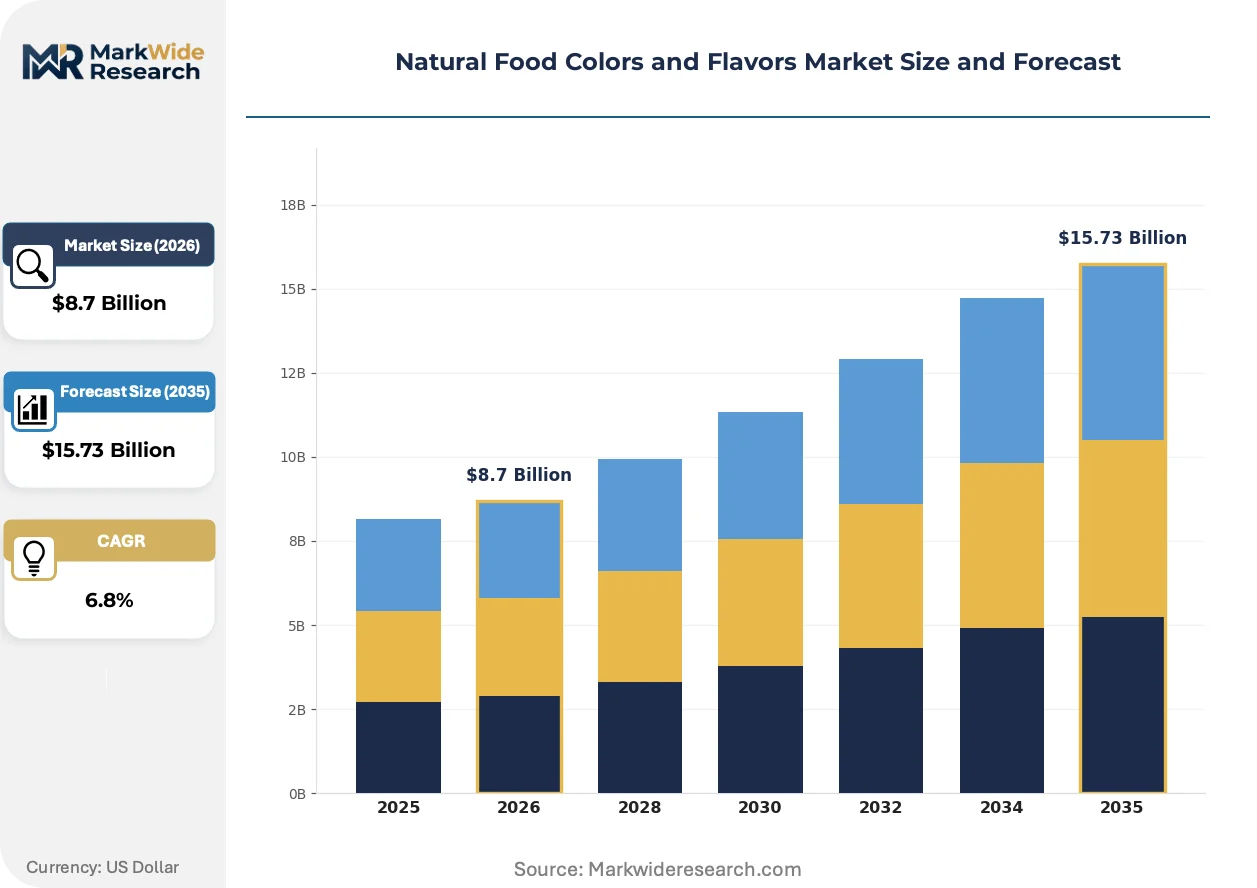
Clean-label procurement mandates from major beverage retailers are compressing synthetic-to-natural reformulation timelines, forcing ingredient suppliers to scale botanical extraction capacity ahead of contracted volume ramps.
Growth Catalysts
- EU Green Deal additive restrictions:REACH compliance deadlines are redirecting European formulation budgets toward plant-derived colorants ahead of 2030 phase-out targets.
- Beverage sector clean-label adoption:Transparent ingredient declarations now command measurable willingness-to-pay premiums in functional drinks and premium soft drinks.
- Germany processing hub concentration:Ingredient manufacturers cluster around Hamburg and Frankfurt extraction facilities, reducing logistics costs for continental distribution.
Market Restraints
- Agricultural input cost volatility:Weather-driven beetroot and spirulina harvest variability creates raw material price instability for concentrated pigments.
- Single-source supply concentration:Rare botanical extracts depend on limited cultivation regions, exposing buyers to geopolitical and climate disruption.
- Thermal stability technical limitations:Anthocyanin pigments degrade above 85°C, restricting deployment in high-temperature bakery and extrusion applications.
Strategic Opportunities
- India regulatory harmonization:FSSAI and CDSCO contaminant limit alignment with BIS standards creates qualified supplier entry pathways for imported natural colorants.
- Encapsulation technology convergence:Advanced lipid and polymer encapsulation methods combined with spray-drying are extending heat-sensitive pigment viability into processed foods.
- Direct-to-manufacturer digital channels:B2B ingredient platforms are disintermediating traditional distributor networks for mid-scale beverage formulators.
Industry Challenges
- Novel food authorization timelines:EFSA evaluation pathways for non-traditional plant sources extend raw material qualification cycles by 18-24 months.
- Cross-regulatory compliance complexity:Divergent FDA identity standards, EFSA purity specifications, and Asian positive list revisions multiply formulation testing burdens.
- Specialized extraction workforce scarcity:Botanical processing facilities face recruitment gaps in phytochemistry and supercritical CO2 operation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Colors and Flavors Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Colors, Flavors, Extracts, Emulsifiers Source: Fruits, Vegetables, Spices, Herbs Application: Beverages, Snacks, Dairy, Bakery Form: Powder, Liquid, Gel, Paste |
| Companies Covered | Givaudan, International Flavors & Fragrances, Archer Daniels Midland, Kerry Group, Firmenich, Sensient Technologies Corporation, Symrise, Chr. Hansen Holding, Döhler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Colors and Flavors Market Shifts & Advancements
Extraction and stabilization technologies are compressing the cost-performance gap between natural and synthetic additives while regulatory harmonization efforts reshape qualification pathways across major markets.
Supercritical CO2 extraction equipment is miniaturizing from industrial-scale installations to modular skid-mounted systems deployable at regional processing hubs. Mid-scale ingredient suppliers in Ireland and the Netherlands are adopting these units to reduce solvent residue risks and shorten batch qualification times. This distributed processing architecture is compressing lead times for heat-sensitive carotenoid and anthocyanin concentrates.
EFSA's flavoring group evaluation program is tightening purity specifications for botanical extracts through systematic re-evaluation of existing approvals. The industrial consequence is elevated analytical testing requirements for pesticide residues and heavy metals at the raw material intake stage. Beverage applications face the most acute compliance pressure due to higher consumer exposure assumptions in liquid consumption patterns.
Retail procurement teams are consolidating supplier panels around vertically integrated botanical processors with captive cultivation and extraction capabilities. This supplier base reduction is displacing fragmented trading-house intermediaries in European and North American supply chains. Germany and California demonstrate the most advanced buyer concentration, with three to four preferred suppliers capturing majority share in premium beverage formulations.
Natural Food Colors and Flavors Market Segmentation
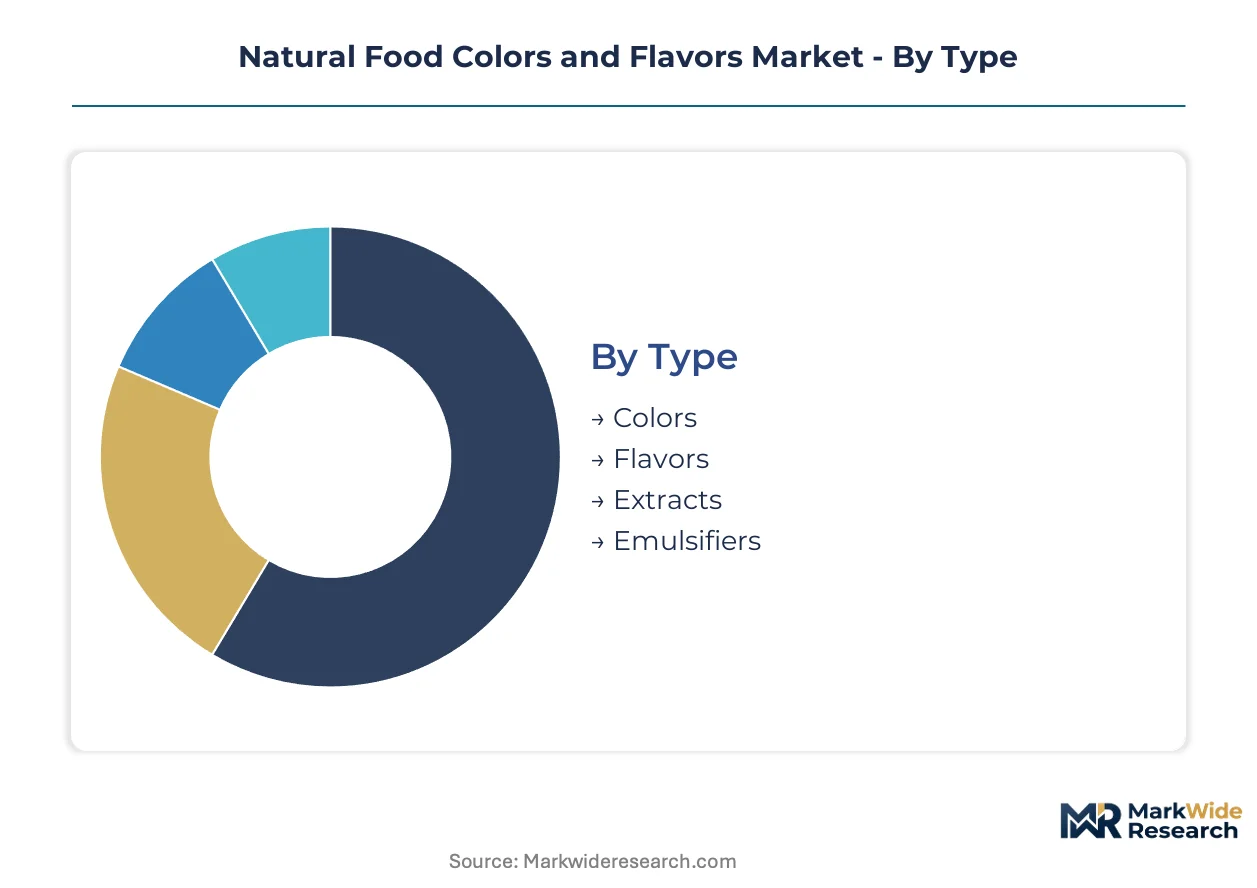
Segmentation in natural food colors and flavors determines regulatory qualification pathways, extraction technology selection, and formulation compatibility. Each dimension carries distinct compliance burdens and margin structures that reshape competitive positioning across supplier tiers.
Type:
FDA identity standards under 21 CFR distinguish natural colors from flavors in labeling declarations, while EFSA's flavoring group evaluation program imposes divergent purity specifications on each category.
- Colors:Pigments including anthocyanins, carotenoids, and curcuminoids deliver hue intensity measured by spectral absorption values. Beverage reformulation in Germany and California concentrates procurement here as retailers mandate synthetic dye replacement. Heat sensitivity above 85°C restricts bakery deployment without encapsulation.
- Flavors:Volatile aromatic compounds and taste-active molecules extracted via steam distillation or cold-pressing. Clean-label adoption in functional drinks drives premium pricing for certified organic variants with full traceability documentation.
- Extracts:Concentrated botanical preparations combining color and flavor compounds. Kerry Group's Irish facilities specialize in multi-component extracts for complex beverage formulations.
- Emulsifiers:Natural lecithin and acacia-derived stabilizers enabling oil-water dispersion in flavored beverages.
Established volume favors Colors; emerging adoption favors Flavors.
Source:
Raw material provenance dictates pesticide residue testing burdens under EPA and EFSA agricultural input regulations, with tropical sources facing elevated mycotoxin screening.
- Fruits:Anthocyanin-rich berries and grape skins supply heat-sensitive red-purple pigments. Spirulina concentrates from controlled cultivation achieve cost parity with synthetic benchmarks in German beverage processing hubs.
- Vegetables:Beetroot concentrates dominate red colorant volumes with betalain stability superior to anthocyanins in neutral pH applications. Weather-driven harvest variability creates price instability for concentrated pigments.
- Spices:Turmeric-derived curcumin and paprika oleoresin deliver intense yellow-orange hues with established GRAS status.
- Herbs:Chlorophyll extracts and specialized aromatic compounds from mint, basil, and rosemary supply niche green coloration and herbal flavor profiles.
Vegetable sourcing anchors current supply; fruit-derived concentrates are climbing the fastest on clean-label beverage demand.
Application:
Thermal processing requirements separate low-heat beverage applications from high-temperature bakery and extrusion environments where pigment degradation risks multiply.
- Beverages:Liquid consumption patterns assume higher consumer exposure, intensifying EFSA contaminant limits for pesticide residues and heavy metals. Transparent ingredient declarations here command measurable willingness-to-pay premiums.
- Snacks:Seasoning applications favor oil-dispersible forms with enhanced light stability for transparent packaging exposure.
- Dairy:pH stability requirements in fermented products favor carotenoid pigments over anthocyanins.
- Bakery:Thermal degradation above 85°C restricts anthocyanin deployment without Sensient Technologies' advanced encapsulation stabilization.
Beverage applications concentrate current formulation budgets; bakery represents the steepest expansion trajectory as encapsulation technologies mature.
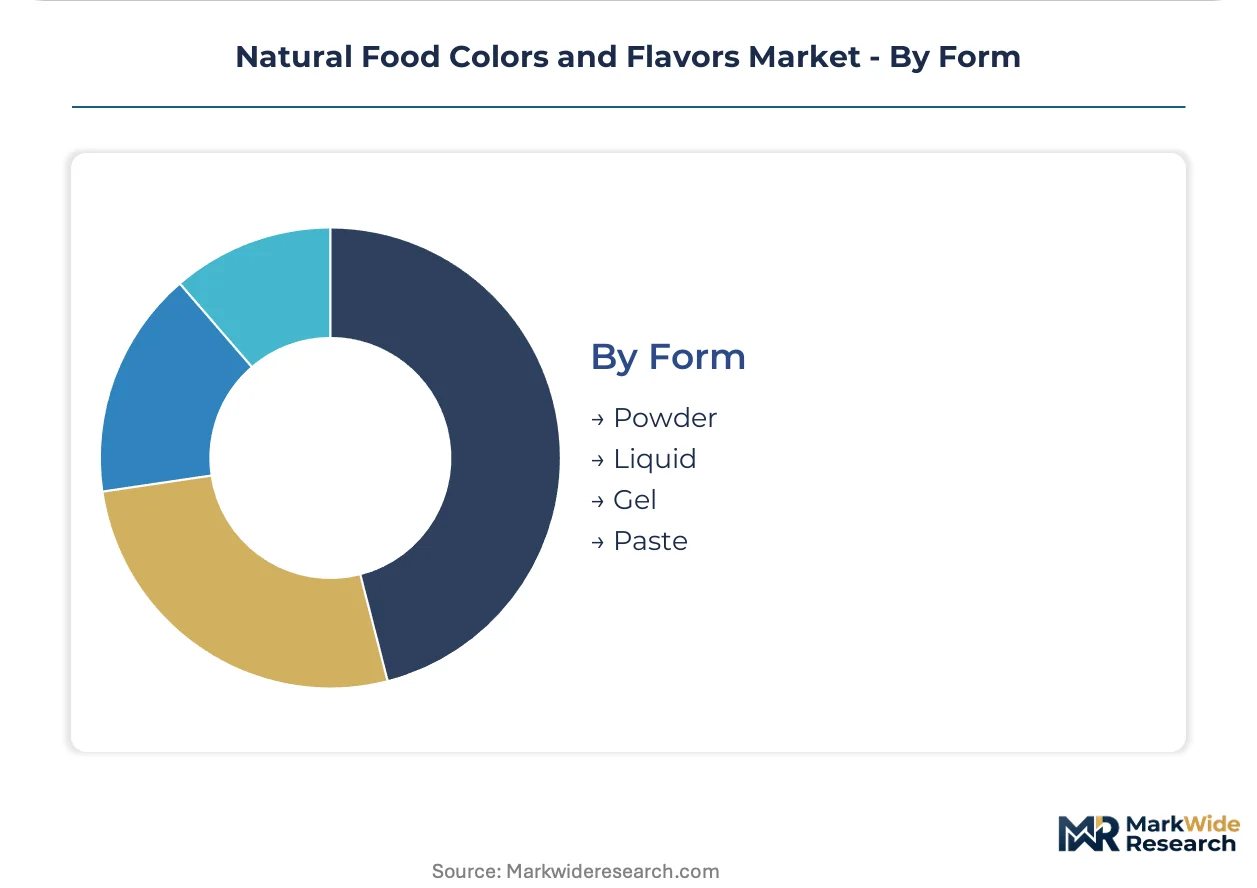
Form:
Physical state determines logistics economics, shelf stability, and manufacturing integration complexity across dispersed processing networks.
- Powder:Spray-dried concentrates minimize transportation costs and extend shelf life through reduced water activity. Preferred for dry blend beverage mixes and seasoning applications.
- Liquid:Direct-pumpable formats reduce manufacturing step complexity for high-volume beverage bottling operations in Hamburg and Frankfurt extraction corridors.
- Gel:Viscous suspensions optimize dosing precision in artisanal and small-batch confectionery applications.
- Paste:High-solids concentrates for industrial-scale bakery and dairy compound manufacturing.
Powder forms dominate long-distance supply; liquid concentrates gain share fastest in regional hub-and-spoke distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient extraction capacity clusters around specialized processing hubs in Germany, Ireland, and the Netherlands where supercritical CO2 infrastructure serves continental beverage formulators. Regional procurement patterns diverge sharply between EU REACH compliance deadlines and FDA identity standards, creating divergent qualification timelines for botanical suppliers.
Germany
Hamburg and Frankfurt anchor continental extraction capacity for beetroot concentrates and spirulina-derived pigments. REACH compliance deadlines ahead of 2030 phase-out targets redirect formulation budgets toward plant-derived colorants. The Hamburg processing corridor concentrates mid-scale suppliers serving premium beverage brands across Northern Europe.
United States
California demonstrates the most advanced buyer concentration with preferred suppliers capturing majority share in premium beverage formulations. FDA identity standards under 21 CFR distinguish natural colors from flavors in labeling declarations. Regional procurement teams consolidate supplier panels around vertically integrated botanical processors with captive cultivation capabilities.
India
FSSAI and CDSCO implement increasingly stringent contaminant limits on imported natural colorants under harmonized BIS standards. Regulatory harmonization creates qualified supplier entry pathways for botanical extracts meeting export specifications. Maharashtra and Gujarat host processing facilities targeting European and North American qualification requirements.
Netherlands
Mid-scale ingredient suppliers adopt modular skid-mounted supercritical CO2 systems to reduce solvent residue risks. EFSA flavoring group evaluation program tightening drives elevated analytical testing for pesticide residues at raw material intake. The Rotterdam-Antwerp corridor specializes in oil-dispersible forms for seasoning applications.
France
ANSM and CNIL frameworks intersect with EU Green Deal additive restrictions in pharmaceutical-adjacent food ingredient applications. Paris-based procurement teams prioritize certified organic variants with full traceability documentation. The Lyon-Grenoble axis concentrates extraction expertise for heat-sensitive carotenoid concentrates.
Natural Food Colors and Flavors Market Competitive Landscape
Concentration sits with vertically integrated botanical processors controlling captive cultivation and extraction capabilities. The supplier base compresses around three to four preferred suppliers per major beverage formulation hub. Two strategic archetypes dominate: multinational flavor houses with integrated botanical supply networks, and specialized extraction facilities with regional hub positioning. Competitive moves center on backward integration into rare raw material streams and technology licensing for encapsulation stabilization.
Within the multinational flavor house tier, Givaudan and International Flavors & Fragrances occupy positions defined by integrated botanical supply networks across multiple continents. Kerry Group anchors European beverage sector partnerships through specialized extraction facilities in Ireland. Sensient Technologies Corporation exemplifies the technology-differentiated archetype through advanced encapsulation capabilities. These three represent distinct competitive positioning vectors: raw material security, regional hub concentration, and processing technology specialization.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Archer Daniels Midland |
| Kerry Group |
| Firmenich |
| Sensient Technologies Corporation |
| Symrise |
| Chr. Hansen Holding |
| Döhler |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between beetroot concentrate processors and German beverage formulators lock in multi-year supply access while capping price volatility exposure against weather-driven harvest fluctuations. These arrangements concentrate procurement power among vertically integrated suppliers operating Hamburg and Frankfurt extraction hubs, compressing margins for spot-market dependent traders.
Pricing Analysis
REACH compliance deadlines dictate the pricing tier structure across European natural colorant procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified organic extracts with full traceability documentation from conventional grades and unqualified imports. Cost compression in economy-tier spirulina concentrates is intensifying because Indian suppliers face elevated FSSAI testing burdens before export qualification. Beverage formulators demonstrate highest price sensitivity due to reformulation volume scale, while premium confectionery buyers absorb organic certification premiums with minimal negotiation.
Supply Chain Analysis
Spirulina cultivation concentration in Maharashtra and Gujarat underwrites pigment supply security for European beverage processors despite monsoon-driven harvest variability. The supply chain draws from beetroot farming cooperatives in Germany, turmeric cultivation belts in India, and paprika oleoresin extraction facilities in Spain. Single-source vulnerability concentrates in rare anthocyanin extracts dependent on specific berry cultivars grown in limited Polish and Ukrainian regions. Distribution runs through Rotterdam-Antwerp corridor consolidation points serving continental seasoning and beverage compound manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical agricultural input cost compression as EU Green Deal implementation timelines force accelerated synthetic-to-natural reformulation budgets. The recovery trajectory rests on sustained regulatory pressure rather than discretionary consumer preference alone.
For Market Incumbents: Shield formulation partnerships through captive cultivation investments in German beetroot cooperatives and Indian spirulina ponds. Secure supercritical CO2 extraction capacity ahead of contracted volume ramps from mid-scale beverage brands. Prioritize EFSA flavoring group evaluation program pre-submissions to compress novel extract qualification cycles against emerging botanical traders. For New Entrants and Emerging Players: Differentiate on modular supercritical CO2 skid deployment serving regional Netherlands and Ireland processing hubs underserved by industrial-scale incumbents. Target bakery encapsulation applications where Sensient Technologies' patent positions create technology licensing opportunities for heat-stabilized anthocyanin concentrates. Pursue direct-to-manufacturer digital channels disintermediating traditional distributor networks for mid-scale beverage formulators. For Investors and Strategic Acquirers: Regional extraction specialists with captive spirulina cultivation and EFSA pre-qualified ingredient portfolios represent priority acquisition targets. Long-term viability over the coming decade hinges on backward integration depth rather than trading-house margin capture. Watch EFSA novel food authorization pathway backlog clearance rates as the inflection signal for raw material qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | German processors securing beetroot cooperative contracts eliminate weather-driven price volatility exposure. |
| Encapsulation Technology Licensing | Heat-sensitive anthocyanin stabilization unlocks bakery segment expansion beyond beverage concentration. |
| EFSA Pre-Qualification Investment | Novel extract submissions ahead of competitor filing dates compress 18-24 month authorization windows. |
| Modular Supercritical CO2 Deployment | Regional hub processing reduces solvent residue risks and shortens batch qualification times for mid-scale suppliers. |
| Direct-to-Manufacturer Digital Channel Buildout | B2B platform disintermediation captures margin from fragmented trading-house intermediaries in European supply chains. |
Research Methodology
A standing panel of extraction facility operations managers, beverage formulation chemists, procurement directors at German retailers, and EFSA regulatory affairs specialists provided ongoing calibration against secondary validation from FDA 21 CFR filings, EFSA flavoring group evaluation registers, BIS contaminant limit notifications, and customs trade data on botanical extract imports. Bottom-up volume modeling across type, source, application, and form segments triangulated with top-down macroeconomic anchor checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across colors versus flavors versus extracts, vegetable versus fruit versus spice sourcing, beverage versus bakery versus dairy applications, and powder versus liquid versus gel formats. CAGRs derived from regression-adjusted historical trajectory analysis incorporating REACH phase-out timeline assumptions and clean-label procurement mandate diffusion curves.
Material uncertainties — EFSA authorization backlog resolution speeds, monsoon severity impacts on Indian spirulina yields, and EU Green Deal enforcement consistency — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory harmonization progress and extraction technology cost curves. Practitioners should keep alternative scenarios live as EFSA re-evaluation program scope expansions and climate-driven agricultural volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market