
 Cartridges for RT-PCR Automatic Systems Market | 2026-2036
Cartridges for RT-PCR Automatic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cartridges for RT-PCR Automatic Systems Market Outlook
The EU In Vitro Diagnostic Regulation is rebalancing procurement criteria across European clinical networks, compelling cartridge suppliers to elevate traceability and batch-consistency protocols. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to sustain long-term contracts with reference laboratories. QIAGEN anchors its position through sample-to-insight automation platforms that reduce hands-on time for technicians. Danaher Corporation competes via subsidiary-level specialization in precision consumables for high-throughput molecular diagnostics.
Cartridges for RT-PCR automatic systems are sealed, single-use consumables engineered from medical-grade polypropylene with precision-molded reaction chambers, typically containing lyophilized or liquid master mixes optimized for thermal cycling fidelity and fluorescence detection. They serve the primary commercial purpose of enabling standardized, contamination-resistant nucleic acid amplification in automated platforms deployed for infectious disease surveillance, oncology biomarker profiling, and genetic screening. RNA-targeting cartridges command the dominant revenue share within product type segmentation, reflecting persistent virological testing volumes, while digital PCR technology represents the fastest-expanding technology segment as oncology laboratories seek absolute quantification capabilities for liquid biopsy workflows.
The FDA enforces design-control and quality-system regulations under 21 CFR Part 820 for cartridge manufacturers supplying the United States, while the EMA coordinates notified body oversight for CE-marked IVD products under the IVDR framework in Europe. These dual regulatory architectures shape demand by mandating clinical validation documentation that extends product development timelines and elevates barriers for non-specialized entrants. Stakeholders must monitor evolving harmonization efforts between FDA and EMA premarket review standards to anticipate where portfolio rationalization or redundant regulatory investments will concentrate capital allocation.
Market Dynamics
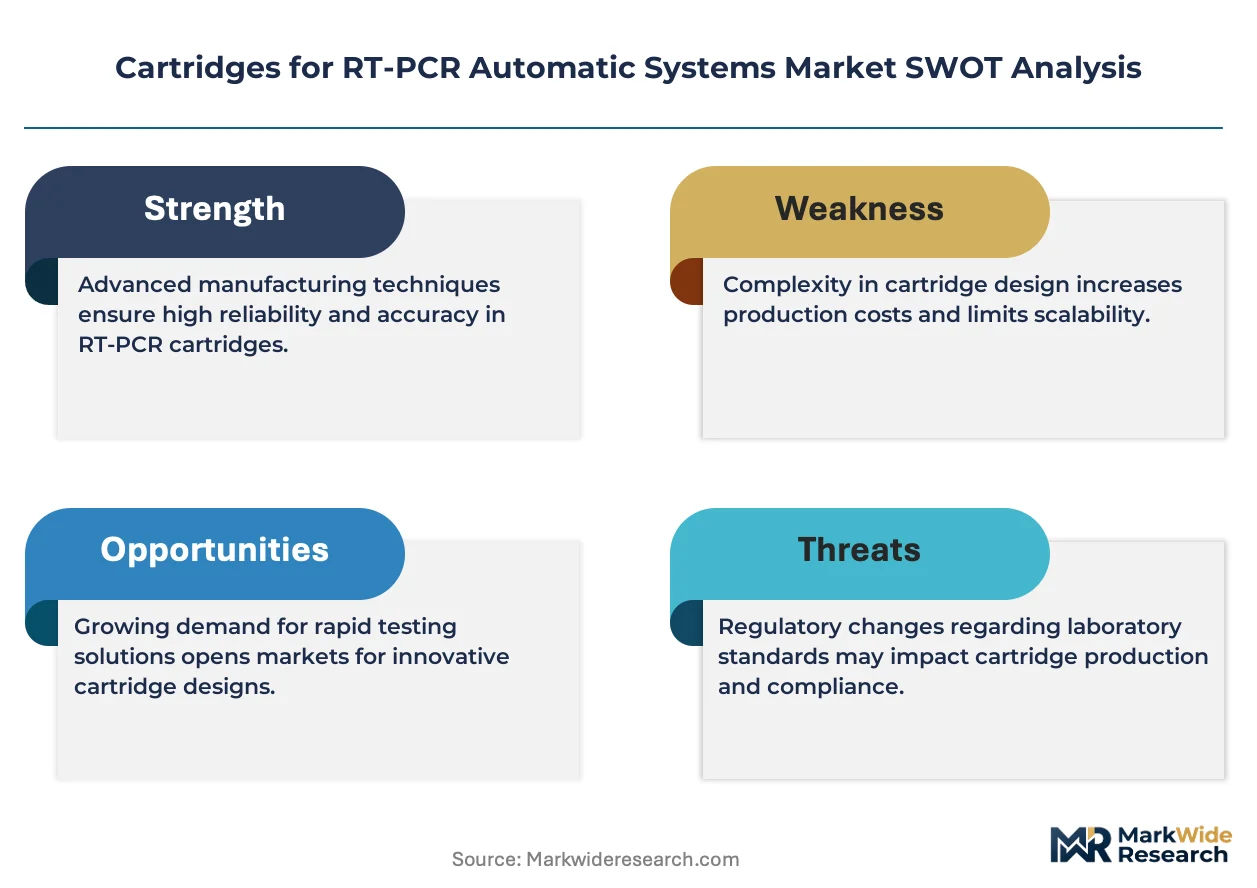
The EU In Vitro Diagnostic Regulation is compressing product development timelines and elevating batch-traceability requirements, forcing cartridge manufacturers to restructure quality systems before IVDR enforcement deadlines. This regulatory pivot is reshaping competitive positioning by favoring suppliers with pre-existing notified body relationships and validated manufacturing footprints.
Growth Catalysts
- Hospital-acquired infection surveillance:United States acute care facilities are expanding automated PCR testing capacity under CDC NHSN reporting mandates, driving replacement cartridge procurement cycles.
- IVDR compliance acceleration:European clinical laboratories are consolidating supplier relationships around CE-IVDR certified cartridge portfolios to avoid service discontinuity risks.
- Lyophilized master mix stabilization:Cold-chain elimination through advanced lyophilization chemistry is enabling point-of-care deployment in resource-limited settings.
Market Restraints
- Medical-grade polypropylene supply concentration:Specialty resin production clusters in Germany and the United States, exposing cartridge molders to feedstock allocation constraints during petrochemical volatility.
- Fluorescence detection patent thickets:Licensing complexity around FAM/VIC/ROX dye chemistries elevates royalty burdens for second-tier cartridge developers.
- IVDR clinical validation documentation:Extended performance study requirements under EU 2017/746 are stretching time-to-market for novel assay formats by 18-24 months.
Strategic Opportunities
- Liquid biopsy oncology expansion:ctDNA and CTC detection workflows are creating demand for ultra-sensitive digital PCR cartridges with absolute quantification capabilities.
- India's CDSCO streamlined IVD pathway:The 2022 Medical Device Rules amendment is reducing import registration timelines for US- and EU-validated PCR consumables.
- AI-assisted assay design convergence:Machine learning platforms are compressing primer-probe optimization cycles, enabling rapid cartridge customization for emerging pathogens.
Industry Challenges
- Multiplex assay development expertise scarcity:Shortage of molecular biologists skilled in competing fluorescence signature optimization is constraining R&D throughput at mid-scale manufacturers.
- Legacy LIS integration complexity:Automated PCR platforms require HL7/FHIR middleware development to connect with hospital information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartridges for RT-PCR Automatic Systems Market |
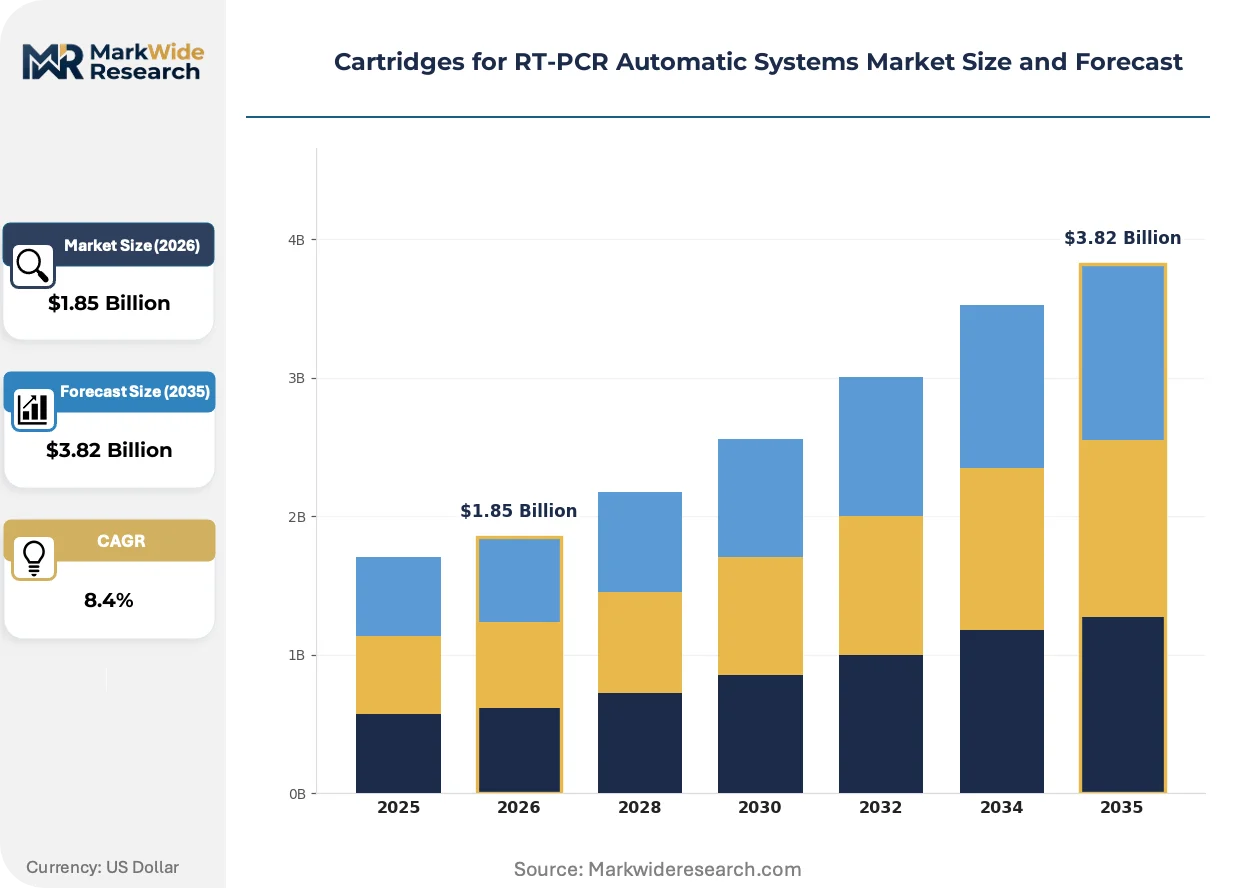
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA, RNA, Viral, Bacterial Therapy Area: Infectious Diseases, Genetic Disorders, Cancer, Chronic Illnesses End User: Hospitals, Diagnostic Centers, Research Laboratories, Academic Institutions Technology: Real-Time PCR, Digital PCR, Multiplex PCR, Nested PCR |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Danaher Corporation, Fluidigm Corporation, Agilent Technologies, Hoffmann-La Roche AG, Bio-Rad Laboratories, Abbott, Takara Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartridges for RT-PCR Automatic Systems Market Strategic Shifts
Digital PCR technology is displacing quantitative PCR in precision oncology workflows, while regulatory harmonization efforts between FDA and EMA are compressing duplicative validation requirements. These forces are converging to reward cartridge suppliers with modular assay architectures and pre-validated international dossiers.
Microfluidic cartridge architectures with integrated sample preparation are integrating nucleic acid extraction, amplification, and detection into single-use consumables. Reference laboratories in the United States and Germany are adopting these platforms to reduce hands-on technician time by 60-70 percent. This convergence is integrating upstream sample processing into the cartridge value chain, compressing the addressable market for standalone extraction kit suppliers.
EMA's coordinated notified body oversight under IVDR Article 48 is mandating annual surveillance audits and post-market performance reporting for Class C IVD devices. European cartridge manufacturers are restructuring quality management systems to accommodate unannounced inspections and batch-specific vigilance reporting. High-complexity molecular diagnostic laboratories in France and the Netherlands are prioritizing suppliers with established IVDR technical documentation to minimize supply continuity risks.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at mid-sized hospital networks. United States health systems exceeding 500 beds are centralizing RT-PCR cartridge purchasing through Premier and Vizient contracts, extracting volume-based pricing concessions. This concentration is most visible in the Southeast and Midwest, where Catholic health system mergers have created regional purchasing monopolies controlling 40-50 laboratory sites.
Cartridges for RT-PCR Automatic Systems Market Segmentation
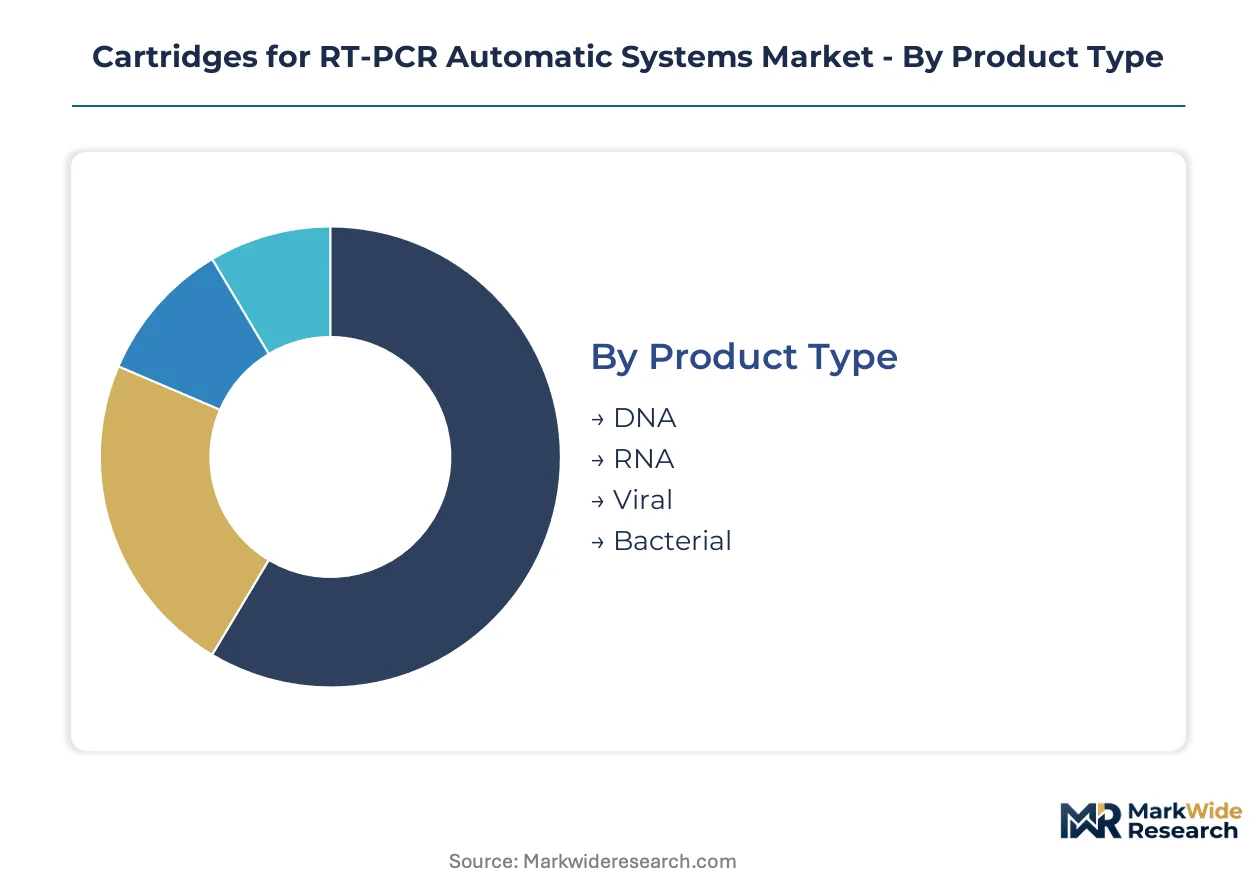
Segmentation in the cartridges market reveals divergent capital requirements across product architectures. Manufacturers must calibrate mold investments and lyophilization capacity to match segment-specific throughput demands and thermal cycling specifications.
Product Type:
Capital intensity peaks with RNA-targeting cartridges requiring specialized stabilizing chemistries and cold-chain alternatives, while DNA formats demand less complex master mix engineering.
- RNA:Lyophilized master mix formulations with ribonuclease inhibitors dominate infectious disease surveillance workflows. United States hospital laboratories under CDC NHSN mandates drive replacement procurement for respiratory pathogen panels.
- DNA:Solid-phase extraction-compatible cartridges serve oncology biomarker profiling with simpler thermal cycling protocols. German reference laboratories anchor European demand for hereditary genetic screening applications.
- Viral:High-sensitivity detection formats for low-titer samples.
- Bacterial:Rapid antimicrobial resistance gene identification in sepsis protocols.
RNA absorbs the bulk of installed capacity; digital PCR integration is expanding most quickly.
Therapy Area:
Application risk profiles determine validation investment levels, with oncology assays requiring extensive clinical correlation studies compared to infectious disease panels.
- Infectious Diseases:Syndromic respiratory panels and bloodstream pathogen detection command the highest cartridge volumes. United States acute care facilities prioritize FDA-cleared assays for hospital-acquired infection surveillance under Joint Commission quality metrics.
- Cancer:Liquid biopsy workflows for ctDNA monitoring demand ultra-sensitive digital PCR cartridges with absolute quantification. French and Dutch molecular pathology laboratories lead European adoption for minimal residual disease tracking.
- Genetic Disorders:Carrier screening and newborn testing protocols.
- Chronic Illnesses:Pharmacogenomic testing for therapeutic drug monitoring.
Infectious diseases maintains the largest installed base; cancer applications are climbing the fastest.
End User:
Customer scale dictates automation tier and cartridge procurement economics, with high-throughput centralized laboratories achieving unit cost advantages over distributed testing sites.
- Hospitals:Integrated health systems exceeding 500 beds deploy automated platforms for stat microbiology and molecular pathology. Southeast and Midwest United States Catholic health system mergers concentrate purchasing through Premier and Vizient group contracts.
- Diagnostic Centers:Independent reference laboratories in Germany and the Netherlands prioritize IVDR-certified cartridge portfolios to ensure supply continuity under EMA notified body oversight.
- Research Laboratories:Custom assay development for investigational protocols.
- Academic Institutions:Grant-funded pathogen discovery and epidemiological surveillance.
Hospitals command the dominant procurement volume; diagnostic centers are gaining share fastest.
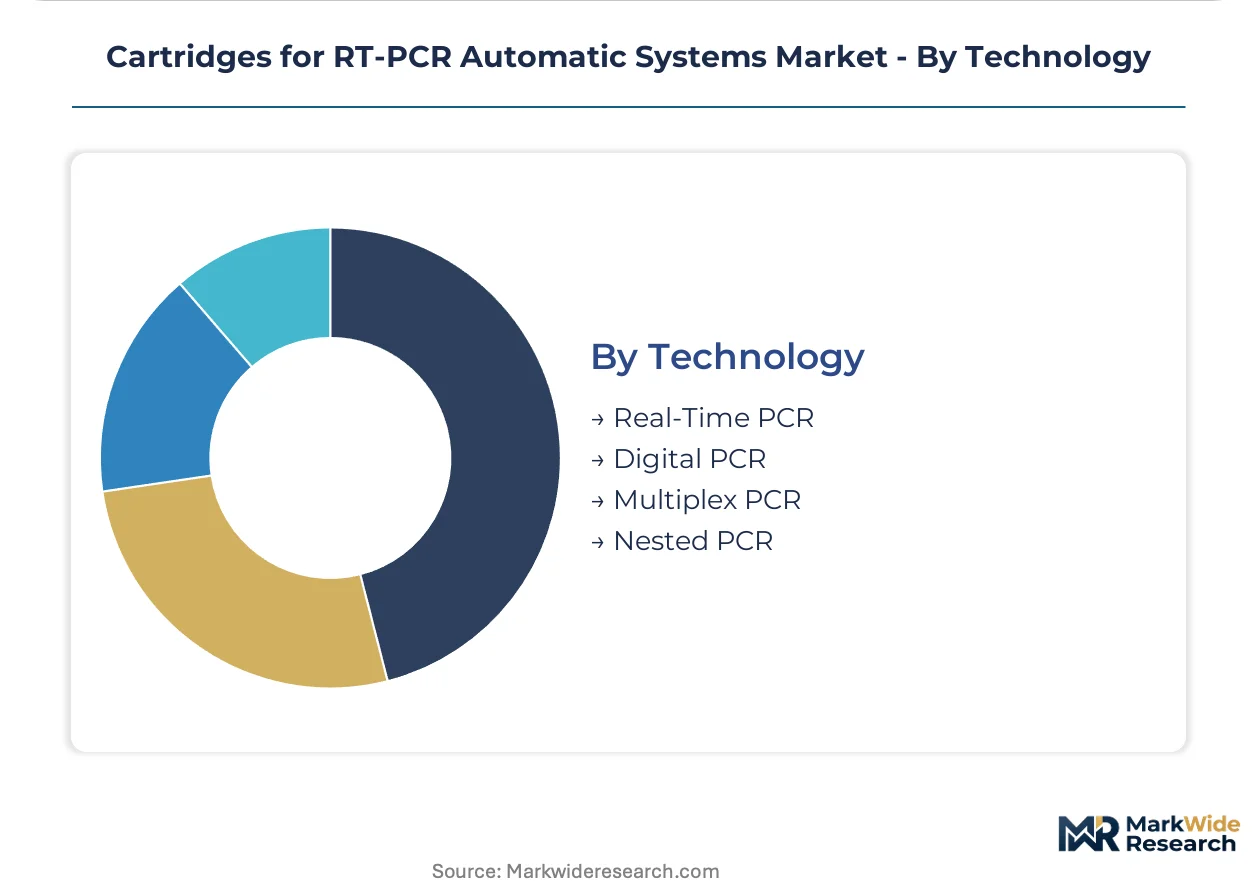
Technology:
Platform sophistication determines cartridge engineering complexity and intellectual property licensing exposure, with fluorescence detection chemistries creating differentiated cost structures.
- Real-Time PCR:Established qPCR platforms with FAM/VIC/ROX dye chemistry dominate routine diagnostic workflows. Patent licensing complexity elevates royalty burdens for second-tier cartridge developers entering quantitative amplification markets.
- Digital PCR:Absolute quantification without standard curves enables liquid biopsy sensitivity thresholds. Oncology laboratories in the United States and Germany are displacing qPCR for minimal residual disease monitoring.
- Multiplex PCR:Competing fluorescence signature optimization requires scarce molecular biology expertise.
- Nested PCR:Enhanced specificity for low-abundance targets in research settings.
Real-time PCR holds the majority of deployed systems; digital PCR is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors North American demand for RT-PCR cartridges, with reference laboratories and precision medicine startups clustering around Kendall Square and the Longwood Medical Area.
United States
Hospital-acquired infection surveillance programs under CDC NHSN reporting mandates drive cartridge procurement cycles at acute care facilities. FDA enforcement of 21 CFR Part 820 quality system regulations shapes supplier qualification timelines. The Southeast and Midwest concentrate purchasing power through Catholic health system mergers controlling 40-50 laboratory sites.
Germany
Reference laboratories in Berlin and Munich prioritize IVDR-certified cartridge portfolios to ensure supply continuity under EMA notified body oversight. The country's medical device regulator enforces annual surveillance audits and batch-specific vigilance reporting for Class C IVD devices. Specialty resin production clusters in the Rhine-Ruhr industrial region expose molders to petrochemical feedstock allocation constraints.
France
Molecular pathology laboratories in Paris and Lyon lead European adoption of digital PCR cartridges for minimal residual disease tracking in liquid biopsy workflows. ANSM coordinates national vigilance reporting for IVD devices alongside EMA harmonization efforts. The Île-de-France region concentrates high-complexity diagnostic infrastructure serving oncology networks.
India
CDSCO's streamlined 2022 Medical Device Rules amendment reduces import registration timelines for US- and EU-validated PCR consumables. Diagnostic chains in Mumbai and Delhi-NCR expand automated platform deployment for infectious disease surveillance. The Maharashtra pharmaceutical manufacturing belt attracts contract molders serving cartridge assembly operations.
Japan
PMDA's premarket approval pathways for IVD devices maintain rigorous clinical validation standards for cartridge suppliers entering the market. Tokyo and Osaka metropolitan areas host centralized reference laboratories displacing manual PCR workflows with automated systems. The Kanto region's precision plastics industry supplies medical-grade polypropylene components to regional assemblers.
Cartridges for RT-PCR Automatic Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory certification depth and lyophilization chemistry sophistication. The vendor base stratifies into three tiers: integrated life science conglomerates with instrument-reagent ecosystems, specialized molecular diagnostics firms with sample-to-insight automation platforms, and regional consumables suppliers competing on batch scale. Consolidation pressure concentrates among mid-scale manufacturers lacking notified body relationships. Dominant competitive moves include backward integration into specialty resin sourcing and strategic partnerships with reference laboratories for co-development of assay-specific cartridge formats.
Within the integrated conglomerate tier, Thermo Fisher Scientific, QIAGEN, and Danaher Corporation exemplify archetypes spanning instrument-reagent ecosystem control, sample-to-insight workflow automation, and precision consumables specialization through subsidiary-level operations. Thermo Fisher represents the vertically integrated model leveraging long-term contracts with reference laboratories. QIAGEN occupies a position emphasizing technician workflow efficiency through hands-on time reduction. Danaher anchors the multi-brand portfolio approach with subsidiary-level focus on high-throughput molecular diagnostics consumables.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Danaher Corporation |
| Fluidigm Corporation |
| Agilent Technologies |
| Hoffmann-La Roche AG |
| Bio-Rad Laboratories |
| Abbott |
| Takara Bio Inc. |
| Others |
Value Chain & Pricing Dynamics
Group purchasing organization consolidation across United States health systems exceeding 500 beds is compressing supplier margins and forcing cartridge manufacturers to restructure contract terms around volume commitments and multi-year service bundling.
Pricing Analysis
Throughput-based pricing anchors cartridge procurement economics, with automated platform vendors tying consumable costs to test-per-hour guarantees and uptime service levels. Pricing stratifies across IVDR-certified premium tiers, FDA-cleared standard tiers, and economy grades for research-use-only applications. Cost compression in the economy tier is intensifying because Indian diagnostic chains are importing US- and EU-validated consumables under streamlined CDSCO pathways. Academic institutions and grant-funded research laboratories exhibit the highest price sensitivity, while oncology reference laboratories in France and Germany prioritize assay sensitivity over unit cost.
Supply Chain Analysis
Medical-grade polypropylene supply rests on specialty resin producers clustered in Germany, the United States, and Japan. Cartridge molders draw from lyophilized master mix chemistries, precision-molded reaction chambers, and fluorescence detection dyes as critical inputs. Single-source vulnerability concentrates in FAM/VIC/ROX dye licensing, where patent thickets constrain second-tier developers. Distribution runs through instrument-reagent ecosystem partnerships and group purchasing organization contracts at high-volume hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital PCR technology is displacing quantitative PCR in precision oncology workflows, creating a technology-transition phase that rewards modular assay architectures and pre-validated international dossiers.
For Market Incumbents: Deploy backward integration into specialty resin sourcing to secure feedstock allocation during petrochemical volatility. Consolidate notified body relationships ahead of IVDR enforcement deadlines to capture European laboratory procurement consolidation. Digital PCR platforms threaten qPCR-installed base revenues; defend through co-development partnerships with reference laboratories for assay-specific cartridge formats. For New Entrants and Emerging Players: Begin with India's CDSCO streamlined import pathway for US- and EU-validated consumables, where diagnostic chains in Mumbai and Delhi-NCR are expanding automated platform deployment. Target liquid biopsy oncology applications in French and Dutch molecular pathology laboratories, where minimal residual disease tracking demand outpaces incumbent supply. Pursue AI-assisted assay design convergence as a go-to-market angle to compress primer-probe optimization cycles for emerging pathogens. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale manufacturers possessing pre-validated IVDR technical documentation and established lyophilization chemistry capabilities, given European supply continuity risks under EMA notified body oversight. Long-term viability hinges on portfolio breadth across infectious disease surveillance and oncology biomarker profiling. Watch IVDR compliance acceleration and group purchasing organization contract renewals as inflection indicators for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR Article 48 compliance secures access to European reference laboratory procurement consolidation. |
| Hospital System Partnership | Premier and Vizient contracts extract volume-based pricing concessions across 40-50 laboratory sites. |
| Software Companion Development | HL7/FHIR middleware integration reduces legacy LIS implementation timelines for automated platforms. |
| Backward Integration into Resin | Captive supply of medical-grade polypropylene mitigates Rhine-Ruhr petrochemical allocation constraints. |
| Reimbursement Strategy | CDC NHSN reporting mandates create budget line-item security for hospital-acquired infection surveillance cartridges. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at IVD manufacturers. FDA 510(k) submissions, EMA IVDR technical documentation, CMS Medicare laboratory fee schedules, and hospital procurement databases supplied validation benchmarks. Bottom-up cartridge volume modeling triangulated against top-down molecular diagnostics market sizing.
Granularity-level modeling deployed product type, therapy area, end user, and technology segment dimensions at the country level across the projection horizon. CAGRs derived from installed base replacement cycles, pathogen surveillance program expansion rates, and digital PCR adoption curves. Assay-specific cartridge format development timelines and lyophilization capacity expansion schedules fed industry-specific forecast inputs.
IVDR enforcement deadline delays, fluorescence detection patent litigation outcomes, and group purchasing organization contract consolidation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around regulatory harmonization progress and petrochemical feedstock stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Cell Harvesting Systems Market