
 Restriction Endonucleases Products (REP) Market | 2026-2036
Restriction Endonucleases Products (REP) Market Size, Share, and Industry Trends Forecast 2026-2036
Restriction Endonucleases Products (REP) Market Analytics
A shortage of trained enzymologists and fermentation specialists is unwinding capacity expansion plans across the REP supply base. New England Biolabs leverages its decades-long strain development program to sustain proprietary expression systems. Thermo Fisher Scientific anchors North American distribution through integrated life sciences channels. Promega Corporation differentiates with application-optimized formulations for cloning workflows.
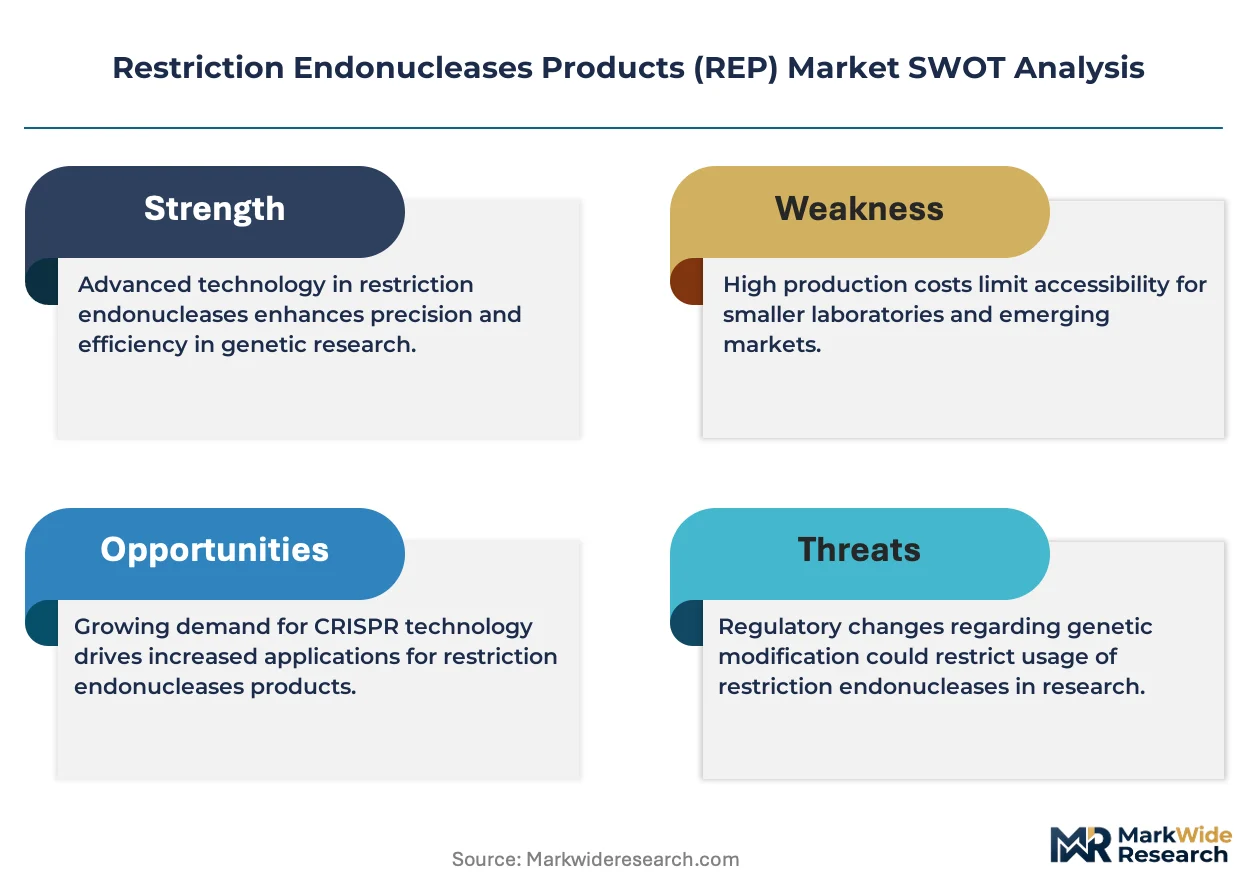
Restriction endonucleases are bacterial enzymes that recognize specific DNA sequences and cleave phosphodiester bonds, typically requiring magnesium cofactors and operating at defined temperature and pH ranges; they enable precise genetic manipulation for research and therapeutic development. Type II restriction enzymes dominate commercial portfolios due to their predictable cleavage patterns and broad protocol compatibility. Synthetic biology applications are expanding fastest as cell-free systems and automated foundries consume enzymes at scale. Academic institutions remain the largest end-user segment, though biopharmaceutical companies capture higher per-unit margins through qualified, audit-grade supply contracts.
US FDA guidance on gene therapy CMC and EMA's ATMP quality requirements shape enzyme purity benchmarks and documentation burdens for suppliers. ISO 13485 and GMP-adjacent quality systems are becoming baseline expectations for clinical-grade enzyme supply, filtering out smaller fermentation houses. Stakeholders must weigh the cost of quality system investment against the contracting window for research-only positioning.
Market Dynamics
CRISPR-Cas9 workflows and next-generation sequencing library preparation are compressing enzyme consumption cycles, forcing suppliers to reconfigure fermentation capacity toward smaller-batch, higher-purity production runs.
Growth Catalysts
- Gene therapy CMC guidelines:FDA and EMA purity specifications are expanding the qualified-supplier pool for clinical-grade enzymes.
- Synthetic biology foundries:Automated cell-free systems in Boston, San Diego, and Shenzhen are consuming restriction enzymes at industrial scale.
- NGS library prep standardization:Protocol convergence across academic core facilities is concentrating demand onto validated enzyme formulations.
Market Restraints
- Fermentation input volatility:Yeast extract and defined media component costs fluctuate with agricultural commodity markets.
- Supplier concentration risk:Three integrated life sciences conglomerates control North American distribution channels.
- Enzyme stability limitations:Temperature-sensitive formulations require cold-chain logistics that constrain remote market access.
Strategic Opportunities
- India biotech corridor expansion:CDSCO's streamlined biologics pathway is attracting contract manufacturing investment to Bengaluru and Hyderabad.
- CRISPR diagnostic convergence:Point-of-care nucleic acid testing is creating demand for thermostable, shelf-stable restriction enzyme variants.
- ISO 13485 certification gap:Mid-tier fermentation houses can capture clinical-grade supply contracts by upgrading quality systems ahead of competitors.
Industry Challenges
- Enzymologist talent scarcity:Academic training programs in protein engineering and strain development are not replacing retiring specialists.
- GMP facility capex requirements:Stainless-steel fermentation suites and isolator technology demand capital commitments that strain private-equity timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restriction Endonucleases Products (REP) Market |
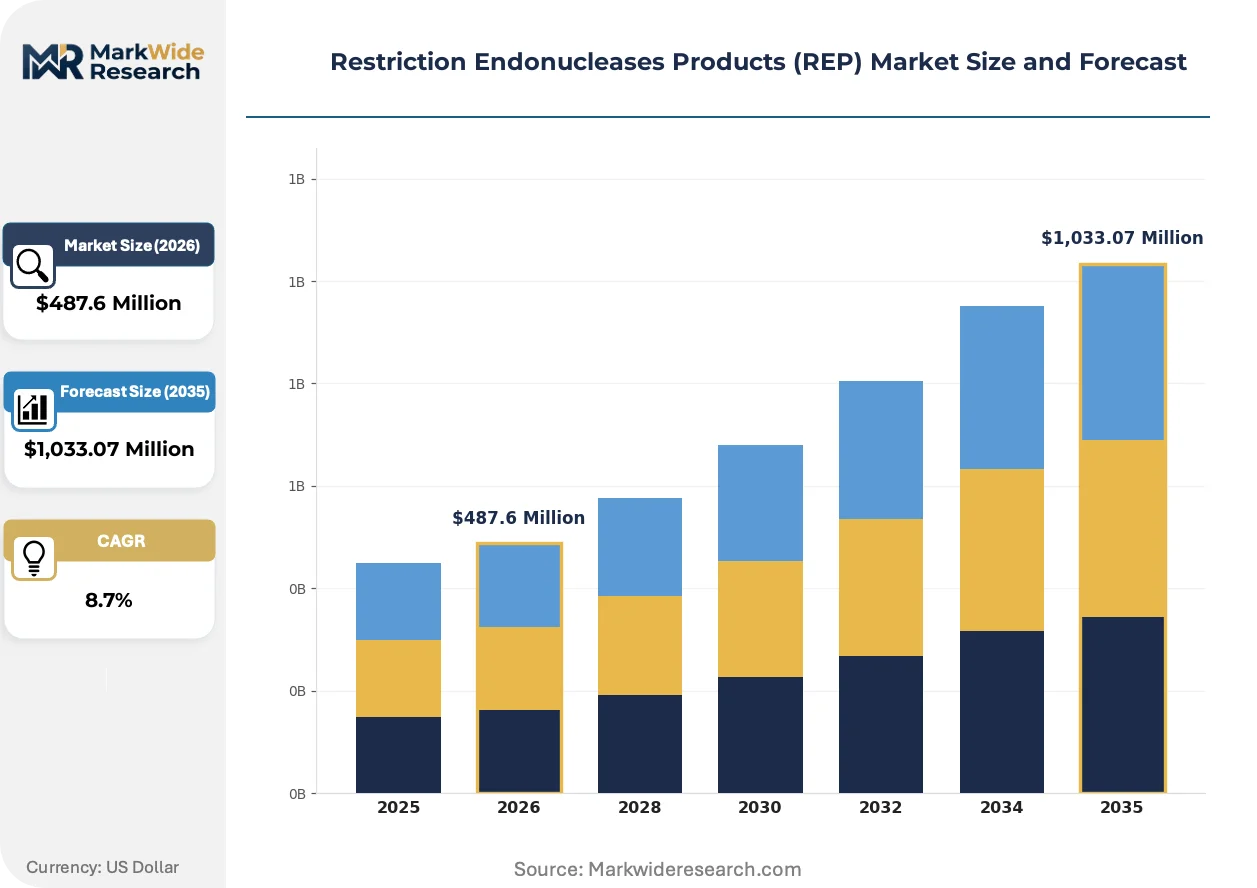
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type II Restriction Enzymes, Type I Restriction Enzymes, Type III Restriction Enzymes, Other Types Application: Molecular Cloning, DNA Fragmentation, Genetic Engineering, Synthetic Biology End User: Academic Institutions, Research Laboratories, Biopharmaceutical Companies, Agricultural Biotechnology Packaging Type: Vials, Ampoules, Pre-filled Syringes, Bulk Packaging |
| Companies Covered | Agilent Technologies, Promega Corporation, New England Biolabs, Illumina, Merck KGaA, Thermo Fisher Scientific, QIAGEN, Sigma-Aldrich, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restriction Endonucleases Products (REP) Market Evolving Landscape
Enzyme engineering and regulatory harmonization are compressing product development cycles while fragmenting buyer expectations across research-grade and clinical-grade tiers.
Engineered high-fidelity restriction enzymes is bifurcating the commercial portfolio landscape. Synthetic biology companies in the United States and Germany are adopting these variants for complex multi-fragment assemblies. The technology is bifurcating supplier R&D budgets between incremental wild-type improvements and de novo protein design programs.
EMA's ATMP quality requirements and FDA's gene therapy CMC guidance are converging on documentary burdens for enzyme traceability. Suppliers must now maintain batch records spanning fermentation harvest through final fill. European contract manufacturers are responding by qualifying second-source enzyme suppliers ahead of audit cycles.
Consolidated procurement through integrated life sciences distributors is displacing direct academic purchasing. University core facilities in Massachusetts, California, and Texas are channeling enzyme spend through sole-source agreements with full-catalog suppliers. This concentration is most visible in the United States, where procurement centralization has reduced the number of active vendor relationships per institution by half.
Restriction Endonucleases Products (REP) Market Segmentation
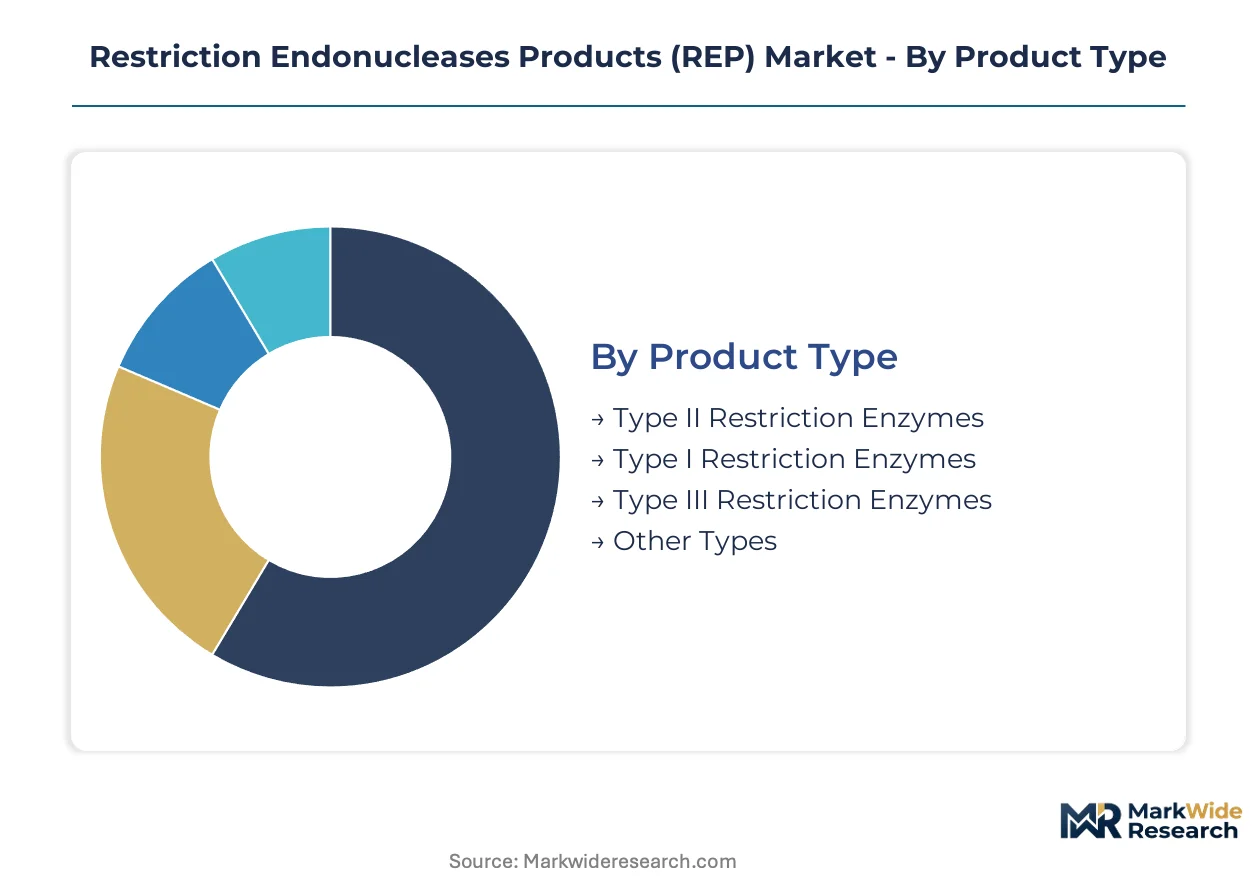
Segmentation in restriction endonucleases determines channel strategy, pricing architecture, and regulatory pathway requirements. Product type and application dictate whether enzymes flow through research distributors or qualified clinical supply chains. End-user concentration in clustered biotech hubs shapes packaging and logistics configurations.
Product Type:
Type II enzymes move through integrated life sciences distributors to academic core facilities, while engineered high-fidelity variants command direct sales to synthetic biology foundries. Type I and III enzymes serve specialized research niches with limited channel overlap.
- Type II Restriction Enzymes:These enzymes recognize palindromic DNA sequences and cleave at fixed positions within or adjacent to recognition sites, delivering predictable fragment ends essential for standardized cloning workflows. Demand concentrates in Massachusetts and California academic core facilities where NGS library preparation protocols have achieved near-universal adoption. FDA gene therapy CMC guidelines are pushing suppliers toward GMP-adjacent manufacturing for clinical-grade variants.
- Type I Restriction Enzymes:ATP-dependent enzymes that cleave DNA at variable distances from asymmetric recognition sequences, requiring complex multi-subunit assemblies that complicate recombinant production. Research laboratories in Germany utilize these for specialized methylation studies where random cleavage patterns provide analytical utility.
- Type III Restriction Enzymes:Bifunctional enzymes exhibiting both restriction and modification activities with unidirectional cleavage patterns, serving niche applications in bacterial strain engineering. Limited commercial availability reflects narrow end-user demand and fermentation complexity.
- Other Types:Includes Type IV enzymes targeting modified DNA and engineered nickases for single-strand cleavage applications. Synthetic biology companies in Shenzhen are piloting these for cell-free circuit construction.
Type II restriction enzymes dominate installed base. Engineered high-fidelity variants represent the fastest-growing trajectory.
Application:
Application segmentation separates high-volume, price-sensitive research workflows from qualified, audit-grade therapeutic development. Molecular cloning and synthetic biology sit at opposite ends of this value spectrum.
- Molecular Cloning:The foundational application enabling insertion of DNA fragments into plasmid vectors through cohesive-end or blunt-end ligation, consuming standardized enzyme formulations in high-throughput academic settings. Research laboratories across Texas and North Carolina channel procurement through sole-source distributor agreements that consolidate volume and reduce per-unit pricing.
- DNA Fragmentation:Controlled enzymatic cleavage for NGS library preparation, requiring precise size distribution and minimal sequence bias. Biopharmaceutical companies in Massachusetts and California demand qualified, lot-traceable supply with ISO 13485 documentation for clinical sequencing applications.
- Genetic Engineering:Site-directed mutagenesis and pathway construction in microbial and mammalian systems. Agricultural biotechnology operations in Iowa and Illinois utilize restriction enzymes for crop trait development under USDA oversight.
- Synthetic Biology:Multi-fragment DNA assembly in automated foundries, consuming engineered enzymes at industrial scale. Boston and San Diego cell-free systems operations are expanding fastest, with Shenzhen emerging as a volume center.
Molecular cloning captures the largest volume footprint. Synthetic biology is where expansion concentrates.
End User:
End-user segmentation reveals a bifurcation between price-sensitive academic procurement and margin-rich qualified supply to therapeutic developers. Channel configuration and documentation burden diverge sharply across these tiers.
- Academic Institutions:University core facilities and departmental laboratories purchasing through consolidated procurement agreements with full-catalog distributors. Massachusetts, California, and Texas institutions have reduced active vendor relationships by half through centralization.
- Research Laboratories:Government and nonprofit research centers with specialized protocol requirements and moderate volume needs. Germany's Max Planck and Helmholtz networks sustain direct supplier relationships for custom formulations.
- Biopharmaceutical Companies:Gene therapy developers and CDMOs requiring GMP-adjacent enzyme supply with batch records spanning fermentation through final fill. FDA and EMA ATMP quality requirements filter supplier pools aggressively.
- Agricultural Biotechnology:Seed companies and trait developers utilizing restriction enzymes for plant transformation and marker-assisted breeding. Operations in Iowa and Illinois face USDA regulatory review timelines.
Academic institutions dominate transaction volume. Biopharmaceutical companies concentrate margin capture.
Packaging Type:
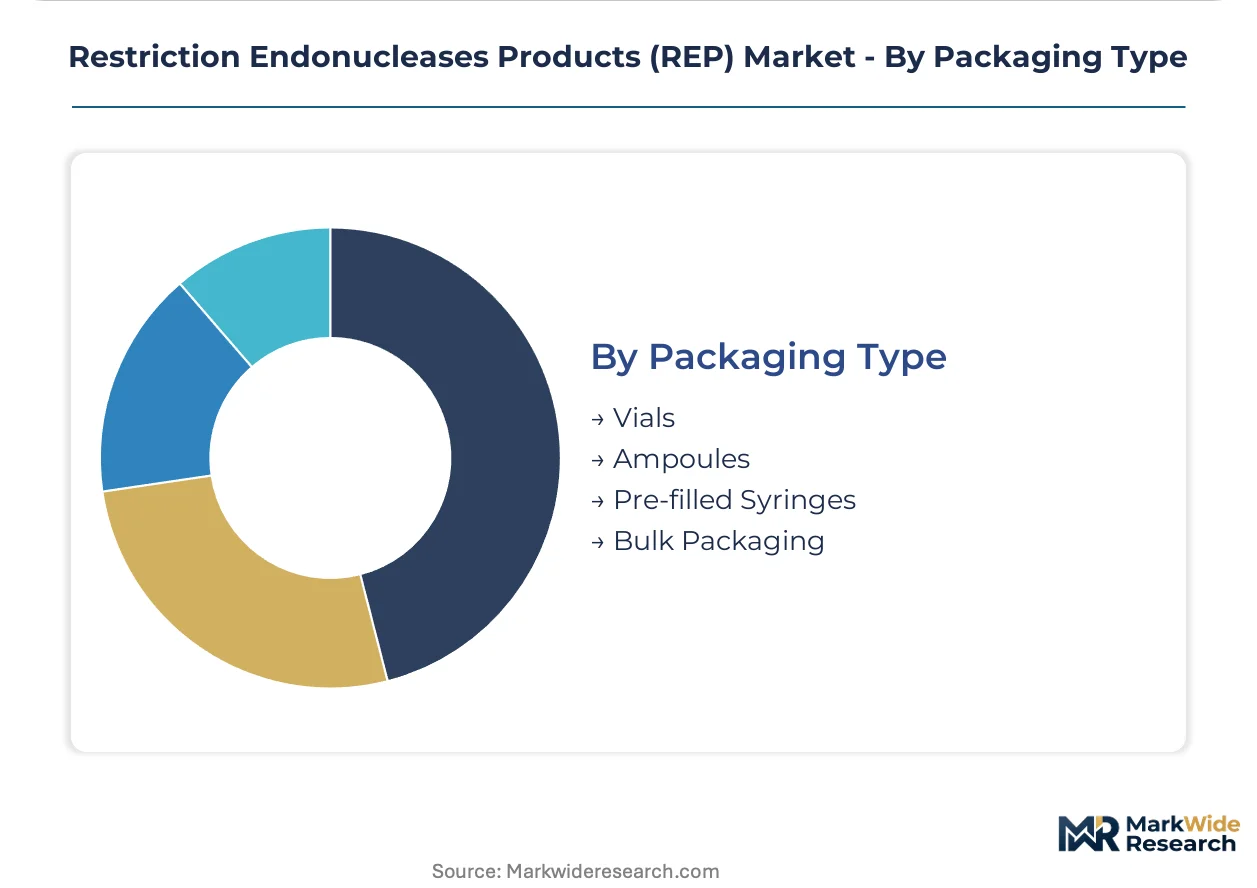
Packaging configuration aligns with end-user scale, stability requirements, and cold-chain logistics constraints. Vials and bulk packaging serve opposite ends of the customer spectrum with minimal overlap.
- Vials:Standard borosilicate glass containers with septum closures, delivering 100-500 unit aliquots optimized for bench-scale research workflows. Academic core facilities in Massachusetts and California specify vial formats for compatibility with liquid-handling automation.
- Ampoules:Single-use glass containers for oxygen-sensitive or highly concentrated formulations, serving specialized methylation-sensitive enzyme applications. Limited adoption reflects handling inconvenience and breakage risk.
- Pre-filled Syringes:Ready-to-use formats for clinical-grade enzyme supply, eliminating reconstitution steps in GMP environments. EMA ATMP quality requirements are driving adoption among European contract manufacturers.
- Bulk Packaging:Liter-scale containers for synthetic biology foundries and CDMOs with automated dispensing infrastructure. Boston and Shenzhen cell-free systems operations consume bulk formats at industrial scale.
Vials dominate installed base. Bulk packaging is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme consumption patterns diverge sharply across major markets. The United States concentrates qualified clinical-grade supply for gene therapy developers, while China and Germany prioritize research-grade volume for academic and synthetic biology applications.
United States
FDA gene therapy CMC guidelines and CRISPR diagnostic commercialization drive demand for GMP-adjacent enzymes. Massachusetts and California biotech clusters sustain bulk purchasing agreements through consolidated procurement channels. Boston cell-free systems operations consume engineered restriction enzymes at industrial scale.
Germany
EMA ATMP quality requirements and synthetic biology foundry expansion shape enzyme purity benchmarks. Baden-Württemberg and Bavaria host precision fermentation facilities supplying European contract manufacturers. Max Planck and Helmholtz networks maintain direct supplier relationships for specialized formulations.
China
Shenzhen and Shanghai synthetic biology corridors consume restriction enzymes for automated foundry operations. NMPA biologics pathway refinements attract CDMO investment to Yangtze River Delta clusters. Domestic fermentation capacity expansion targets import substitution for research-grade supply.
India
CDSCO streamlined biologics approvals and contract manufacturing growth concentrate demand in Bengaluru and Hyderabad. Academic institutions drive research-grade procurement through centralized distributor agreements. Fermentation input cost volatility constrains margin expansion for domestic suppliers.
Japan
PMDA gene therapy guidelines and cell-free system adoption in Kanto region sustain qualified enzyme demand. METI synthetic biology initiatives support foundry infrastructure development around Tokyo and Osaka. Thermostable enzyme variants attract investment for point-of-care diagnostic applications.
Restriction Endonucleases Products (REP) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with distribution consolidation favoring full-catalog suppliers. Three conglomerates anchor North American channels through integrated life sciences platforms. Specialist archetypes include strain-development houses with proprietary expression systems and application-optimized formulation developers. Competitive moves center on GMP facility investment and quality system certification ahead of regulatory audit cycles.
Within the integrated tier, Thermo Fisher Scientific and Agilent Technologies occupy positions spanning research through clinical-grade supply chains. New England Biolabs exemplifies the strain-development specialist archetype with decades-long proprietary expression programs. Promega Corporation represents application-optimized formulation development for standardized cloning workflows.
| Leading Market Players |
|---|
| Agilent Technologies |
| Promega Corporation |
| New England Biolabs |
| Illumina |
| Merck KGaA |
| Thermo Fisher Scientific |
| QIAGEN |
| Sigma-Aldrich |
| Takara Bio |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between synthetic biology foundries and fermentation houses lock in multi-year enzyme supply access while fixing price visibility against yeast extract and defined media volatility. These contracts insulate Boston and Shenzhen cell-free systems operators from spot-market input swings that compress margins for research-grade purchasers.
Pricing Analysis
Contract-based long-term offtake dominates qualified clinical-grade supply, while spot purchasing persists in research-tier transactions. Price differentiation hinges on ISO 13485 certification grade and volume scale, with biopharmaceutical companies absorbing premiums for batch-traceable documentation. Cost compression in research-grade tiers intensifies as academic procurement centralization concentrates bargaining power. University core facilities in Massachusetts and California exhibit highest price sensitivity; gene therapy CDMOs demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Strategic stockpiling of yeast extract and defined media components buffers fermentation houses against agricultural commodity volatility, while just-in-time enzyme distribution serves research laboratories through consolidated distributor networks. Supply concentrates in the United States, Germany, and China, where clustered biotech hubs sustain bulk purchasing agreements. Raw material dependencies include yeast extract, magnesium cofactors, and borosilicate glass vials. Single-source vulnerability in proprietary strain development programs constrains supply resilience. Distribution runs through integrated life sciences conglomerates controlling North American channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in qualified documentation and batch-record management are expanding faster than base enzyme formulations, as FDA and EMA gene therapy guidelines deepen compliance burdens for clinical-grade supply.
For Market Incumbents: Fortify proprietary expression systems through backward integration into strain development capabilities, insulating against enzymologist talent scarcity. Expand GMP-adjacent fermentation capacity in Massachusetts and California clusters to capture gene therapy CDMO contracts ahead of regulatory audit cycles. Certification investment in ISO 13485 quality systems represents the critical defensive lever against mid-tier fermentation house upgrades. For New Entrants and Emerging Players: Anchor in the India biotech corridor, where CDSCO's streamlined biologics pathway and contract manufacturing growth create white-space for research-grade supply. Target academic institutions in Bengaluru and Hyderabad with price-competitive formulations distributed through centralized procurement agreements. A direct-sales model emphasizing customization for specialized methylation studies offers entry against full-catalog incumbents. For Investors and Strategic Acquirers: Strain-development specialists with decades-long proprietary expression programs present compelling acquisition targets, given irreplaceable enzymologist expertise and fermentation IP. Long-term viability across the analysis window rests on GMP facility capex deployment and quality system certification ahead of regulatory convergence. Watch for EMA ATMP quality requirement harmonization with FDA gene therapy CMC guidance as the inflection signal for clinical-grade supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Investment | Stainless-steel fermentation suites in Massachusetts and California capture gene therapy CDMO contracts under FDA scrutiny. |
| ISO 13485 Certification | Quality system upgrades filter mid-tier fermentation houses into clinical-grade supply chains ahead of EMA audit cycles. |
| Strain Development Acquisition | Proprietary expression systems insulate against enzymologist talent scarcity constraining capacity expansion. |
| Long-term Supply Agreement | Multi-year offtake contracts with synthetic biology foundries fix price visibility against yeast extract volatility. |
| Application-Optimized Formulation | Standardized cloning workflows for NGS library preparation concentrate demand onto validated enzyme portfolios. |
Research Methodology
The analysis maps Type II restriction enzymes, engineered high-fidelity variants, and clinical-grade formulations, each validated through fermentation specialists, academic core facility directors, gene therapy CMO procurement leads, and regulatory affairs officers at CDMOs. Primary interviews with these stakeholders combined with secondary validation from FDA guidance documents, EMA ATMP quality requirements, SEC 10-K filings of integrated life sciences conglomerates, and customs trade data for fermentation inputs. Bottom-up enzyme consumption modeling triangulated against top-down market sizing across product type, application, end user, and packaging format dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across enzyme type, application workflow, end-user tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating synthetic biology foundry expansion rates, gene therapy pipeline advancement, and academic procurement centralization trends. Forecast inputs included CRISPR-Cas9 workflow adoption curves and NGS library preparation protocol standardization trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained gene therapy CMC guideline convergence and stable agricultural commodity pricing for fermentation media; material deviation would warrant model refresh. Specific risk factors include enzymologist training program collapse, GMP facility capex timeline compression, and regulatory requirement divergence between FDA and EMA. Revision becomes warranted when synthetic biology foundry capacity utilization crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market