
 Carry Bag Market | 2026-2036
Carry Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Carry Bag Market Analysis
Skilled weaving labor for natural fiber carry bags is collapsing across South Asian manufacturing clusters, forcing producers to automate or relocate. Mondi Group Plc leverages its integrated paper pulp operations to anchor European kraft bag supply. Smurfit Kappa Group dominates corrugated and paper-based packaging with recycled content specialization. International Paper Company sustains North American market presence through mill-level vertical integration and forest certification programs.
A carry bag is a portable container constructed from flexible sheet materials—typically ranging from 30 to 150 grams per square meter in basis weight—designed for manual transport of goods across retail, food service, and logistics endpoints. Manufacturing processes span extrusion and blown film for polyethylene variants, weaving and lamination for polypropylene, and kraft pulping with adhesive bonding for paper grades. Plastic carry bags retain volume leadership in emerging markets where cost thresholds govern procurement decisions, though margin pools are migrating toward jute and cotton segments where certification premiums apply. Paper carry bags are accelerating fastest in European grocery channels following F-Gas Regulation alignment and supermarket chain sustainability mandates.
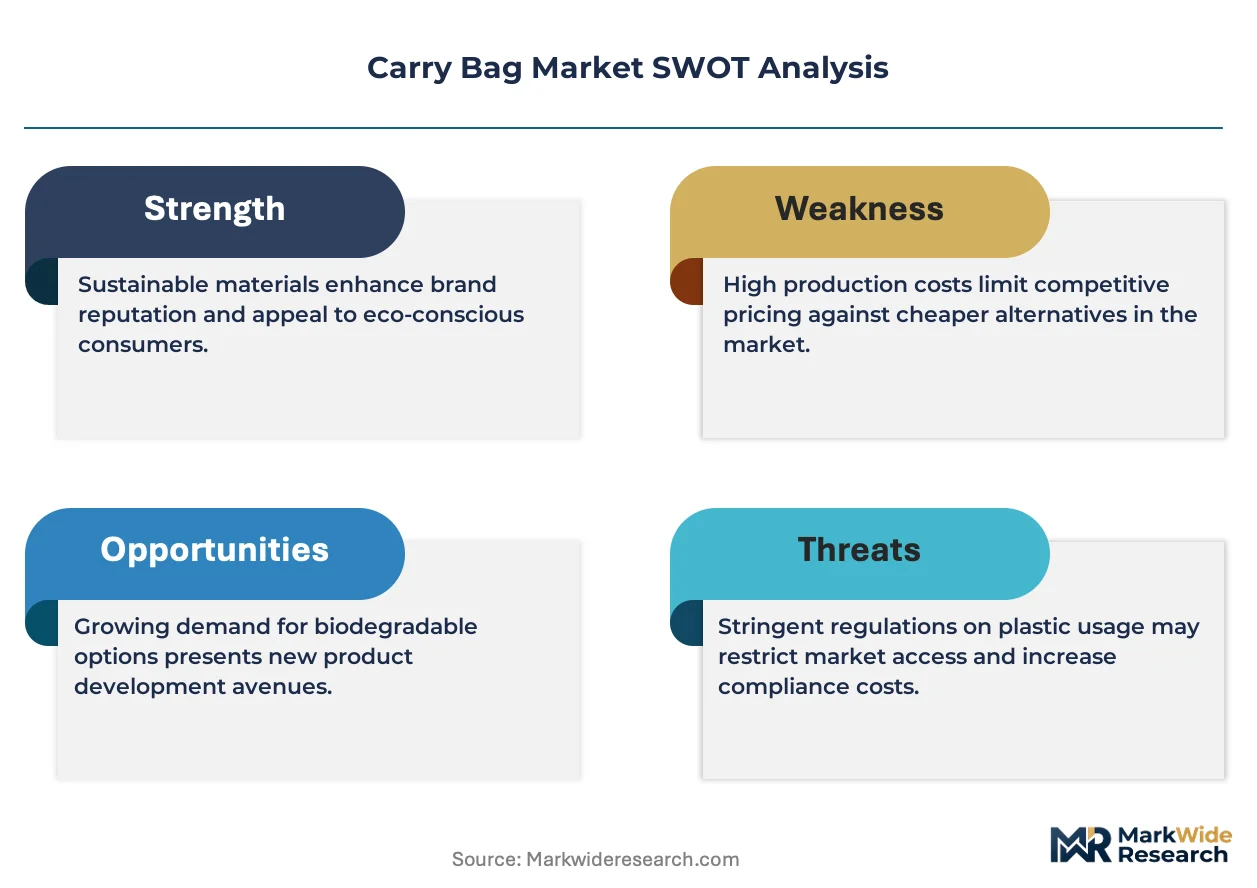
The EU Green Deal and REACH chemical frameworks restrict virgin polymer content and mandate recyclability disclosures across member states. India's BIS certification and Plastic Waste Management Rules enforce thickness minimums and extended producer responsibility for domestic manufacturers. Stakeholders must monitor how divergent national timelines for single-use phaseouts reshape export qualification requirements and raw material sourcing geographies.
Market Dynamics
The carry bag market is fracturing along material lines as EU Green Deal enforcement and India's Plastic Waste Management Rules force simultaneous supply chain reconfigurations across three continents. Producers face incompatible national timelines for single-use phaseouts, requiring parallel certification tracks and raw material hedging strategies.
Growth Catalysts
- EU Green Deal packaging rules:Retail grocery chains in Germany and France are expanding reusable bag programs, pulling demand toward certified paper and jute alternatives with traceable supply chains.
- India BIS thickness mandates:Domestic manufacturers must meet minimum gauge requirements and extended producer responsibility obligations, consolidating production toward organized sector players with testing capabilities.
- Jute certification premiums:Food service and luxury retail segments are absorbing price premiums for biodegradable carry bags that carry FSC or comparable sustainability credentials.
Market Restraints
- Skilled weaving labor collapse:South Asian manufacturing clusters face acute shortages of trained artisans for natural fiber bag production, forcing automation investments or geographic relocation.
- Polypropylene feedstock volatility:PP resin prices tied to naphtha and propylene monomer markets create margin compression for woven bag producers serving emerging market grocery channels.
- REACH chemical disclosure friction:EU importers face extended compliance timelines for adhesives and dyes used in laminated paper bags, delaying product launches by quarters.
Strategic Opportunities
- Brazil single-use restrictions:Pending federal legislation targeting plastic bags in São Paulo and Rio de Janeiro retail corridors creates first-mover advantage for paper and biopolymer suppliers.
- Corrugated e-commerce inserts:Last-mile delivery packaging is absorbing carry bag design principles, with foldable kraft containers replacing single-use plastic mailers in European fulfillment centers.
- China dual carbon alignment:Provincial carbon intensity targets in Zhejiang and Guangdong are accelerating domestic demand for cellulose-based alternatives with verified lifecycle assessments.
Industry Challenges
- Multi-jurisdiction certification complexity:Producers serving EU, Indian, and Brazilian markets simultaneously must maintain parallel testing protocols for biodegradability, heavy metal content, and recyclability claims.
- Legacy extrusion asset stranding:Blown film lines optimized for thin-gauge PE bags face accelerated obsolescence as thickness floors rise, requiring write-downs or retrofit capex for heavier gauge or alternative polymers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carry Bag Market |
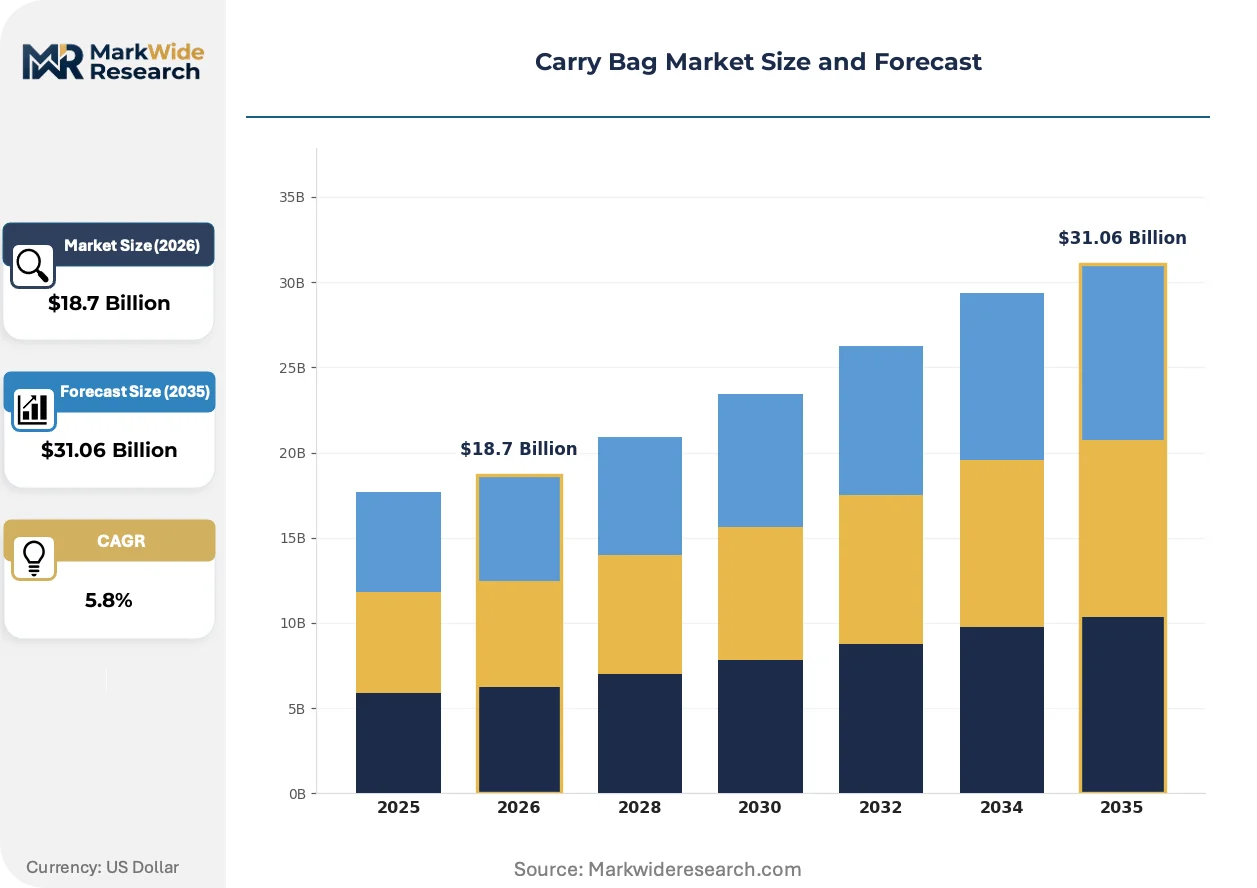
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Cotton, Jute, Paper Usage Type: Grocery, Promotional, Fashion, Eco-friendly Size: Small, Medium, Large, Extra Large Closure Type: Zipper, Drawstring, Button, Magnetic |
| Companies Covered | Novolex Holdings, Mondi Group Plc, International Paper Company, Smurfit Kappa Group, Amcor, Berry Global, Sonoco Products, Sealed Air, Global-Pak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carry Bag Market Emerging Trajectories
Material science advances and regulatory sequencing are compressing traditional product lifecycles, forcing carry bag producers to maintain parallel R&D tracks for biodegradable polymers, engineered papers, and natural fiber composites without clear dominant design emergence.
Barrier-coated kraft paper is bifurcating the grocery carry bag segment between moisture-resistant grades for fresh food and untreated standard grades for dry goods. German and French supermarket chains are specifying the coated variant for produce and deli counters, while discount channels absorb untreated volumes. This technical split is compressing margins on undifferentiated kraft as buyers segment procurement by performance tier.
REACH chemical frameworks and F-Gas Regulation alignment are restricting fluorinated treatments for grease resistance in food service paper bags. The industrial consequence is accelerated migration toward bio-based barrier coatings derived from chitosan or plant waxes. Quick-service restaurant chains in Northern Europe are most affected, with procurement teams rewriting material specifications to exclude per- and polyfluoroalkyl substances ahead of enforcement deadlines.
Consolidated buying by retail grocery chains is displacing fragmented procurement through independent distributors. Carrefour and REWE Group are centralizing carry bag sourcing through direct mill relationships, extracting volume discounts and custom print capabilities that regional wholesalers cannot match. This concentration is most visible in Germany and France, where top-five grocery banners control majority carry bag volumes and are unbundling design, logistics, and manufacturing contracts to optimize total landed cost.
Carry Bag Market Segmentation
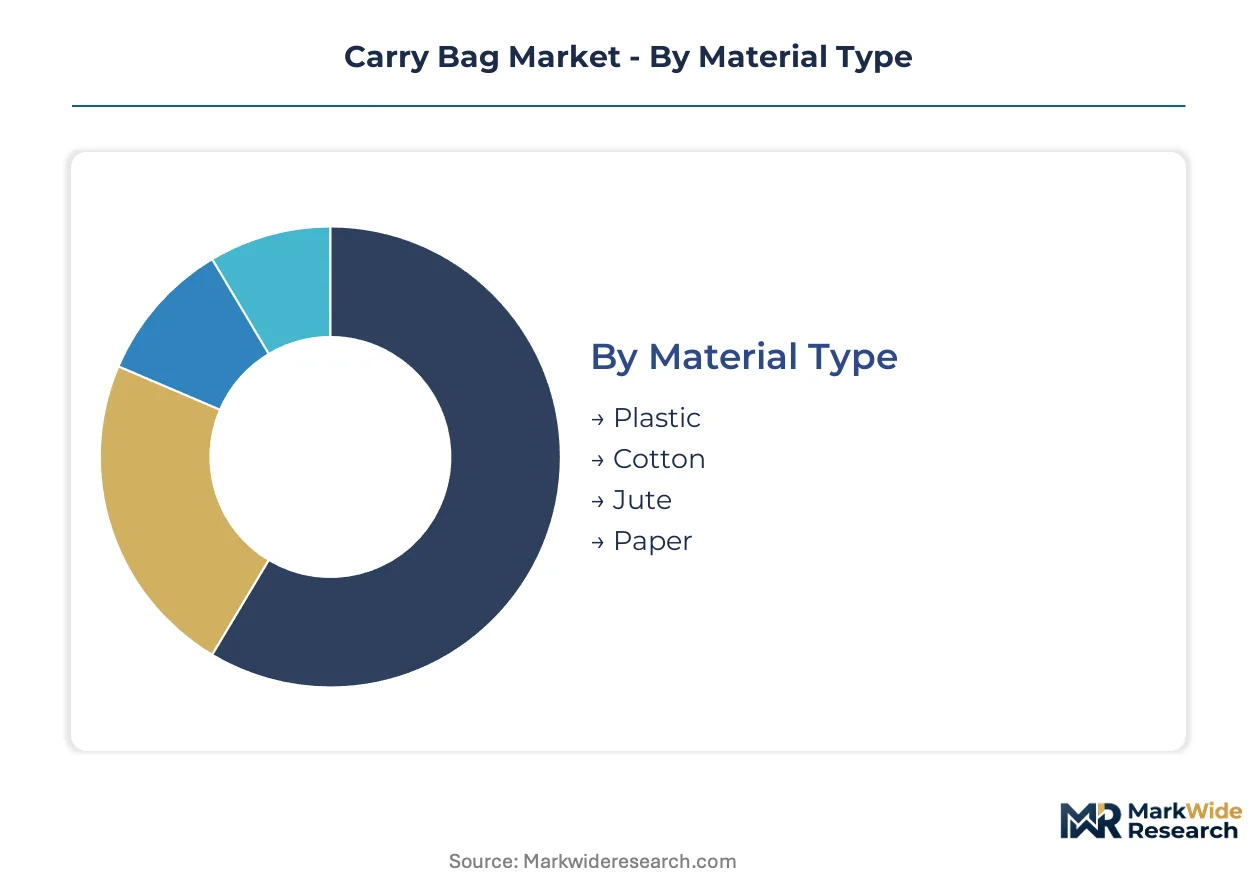
Carry bag procurement channels diverge sharply by material and end-use, with supermarket chains centralizing sourcing for grocery-grade volumes while specialty distributors handle fashion and promotional segments. Understanding these channel-material pairings reveals where margin pools concentrate and which specifications drive supplier selection.
Material Type:
Channel mix varies dramatically: plastic and paper dominate grocery retail direct procurement, cotton and jute flow through specialty distributors to fashion and eco-conscious end-uses.
- Plastic:Extruded polyethylene and polypropylene films remain the default for emerging market grocery chains where cost thresholds govern procurement. Thickness mandates from India's BIS and pending restrictions in Brazil are forcing gauge increases and recyclability investments.
- Paper:Kraft pulp-based bags with adhesive bonding are accelerating fastest in European grocery channels following EU Green Deal alignment and F-Gas Regulation compliance requirements. Coated variants for fresh food command performance premiums over untreated dry-goods grades.
- Cotton:Woven natural fiber construction serves fashion retail and reusable program segments, with certification premiums applying for organic and fair-trade credentials.
- Jute:Biodegradable bast fiber bags absorb sustainability premiums in food service and luxury retail where FSC traceability is specified.
By volume, plastic leads. By growth pace, paper is climbing the fastest as European regulatory deadlines approach.
Usage Type:
Cost tier stratification separates commodity grocery volumes from premium fashion and certified eco-friendly segments, with promotional bags occupying a mid-tier volume position.
- Grocery:High-throughput retail chains in Germany and France specify certified paper and jute alternatives under EU Green Deal mandates, consolidating procurement through direct mill relationships rather than distributors.
- Promotional:Custom-printed polypropylene and non-woven polypropylene serve event marketing and corporate branding, with volume discounts extracted by consolidated buying from major retail banners.
- Fashion:Luxury retail segments specify cotton canvas and laminated paper with premium finishing, where design and print capabilities outweigh pure material cost.
- Eco-friendly:Certified biodegradable and compostable variants across paper, jute, and bio-polymer materials command price premiums in Northern European quick-service restaurant and organic retail channels.
Grocery captures the largest volume base. Eco-friendly specifications are gaining share fastest as regulatory deadlines tighten across multiple jurisdictions.
Size:
Application requirements and logistics constraints shape the size mix, with e-commerce fulfillment driving expansion in larger formats.
- Small:Compact formats for convenience retail, pharmacy, and specialty food service where load-bearing requirements are minimal and storage efficiency matters.
- Medium:Standard grocery checkout dimensions dominate unit volumes across European and Asian supermarket chains.
- Large:Big-box retail and warehouse club specifications require reinforced handles and higher basis weight materials.
- Extra Large:Bulk goods and last-mile delivery applications are absorbing carry bag design principles, with foldable kraft containers replacing single-use plastic mailers in European fulfillment centers.
Medium sizes lead by unit volume. Extra large formats are expanding most quickly as e-commerce packaging requirements evolve.
Closure Type:
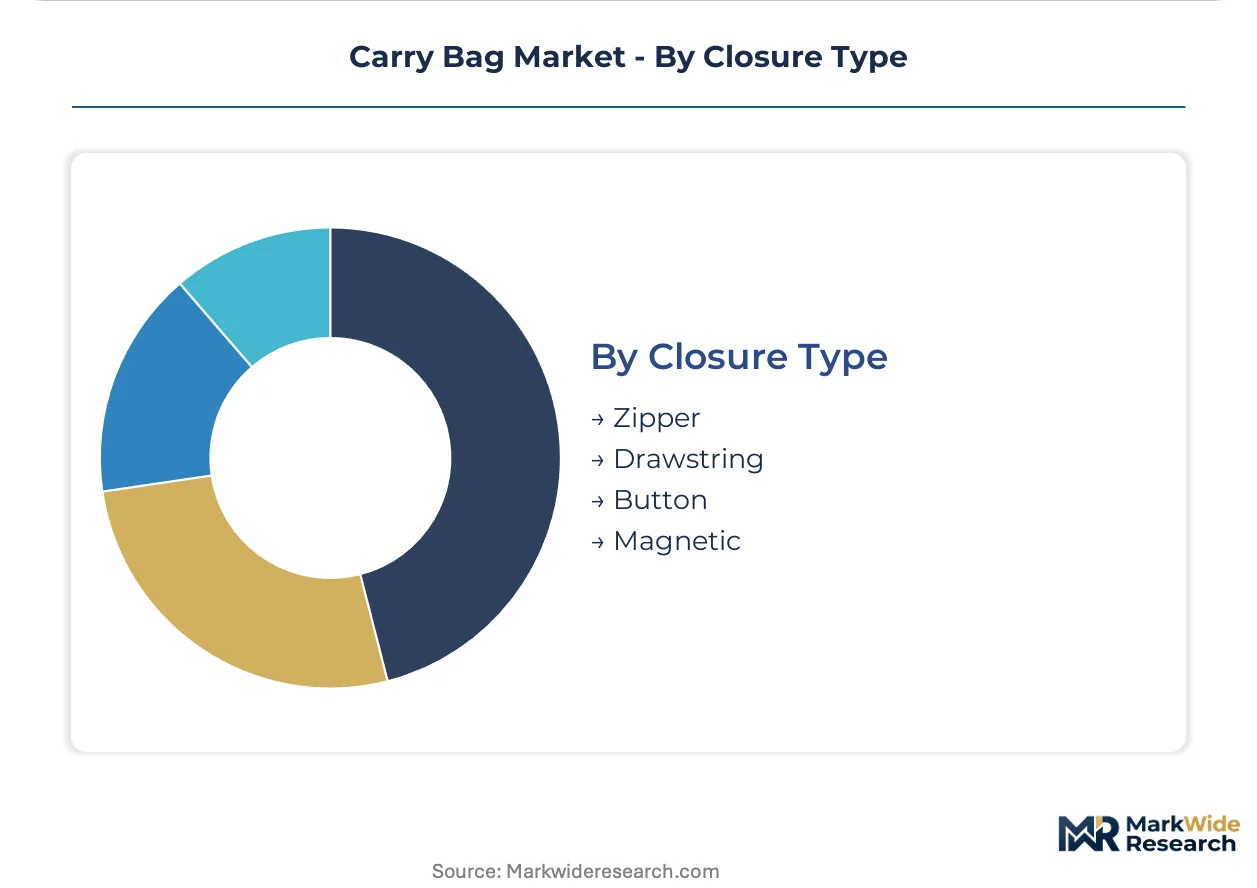
Functional performance tier separates basic open-top grocery bags from secure-closure formats commanding material and labor cost premiums.
- Zipper:Reusable storage and food preservation applications specify zipper closures on laminated and multi-layer constructions, with REACH chemical disclosure requirements affecting adhesive and film selections.
- Drawstring:Sportswear, gift, and promotional segments favor cotton and non-woven drawstring constructions for portability and reclosure convenience.
- Button:Fashion and accessory retail specify button closures on structured paper and canvas constructions where presentation quality drives selection.
- Magnetic:Luxury retail and high-end gift packaging incorporate magnetic closures on rigid paperboard and laminated constructions, with sourcing concentrated among specialty converters.
Open-top designs without closure dominate total volume. Zipper and magnetic closures are gaining specification fastest in premium retail and reusable program segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France absorb premium paper and jute specifications under EU Green Deal mandates, while India and Brazil retain plastic dominance amid divergent regulatory timelines. China pivots fastest toward cellulose alternatives under provincial carbon targets. This consumption-mix differential shapes parallel sourcing strategies for multinational suppliers.
Germany
REWE Group and Carrefour centralize carry bag procurement through direct mill relationships, extracting volume discounts and custom print capabilities. The EU Green Deal packaging rules and F-Gas Regulation alignment restrict fluorinated grease barriers, accelerating bio-based coating adoption. Manufacturing clusters in North Rhine-Westphalia and Bavaria host integrated kraft pulp operations serving supermarket chains.
France
Supermarket banners specify certified paper alternatives for produce and deli counters, segmenting procurement between moisture-resistant coated grades and untreated dry-goods variants. REACH chemical disclosure requirements extend compliance timelines for adhesives and dyes in laminated constructions. Industrial concentration around Paris and Lyon supports specialty converters supplying quick-service restaurant chains.
India
Domestic grocery chains and organized retail drive polyethylene and polypropylene volumes where cost thresholds govern procurement decisions. BIS certification mandates minimum thickness requirements and extended producer responsibility obligations for manufacturers. Production clusters in Maharashtra and Gujarat consolidate toward organized sector players with testing capabilities as informal producers exit.
China
Provincial carbon intensity targets in Zhejiang and Guangdong accelerate domestic demand for cellulose-based alternatives with verified lifecycle assessments. The country's dual carbon alignment pressures converters to source pulp with traceable supply chains. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta shifts capacity from virgin polymer extrusion toward engineered paper grades.
Brazil
Pending federal legislation targeting plastic bags in São Paulo and Rio de Janeiro retail corridors creates first-mover positioning for paper and biopolymer suppliers. Supermarket chains in southeastern metro areas pilot reusable programs ahead of enforcement deadlines. Local converters in São Paulo state invest in kraft pulping capacity to serve anticipated grocery channel substitution.
Carry Bag Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-bag verticality determining margin capture in European markets. The structure bifurcates between scale-driven paper conglomerates with captive fiber supply and regional converters dependent on spot pulp markets. Three archetypes dominate: integrated pulp-and-paper multinationals, specialty flexible packaging houses, and regional woven bag fabricators. Competitive moves center on mill-level backward integration into fiber sourcing and geographic relocation to evade labor shortages in South Asian weaving clusters.
Within the integrated tier, Mondi Group Plc and International Paper Company exemplify pulp-captive positioning through European and North American mill networks respectively. Smurfit Kappa Group occupies a position between scale and specialization, leveraging recycled content capabilities across corrugated and paper-based formats. These three entities represent distinct geographic anchors for procurement consolidation by retail grocery chains.
| Leading Market Players |
|---|
| Novolex Holdings |
| Mondi Group Plc |
| International Paper Company |
| Smurfit Kappa Group |
| Amcor |
| Berry Global |
| Sonoco Products |
| Sealed Air |
| Global-Pak Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day kraft pulp inventory cycles at European converters determine pricing leverage across grocery procurement contracts, concentrating margin capture among integrated producers while spot-dependent regional fabricators absorb volatility. This lead-time asymmetry separates captive-fiber mills from converters sourcing through merchant pulp markets.
Pricing Analysis
Long-term offtake agreements between REWE Group and Mondi's kraft operations anchor European paper bag pricing, while Indian polyethylene converters trade on spot resin markets with monthly repricing. Three-tier pricing structure across FSC-certified premium, standard recycled-content, and economy virgin-polymer grades separates procurement tiers. Cost compression in undifferentiated kraft intensifies as supermarket chains unbundle design and logistics contracts. Emerging market grocery banners exhibit highest price sensitivity; luxury retail segments absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam elevates inbound logistics costs for South Asian jute shipments arriving at European laminating facilities. Manufacturing gravity centers on Germany, China, and India for paper, plastic, and natural fiber grades respectively. Raw material flows draw from Scandinavian pulp, Middle Eastern polypropylene resin, and Bangladeshi jute cultivation. Single-source vulnerability concentrates in skilled weaving labor for natural fiber construction. Distribution runs through direct mill relationships with supermarket chains in Europe, fragmented wholesale networks in India, and converter-led channels in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carry bag market is exiting a cyclical trough as EU Green Deal enforcement triggers replacement demand for compliant packaging formats. Regulatory sequencing across multiple jurisdictions compresses decision windows for capacity positioning.
For Market Incumbents: Fortify pulp-captive positions through backward integration into certified fiber sourcing, particularly in Nordic regions with FSC traceability. Accelerate automation investments to offset South Asian weaving labor collapse. Defend against specialty converter encroachment by locking multi-year direct procurement contracts with consolidating grocery banners in Germany and France.
For New Entrants and Emerging Players: Differentiate on bio-based barrier coating technology for fresh food applications, where REACH fluorinated restrictions have eliminated incumbent chemistries. Target Brazilian supermarket pilots ahead of federal plastic restrictions in São Paulo and Rio de Janeiro corridors. Pursue white-label manufacturing partnerships with European quick-service restaurant chains rewriting material specifications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with stranded blown-film assets facing thickness mandate obsolescence. Five-to-ten year viability favors integrated kraft operations with mill-level fiber control over polymer-dependent converters. Monitor BIS enforcement intensity in Maharashtra and Gujarat as inflection signal for Indian market consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Supply | Captures FSC premiums from REWE and Carrefour sustainability mandates. |
| Automation Deployment for Natural Fiber Weaving | Offsets labor collapse in Bangladeshi and Indian manufacturing clusters. |
| Bio-Based Barrier Coating Development | Replaces fluorinated treatments prohibited under REACH food-contact rules. |
| Direct Mill Procurement Relationships | Bypasses distributor margin extraction by consolidated European grocery banners. |
| Geographic Relocation to Brazil | Positions capacity ahead of federal single-use plastic phaseout enforcement. |
Methodological Framework
Initial hypotheses were tested against primary input from procurement directors at European supermarket chains, plant managers at Indian polyethylene converters, sustainability officers at quick-service restaurant brands, and technical directors at kraft pulp operations, then refined against customs trade records, EU packaging directive filings, BIS certification registries, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity assessments triangulated with top-down demand modeling across material and usage segments.
Variance decomposition isolated volume drivers by material type, usage specification, closure complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic elasticity assumptions. Modeled inputs incorporated pulp price indices, polypropylene resin spreads, and certification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated BIS compliance timelines would require recalibration. Forecasts reflect assumptions about regulatory sequencing and substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Bin Liners Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Net Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bakery Bread Bag Market