
 Net Bags Market | 2026-2036
Net Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Net Bags Market Foresight
Modular sizing across small, medium, and large configurations is broadening buyer choice in the Net Bags Market. GSH Group leverages vertical integration across fiber extrusion and finished bag production to control cost structures. LC Packaging International BV anchors European distribution through centralized warehousing in the Netherlands. Karatzis S.A. specializes in high-tenacity polyethylene nets for agricultural and cargo applications.
Net bags are woven or knitted flexible containers manufactured from polyethylene, nylon, cotton, or jute filaments, designed for breathable storage, visible containment, and reduced material weight in transport. The product typically features mesh counts between 8 and 24 strands per inch, with drawstring or heat-sealed closures for load security. Polyethylene-based produce bags dominate volume due to moisture resistance and low unit cost, while cotton and jute variants command premium positioning among sustainability-focused retailers. Cargo nets and fruit bags represent faster-growing configurations as logistics operators and orchard cooperatives adopt standardized mesh containment for palletized and tree-harvested goods.
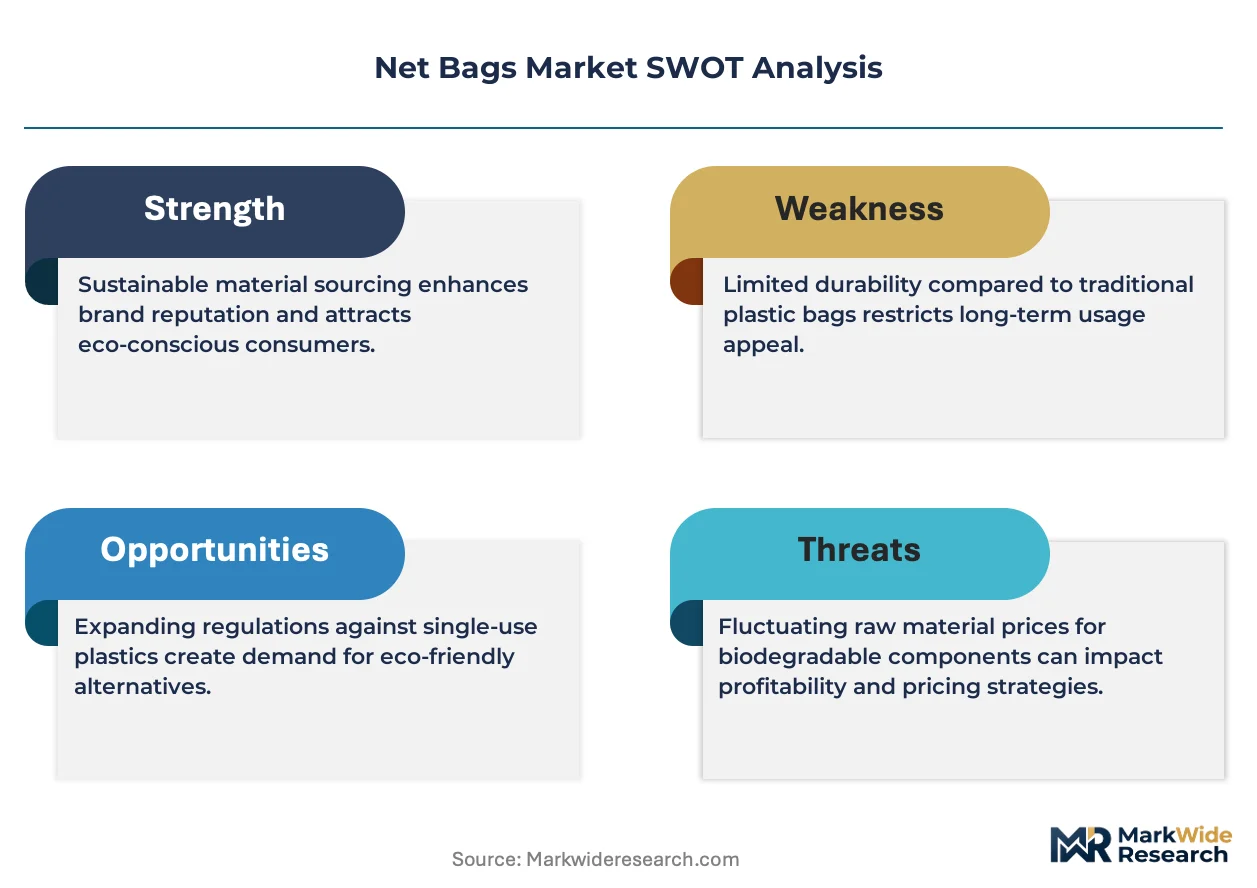
The EU Single-Use Plastics Directive and REACH chemical compliance frameworks constrain virgin polymer inputs and mandate recyclability disclosures across member states. FDA food-contact material standards govern polyethylene and nylon net bags distributed through U.S. retail channels, requiring migration testing for indirect additive exposure. Stakeholders must monitor evolving extended producer responsibility schemes and fiber traceability requirements as regulatory granularity tightens across multiple jurisdictions.
Market Dynamics
Supermarket chains are systematically replacing conventional plastic sacks with reusable mesh alternatives across produce aisles, while the EU Single-Use Plastics Directive accelerates material transitions toward biodegradable fibers. This regulatory pressure is compressing virgin polyethylene demand and redrawing competitive boundaries between petrochemical and natural fiber suppliers.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-outs of conventional plastic carrier bags are forcing retail chains to adopt certified reusable mesh alternatives for fruit and vegetable containment.
- Agricultural mechanization:Orchard cooperatives in Spain and Italy are standardizing polyethylene cargo nets for mechanized harvesting of citrus and stone fruits.
- Biodegradable fiber R&D:Advances in polylactic acid and hemp-blend extrusion are enabling compostable net bags that meet industrial decomposition timelines.
Market Restraints
- Petrochemical price volatility:Ethylene feedstock fluctuations from naphtha cracking operations in the Middle East directly compress margins on polyethylene-based net bags.
- Natural fiber supply concentration:Premium jute and cotton sourcing remains concentrated in Bangladesh and India, exposing converters to monsoon-dependent harvest variability.
- REACH compliance friction:ECHA substance restrictions on certain plasticizers and colorants force reformulation cycles that delay product launches by 8-14 months.
Strategic Opportunities
- Extended producer responsibility schemes:France's AGEC law and similar frameworks in Germany create mandatory take-back infrastructure that favors durable, repairable mesh designs over single-use alternatives.
- Pharmaceutical cold-chain logistics:Breathable high-density polyethylene nets are displacing solid-wall crates for temperature-sensitive vaccine palletization in emerging markets.
- Direct-to-farm digital channels:Agricultural supply platforms are enabling net bag manufacturers to bypass traditional distributor markups and capture orchard cooperative procurement directly.
Industry Challenges
- Migration testing backlog:FDA food-contact certification for novel biodegradable polymers faces 12-18 month queue times at third-party laboratories, freezing product pipelines.
- Knitting technician scarcity:Specialized skills for high-tenacity polyethylene raschel knitting are retiring faster than vocational programs in Portugal and Greece can replenish them.
- Legacy warehouse automation incompatibility:Existing robotic palletizing systems designed for rigid containers require sensor recalibration to handle flexible mesh loads without compression damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Net Bags Market |
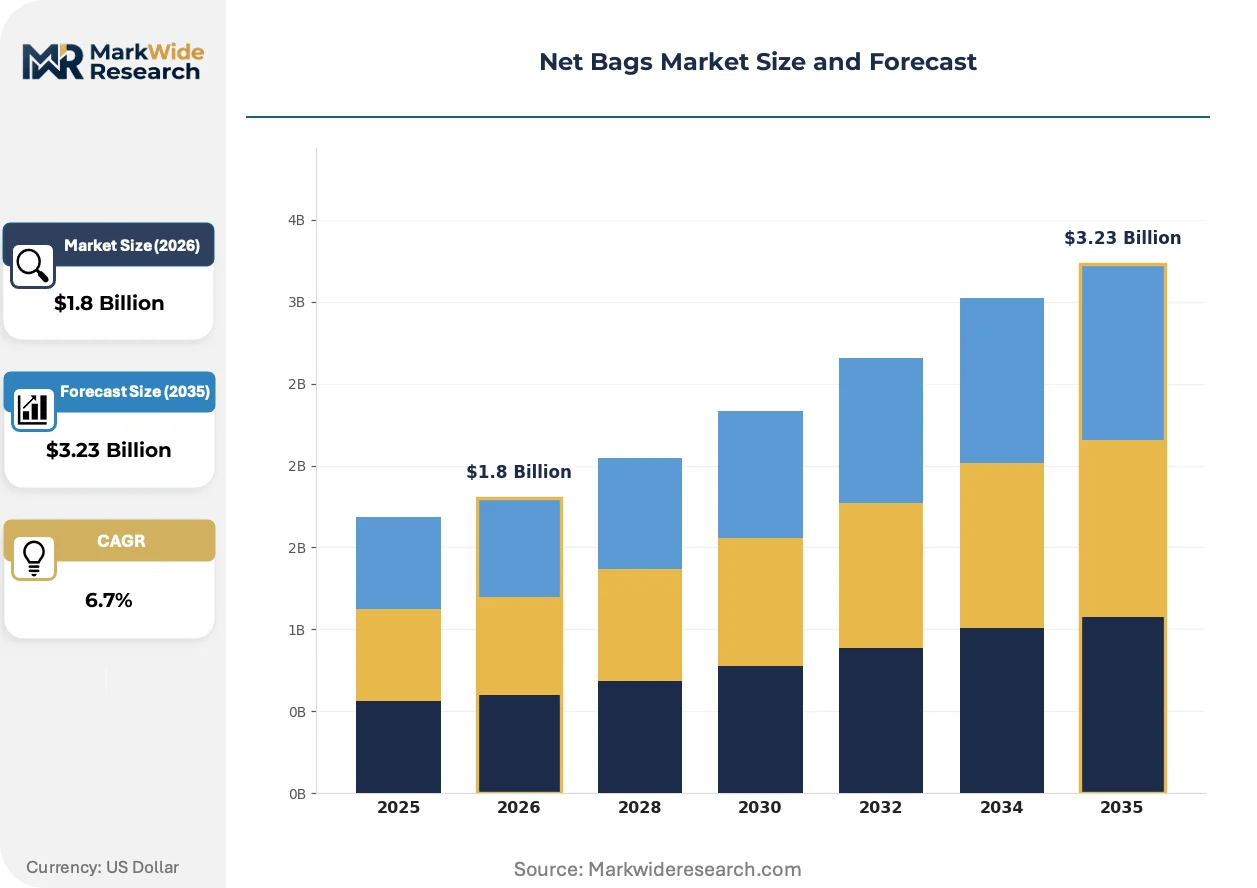
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Nylon, Cotton, Jute Product Type: Produce Bags, Laundry Bags, Fruit Bags, Cargo Nets End User: Retailers, Wholesalers, Restaurants, Households Size: Small, Medium, Large, Extra Large |
| Companies Covered | GSH Group, Chemco Group, LC Packaging International BV, Packnatur GmbH, SKAPS Industries, Intermas Nets, EXPO-NET, Karatzis S.A., ULINE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Net Bags Market Shifts & Advancements
Material science breakthroughs and regulatory granularity are compressing product development cycles while fragmenting buyer specifications across sustainability certifications. Three convergent developments are restructuring how net bags are engineered, validated, and procured.
Monomaterial polyethylene constructions with integrated colorants are consolidating technical specifications across retail and agricultural segments. These designs eliminate separate closure components and enable mechanical recycling without disassembly. German supermarket chains and Dutch flower auction cooperatives are adopting them fastest. The consolidation is compressing demand for multi-material laminated alternatives that previously dominated premium positioning.
REACH chemical compliance frameworks are tightening disclosure requirements for indirect additive migration in food-contact applications. ECHA's expanded authorization list now covers specific UV stabilizers and slip agents common in polyethylene extrusion. Net bag converters serving EU retail channels are responding by accelerating supplier audits and substituting approved additive packages before 2026 enforcement deadlines.
Centralized procurement by retail conglomerates is consolidating supplier relationships and compressing switching cycles. Previously fragmented buying across regional supermarket banners is merging into pan-European tenders with standardized mesh counts and certification requirements. This concentration is most visible in Germany, where REWE and EDEKA group purchasing now dictates specifications that ripple through converter order books within single quarters.
Net Bags Market Segmentation
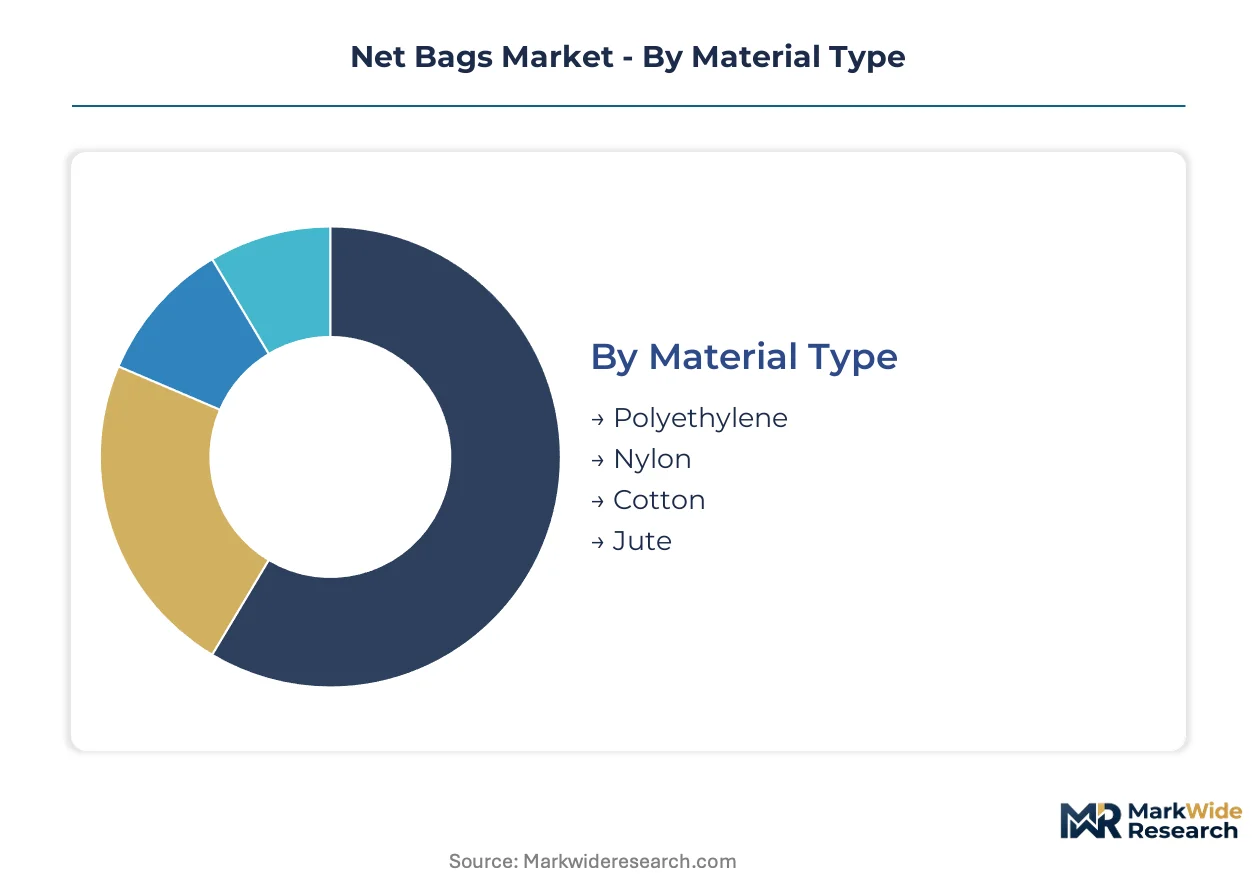
Net bag specifications fragment sharply across material chemistry and end-use performance requirements. Buyers select mesh construction, filament tenacity, and closure systems based on load-bearing demands and regulatory exposure rather than price alone.
Material Type:
Polyethylene dominates unit volume while cotton and jute command margin premiums in certified retail channels.
- Polyethylene:Extruded high-density and low-density variants provide moisture resistance and mechanical recyclability. Supermarket chains in Germany and the Netherlands specify monomaterial constructions to comply with ECHA REACH disclosure requirements for food-contact applications.
- Nylon:Polyamide filaments deliver superior abrasion resistance and elastic recovery under load. Pharmaceutical cold-chain operators in the United States favor nylon cargo nets for temperature-sensitive palletization where FDA migration testing standards apply.
- Cotton:Natural fiber construction meets compostability certifications for premium retail positioning. French supermarket compliance with AGEC extended producer responsibility laws is accelerating cotton mesh procurement for reusable produce containment.
- Jute:Coarse bast fiber from Bangladesh and India supplies agricultural bulk packaging with biodegradable end-of-life credentials. Orchard cooperatives in Spain specify jute for citrus harvesting nets where soil disposal is routine.
Mature deployment sits with polyethylene. Newer deployment is concentrated in cotton.
Product Type:
Functional differentiation separates breathable produce containment from high-tenacity cargo securing applications.
- Produce Bags:Lightweight mesh with 8-16 strand density enables visible fruit and vegetable display while permitting airflow. REWE and EDEKA group purchasing in Germany now mandates standardized mesh counts and REACH-compliant colorants across centralized procurement tenders.
- Cargo Nets:High-tenacity raschel-knitted constructions secure palletized loads during transport. Logistics operators in Italy are displacing solid-wall crates with breathable polyethylene nets for mechanized handling of perishable stone fruits.
- Laundry Bags:Medium-density mesh with drawstring closures protects garments during industrial washing cycles. Commercial laundry services in Portugal specify polyester-blend constructions for durability against chemical detergents.
- Fruit Bags:Specialized small-aperture designs prevent bruising during tree harvesting and orchard transport. Agricultural cooperatives in Greece are standardizing polyethylene fruit bags for mechanized citrus collection to reduce labor dependency.
Volume concentration favors produce bags. Steepest expansion trajectory belongs to cargo nets.
End User:
Procurement scale and certification sophistication vary dramatically across buyer categories.
- Retailers:Centralized purchasing by supermarket conglomerates dictates standardized specifications with mandatory recyclability disclosures. German retail compliance deadlines under EU Single-Use Plastics Directive implementation are compressing supplier qualification cycles.
- Wholesalers:Intermediate distributors aggregate fragmented agricultural demand across multiple orchard cooperatives. Dutch flower auction cooperatives specify monomaterial polyethylene nets to enable mechanical recycling of post-harvest packaging waste.
- Restaurants:Food service operators procure branded reusable mesh for produce storage and front-of-house presentation. Parisian restaurant groups are adopting cotton net bags to align with municipal waste reduction ordinances.
- Households:Individual consumers purchase small-format multipacks for grocery shopping and home organization. Direct-to-consumer channels in the United Kingdom are displacing traditional retail distribution for reusable produce mesh.
Contractual volume sits with retailers. Emerging demand concentration is visible among households.
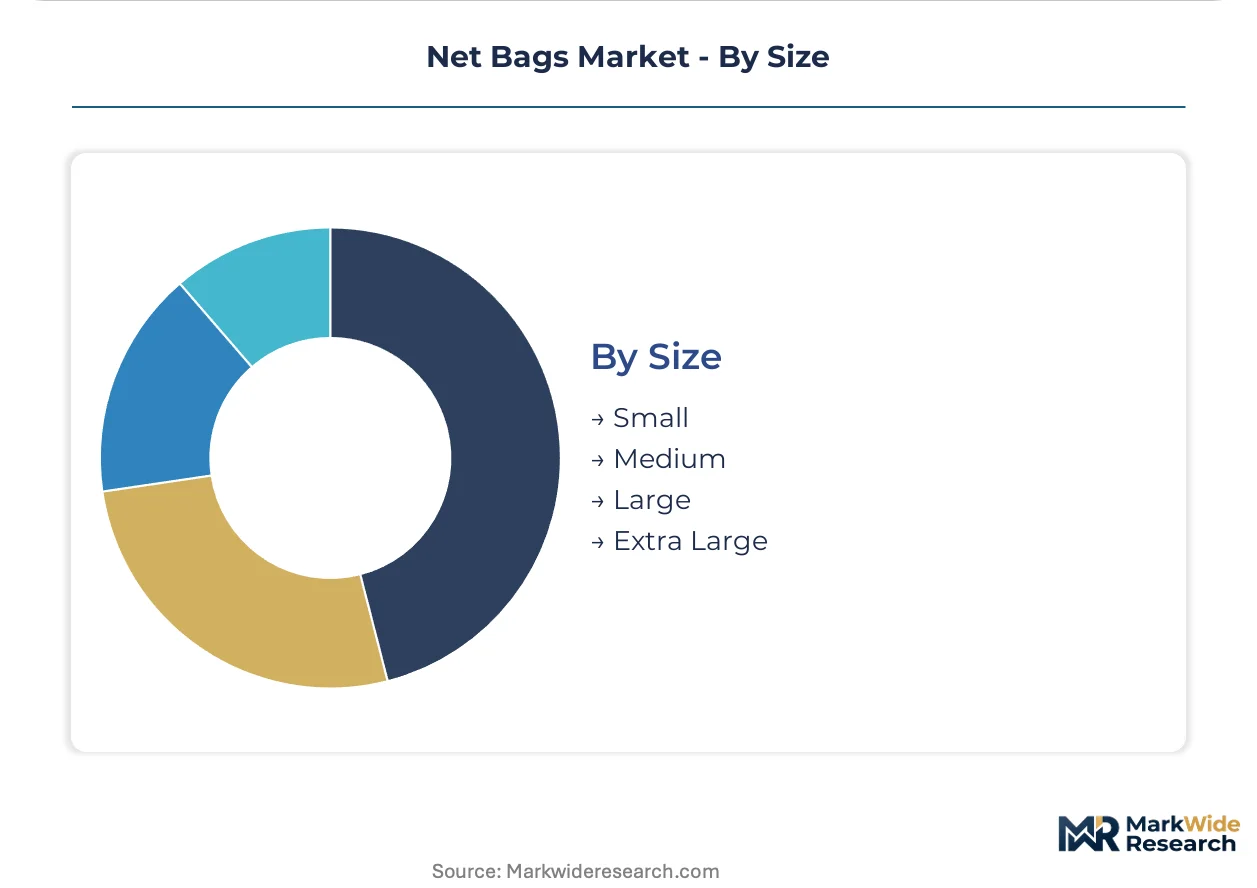
Size:
Modular dimensioning enables load-specific optimization across handling systems and storage footprints.
- Small:Compact formats under 5-liter capacity target individual produce items and pharmacy small-parcel containment. Convenience retail formats in Belgium specify small mesh bags for single-serve fruit portions.
- Medium:Standard grocery tote dimensions balance portability with load capacity for typical household shopping trips. Supermarket private label programs across France standardize medium sizing for interoperability with checkout conveyor systems.
- Large:Expanded capacity accommodates bulk agricultural harvests and commercial laundry batch processing. Spanish citrus cooperatives specify large-format cargo nets for palletized orchard collection to minimize handling stages.
- Extra Large:Industrial-scale dimensions serve containerized shipping and heavy equipment securing. Greek port logistics operators deploy extra-large polyethylene nets for break-bulk cargo stabilization under Mediterranean climate exposure.
Procurement standardization centers on medium formats. Capacity expansion is most visible in extra large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangladesh and India's jute belt concentrate natural fiber supply, while Germany's industrial clusters anchor synthetic mesh conversion for EU retail compliance.
Germany
REWE and EDEKA group purchasing dictates standardized mesh specifications across centralized procurement tenders. The EU Single-Use Plastics Directive compresses supplier qualification cycles with tight compliance deadlines. North Rhine-Westphalia hosts converter operations serving pan-European retail distribution.
Netherlands
Dutch flower auction cooperatives specify monomaterial polyethylene nets for post-harvest packaging waste recycling. ECHA REACH disclosure requirements govern food-contact material standards. Centralized warehousing in Rotterdam anchors European distribution networks for agricultural mesh.
Spain
Orchard cooperatives in Valencia and Murcia standardize polyethylene cargo nets for mechanized citrus harvesting. The EU Green Deal accelerates transitions toward biodegradable fiber alternatives. Catalan converters specialize in high-tenacity raschel-knitted constructions for palletized stone fruit transport.
United States
FDA food-contact material standards govern polyethylene and nylon net bags distributed through retail channels, requiring migration testing for indirect additive exposure. Pharmaceutical cold-chain operators favor breathable high-density polyethylene nets for temperature-sensitive palletization. Southeast distribution hubs serve agricultural cooperatives across Florida and California.
Bangladesh
Jute cultivation concentrates in the Ganges delta, supplying coarse bast fiber for agricultural bulk packaging with biodegradable credentials. Monsoon-dependent harvest variability exposes converters to supply concentration risk. Dhaka-based processors export to European orchard cooperatives seeking soil-disposable harvesting nets.
Net Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material chemistry and end-use segments. Market structure tilts toward consolidation as centralized retail procurement compresses supplier counts. Three archetypes dominate: petrochemical-integrated mesh converters, natural fiber specialists with Bangladeshi or Indian supply bases, and diversified packaging conglomerates with pan-European distribution assets. Competitive moves center on backward integration into fiber extrusion and strategic partnerships with agricultural cooperatives for direct procurement bypass.
Among vertically integrated specialists, GSH Group exemplifies captive control over fiber extrusion and finished bag production. LC Packaging International BV anchors European distribution positioning through Netherlands-based warehousing infrastructure. Karatzis S.A. occupies a specialist tier focused on high-tenacity polyethylene constructions. These three represent distinct competitive vectors: upstream manufacturing control, logistics network scale, and technical performance specialization respectively.
| Leading Market Players |
|---|
| GSH Group |
| Chemco Group |
| LC Packaging International BV |
| Packnatur GmbH |
| SKAPS Industries |
| Intermas Nets |
| EXPO-NET |
| Karatzis S.A. |
| ULINE |
| Others |
Supply & Pricing Matrix
EU REACH compliance mandates for food-contact additive disclosure gate both qualified supply and premium-tier pricing access, as converters lacking certified additive packages face exclusion from REWE and EDEKA tenders while ECHA-registered suppliers command certification premiums.
Pricing Analysis
Margin tightening in standard-grade polyethylene net bags reflects ethylene feedstock volatility from Middle Eastern naphtha cracking operations. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered suppliers from uncertified converters from commodity spot buyers. Price differentiation hinges on REACH certification tier and volume scale in centralized retail tenders. Supermarket conglomerates exhibit highest price sensitivity, while pharmaceutical cold-chain operators prioritize FDA migration compliance over unit cost.
Supply Chain Analysis
Direct-to-farm digital channels and Netherlands-based distribution hubs handle pan-European agricultural demand. Raw material supply concentrates in Bangladesh and India for jute bast fiber, Saudi Arabia and Qatar for ethylene feedstock, and Germany for high-tenacity polyethylene extrusion. Supply chain risk centers on monsoon-dependent harvest variability in the Ganges delta. Distribution runs through Rotterdam warehousing infrastructure and specialized agricultural supply platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized knitting technician scarcity in Portugal and Greece props pricing for high-tenacity cargo net production, creating supply-constrained conditions favoring incumbent converters with captive vocational training pipelines.
For Market Incumbents: Deploy backward integration into polylactic acid and hemp-blend fiber extrusion to preempt biodegradable substitution threats from emerging compostable net specialists. Capture orchard cooperative procurement directly through agricultural supply platforms, bypassing traditional distributor markups that compress margins. For New Entrants and Emerging Players: The premium-economy price-point gap in cotton mesh produce bags creates entry space for mid-tier certified compostable alternatives. Target French supermarket compliance with AGEC extended producer responsibility laws, where municipal waste reduction ordinances accelerate procurement of reusable containment. Lead with digital-native direct-to-consumer channels displacing traditional retail distribution. For Investors and Strategic Acquirers: REWE and EDEKA group purchasing consolidation into pan-European tenders is the leading indicator that supplier relationship concentration will accelerate. Five-to-ten-year viability favors converters with Netherlands warehousing assets and ECHA-registered additive packages. Monitor FDA food-contact certification queue times at third-party laboratories as inflection signal for product pipeline freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Fiber Extrusion | Polylactic acid and hemp-blend captive supply secures compostable net bag positioning ahead of EU Green Deal enforcement. |
| Direct-to-Farm Digital Channel Development | Agricultural supply platforms enable bypass of distributor markups for Spanish and Italian orchard cooperative procurement. |
| ECHA REACH Certification Investment | Registered additive packages qualify converters for REWE and EDEKA centralized tenders with mandatory disclosure requirements. |
| Netherlands Warehousing Infrastructure Expansion | Rotterdam distribution hubs anchor pan-European agricultural mesh logistics for Dutch flower auction cooperatives. |
| Vocational Training Pipeline for Raschel Knitting | Specialized technician programs in Portugal and Greece replenish retiring skills for high-tenacity polyethylene cargo net production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fiber extrusion plant managers, supermarket category buyers, agricultural cooperative procurement leads, and ECHA regulatory affairs specialists. Secondary sources included EU Single-Use Plastics Directive implementation reports, FDA food-contact material guidance, and Bangladesh jute cultivation statistics. Bottom-up demand modeling and top-down supply capacity estimates were triangulated for convergence.
Data-stream reconciliation across material type, product configuration, end-user category, and geographic regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions. Industry-specific forecast inputs included ethylene feedstock price indices and ECHA authorization list expansion timelines.
Inputs from EU regulatory databases and Bangladesh agricultural statistics were available through the study window; gaps in monsoon-dependent jute harvest data introduce uncertainty bands around natural fiber supply assumptions. Forecasts reflect documented base-case assumptions regarding REACH enforcement timing and retail procurement consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Isothermal Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Global PP Jumbo Bags Market