
 Quad Seal Bag Market | 2026-2036
Quad Seal Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Quad Seal Bag Market Outlook
Subscription-based packaging design services is expanding how converters monetize quad seal bag relationships beyond unit sales. Amcor plc leverages its global film extrusion network to supply pre-qualified laminates for food-contact applications. Mondi Group anchors European demand through integrated kraft paper and barrier film production. Sealed Air Corporation differentiates via automated bagging equipment bundled with material supply contracts.
A quad seal bag employs four side seals to create a rectangular base and vertical panels, typically constructed from laminated films incorporating polyethylene, polyethylene terephthalate, or aluminum oxide barrier layers to achieve oxygen transmission rates below 0.1 cc per square meter per day. This geometry maximizes printable surface area and stable pallet stacking for dry goods, coffee, and powdered supplements. Stand-up pouches within the product type category command premium positioning due to consumer convenience and retail shelf presence, while biodegradable films represent the fastest-growing material trajectory as brand owners face plastic reduction commitments. Small-to-medium size configurations dominate volume for single-serve and sample applications, whereas large format bags concentrate margin pools in industrial ingredient and agricultural sectors.
FDA food-contact notification requirements govern material composition for quad seal bags entering United States food channels, while EU REACH and the Packaging and Packaging Waste Regulation shape substance restrictions and extended producer responsibility obligations across European markets. The EU Green Deal's carbon border adjustment mechanism will incrementally raise compliance documentation burdens for imported film substrates. Stakeholders must monitor how California's SB 54 implementation and emerging state-level extended producer responsibility laws in the United States interact with federal frameworks to determine whether regional specification divergence or harmonization prevails.
Market Dynamics
Specialty coffee roasters and premium pet food brands are accelerating adoption of quad seal formats for shelf differentiation, while REACH compliance in Europe and evolving FDA food-contact material rules in the United States are reshaping specification requirements for multilayer barrier films. This dual pressure from brand owners seeking premium aesthetics and regulators tightening chemical safety standards is compressing converter margins while rewarding technical sophistication.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are pushing brand owners toward higher-performance formats like quad seal bags that reduce material intensity per unit volume.
- Specialty coffee roasting:Third-wave coffee brands prioritize oxygen transmission rates below 0.1 cc per square meter per day to preserve volatile aromatics, driving specification upgrades across North American and European supply chains.
- Germany's precision engineering culture:Converter capability and packaging machinery investment in Bavaria and Baden-Württemberg are concentrating high-barrier film production capacity for export markets.
Market Restraints
- Aluminum oxide barrier layer cost volatility:Thin-film deposition equipment and precursor material pricing swings compress converter margins when brand owners resist pass-through.
- Multilayer film recycling infrastructure gaps:Mechanical separation limitations for polyethylene-polyethylene terephthalate laminates create compliance friction under emerging state-level extended producer responsibility laws.
- Stand-up pouch substitution:Alternative formats with lower capital equipment requirements capture share in mid-tier dry goods segments where shelf differentiation matters less.
Strategic Opportunities
- Biodegradable film convergence:Polylactic acid and polyhydroxyalkanoate barrier technologies are opening premium positioning for brands with plastic reduction commitments.
- Subscription-based packaging design services:Converters monetize relationships through recurring revenue streams for structural engineering and print optimization rather than transactional unit sales.
- Industrial ingredient bulk formats:Large configuration quad seal bags for agricultural and food manufacturing inputs concentrate margin pools underserved by commodity flexible packaging suppliers.
Industry Challenges
- Multilayer coextrusion technician scarcity:Specialized knowledge of tie-layer chemistry and barrier film lamination is concentrating among aging workforces in Germany and the United States.
- FDA food-contact notification timelines:New material approvals for novel biodegradable substrates extend commercialization cycles by 18-24 months versus conventional polyethylene structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quad Seal Bag Market |
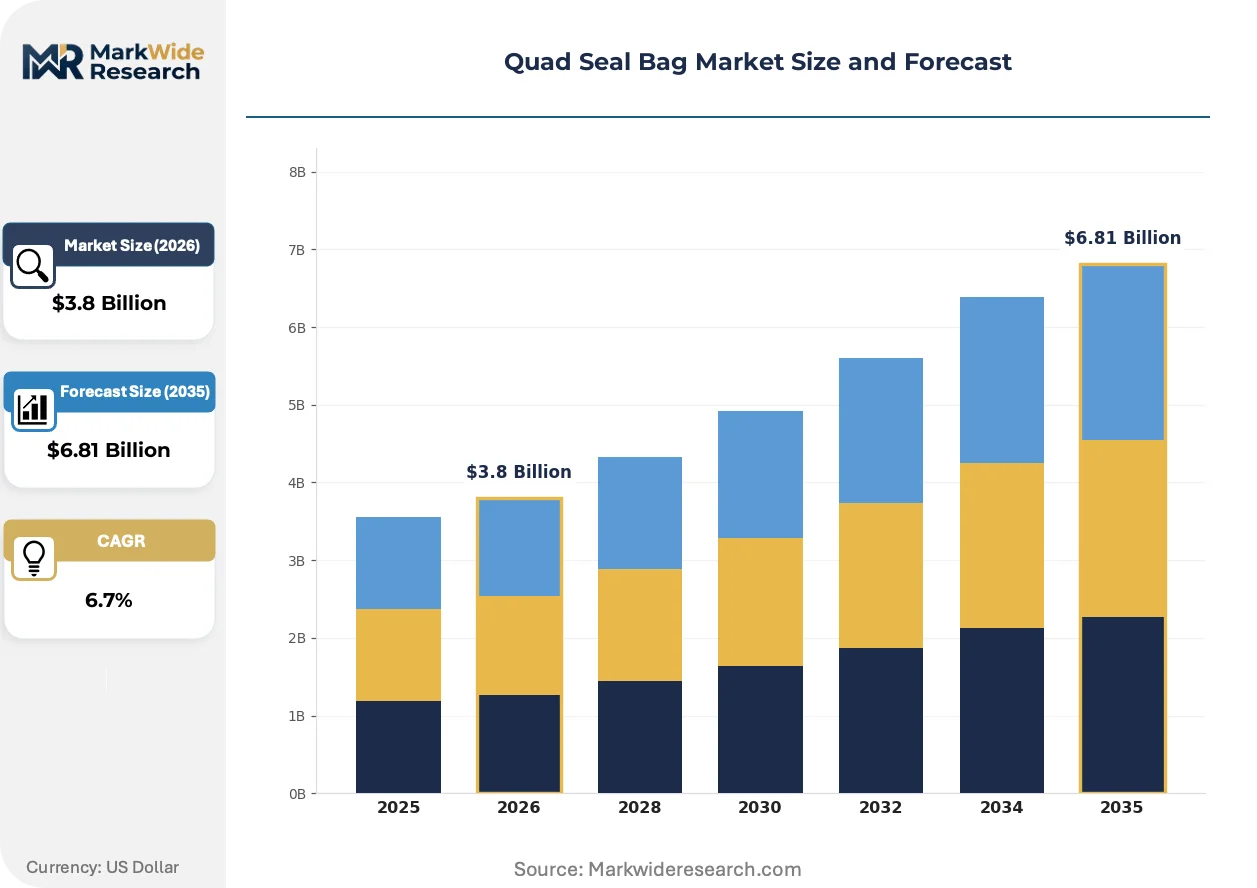
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-Up Pouches, Gusseted Bags, Custom Bags Material: Plastic, Paper, Biodegradable Films, Aluminum Foil End User: Food & Beverages, Pharmaceuticals, Cosmetics, Industrial Size: Small, Medium, Large, Custom |
| Companies Covered | Amcor plc, Mondi Group, Sealed Air Corporation, Tyler Packaging Limited, Foster Packaging Pty Ltd, Diamond Flexible Packaging Co., Pacific Bag, Inc., Swiss Pack Pvt Ltd, Cas-Pak Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quad Seal Bag Market Strategic Shifts
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability for specialty food and supplement brands. These capabilities are reshaping how converters compete on speed and customization rather than scale alone.
High-definition flexographic and inkjet printing systems are electrifying short-run production economics for regional coffee roasters and craft pet food brands. Equipment suppliers report 40% capacity utilization thresholds dropping toward 500-unit runs. This technology is electrifying market entry for micro-brands previously excluded by rotogravure cylinder costs and 10,000-unit minimums.
EU REACH substance restrictions and the Packaging and Packaging Waste Regulation are forcing reformulation of adhesives and inks across European converter operations. Bisphenol A and per- and polyfluoroalkyl substance restrictions are eliminating incumbent chemistries. German converters are responding fastest, leveraging existing technical service relationships with film suppliers to qualify replacement laminates ahead of enforcement deadlines.
Brand owners are unbundling structural design from material procurement, contracting directly with specialized packaging engineers while sourcing films through separate tenders. This disintermediation of converter value chains is most visible in United States specialty coffee, where roasters retain intellectual property for unique bag geometries. Third-party design boutiques in Portland and Brooklyn are capturing fees previously embedded in converter margins.
Quad Seal Bag Market Segmentation
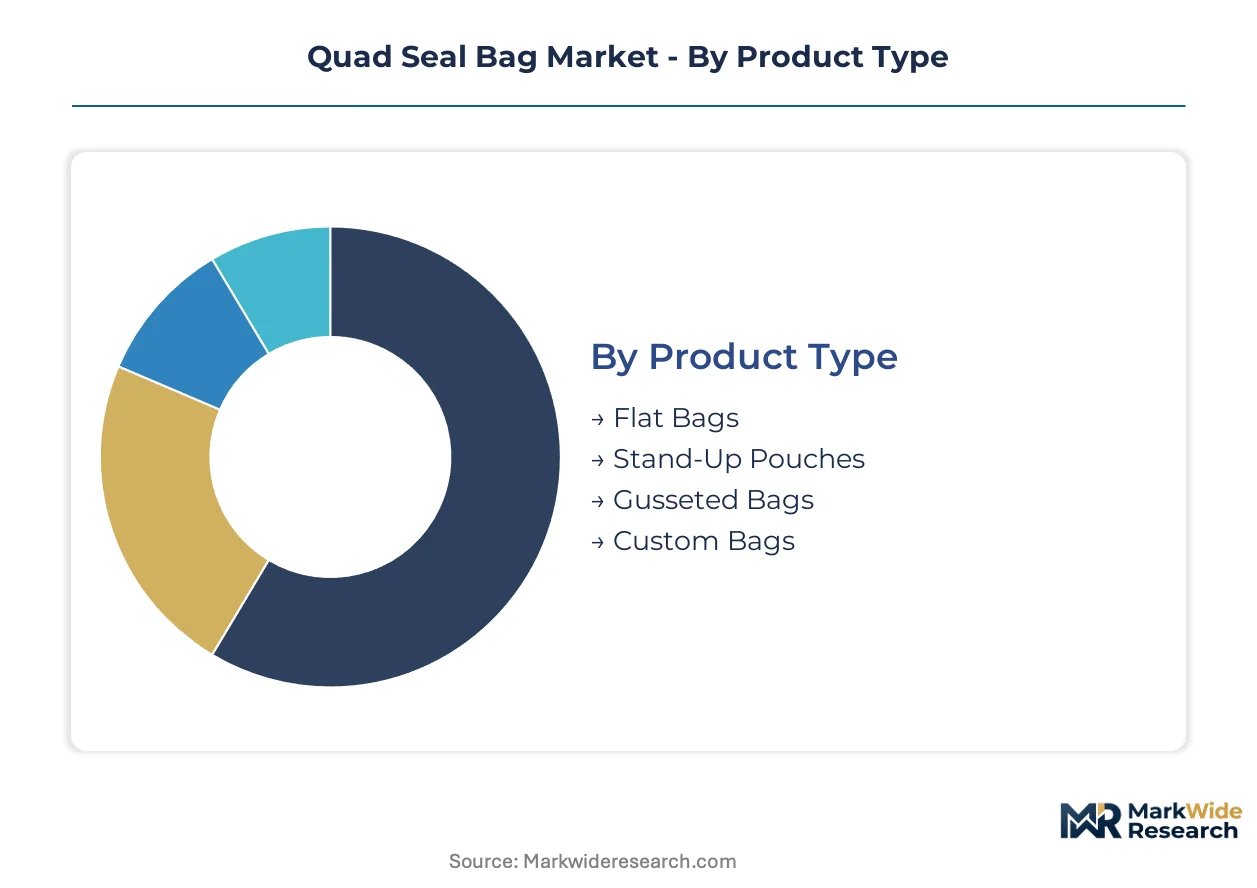
Quad seal bag configurations serve distinct operational requirements across supply chains, from automated filling lines demanding dimensional precision to retail environments prioritizing shelf presence. Each segment category reflects divergent technical specifications, material investments, and margin structures that reshape converter capabilities and procurement patterns.
Product Type:
Flat bags function as standalone packaging for automated high-speed lines, while stand-up pouches embed consumer-facing features that command premium positioning in retail environments.
- Flat Bags:Four-side seal geometry with minimal material overhead suits bulk ingredient handling and B2B distribution channels. Demand concentrates in German industrial ingredient supply chains where pallet stability and oxygen transmission rates below 0.1 cc per square meter per day preserve product integrity during extended storage.
- Stand-Up Pouches:Rectangular base construction with vertical panels maximizes printable surface area for brand differentiation. Specialty coffee roasters in Portland and Brooklyn drive specification upgrades for volatile aromatic preservation, combining zipper reclosure with degassing valves.
- Gusseted Bags:Side-fold expansion accommodates volume variation without format changeover.
- Custom Bags:Proprietary geometries developed under direct brand owner engineering contracts.
Volume placements concentrate in flat bags; the faster expansion belongs to stand-up pouches.
Material:
Material selection stratifies across barrier performance tiers, with commodity laminates serving cost-sensitive applications and engineered substrates capturing sustainability premiums.
- Plastic:Multilayer polyethylene and polyethylene terephthalate laminates dominate functional barrier requirements through coextrusion and adhesive lamination. REACH compliance in Europe and FDA food-contact notifications in the United States reshape adhesive and ink formulations across converter operations.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate technologies open premium positioning for brands with plastic reduction commitments. Extended FDA notification timelines for novel substrates stretch commercialization cycles versus conventional structures.
- Paper:Kraft-based constructions with barrier coatings serve dry goods with moderate shelf-life requirements.
- Aluminum Foil:Metallized and aluminum oxide deposition achieves ultra-low oxygen transmission for oxygen-sensitive pharmaceuticals and specialty foods.
Plastic retains dominant volume share; biodegradable films are climbing the fastest as extended producer responsibility mandates tighten across European markets.
End User:
End-use concentration reflects divergent regulatory exposure, with food-contact applications facing FDA and EFSA scrutiny while industrial segments prioritize mechanical performance over chemical compliance.
- Food & Beverages:Oxygen barrier specifications below 0.1 cc per square meter per day preserve volatile aromatics in specialty coffee and powdered supplements. Third-wave roasting brands in Germany and the United States drive adoption of high-barrier quad seal formats for retail shelf differentiation.
- Pharmaceuticals:USP and EP compliance requirements govern multilayer film selection for active pharmaceutical ingredient protection. Moisture vapor transmission rate specifications often dictate aluminum oxide or foil-containing laminates.
- Cosmetics:Premium positioning through tactile finishes and metallic effects.
- Industrial:Large-format configurations for agricultural and chemical inputs prioritize puncture resistance over barrier precision.
Food and beverage applications command dominant volume; pharmaceuticals deliver the steepest margin expansion trajectory.
Size:
Size configuration aligns with distribution channel economics, where single-serve formats serve direct-to-consumer subscription models and bulk formats concentrate in manufacturing input supply chains.
- Small:Single-serve and sample configurations suit specialty coffee tasting kits and supplement trial packs. Digital printing enables 500-unit minimum order quantities for micro-brands previously excluded by rotogravure cylinder costs.
- Large:Industrial ingredient and agricultural input formats concentrate margin pools underserved by commodity flexible packaging suppliers. Bavarian converter investments in high-speed bagging equipment capture this segment.
- Medium:Standard retail shelf configurations for mainstream dry goods.
- Custom:Dimensional specifications tied to proprietary filling equipment.
Medium sizes retain volume concentration; large formats are gaining share fastest in industrial supply chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in Germany while consumption spreads across specialty coffee clusters in the United States and industrial ingredient buyers in Asia-Pacific. This geographic split shapes trade flows and specification divergence.
Germany
Precision engineering culture drives Bavarian and Baden-Württemberg converter investments in high-speed bagging equipment for export markets. REACH compliance deadlines force rapid adhesive and ink reformulation across converter operations. Stuttgart-based machinery suppliers anchor technical service relationships that accelerate laminate qualification cycles.
United States
Third-wave coffee roasters in Portland and Brooklyn specify oxygen transmission rates below 0.1 cc per square meter per day for volatile aromatic preservation. FDA food-contact notification requirements govern multilayer film composition for specialty food channels. California's SB 54 implementation creates state-level extended producer responsibility friction distinct from federal frameworks.
China
Domestic flexible packaging demand absorbs regional converter capacity for industrial ingredient and agricultural input formats. The country's national packaging standards authority tightens food-contact material rules in parallel with import market requirements. Yangtze River Delta film extrusion clusters supply laminate substrates to Southeast Asian converter operations.
India
Specialty coffee roasting adoption accelerates in Bengaluru and Mumbai metro markets as premium retail formats penetrate tier-one cities. FSSAI food-contact regulations reshape specification requirements for imported multilayer barrier films. Maharashtra-based converters invest in digital printing capacity to serve micro-brand minimum order quantities.
United Kingdom
Premium pet food brands drive quad seal adoption for shelf differentiation in London and Southeast retail corridors. EU REACH substance restrictions continue influencing adhesive formulations despite post-Brexit regulatory divergence. Midlands converter operations specialize in short-run digital production for craft food and supplement brands.
Quad Seal Bag Market Competitive Environment
Top-tier vendors anchor integrated film-to-bag supply chains, while mid-tier converters compete on digital printing speed and design service bundling. The market structure rewards technical sophistication in barrier film lamination alongside regulatory compliance documentation capabilities. Three archetypes dominate: multinational material-science conglomerates with captive extrusion networks, regional specialists in high-barrier laminates, and digital-native converters serving micro-brand segments. Competitive moves concentrate on M&A for film extrusion assets and strategic partnerships between equipment suppliers and material vendors.
Within the integrated-materials tier, Amcor plc and Mondi Group exemplify scale-driven positioning through global film extrusion networks and European kraft paper integration respectively. Sealed Air Corporation occupies a distinct position bundling automated bagging equipment with material supply contracts. These three entities represent contrasting strategic postures: extrusion-led global supply, regional paper-film integration, and equipment-enabled service models.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Sealed Air Corporation |
| Tyler Packaging Limited |
| Foster Packaging Pty Ltd |
| Diamond Flexible Packaging Co. |
| Pacific Bag, Inc. |
| Swiss Pack Pvt Ltd |
| Cas-Pak Products Ltd |
| Others |
Value Chain & Pricing Dynamics
Aluminum oxide precursor material volatility flows from specialty chemical producers through converter operations into tiered pricing structures that separate premium barrier laminates from standard polyethylene configurations.
Pricing Analysis
Margin tightening in standard-grade laminates reflects brand owner resistance to aluminum oxide cost pass-through. Three-tier pricing structure across premium, standard, and economy levels stratifies by oxygen transmission performance and FDA pre-qualification status. Cost-down pressure on commodity converters accelerates because specialty coffee roasters consolidate procurement around pre-qualified suppliers. Industrial ingredient buyers exhibit highest price sensitivity; pharmaceutical and third-wave coffee segments absorb premium positioning.
Supply Chain Analysis
Barrier film substrate supply rests on German extrusion clusters, Chinese Yangtze River Delta producers, and South Korean specialty resin manufacturers. Raw material dependencies encompass polyethylene terephthalate resin, aluminum oxide deposition equipment, and REACH-compliant adhesive formulations. Single-source vulnerability concentrates in thin-film metallization equipment where German and Japanese suppliers dominate technical service relationships. Distribution runs through converter-direct contracts for large-volume food and beverage accounts, with digital-native converters serving micro-brand segments via e-commerce procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quad seal bag competition is becoming a vertical-integration race as converters pursue captive film extrusion capacity to secure barrier laminate supply and margin control.
For Market Incumbents: Extend technical service relationships with specialty coffee roasters into subscription-based packaging design services, converting transactional unit sales into recurring revenue. Capture Bavarian and Baden-Württemberg machinery suppliers through exclusive equipment bundling agreements that lock out rival material vendors. Biodegradable film qualification timelines and multilayer coextrusion technician scarcity represent the primary defensive moats.
For New Entrants and Emerging Players: Micro-brand specialty coffee roasters in Portland, Brooklyn, and Bengaluru present the most penetrable entry point, as these buyers prioritize digital printing speed and 500-unit minimums over incumbent scale. Target industrial ingredient bulk formats in agricultural supply chains where commodity flexible packaging suppliers underserve margin pools. Lead with digital-native design boutiques that unbundle structural engineering from material procurement.
For Investors and Strategic Acquirers: FDA food-contact notification submissions for novel biodegradable substrates is the leading indicator that polylactic acid and polyhydroxyalkanoate barrier technologies are approaching commercial viability. Acquisition candidates include regional high-barrier laminate specialists with REACH-compliant adhesive formulation capabilities and established technical service relationships. Watch for California SB 54 implementation friction creating state-level extended producer responsibility compliance premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polyethylene terephthalate supply secures barrier laminate margins against aluminum oxide volatility. |
| Biodegradable Film Qualification Program | Polylactic acid substrate FDA notification positions converters for plastic reduction commitment premiums. |
| Digital Printing Capacity Expansion | Short-run production economics at 500-unit thresholds unlock micro-brand segments previously excluded by rotogravure. |
| Equipment Bundling Partnership | Stuttgart-based machinery supplier alliances create exclusive automated bagging equipment distribution channels. |
| Subscription Design Service Launch | Recurring revenue from structural engineering and print optimization monetizes converter relationships beyond unit sales. |
Study Parameters
Trade association filings, customs import records, and FDA food-contact notification databases formed the secondary backbone, cross-referenced against primary interviews with converter operations managers, specialty coffee roaster procurement leads, multilayer film extrusion technicians, and packaging machinery supplier technical directors. Bottom-up triangulation across product type, material grade, end-use application, and size configuration validated top-down market sizing derived from film substrate production capacity and bagging equipment installation data.
Bottom-up volume modeling tracked laminate substrate consumption through the analysis window, segmented by barrier performance tier, geographic production cluster, and regulatory compliance status. Value projections incorporated raw material cost pass-through assumptions, premium positioning coefficients for biodegradable films, and equipment bundling contract structures. CAGRs derived from segment-level growth trajectories weighted by end-use concentration in food and beverage channels.
Revisions become necessary when REACH substance restriction enforcement timelines accelerate, FDA notification backlogs extend commercialization cycles, or state-level extended producer responsibility laws fragment specification requirements across United States markets. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Shrink Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Woven Bags Market