
 Bag Making Machine Market | 2026-2036
Bag Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Making Machine Market Outlook
The gap between premium servo-driven systems and basic mechanical units is shifting from a price divide into a capability chasm. Windmöller & Hölscher leverages German engineering heritage to dominate high-speed flexographic integration lines. Zhejiang Ounuo Machinery Co., Ltd. anchors the mid-market with standardized configurations for emerging Asian converters. Holweg Weber specializes in niche paper-forming equipment for pharmaceutical-grade pouches.
A bag making machine is an automated or semi-automated production system that converts flat substrate rolls into finished bags through heat-sealing, cutting, and handle-attachment cycles operating at speeds from 50 to 600 bags per minute depending on configuration. These systems serve retail distribution, food preservation, and industrial bulk-handling workflows where consistent seal integrity and throughput determine operational economics. Plastic bag machines still occupy the largest installed base but face margin compression as regulatory bans proliferate across municipalities. Paper bag machines represent the fastest-growing technology category as quick-service brands eliminate plastic carryout. Non-woven bag machines sustain steady demand from reusable shopping bag mandates in European supermarkets.
The EU F-Gas Regulation and REACH compliance requirements shape material compatibility specifications for sealing components and adhesive systems across machines exported into Europe. The US FDA maintains strict contact-surface standards for food packaging equipment sold into interstate commerce, while China's SAMR enforces GB standards on domestic and imported machinery alike. Stakeholders must track evolving substrate certification requirements before committing to platform architectures that lock out next-generation biodegradable films.
Market Dynamics
Substrate migration from plastic to paper and biodegradable films is restructuring machine specifications across the installed base. EU Single-Use Plastics Directive enforcement and China's dual carbon goals are forcing converters to retool lines for heat-sealing compatibility with cellulose-based materials.
Growth Catalysts
- Regulatory phase-out mandates:The EU Single-Use Plastics Directive and municipal plastic bag bans across North American cities are compelling food packaging converters to replace legacy plastic lines with paper-capable systems.
- Quick-service restaurant expansion:Southeast Asian QSR chains are scaling carryout operations, driving demand for high-throughput pouch and handle-bag equipment in Vietnam's industrial zones near Ho Chi Minh City.
- Biodegradable film commercialization:PLA and PHA substrate advances are opening new machine categories requiring modified sealing temperature profiles and adhesive systems.
Market Restraints
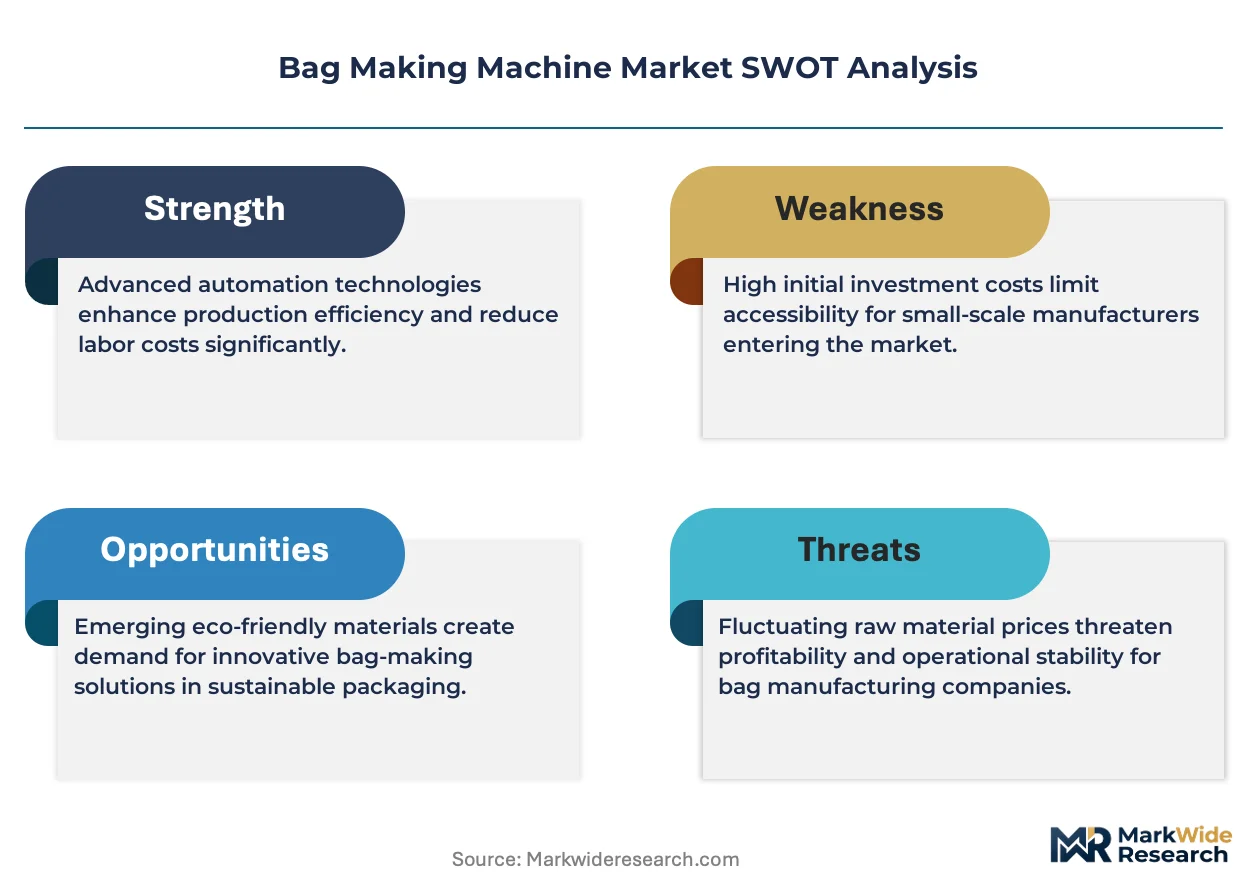
- Steel and servo motor cost volatility:Input price swings for precision mechanical components compress margins on standardized mid-market equipment.
- Specialized component supply concentration:High-frequency sealing jaws and ceramic-coated cutting assemblies depend on German and Japanese precision metalworking suppliers.
- Technical sealing limitations:Paper substrates lack the thermal elasticity of polyethylene, restricting line speeds and requiring longer dwell times that reduce effective throughput.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya lack domestic bag machine manufacturing, creating import-dependent markets for refurbished European and Asian equipment.
- Pharmaceutical-grade pouch applications:Sterile barrier packaging for medical devices demands cleanroom-compatible paper-forming systems with validated seal integrity protocols.
- India's PLI scheme for packaging machinery:Production-linked incentives for capital goods manufacturing attract assembly operations serving South Asian and Middle Eastern converters.
Industry Challenges
- Cross-functional engineering talent scarcity:Machine builders struggle to hire technicians fluent in both mechanical drive systems and programmable logic controller programming.
- Multi-jurisdiction certification timelines:Obtaining concurrent CE marking, US FDA food contact surface validation, and China GB standard compliance extends product launch cycles by 8-14 months.
- Legacy line integration complexity:Retrofitting servo-driven sealing modules onto mechanical cam-driven frames requires custom mechanical adapters that void original equipment warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Making Machine Market |
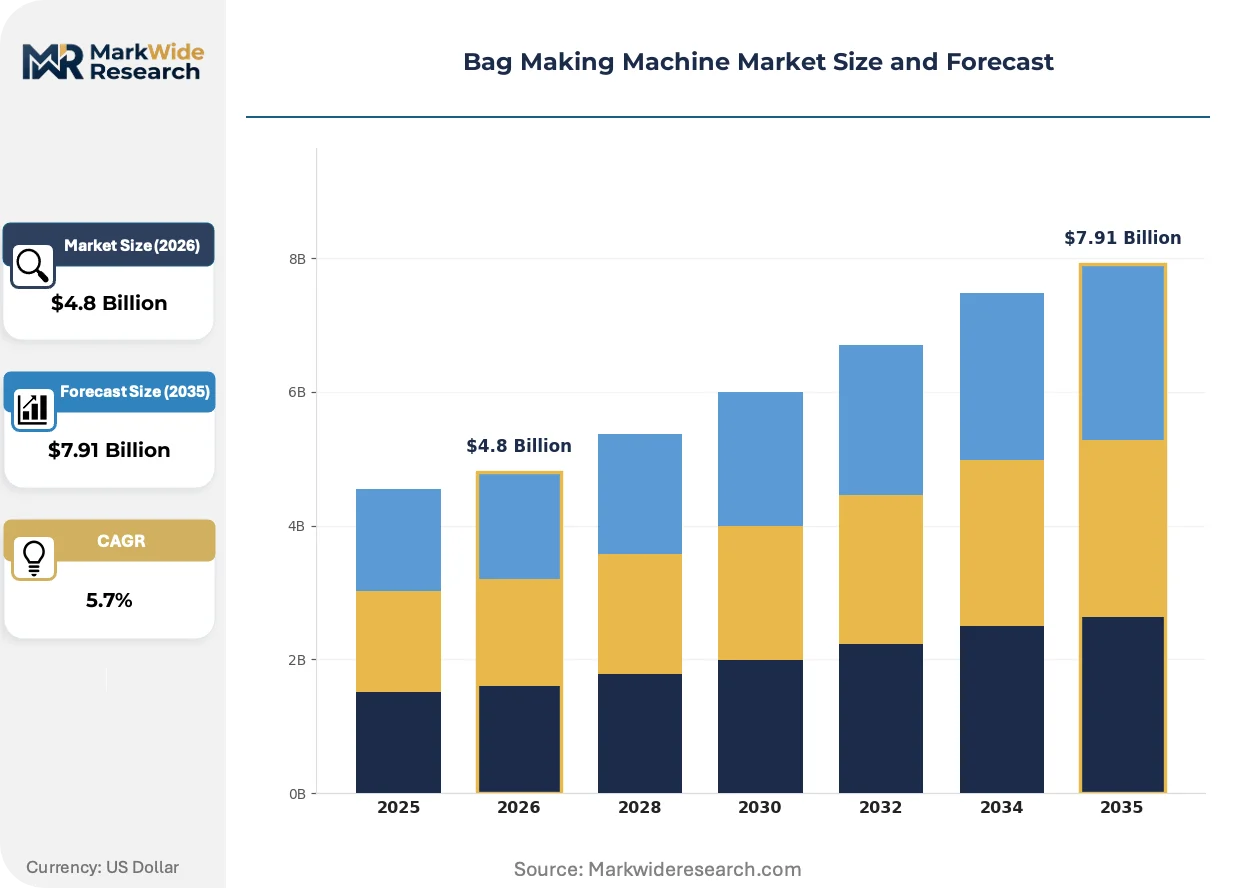
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bag Machines, Paper Bag Machines, Woven Bag Machines, Non-Woven Bag Machines Technology: Automatic, Semi-Automatic, Manual, Digital End User: Retail, Packaging, Food & Beverage, Pharmaceutical Application: Shopping Bags, Garbage Bags, Food Packaging, Industrial Packaging |
| Companies Covered | Newlong Machine Works, Ltd., Zhejiang Ounuo Machinery Co., Ltd., KIMATIC SRL, CMD Corporation, S-DAI Industrial Corporation Ltd., Holweg Weber, Windmöller & Hölscher, Zhejiang Youjia Machinery Co., Ltd., Mamata Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Making Machine Market Strategic Shifts
Digital control architectures and substrate material science are converging to redefine machine performance benchmarks. The transition from fixed mechanical timing to adaptive process control is enabling real-time parameter adjustment during production runs.
Direct-drive servo motors are overtaking mechanical cam systems as the dominant actuation method for sealing and cutting stations. Quick-service restaurant converters in Southeast Asia are specifying all-electric lines for their flexibility across bag formats. This shift is compressing maintenance intervals and reducing changeover downtime from hours to minutes.
REACH compliance requirements are reshaping material specifications for sealing components exported into Europe. ECHA restrictions on per- and polyfluoroalkyl substances are forcing manufacturers to reformulate non-stick coatings on heat-sealing jaws. Food packaging equipment destined for EU markets now requires substance-of-concern documentation across the full bill of materials.
Converter procurement teams are consolidating vendor relationships and demanding outcome-based performance guarantees rather than equipment-only transactions. Large Southeast Asian packaging groups are negotiating throughput commitments and spare parts availability contracts as standard terms. This behavior is most visible in Vietnam's industrial zones where multinational QSR suppliers enforce supplier consolidation mandates.
Bag Making Machine Market Segmentation
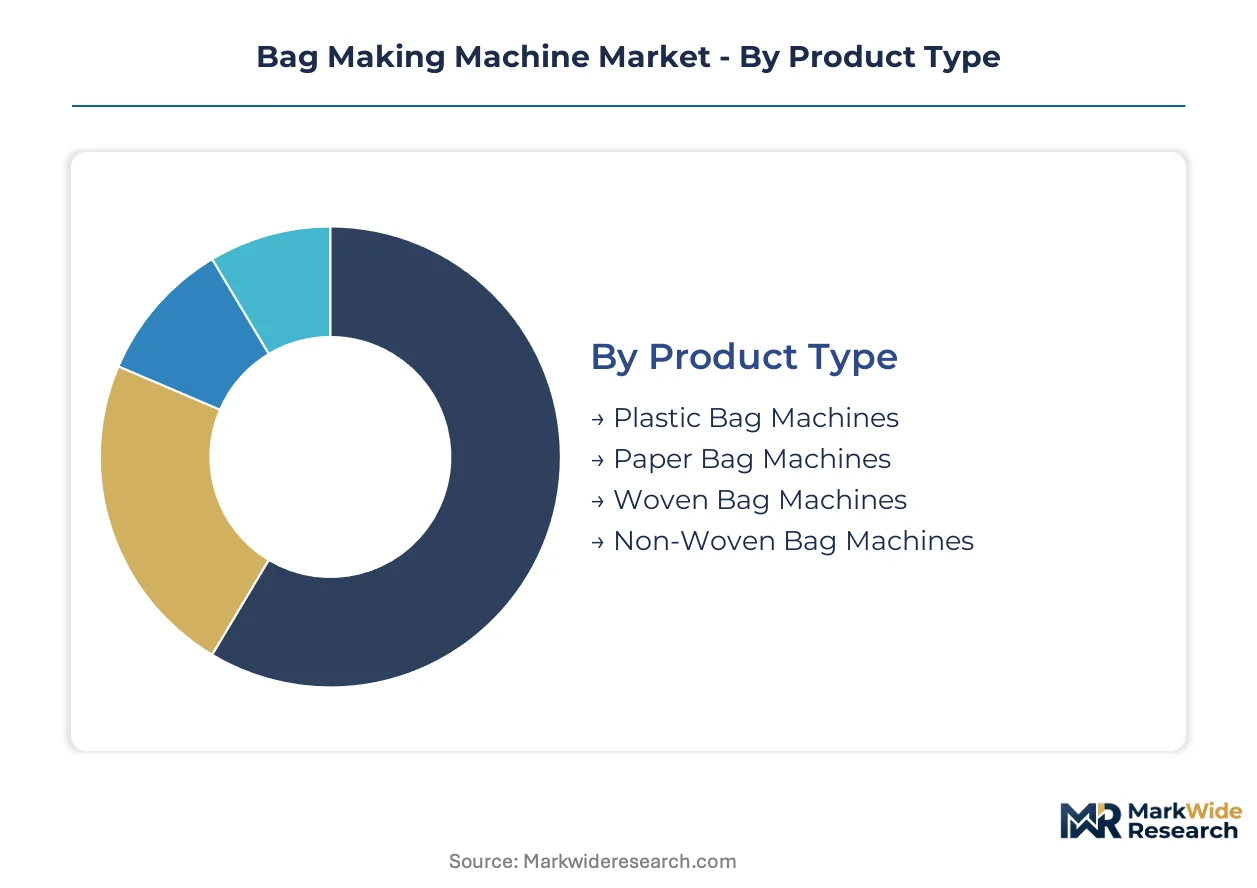
Bag making machine specifications diverge sharply based on substrate compatibility and throughput requirements. Converters select platforms that align with regulatory mandates and end-use certification standards rather than generic capacity metrics.
Product Type:
Supply concentration among German and Japanese component specialists favors machine builders with captive sourcing agreements for precision sealing jaws and ceramic cutting assemblies.
- Plastic Bag Machines:Heat-sealing systems process polyethylene and polypropylene films at speeds reaching 600 bags per minute. Quick-service restaurant chains in Vietnam's industrial zones near Ho Chi Minh City drive replacement demand as EU Single-Use Plastics Directive enforcement accelerates substrate migration.
- Paper Bag Machines:Forming equipment for cellulose-based substrates requires modified sealing temperature profiles and longer dwell times that reduce effective throughput. China's dual carbon goals and municipal plastic bans across North American cities position this category for sustained expansion.
- Woven Bag Machines:Heavy-duty systems produce polypropylene sacks for agricultural and construction bulk handling with mechanical stitching rather than heat sealing.
- Non-Woven Bag Machines:Ultrasonic welding platforms serve reusable shopping bag mandates in European supermarkets with spunbond polypropylene substrates.
Plastic bag machines absorb the bulk of installed capacity; paper bag machines are expanding most quickly.
Technology:
Cost tier differentiation separates premium servo-driven architectures from standardized mechanical configurations serving price-sensitive emerging markets.
- Automatic:Programmable logic controller architectures enable real-time parameter adjustment across sealing, cutting, and handle-attachment cycles. Southeast Asian packaging groups specify all-electric lines for format flexibility across pouch and carryout bag specifications.
- Semi-Automatic:Operator-assisted loading stations reduce capital outlay for small-batch converters in underpenetrated African markets lacking domestic manufacturing.
- Manual:Foot-pedal actuation survives in artisanal packaging workshops and refurbished equipment markets serving import-dependent regions.
- Digital:Adaptive process control systems integrate vision inspection and predictive maintenance modules for pharmaceutical-grade pouch validation protocols.
Automatic platforms command the dominant revenue share; digital configurations are climbing the fastest as converters consolidate vendor relationships around outcome-based performance guarantees.
End User:
Application-specific certification requirements fragment procurement patterns across food contact, sterile barrier, and industrial bulk-handling specifications.
- Retail:High-throughput lines produce branded carryout bags with inline printing for supermarket and department store chains.
- Packaging:Contract converters serving multinational brands require rapid changeover capability across substrate formats.
- Food & Beverage:Equipment must satisfy US FDA contact-surface standards for interstate commerce and EU F-Gas Regulation compliance for sealing component materials.
- Pharmaceutical:Cleanroom-compatible paper-forming systems with validated seal integrity protocols command premium pricing for sterile barrier medical device packaging.
Food and beverage applications anchor volume demand; pharmaceutical specifications show the steepest expansion trajectory as regulatory scrutiny intensifies.
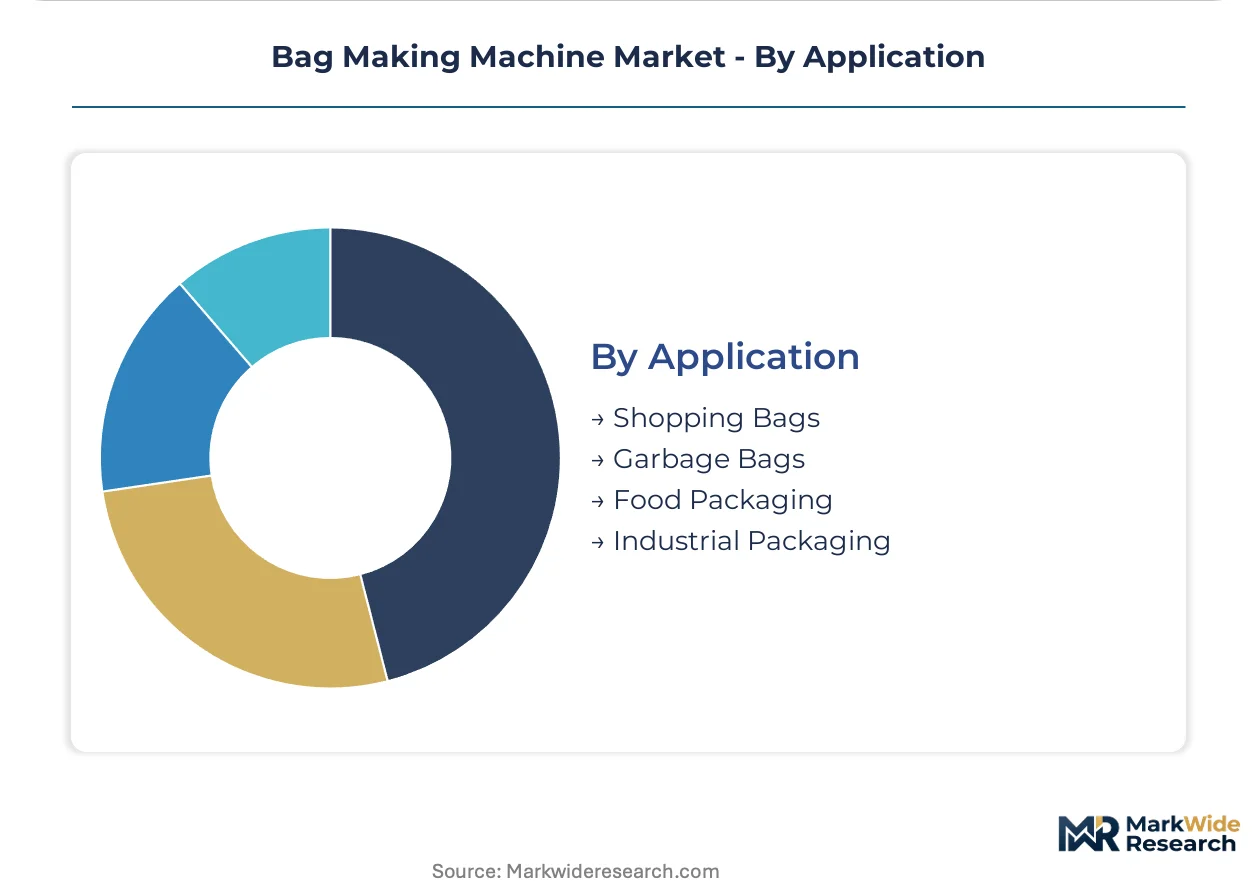
Application:
Volume concentration in commodity segments contrasts with margin-rich specialized formats requiring customized machine configurations.
- Shopping Bags:Handle-attachment modules and inline flexographic printing dominate quick-service restaurant and retail chain specifications.
- Garbage Bags:High-density polyethylene processing on continuous roll systems serves municipal and commercial waste management contracts.
- Food Packaging:Pouch and vacuum-seal configurations demand oxygen barrier compatibility and modified atmosphere sealing for preservation.
- Industrial Packaging:Heavy-gauge woven and laminated structures require reinforced stitching and gusset-forming capabilities for bulk chemical and mineral transport.
Shopping bags represent the largest addressable base; food packaging applications are gaining share fastest as biodegradable film commercialization opens new substrate categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's industrial zones near Ho Chi Minh City concentrate Southeast Asian bag machine procurement activity as quick-service restaurant chains scale carryout operations across the region.
United States
Food packaging converters in the Midwest and Southeast are retooling lines to meet municipal plastic bag bans spreading across California, New York, and Illinois. The FDA maintains strict contact-surface standards for interstate commerce equipment. Dallas-Fort Worth logistics hubs serve as distribution nodes for Mexican and Canadian cross-border equipment shipments.
Germany
Precision engineering heritage anchors European high-end machine manufacturing with flexographic integration lines commanding premium positioning. The ECHA REACH framework and EU F-Gas Regulation shape sealing component material specifications for exports. Stuttgart industrial corridors host component specialists supplying ceramic-coated cutting assemblies to global machine builders.
China
Domestic converters are migrating toward paper-capable systems under SAMR-enforced GB standards and national dual carbon goals targeting carbon neutrality. Yangtze River Delta manufacturing clusters near Shanghai produce standardized mid-market configurations for emerging Asian markets. Zhejiang province fabricators dominate regional supply for plastic-to-paper substrate transition demand.
India
The PLI scheme for packaging machinery attracts assembly operations targeting South Asian and Middle Eastern converter markets with production-linked incentives. BIS certification requirements govern domestic and imported equipment standards. Gujarat industrial corridors near Ahmedabad are emerging as assembly hubs for refurbished European and Chinese equipment serving price-sensitive regional buyers.
Brazil
Agricultural bulk-handling demand sustains woven bag machine procurement for polypropylene sack production serving soybean and mineral export supply chains. ANVISA pharmaceutical regulations create niche demand for sterile barrier packaging equipment in São Paulo state manufacturing zones. São Paulo industrial districts concentrate import-dependent converter operations lacking domestic machine fabrication capacity.
Bag Making Machine Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered market structure where German engineering heritage anchors premium positioning and Chinese standardized configurations capture mid-market volume. The vendor base separates into three strategic archetypes: precision component integrators serving pharmaceutical-grade specifications, scale-oriented fabricators optimizing for quick-service restaurant throughput requirements, and refurbished equipment traders addressing underpenetrated African and Latin American markets. Dominant competitive moves include strategic partnerships with sealing jaw specialists and geographic expansion through distributor networks in import-dependent regions.
Among Japanese precision fabricators, Newlong Machine Works, Ltd. exemplifies the component-integrated archetype, while Zhejiang Ounuo Machinery Co., Ltd. and Zhejiang Youjia Machinery Co., Ltd. occupy positions within the standardized mid-market tier serving emerging Asian converter demand. Windmöller & Hölscher represents the premium engineering heritage segment with German-origin flexographic integration capabilities. Holweg Weber sits within the niche specialization vector targeting pharmaceutical-grade paper-forming applications.
| Leading Market Players |
|---|
| Newlong Machine Works, Ltd. |
| Zhejiang Ounuo Machinery Co., Ltd. |
| KIMATIC SRL |
| CMD Corporation |
| S-DAI Industrial Corporation Ltd. |
| Holweg Weber |
| Windmöller & Hölscher |
| Zhejiang Youjia Machinery Co., Ltd. |
| Mamata Enterprises, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in Zhejiang province anchor supply-side discipline through backward integration into servo motor assembly, compressing price elasticity for standardized configurations while premium German engineering houses maintain value-based pricing power through captive sealing jaw technology.
Pricing Analysis
Value-based pricing anchored to throughput guarantees dominates procurement negotiations in Vietnam's industrial zones near Ho Chi Minh City. Three-tier pricing structure across premium servo-driven, standard automatic, and economy semi-automatic levels reflects certification grade differentiation and after-sales bundling intensity. Cost compression in mid-market mechanical configurations is intensifying because steel and servo motor input volatility erodes margin buffers. Small-batch converters in underpenetrated African markets exhibit highest price sensitivity, while pharmaceutical-grade pouch specifications show lowest elasticity due to validated seal integrity requirements.
Supply Chain Analysis
High-frequency sealing jaw supply rests on German and Japanese precision metalworking specialists, with ceramic-coated cutting assembly production concentrated in Stuttgart industrial corridors and Nagoya manufacturing clusters. Raw material flows draw from Chinese steel mills for frame fabrication, Taiwanese servo drive controllers for actuation systems, and Italian flexographic printing modules for inline branding. Single-source vulnerability around pharmaceutical-grade coating formulations creates exposure to ECHA REACH substance restrictions. Distribution runs through regional equipment distributors with aftermarket service contracts in import-dependent markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where multi-jurisdiction certification timelines and cross-functional engineering talent scarcity force sub-scale fabricators toward distressed exits or strategic absorption.
For Market Incumbents: Extend platform architecture flexibility through modular servo retrofit kits that preserve warranty coverage for legacy mechanical frames, countering margin pressure from emerging Asian standardized configurations. Deepen captive supply agreements with Stuttgart-based ceramic coating specialists to lock in REACH-compliant sealing component flows before ECHA per- and polyfluoroalkyl substance restrictions tighten material specifications. For New Entrants and Emerging Players: Adaptive process control systems with integrated vision inspection offer a technology-first wedge into pharmaceutical-grade pouch validation protocols where incumbent warranty structures and validated seal integrity requirements create switching friction. Target underpenetrated Nigerian and Kenyan import-dependent markets with refurbished European equipment bundled with local spare parts availability contracts, leveraging absence of domestic manufacturing capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market standardized fabricators with established distributor networks in Southeast Asian quick-service restaurant supply chains, positioned for substrate migration tailwinds. Watch India's PLI scheme for packaging machinery as an inflection signal where production-linked incentive disbursement velocity indicates assembly operation commitment scale and regional hub emergence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Jaw Manufacturing | Captive supply of REACH-compliant ceramic coatings insulates German engineering houses from ECHA substance restrictions. |
| Modular Servo Retrofit Platform Development | Custom mechanical adapters preserve warranty coverage for legacy cam-driven frames during substrate migration retooling. |
| Pharmaceutical-Grade Validation Protocol Investment | Cleanroom-compatible paper-forming systems command premium positioning under FDA sterile barrier packaging standards. |
| Regional Distributor Network Expansion | Aftermarket service contracts in Vietnam's industrial zones secure quick-service restaurant procurement consolidation mandates. |
| Biodegradable Film Sealing Technology Licensing | Modified temperature profile patents for PLA and PHA substrates capture emerging regulatory-driven substrate categories. |
Study Parameters
Document review covered customs and trade flow databases, EU F-Gas Regulation implementation filings, and SAMR GB standard enforcement records, complemented by interviews with plant engineers at food packaging converters, procurement leads at quick-service restaurant supply chains, aftermarket service heads at regional distributors, and technical R&D directors at sealing component specialists. Bottom-up equipment shipment triangulation was cross-validated against top-down converter capacity expansion announcements across Vietnam's industrial zones near Ho Chi Minh City, Yangtze River Delta manufacturing clusters, and Gujarat assembly corridors.
Historical capacity installation patterns were cross-referenced against panel input from machinery procurement committees to anchor growth trajectory assumptions across the projection horizon. Segmentation modeling captured substrate type compatibility, automation technology tier, end-use certification requirements, and geographic regulatory cluster intensity. CAGRs were derived from elasticity-adjusted demand functions incorporating quick-service restaurant expansion rates, municipal plastic ban enforcement velocity, and biodegradable film commercialization timelines.
Several conditions sit outside the modeled scope, including sudden tariff reconfigurations affecting German-Japanese precision component trade flows, unscheduled ECHA substance restriction amendments, and force majeure disruptions at Yangtze River Delta steel processing centers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Circular Industrial Bags Market