
 Bag in Drum Market | 2026-2036
Bag in Drum Market Size, Share, and Industry Trends Forecast 2026-2036
Bag in Drum Market Outlook
Asset-light leasing models for returnable intermediate bulk containers is rewriting competitive entry barriers in drum packaging. Greif Inc. leverages its North American manufacturing footprint to sustain long-term supply contracts with chemical processors. SCHÜTZ GmbH anchors European demand through specialized composite drum systems engineered for hazardous material transport. Time Technoplast competes on cost-optimized polyethylene bag formulations serving agricultural and food-grade applications across Asian markets.
A bag in drum system comprises a flexible inner liner bag, typically constructed from multilayer polyethylene or laminated barrier films, inserted within a rigid outer drum to enable contained filling, storage, and discharge of liquid or powdered products. The inner bag collapses during evacuation, minimizing residual product and reducing cleaning requirements for the reusable outer drum. Polyethylene bag inserts lead volume due to cost efficiency and chemical compatibility, though composite configurations capture premium margin pools where barrier performance against oxygen and moisture migration is critical. Chemical end users represent the most structurally entrenched demand segment, while pharmaceutical applications exhibit the fastest expansion trajectory driven by sterility and contamination control protocols.
EPA hazardous waste container regulations and DOT transport requirements in the United States shape product certification pathways, while REACH and EU Packaging and Packaging Waste Directive compliance in Europe mandates material recyclability documentation and restricted substance thresholds. FDA food contact material standards additionally govern polyethylene liner formulations destined for food and beverage drum applications. Stakeholders must monitor evolving extended producer responsibility frameworks and assess whether barrier film innovation or circular material sourcing will become the decisive axis of competitive differentiation.
Market Dynamics
REACH compliance and EU packaging waste directives are tightening material traceability requirements, forcing specialty chemical manufacturers to expand procurement of multilayer barrier bag systems for drum inserts.
Growth Catalysts
- REACH substance restrictions:European chemical processors must document restricted substance thresholds in liner materials, accelerating replacement cycles for non-compliant bag systems.
- Hazardous material transport:DOT regulations in the United States mandate certified container systems for chemical drum shipments, structurally entrenching demand for engineered barrier configurations.
- Pharmaceutical sterility protocols:Contamination control standards in sterile manufacturing are displacing conventional drum cleaning methods with single-use liner systems.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices fluctuate with naphtha cracking margins, compressing formulation cost predictability for bag manufacturers.
- Barrier film supply concentration:EVOH and aluminum oxide coating capacity clusters in Japan and South Korea, creating import dependency for European and North American converters.
- Mechanical compatibility limits:Laminated barrier films exhibit reduced puncture resistance versus monolayer polyethylene, restricting adoption in abrasive powder handling.
Strategic Opportunities
- Indian specialty chemical expansion:CDSCO and DGFT compliance requirements for pharmaceutical exports are creating certified liner demand at Mumbai and Hyderabad manufacturing clusters.
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Directive amendments incentivize recyclable mono-material barrier designs over multi-polymer laminates.
- RFID-enabled track-and-trace:Convergence of printed electronics with barrier films is digitizing supply chain visibility for high-value chemical and pharmaceutical shipments.
Industry Challenges
- Multilayer coextrusion technician scarcity:Operating precision barrier film lines requires specialized polymer rheology expertise concentrated at aging European and Japanese technical centers.
- FDA food contact notification timelines:Novel polyethylene additive packages face 120-day pre-market review cycles, delaying formulation launches for food-grade drum applications.
- Legacy drum fleet interoperability:Existing steel and fiber drum dimensions vary across regional standards, complicating universal liner fitment specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag in Drum Market |
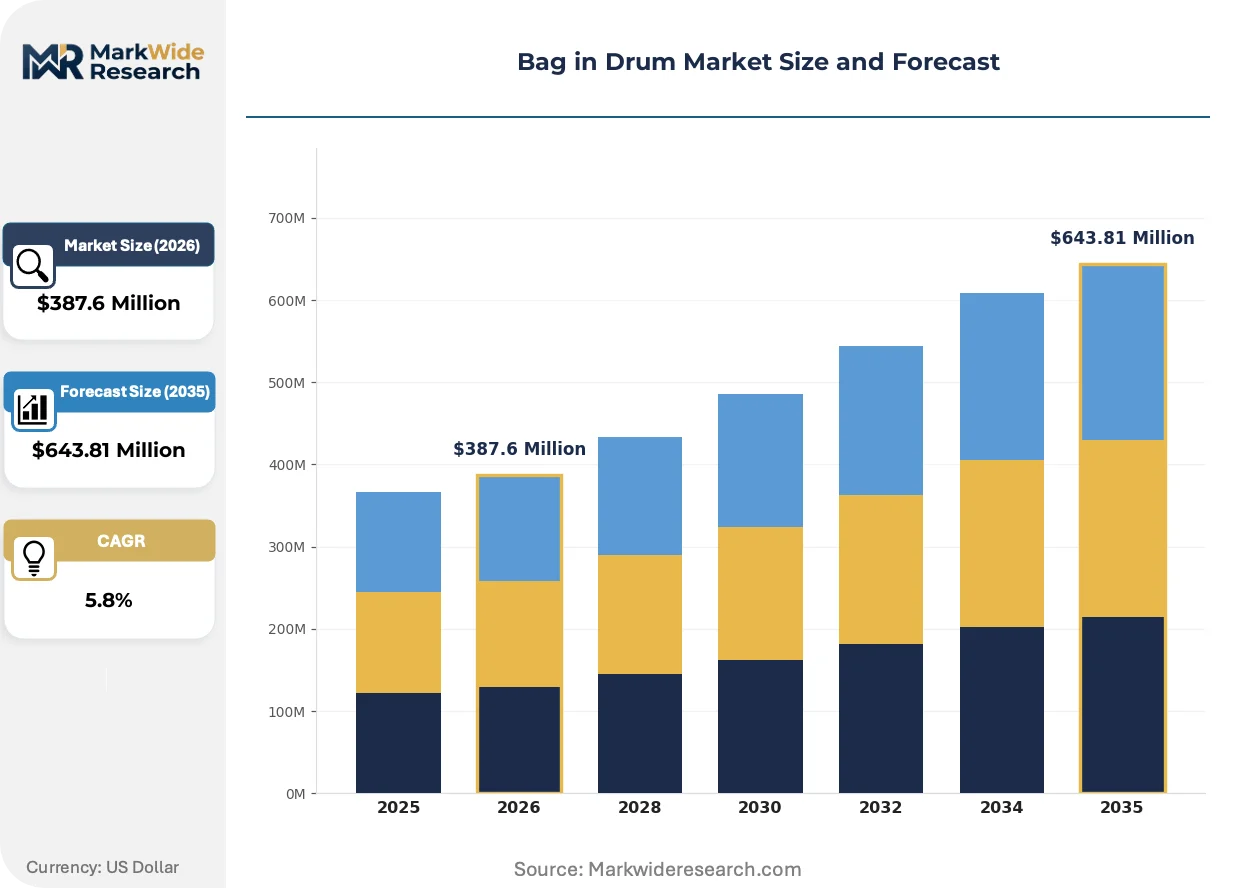
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Steel, Composite, Fiber End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale Capacity: 50 Liters, 100 Liters, 200 Liters, 1000 Liters |
| Companies Covered | Greif Inc., Mauser Group, SCHÜTZ GmbH, Time Technoplast, Orlando Drum & Container Corporation, Enviro-Pak, C.L. Smith, Muller Group, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag in Drum Market Strategic Shifts
Barrier film engineering and digital traceability integration are compressing the technical gap between commodity polyethylene liners and premium composite systems. These developments are reshaping how chemical and pharmaceutical processors specify containment solutions.
Smart barrier films incorporating embedded temperature and pressure sensors are digitizing real-time condition monitoring for temperature-sensitive pharmaceutical intermediates. Biologics manufacturers in Germany and Switzerland are piloting these systems for cold-chain drum shipments. The technology is digitizing quality assurance documentation, reducing manual inspection overhead while compressing insurance and liability exposure for high-value cargo.
EU F-Gas Regulation phase-down schedules are accelerating adoption of non-fluorinated high-barrier coatings in place of PVDC laminates for oxygen-sensitive chemical storage. Formulators in Ludwigshafen and Antwerp chemical clusters face reformulation mandates by 2027. The regulation is forcing migration to silicon oxide and aluminum oxide deposition technologies, with coating equipment suppliers reporting extended order backlogs from European converter investments.
Asset-light leasing models for returnable intermediate bulk containers are compressing capital deployment cycles for mid-volume chemical processors. Specialty chemical manufacturers in Texas and Louisiana are substituting owned drum fleets with third-party managed services bundling liner supply, logistics, and cleaning. This shift is most visible in agricultural chemical distribution, where seasonal demand volatility favors operational flexibility over fixed asset ownership.
Bag in Drum Market Segmentation
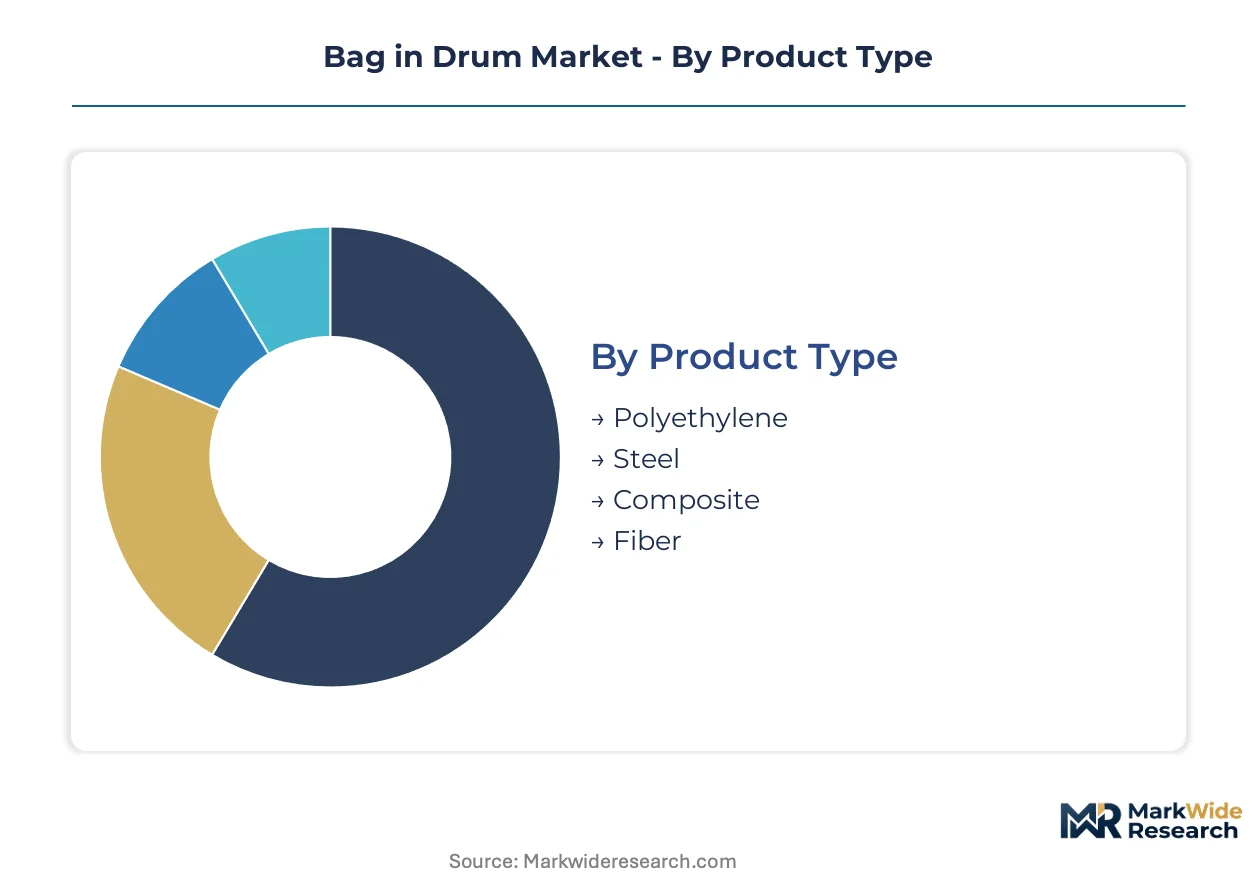
Segmentation in the bag in drum market reveals how procurement cycles, regulatory exposure, and asset utilization patterns diverge across material grades and end-use applications. Chemical processors rotate liner inventories on compressed schedules compared to food-grade operators, while pharmaceutical specifications demand the most rapid specification turnover due to sterility protocol updates.
Product Type:
Replacement velocity varies dramatically across material platforms, with commodity resins turning over fastest and engineered composites commanding extended procurement timelines due to qualification requirements.
- Polyethylene:Monolayer and multilayer polyethylene formulations dominate volume through cost efficiency and broad chemical compatibility. Demand concentrates in German industrial chemical clusters around Ludwigshafen and Leverkusen, where REACH documentation requirements accelerate replacement of non-compliant legacy liners.
- Composite:Laminated barrier constructions incorporating EVOH or aluminum oxide coatings deliver superior oxygen and moisture protection for sensitive pharmaceutical intermediates. Swiss biologics manufacturers in Basel are piloting smart barrier variants with embedded sensors, compressing qualification cycles for temperature-critical shipments.
- Steel:Rigid outer drum shells provide structural integrity for hazardous material transport under DOT regulations, with reusable fleets turning on 3-5 year depreciation schedules.
- Fiber:Fiberboard drum constructions serve cost-sensitive agricultural chemical distribution, particularly in Asian markets where seasonal demand volatility favors lightweight disposable configurations.
Polyethylene anchors the volume base while composite gains share at the steepest rate.
End User:
Margin structures diverge sharply across customer categories, with pharmaceutical applications capturing premium pricing for contamination-controlled systems and agricultural users driving commoditization at the volume tier.
- Chemicals:Specialty chemical manufacturers represent the most entrenched demand segment, with multilayer barrier systems now mandatory for REACH-compliant operations in EU industrial clusters. Mumbai and Hyderabad manufacturing hubs are expanding certified liner procurement to meet CDSCO export requirements.
- Pharmaceuticals:Sterile manufacturing protocols are displacing conventional drum cleaning with single-use liner systems, particularly for biologics cold-chain distribution. FDA food contact notification timelines for novel additive packages compress formulation launch windows.
- Food & Beverage:FDA-regulated polyethylene liner formulations serve edible oil and liquid ingredient transport, with extended producer responsibility frameworks in Europe incentivizing recyclable mono-material designs.
- Agriculture:Pesticide and fertilizer distributors favor cost-optimized polyethylene configurations, with asset-light leasing models compressing capital deployment for seasonal volume spikes.
Chemicals anchors the volume base while pharmaceuticals expands most quickly.
Distribution Channel:
Channel selection correlates directly with order scale and technical service intensity, with direct relationships dominating specification-heavy pharmaceutical procurement and distributor networks capturing fragmented agricultural demand.
- Direct Sales:Engineered composite systems for hazardous chemical and pharmaceutical applications move through manufacturer-direct relationships, bundling technical qualification support and regulatory documentation.
- Distributors:Regional packaging distributors aggregate demand from mid-volume chemical processors and food manufacturers, consolidating SKU breadth and logistics services.
- Wholesale:Agricultural chemical wholesalers in Texas and Louisiana are bundling liner supply with third-party managed drum services, substituting owned fleets with operational flexibility.
- Online Retail:Standardized polyethylene liner specifications for non-hazardous applications are migrating to digital procurement platforms, compressing transaction friction for repeat purchases.
Direct sales anchors the volume base while wholesale gains share at the steepest rate.
Capacity:
Asset utilization economics favor standardized capacities, with 200-liter configurations achieving maximum fleet interoperability and niche sizes serving specialized pharmaceutical and bulk chemical handling.
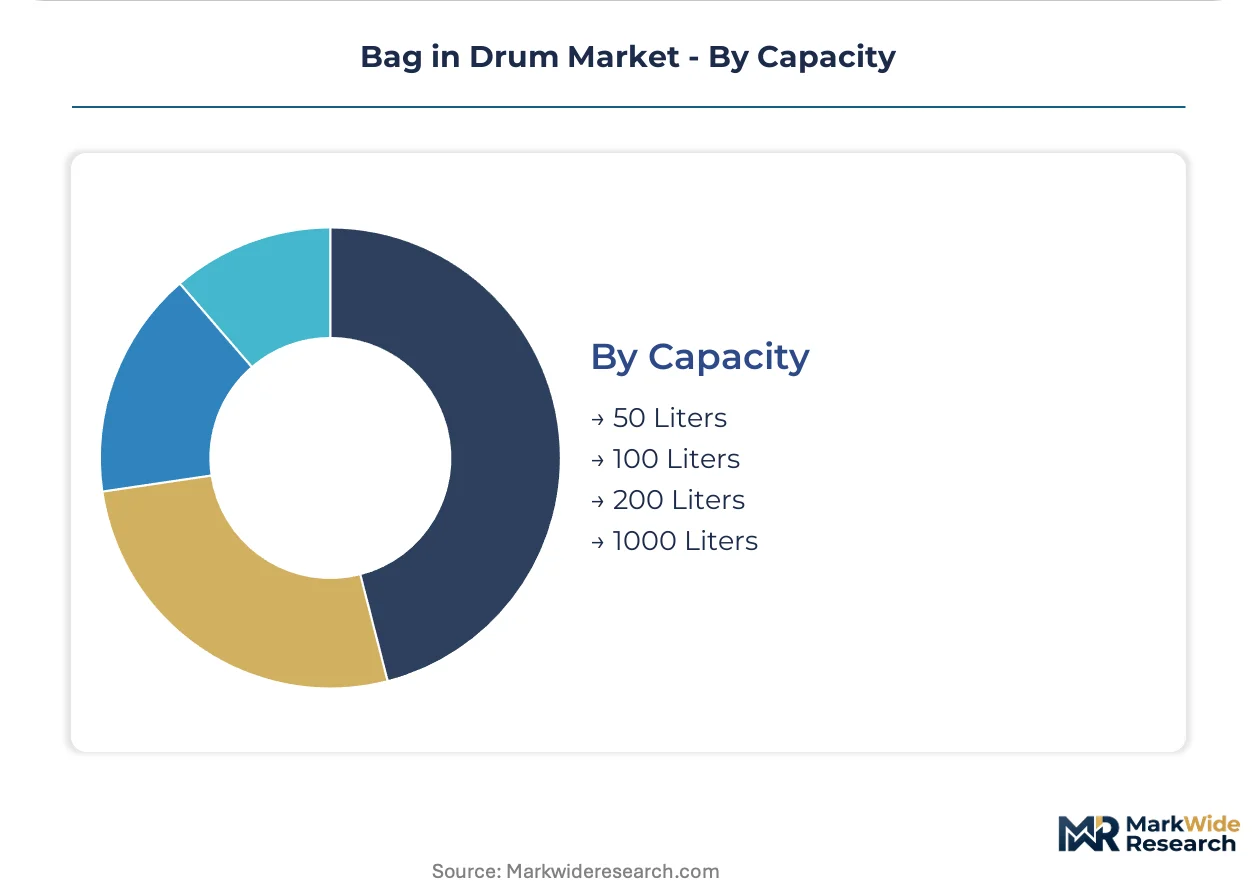
- 200 Liters:The dominant intermediate bulk format achieves optimal handling efficiency across chemical, food, and pharmaceutical logistics networks. Legacy steel and fiber drum dimension variations across regional standards complicate universal liner fitment.
- 1000 Liters:Large-capacity systems serve bulk chemical transfer and agricultural formulation operations, with specialized barrier requirements for oxygen-sensitive storage.
- 100 Liters:Mid-size configurations address pharmaceutical intermediate handling and specialty chemical sampling, with reduced residual volume requirements.
- 50 Liters:Compact formats serve laboratory-scale pharmaceutical production and high-value chemical sampling, with premium barrier specifications justified by cargo value density.
200-liter anchors the volume base while 1000-liter gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions and EU Packaging and Packaging Waste Directive amendments are accelerating certified liner replacement cycles across European chemical clusters, while DOT hazardous material regulations sustain North American demand for engineered barrier systems.
Germany
Industrial chemical processors around Ludwigshafen and Leverkusen anchor European demand for multilayer barrier bag systems. ECHA enforcement of restricted substance documentation mandates replacement of non-compliant legacy liners by 2027. BASF's Ludwigshafen Verbund site is expanding certified liner procurement to maintain REACH-compliant supply chains for specialty chemical exports.
United States
Specialty chemical manufacturers in Texas and Louisiana are substituting owned drum fleets with third-party managed services bundling liner supply and logistics. EPA hazardous waste container regulations structurally entrench demand for DOT-certified barrier configurations. Houston's petrochemical corridor is piloting RFID-enabled track-and-trace systems for temperature-sensitive pharmaceutical intermediates.
India
Pharmaceutical exporters in Mumbai and Hyderabad manufacturing clusters are expanding certified liner procurement to meet CDSCO and DGFT compliance requirements. The country's national pharmaceutical regulator mandates sterility documentation for active pharmaceutical ingredient shipments. Gujarat's specialty chemical belt is attracting barrier film converter investments to serve regional agrochemical formulation demand.
Switzerland
Biologics manufacturers in Basel are piloting smart barrier films with embedded temperature sensors for cold-chain drum shipments. Swissmedic sterility protocols are displacing conventional drum cleaning with single-use liner systems. The country's pharmaceutical cluster is compressing qualification cycles for temperature-critical cargo through digitized quality assurance documentation.
Japan
EVOH and aluminum oxide coating capacity concentrates in Japanese technical centers, creating supply concentration for European and North American converters. METI industrial standards govern barrier film performance specifications for oxygen-sensitive chemical storage. Osaka-based coating equipment suppliers report extended order backlogs from European converter investments responding to EU F-Gas Regulation phase-down schedules.
Bag in Drum Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with drum manufacturing and liner supply capabilities, specialized barrier film converters serving pharmaceutical qualification requirements, and regional polyethylene formulators competing on cost-optimized agricultural applications. Dominant competitive moves include capacity expansion in multilayer coextrusion lines and strategic partnerships bundling liner supply with third-party managed drum services.
Within the integrated packaging tier, Greif Inc. and SCHÜTZ GmbH occupy positions spanning drum manufacturing and engineered liner systems. Greif leverages its North American manufacturing footprint to sustain long-term supply relationships with chemical processors, while SCHÜTZ anchors European demand through specialized composite drum configurations. Time Technoplast represents the cost-optimized formulation archetype, serving agricultural and food-grade applications across Asian markets through polyethylene bag systems.
| Leading Market Players |
|---|
| Greif Inc. |
| Mauser Group |
| SCHÜTZ GmbH |
| Time Technoplast |
| Orlando Drum & Container Corporation |
| Enviro-Pak |
| C.L. Smith |
| Muller Group |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's container handling costs cascade through European barrier film supply chains, compressing margins for converters serving Ludwigshafen chemical clusters while amplifying price differentiation between REACH-certified and standard-grade liner systems. This logistics chokepoint concentrates pricing power among Japanese and South Korean coating equipment suppliers, forcing drum liner manufacturers to absorb tariff exposure or pass through elevated EVOH resin costs to pharmaceutical end users.
Pricing Analysis
Certification level (REACH/FDA-grade) creates the primary spread between commodity polyethylene liners and premium composite systems. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance tiers, with pharmaceutical qualification documentation commanding substantial premiums over agricultural-grade formulations. Cost compression in standard polyethylene tiers is intensifying because of naphtha cracking margin volatility, while agricultural distributors exhibit highest price sensitivity and biologics manufacturers show lowest elasticity due to sterility protocol mandates.
Supply Chain Analysis
Tariff exposure between Japan and Germany dominates supply chain risk planning for European barrier film converters. EVOH resin production concentrates in Japan, South Korea, and the United States, with aluminum oxide coating capacity similarly clustered in East Asian technical centers. Raw material dependencies rest on ethylene feedstock from naphtha cracking, specialized polymer additives for REACH compliance, and precision coating equipment from Osaka-based suppliers. Distribution runs through manufacturer-direct relationships for pharmaceutical applications and regional packaging distributors for agricultural chemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bag in drum market is entering a cyclical recovery phase as REACH compliance deadlines force replacement of non-compliant legacy liner inventories across European chemical clusters. This regulatory-driven refresh cycle compresses procurement timelines and expands addressable demand for certified barrier systems.
For Market Incumbents: Pre-empt margin erosion in commodity polyethylene tiers by securing backward integration into multilayer coextrusion capacity in Germany or India. Lock in long-term supply contracts with BASF's Ludwigshafen Verbund and other anchored chemical processors before CDSCO certification requirements expand procurement pools in Mumbai and Hyderabad. Defensive patent positioning around smart barrier film sensor integration will block emerging electronics-converter partnerships.
For New Entrants and Emerging Players: Build out barrier film converter capacity in Gujarat's specialty chemical belt to serve underpenetrated agrochemical formulation demand with cost-optimized REACH-compliant formulations. Target Indian pharmaceutical exporters facing CDSCO documentation mandates with bundled liner-logistics services. Go-to-market leverage comes from partnering with agricultural chemical wholesalers in Texas and Louisiana already shifting to asset-light drum fleet models.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated packaging conglomerates seeking to divest non-core liner operations amid portfolio rationalization pressures. Five-to-ten year viability hinges on exposure to pharmaceutical cold-chain expansion versus agricultural commodity cyclicality. Watch for inflection when EU F-Gas Regulation phase-down schedules accelerate silicon oxide coating equipment order backlogs beyond eighteen-month delivery windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multilayer Coextrusion | Captures margin pool from Japanese EVOH resin suppliers serving REACH-compliant European demand. |
| Smart Barrier Film Sensor Integration | Digitizes cold-chain quality assurance for Basel biologics manufacturers compressing insurance exposure. |
| Asset-Light Drum Fleet Services | Bundles liner supply with logistics for Texas agricultural chemical distributors seeking operational flexibility. |
| REACH-Certified Converter Capacity in India | Positions to serve CDSCO-mandated pharmaceutical exports from Mumbai and Hyderabad manufacturing clusters. |
| Non-Fluorinated Barrier Coating Transition | Aligns with EU F-Gas Regulation timelines forcing Ludwigshafen formulators toward silicon oxide deposition. |
Study Parameters
Cross-validation between primary interviews with drum fleet managers, pharmaceutical packaging engineers, and chemical procurement leads anchors the qualitative findings against secondary sources including ECHA substance restriction databases, customs trade flows for polyethylene resin, and SEC filings from integrated packaging conglomerates. Bottom-up triangulation against top-down market sizing ensures segment-level consistency across material grades and end-use applications.
Calibration against historical replacement cycles for drum liner inventories and observed qualification timelines for pharmaceutical barrier systems shapes the analytical framework. Segmentation dimensions span material platform, end-use industry, distribution channel, and regional regulatory cluster, with CAGRs derived from elasticity modeling against chemical production indices and pharmaceutical export growth patterns. Forecast inputs incorporate EVOH resin price volatility indices and coating equipment order backlogs from Japanese suppliers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese polyethylene formulators or accelerated smart barrier film adoption by Swiss biologics manufacturers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Piping Bags Market