
 Glandular Ingredients Market | 2026-2036
Glandular Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Glandular Ingredients Market Foresight
Plant-derived enzyme concentrates are displacing traditional porcine-sourced glandular matrices in cost-sensitive formulations, which is realigning raw material procurement economics across the value chain. American Laboratories, Inc. leverages captive rendering partnerships to secure consistent bovine liver feedstock. Standard Process sustains vertically integrated manufacturing from organic livestock operations through finished capsule production. NOW Foods competes on volume scale, occupying mass-market shelf space with multi-glandular complexes.
Glandular ingredients comprise desiccated, defatted, and lyophilized tissue extracts sourced from bovine, porcine, or ovine organs, standardized to specified protein content and hormone residue thresholds for therapeutic or nutritional use. These materials function as tissue-specific biologics in oral dosage forms, supplying nucleotides, peptides, and organ-specific cofactors that support targeted physiological functions. Thyroid extract and liver concentrate lead product type revenue pools, with the former commanding premium positioning due to stringent potency verification requirements. Powder and capsule forms dominate formulation demand, while dietary supplements anchor application volume as functional foods remain constrained by taste-masking limitations and regulatory novelty status.
FDA cGMP rules and USDA biologics oversight govern domestic manufacturing, with EFSA novel food assessments creating divergent market access conditions across the Atlantic. Compliance with hormone residue limits and species-of-origin documentation shapes supplier qualification timelines and contract structuring. Stakeholders must monitor evolving tissue-sourcing traceability mandates and alternative protein authentication technologies to defend supply chain integrity.
Market Dynamics
EFSA novel food assessments are compressing supplier qualification timelines and forcing raw material sourcing consolidation toward vertically integrated renderers with captive traceability systems.
Growth Catalysts
- Thyroid extract demand:Nutraceutical distributors in Germany are expanding procurement volumes as EFSA tightens purity benchmarks for hormone residue thresholds.
- cGMP enforcement:FDA cGMP rules are driving supplier consolidation in North American dietary supplement channels toward certified raw material sources.
- Plant-derived alternatives:Enzyme concentrate technology is creating new formulation options for cost-sensitive supplement manufacturers seeking porcine-free matrices.
Market Restraints
- Species-of-origin documentation:USDA biologics oversight mandates create compliance friction and extend contract structuring timelines for cross-border tissue shipments.
- Hormone residue verification:Potency testing requirements for thyroid extracts impose laboratory cost burdens that disadvantage smaller raw material suppliers.
- Rendering feedstock concentration:Bovine liver supply depends on regional meatpacking density, creating geographic sourcing vulnerability in areas with declining cattle processing.
Strategic Opportunities
- Organic livestock integration:Vertically controlled operations from pasture to capsule production bypass conventional rendering intermediaries and command premium positioning.
- Functional food expansion:Taste-masking technology advances could unlock beverage and bar applications currently constrained by organoleptic limitations of desiccated powders.
- Traceability authentication:Blockchain and isotope verification systems are opening export pathways to markets with strict species-origin requirements.
Industry Challenges
- Laboratory capacity constraints:Qualified analytical chemists for hormone residue quantification are scarce, creating bottlenecks in batch release timelines.
- Lyophilization equipment access:Capital-intensive freeze-drying infrastructure limits scale-up capacity for entrants seeking defatted tissue processing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glandular Ingredients Market |
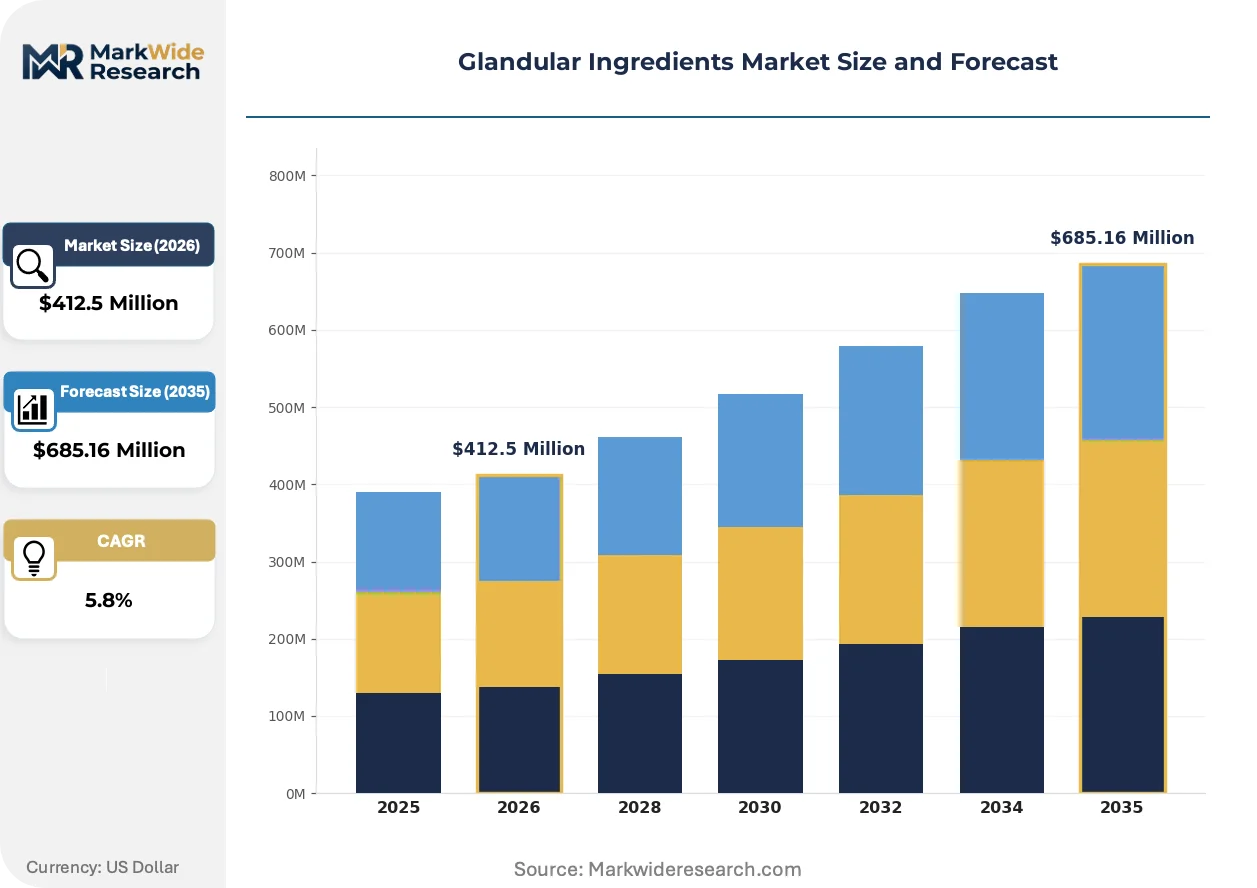
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thyroid Extract, Prostate Powder, Liver Concentrate, Pancreas Extract, Spleen Powder Form: Powder, Capsule, Tablet, Liquid Extract, Granules Application: Dietary Supplements, Functional Foods, Cosmetics, Animal Nutrition, Pharmaceuticals End User: Supplement Manufacturers, Cosmetic Companies, Veterinary Firms, Pharmaceutical Producers, Nutraceutical Distributors |
| Companies Covered | Laboratorio Opoterapico Argentino S.A., Agri-lab Co-Products Ltd., American Laboratories, Inc., American Biologics, Standard Process, Biotics Research, Pure Encapsulations, NOW Foods, Thorne Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glandular Ingredients Market Shifts & Advancements
Biotechnology and regulatory science are converging to transform how glandular materials are sourced, verified, and formulated across nutraceutical and therapeutic channels.
Lyophilization protocols with real-time moisture monitoring are overtaking conventional vacuum-drying methods for thyroid and adrenal extracts. Specialized contract manufacturers serving premium supplement brands are adopting these systems to reduce protein denaturation and extend shelf stability. The shift is compressing batch rejection rates and enabling tighter potency specifications that conventional drying cannot achieve.
EFSA novel food assessments are recategorizing historical tissue extracts as regulated biologics rather than grandfathered ingredients. This reclassification forces European distributors to submit comprehensive safety dossiers including hormone residue toxicology data. German and Swiss nutraceutical importers are responding by consolidating procurement through EFSA-prequalified rendering partnerships with existing novel food approvals.
Direct-to-manufacturer sourcing contracts are replacing traditional ingredient distributor intermediaries for large-scale supplement producers. Mass-market brands with predictable volume requirements are negotiating multi-year supply agreements with captive rendering operations. This pattern is most visible in North American dietary supplement channels where FDA cGMP audit requirements favor documented, long-term supplier relationships over spot-market purchasing.
Glandular Ingredients Market Segmentation
Segmentation in glandular ingredients separates commodity tissue powders from premium standardized extracts. Each dimension carries distinct margin profiles and regulatory burdens that reshape procurement strategies.
Product Type:
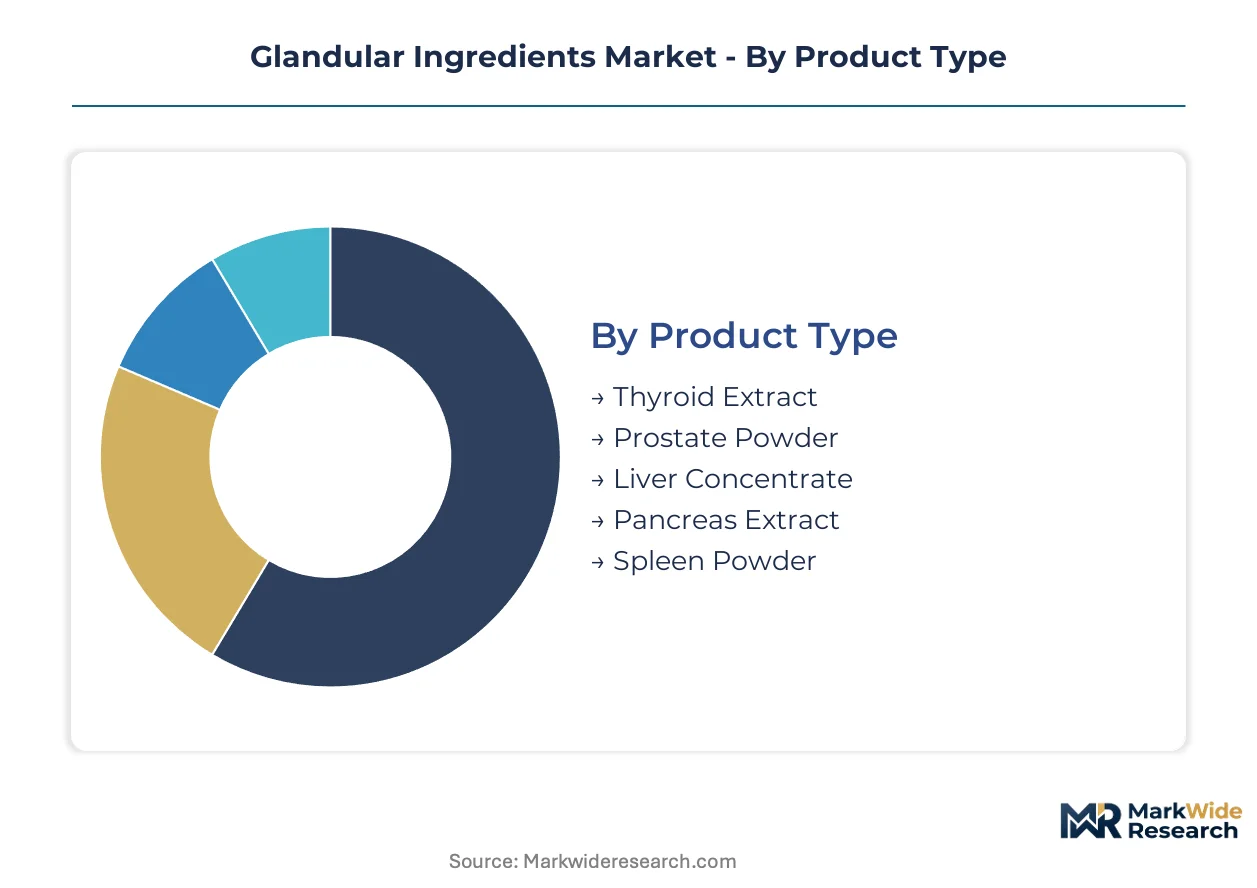
Volume concentrates in liver concentrates while thyroid extracts command premium positioning through potency verification requirements.
- Thyroid Extract:Lyophilized tissue standardized to hormone residue thresholds, requiring laboratory verification for triiodothyronine and thyroxine content. German nutraceutical distributors are expanding procurement volumes as EFSA tightens purity benchmarks for hormone residue thresholds.
- Liver Concentrate:Defatted bovine tissue rich in heme iron and B-vitamin cofactors, produced through vacuum-drying or lyophilization. North American dietary supplement channels absorb the largest volumes as FDA cGMP enforcement drives supplier consolidation toward certified raw material sources.
- Prostate Powder:Desiccated tissue matrix targeting men's health formulations with lipid-soluble compound retention.
- Pancreas Extract:Enzyme-active tissue preparation containing amylase, lipase, and protease fractions for digestive support applications.
- Spleen Powder:Niche organ tissue with immunoglobulin content, sourced primarily from ovine and bovine origins.
Today's leader: Liver Concentrate. Tomorrow's challenger: Thyroid Extract.
Form:
Cost tier separation runs from commodity powders to precision-dosed capsules with stability-enhancing excipients.
- Powder:Bulk desiccated tissue with specified protein content, serving as the foundational input for further processing or direct formulation in functional foods.
- Capsule:Encapsulated powder or granule forms with moisture-barrier packaging, dominating premium supplement positioning due to dosing precision and taste masking.
- Tablet:Compressed matrix with binders and disintegrants, competing on manufacturing throughput for mass-market brands.
- Liquid Extract:Hydroalcoholic or glycerite preparations with faster absorption profiles, constrained by shorter shelf stability and shipping weight.
- Granules:Intermediate particle size for sachet or stick-pack applications, bridging powder handling efficiency with finished dose convenience.
Volume anchor: Powder. Margin expansion path: Capsule.
Application:
Customer type stratification separates established supplement channels from emerging functional food experiments.
- Dietary Supplements:Capsule and tablet formulations targeting specific physiological support claims, absorbing the majority of glandular ingredient throughput.
- Functional Foods:Beverage, bar, and fortified food applications currently constrained by taste-masking limitations and regulatory novelty status.
- Cosmetics:Topical formulations leveraging tissue-derived peptides, a marginal channel with growth contingent on cosmeceutical regulatory clarity.
- Animal Nutrition:Pet supplement and veterinary applications with lower purity thresholds and reduced documentation requirements.
- Pharmaceuticals:Prescription thyroid preparations and organotherapy products governed by drug-level cGMP and biologics oversight.
Established base: Dietary Supplements. Regulatory unlock needed: Functional Foods.
End User:
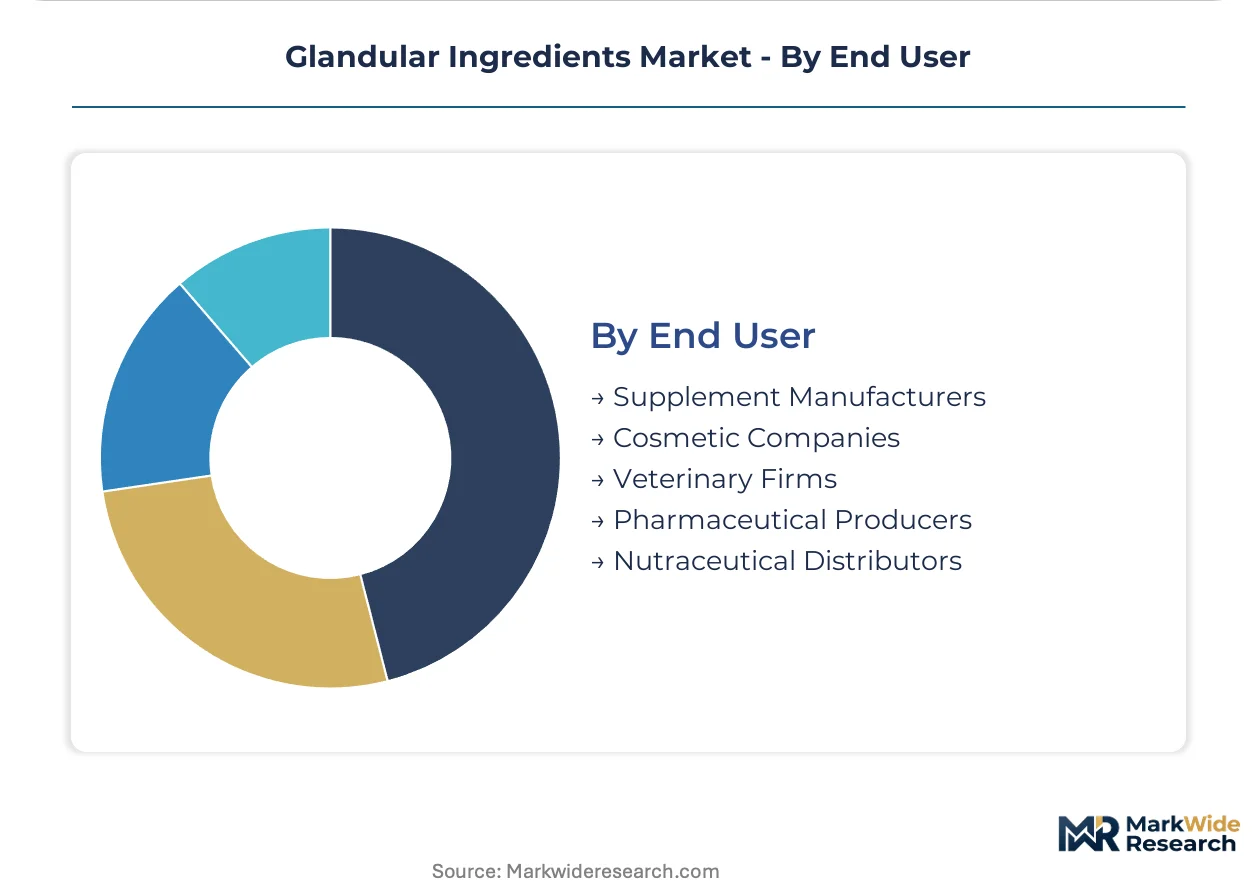
Supply concentration favors large-scale supplement manufacturers with multi-year sourcing contracts over fragmented distributor intermediaries.
- Supplement Manufacturers:Direct-to-manufacturer procurement patterns dominate, with mass-market brands negotiating captive rendering agreements to satisfy FDA cGMP audit requirements.
- Nutraceutical Distributors:Consolidating procurement through EFSA-prequalified rendering partnerships to navigate novel food assessment timelines.
- Cosmetic Companies:Small-volume buyers with peptide-specific sourcing needs and cosmetic ingredient safety dossier obligations.
- Veterinary Firms:Animal nutrition specialists with species-appropriate tissue sourcing and reduced regulatory documentation burdens.
- Pharmaceutical Producers:Drug manufacturers requiring USP-grade materials with complete chain-of-custody documentation and validated analytical methods.
Procurement power center: Supplement Manufacturers. Qualification bottleneck: Nutraceutical Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nebraska's rendering corridor anchors glandular ingredient production through dense cattle processing infrastructure and captive bovine liver feedstock access.
United States
FDA cGMP enforcement drives supplement manufacturers toward certified rendering partnerships with documented chain-of-custody systems. USDA biologics oversight mandates hormone residue testing protocols that extend supplier qualification timelines. Omaha and Grand Island processing clusters concentrate bovine liver drying capacity serving North American capsule manufacturers.
Germany
EFSA novel food assessments compress procurement timelines for thyroid extracts as distributors consolidate through prequalified rendering channels. German nutraceutical importers face expanded safety dossier requirements including hormone residue toxicology data. Hamburg and Frankfurt distribution hubs channel EFSA-compliant glandular materials into European supplement formulation networks.
Switzerland
Swissmedic pharmaceutical-grade standards attract premium thyroid extract demand from prescription compounders seeking validated analytical methods. The country's biologics oversight framework exceeds EFSA baseline requirements for tissue-sourced therapeutics. Basel and Zurich manufacturing clusters specialize in lyophilized glandular preparations for continental European export.
Canada
Health Canada and PMRA joint oversight creates dual-track regulatory pathways for glandular ingredients crossing pharmaceutical and natural health product categories. Prairie province cattle rendering supplies defatted liver concentrates to domestic supplement manufacturers. Alberta and Manitoba processing facilities leverage integrated meatpacking infrastructure for consistent raw material sourcing.
Australia
TGA biologics regulations govern ovine-sourced glandular imports with strict species-of-origin documentation requirements for cross-border tissue shipments. Melbourne and Sydney nutraceutical distributors navigate extended approval timelines for novel tissue extracts. Domestic sheep processing infrastructure supports niche spleen powder production for immunoglobulin-focused formulations.
Glandular Ingredients Market Competitive Landscape
Global majors compete with regional champions across rendering partnerships and certification depth, producing a tiered structure where scale-driven volume players coexist with vertically integrated premium specialists. Market concentration favors established operators with captive feedstock agreements and validated laboratory infrastructure. Three archetypes dominate: rendering-integrated manufacturers controlling upstream supply, contract research organizations specializing in hormone residue analytics, and mass-market brands competing on multi-glandular complex scale. Consolidation proceeds through multi-year supply agreements and backward integration into certified rendering operations.
Among rendering-integrated manufacturers, American Laboratories, Inc. and Standard Process exemplify divergent scale positions within the captive supply archetype, while NOW Foods occupies a position on the volume-driven end of the spectrum. These three entities represent the competitive bandwidth spanning premium organic integration through mass-market shelf presence.
| Leading Market Players |
|---|
| Laboratorio Opoterapico Argentino S.A. |
| Agri-lab Co-Products Ltd. |
| American Laboratories, Inc. |
| American Biologics |
| Standard Process |
| Biotics Research |
| Pure Encapsulations |
| NOW Foods |
| Thorne Research |
| Others |
Supply & Pricing Matrix
Lyophilization energy costs cascade through thyroid extract premiums, compressing margins for freeze-drying operators while rewarding vacuum-drying specialists serving liver concentrate commoditization. German nutraceutical distributors absorb EFSA novel food assessment fees into landed costs, widening spreads between EFSA-prequalified and uncertified raw material channels.
Pricing Analysis
Input-cost pass-through from bovine liver rendering runs through three-tier pricing structure across premium, standard, and economy levels. Certification grade under EFSA novel food status and volume scale drive price differentiation, with organic livestock integration commanding substantial premiums over conventional rendering. Pricing pressure stems from laboratory capacity constraints for hormone residue quantification, extending batch release timelines and inflating analytical cost burdens. Mass-market supplement manufacturers exhibit highest price sensitivity, while Swiss prescription compounders show lowest sensitivity due to validated analytical method requirements.
Supply Chain Analysis
Workforce availability for qualified analytical chemists concentrates in Nebraska's rendering corridor and Switzerland's Basel manufacturing cluster, creating geographic bottlenecks in hormone residue verification. Bovine liver feedstock draws from US prairie province rendering and German meatpacking density, with ovine spleen powder sourcing anchored in Australian sheep processing infrastructure. Single-source vulnerability manifests in lyophilization equipment access, where capital-intensive freeze-drying infrastructure limits scale-up capacity. Distribution runs through direct-to-manufacturer contracts replacing traditional ingredient distributor intermediaries for large-scale supplement producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glandular ingredients market functions as a regulatory compounder, with FDA cGMP enforcement and EFSA novel food assessments sequentially tightening compliance thresholds that filter supplier viability and concentrate procurement power.
For Market Incumbents: Hedge against plant-derived enzyme concentrate displacement by securing captive organic livestock operations and validated lyophilization partnerships. American Laboratories, Inc. and Standard Process demonstrate defensive positioning through backward integration into certified rendering with documented chain-of-custody systems. Prioritize laboratory infrastructure investment to bypass analytical chemist scarcity bottlenecks in batch release timelines. For New Entrants and Emerging Players: Veterinary firms and animal nutrition specialists represent underserved buyer archetypes with reduced documentation requirements and lower purity thresholds. Functional food applications present white-space expansion paths contingent on taste-masking technology advances unlocking beverage and bar formats. Pursue blockchain traceability authentication as go-to-market differentiation for export markets with strict species-origin mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA novel food assessments compress supplier qualification timelines and extend contract structuring friction. Long-term viability favors vertically integrated operators with captive feedstock agreements spanning organic livestock through finished capsule production. Watch laboratory capacity expansion rates as inflection indicator for batch release bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Prequalification | Secures European market access ahead of tightened purity benchmark enforcement. |
| Captive Organic Livestock Integration | Eliminates rendering intermediary dependence and commands premium positioning. |
| Lyophilization Equipment Investment | Enables protein stability specifications that vacuum-drying competitors cannot match. |
| Blockchain Traceability Implementation | Unlocks export pathways to markets with strict species-of-origin documentation. |
| Direct-to-Manufacturer Contracting | Bypasses distributor intermediaries and satisfies FDA cGMP audit requirements. |
Research Methodology
Direct dialogue with rendering facility operations managers, nutraceutical procurement directors, EFSA regulatory consultants, and veterinary formulation specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA cGMP inspection records, EFSA novel food approval databases, USDA biologics oversight guidance, and customs trade data for cross-border tissue shipments. Bottom-up volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Bottom-up segmentation analysis modeled thyroid extract, liver concentrate, and specialty organ powders by form, application, and end-user archetype. Top-down macro validation referenced dietary supplement channel growth trajectories and rendering industry capacity utilization. CAGRs derived from regression analysis of historical procurement patterns and regulatory milestone timing. Forecast inputs incorporated EFSA assessment pipeline velocity and lyophilization equipment installation rates.
Underlying measurement precision varies by segment; thyroid extract potency verification carries tighter precision than commodity liver concentrate powder estimates. Forecasts reflect assumptions regarding regulatory assessment timelines and laboratory capacity expansion. Material deviation in EFSA novel food approval velocity or hormone residue testing protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
North America Food Starch Market