
 Asia-Pacific Food Additives Market | 2026-2036
Asia-Pacific Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Additives Market Analysis
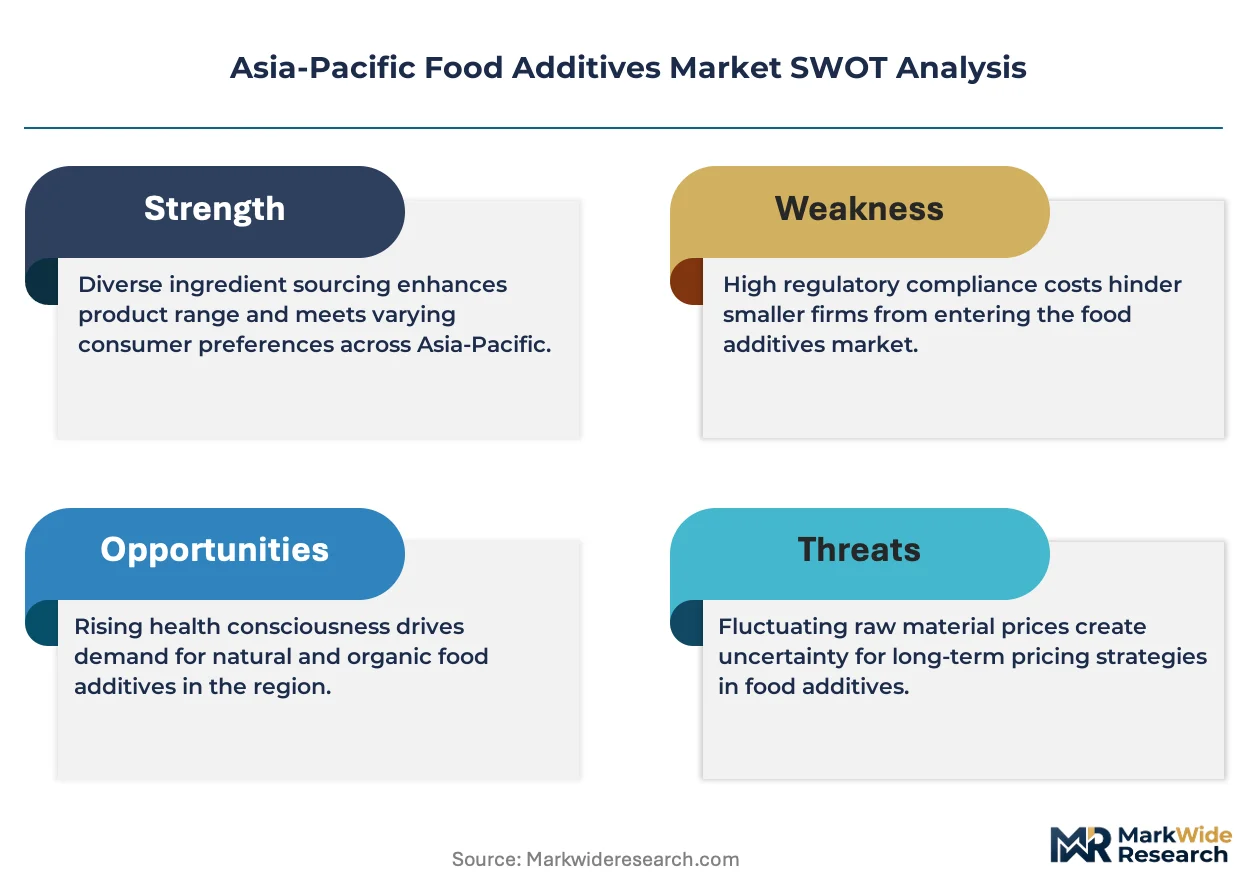
ISO 22000 certification is reorganizing competitive access across the Asia-Pacific Food Additives Market, filtering out smaller compounders lacking integrated hazard management systems. Cargill Corporation leverages its Thai corn-processing base to sustain regional sweetener supply continuity. Ajinomoto Co. Inc. anchors umami additive production through fermentation scale in Japan and China. BASF SE differentiates on synthetic colorant stability under tropical storage conditions.
Food additives comprise functional substances introduced during processing to modify sensory properties, extend stability, or enhance nutritional profiles, typically dosed at parts-per-million to single-digit percentage levels depending on regulatory maximum limits and desired effect intensity. Their primary commercial purpose centers on enabling standardized product performance across variable raw material inputs and distribution temperatures. Preservatives command mature margin pools in ambient-stable snack applications, while shelf-life extenders attract accelerated investment from dairy processors confronting cold-chain intermittency. Emulsifier demand tracks bakery sector expansion, with powder formulations dominating industrial-scale procurement for blending efficiency.
FSSAI in India, China's SAMR under GB standards, and Japan's MHLW notification system collectively determine additive approval pathways, maximum usage levels, and labeling stringency across the region. These frameworks elevate compliance costs for imported formulations while creating preference windows for locally certified production. Stakeholders must monitor harmonization pressure between ASEAN unified standards and national retention of stricter domestic limits.
Market Dynamics
Clean-label reformulation cycles are compressing additive specification timelines across the Asia-Pacific Food Additives Market, forcing compounders to pre-certify alternatives before incumbent ingredients face regulatory sunset. This velocity shift favors integrated suppliers with captive fermentation and extraction capabilities over trading-focused distributors.
Growth Catalysts
- FSSAI Labeling Tightening:India's stricter additive disclosure norms are accelerating domestic production investments as importers face extended compliance timelines and local certification preference windows.
- Cold-Chain Intermittency:Dairy processors across Vietnam and Indonesia are expanding preservative and shelf-life extender procurement to offset temperature excursion risks in last-mile distribution.
- Export-Ready Snack Lines:Contract manufacturers in China's eastern seaboard processing clusters are upgrading emulsifier specifications to meet EU and Middle Eastern import standards, pulling higher-grade additive demand.
Market Restraints
- Corn-Derivative Feedstock Volatility:Regional sweetener and polyol production faces margin compression from Thai and Indonesian corn price swings tied to climate variability.
- Fermentation Capacity Concentration:Umami additive and natural preservative supply hinges on Japanese and Chinese fermentation infrastructure, creating single-geography bottleneck exposure.
- Synthetic Colorant Substitution Pressure:Natural colorant performance gaps in tropical heat and light stability limit complete formulation pivots away from azo and triarylmethane dyes.
Strategic Opportunities
- ASEAN Harmonization Gaps:Divergence between proposed unified standards and national retention of stricter domestic limits creates compliance advisory and localized production service openings in Thailand, Vietnam, and Philippines.
- Plant-Protein Beverage Expansion:Oat, pea, and coconut milk processors require tailored emulsifier and stabilizer blends distinct from legacy dairy formulations, opening specialty compounder niches.
- Biopreservative Fermentation Scale:Nisin and natamycin production via controlled fermentation is attracting capital as chemical preservative scrutiny intensifies under Japan's MHLW notification system.
Industry Challenges
- ISO 22000 Certification Backlogs:Smaller compounders face 12-18 month integrated hazard management system implementation timelines, filtering competitive access before demand windows close.
- Reformulation Technical Debt:Accelerated clean-label cycles force simultaneous multi-additive replacement without full sensory and stability validation, elevating product failure risk in export markets.
- Specialized Fermentation Talent Scarcity:Industrial microbiology and downstream processing expertise concentrates in Japan and select Chinese biotech hubs, constraining regional capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Additives Market |
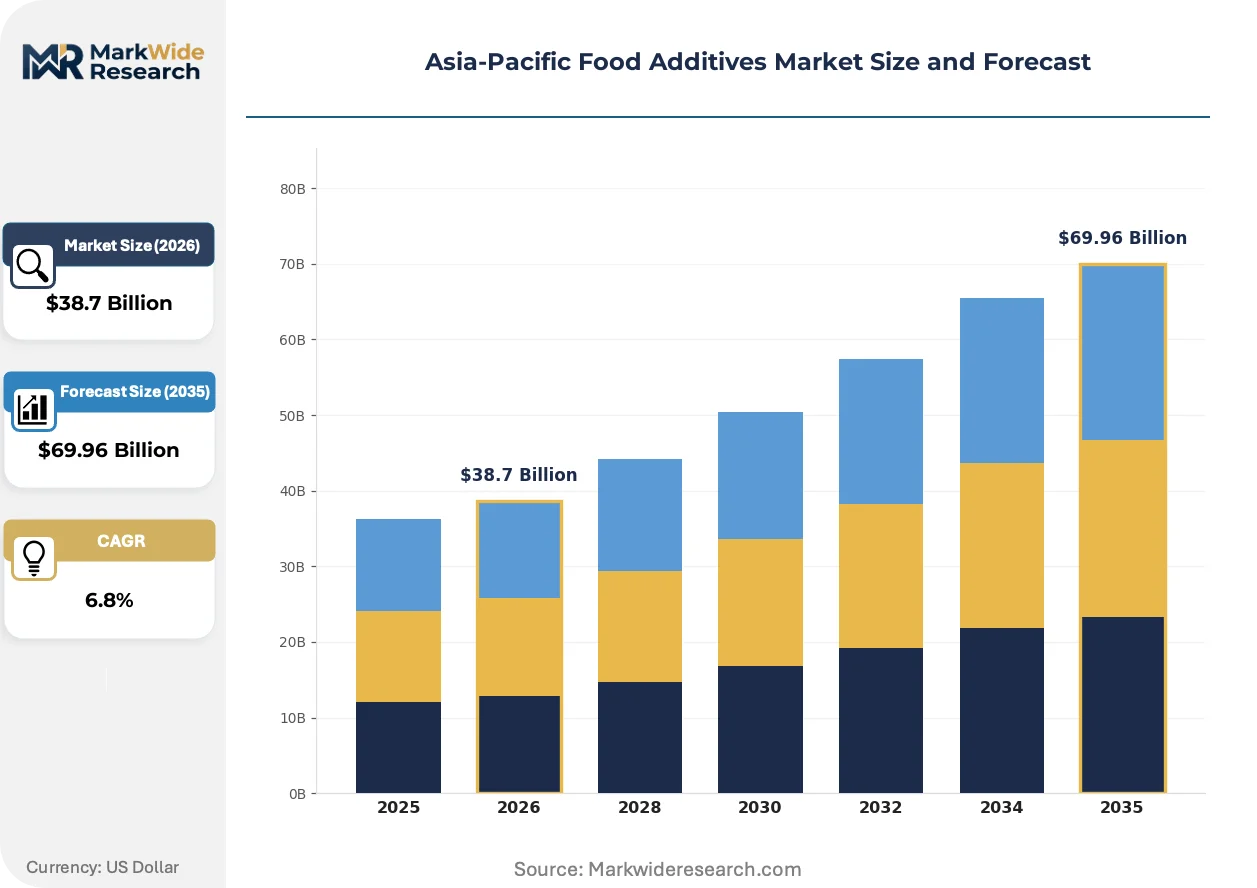
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavorings, Colorants, Preservatives, Emulsifiers End Use Industry: Bakery, Dairy, Beverages, Snacks Functionality: Texture Enhancers, Nutritional Additives, Sweeteners, Shelf-Life Extenders Form: Powder, Liquid, Granules, Paste |
| Companies Covered | Tate & Lyle PLC, Ajinomoto Co. Inc., Cargill Corporation, International Flavors & Fragrances, Inc., Ingredion, Incorporated, Archer Daniels Midland Company, BASF SE, Chr. Hansen Holding A/S, Kerry Group PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Additives Market Emerging Trajectories
Biotechnology-enabled ingredient production is compressing traditional extraction and chemical synthesis pathways across the Asia-Pacific Food Additives Market. Fermentation-derived solutions are capturing share in colorants, sweeteners, and preservatives as energy and feedstock costs pressure conventional manufacturing economics.
Enzymatic modification of plant proteins is displacing chemical hydrolysis in flavor enhancer and emulsifier precursor production. Japanese and South Korean savory processors are adopting these biocatalytic routes at pilot-to-commercial scale within 18-24 month windows. The shift is enabling cleaner-label claims while reducing solvent handling and wastewater treatment burdens that previously anchored production in industrial chemical zones.
China's SAMR is tightening GB standard enforcement on imported additive formulations, requiring pre-market substance dossiers and expanded stability documentation for tropical storage conditions. Foreign suppliers face extended registration timelines and reformulation costs to meet maximum usage level adjustments divergent from Codex Alimentarius baselines. Dairy and infant nutrition additive categories are experiencing the most intensive compliance scrutiny, with several European colorant and emulsifier ranges currently under usage-level review.
Beverage sector buyers are consolidating supplier relationships around integrated compounders offering bundled preservative-emulsifier-stabilizer systems rather than discrete ingredient procurement. Thailand's ready-to-drink tea and functional beverage manufacturers are leading this specification bundling, compressing trading-house margins while rewarding technical service capabilities. The pattern is most visible in Bangkok and Ho Chi Minh City processing corridors where contract manufacturers serve multiple brand owners under tight formulation confidentiality requirements.
Asia-Pacific Food Additives Market Segmentation
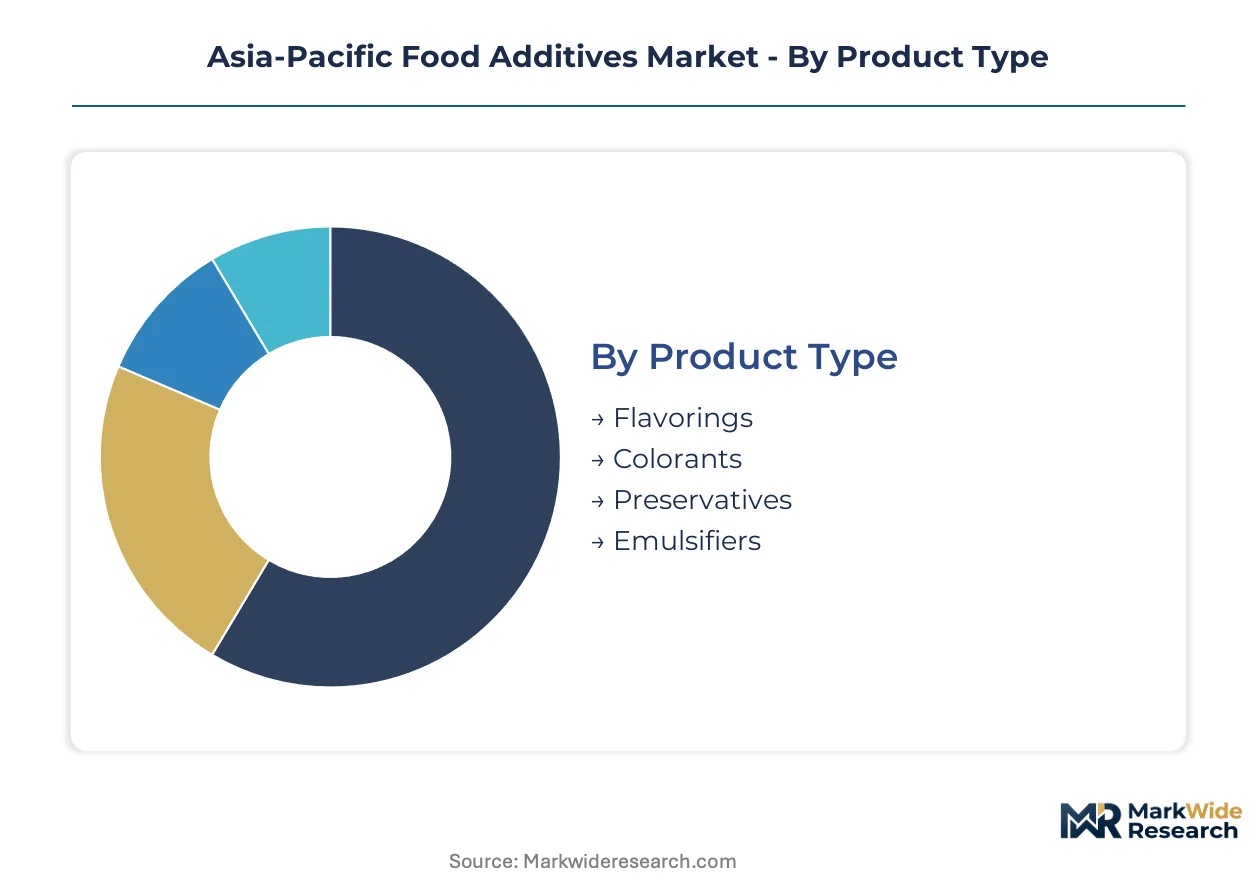
Food additive specifications in Asia-Pacific diverge sharply across national regulatory frameworks, with China's SAMR, India's FSSAI, and Japan's MHLW each imposing distinct maximum usage levels and labeling protocols. These compliance boundaries reshape procurement patterns by product type, end-use application, and physical form.
Product Type:
FSSAI tightening of additive disclosure norms in India is accelerating specification divergence across flavoring and preservative categories, while China's SAMR enforces GB standard maximum limits that vary by product class.
- Flavorings:Natural and nature-identical compounds dominate high-value applications, with fermentation-derived umami enhancers from Japanese and Chinese facilities capturing premium positioning in savory processing. Reformulation cycles in Thailand's ready-to-drink tea sector are compressing specification timelines for clean-label flavor systems.
- Preservatives:Chemical preservatives face substitution pressure under Japan's MHLW notification system, while biopreservative fermentation capacity concentrates in Japanese and select Chinese biotech hubs. Dairy processors across Vietnam and Indonesia are expanding procurement of shelf-life extenders to offset cold-chain intermittency risks.
- Colorants:Natural colorant performance gaps in tropical heat and light stability sustain partial reliance on azo and triarylmethane dyes despite clean-label trends.
- Emulsifiers:Powder formulations dominate industrial-scale procurement for blending efficiency in China's eastern seaboard processing clusters.
Established volume favors Preservatives; emerging adoption favors Flavorings.
End Use Industry:
Cost tier differentiation separates commodity additive procurement in mass-market snacks from premium-grade specifications in export-ready dairy lines.
- Dairy:Infant nutrition and ambient-stable dairy applications command the most intensive compliance scrutiny under China's SAMR, with extended registration timelines for imported emulsifier and colorant ranges. Cold-chain intermittency across Southeast Asia is pulling accelerated investment in preservative and shelf-life extender systems.
- Beverages:Contract manufacturers in Bangkok and Ho Chi Minh City corridors are consolidating supplier relationships around bundled preservative-emulsifier-stabilizer systems rather than discrete ingredient procurement. Plant-protein beverage expansion in oat, pea, and coconut milk segments requires tailored emulsifier blends distinct from legacy dairy formulations.
- Snacks:Export-ready lines in China's eastern seaboard clusters are upgrading emulsifier specifications to meet EU and Middle Eastern import standards.
- Bakery:Emulsifier demand tracks sector expansion with powder formulations preferred for industrial-scale blending efficiency.
Volume concentration sits with Dairy; reformulation velocity peaks in Beverages.
Functionality:
Supply concentration in fermentation infrastructure creates bottleneck exposure for natural shelf-life extenders and umami additives across the region.
- Shelf-Life Extenders:Nisin and natamycin production via controlled fermentation is attracting capital as chemical preservative scrutiny intensifies under Japan's MHLW notification system. Dairy processors confronting cold-chain intermittency in Vietnam and Indonesia represent the most active demand segment.
- Sweeteners:Regional production faces margin compression from Thai and Indonesian corn price swings tied to climate variability, with Cargill Corporation leveraging its Thai corn-processing base to sustain supply continuity.
- Texture Enhancers:Enzymatic modification of plant proteins is displacing chemical hydrolysis in flavor enhancer and emulsifier precursor production at pilot-to-commercial scale.
- Nutritional Additives:Fortification requirements in processed foods drive steady demand for vitamin and mineral premixes with regional compounding capabilities.
Margin stability favors Sweeteners; technology transition favors Shelf-Life Extenders.
Form:
Customer type separates industrial-scale powder procurement from specialized liquid and paste applications in artisanal and small-batch processing.
- Powder:Dominates industrial-scale procurement for blending efficiency across bakery and snack manufacturing in China's eastern seaboard processing clusters. Powder specifications align with automated dosing systems and extended ambient storage requirements.
- Liquid:Preferred in beverage applications where rapid dispersion and homogeneous mixing are critical, particularly in Thailand's ready-to-drink tea and functional beverage manufacturing.
- Granules:Intermediate form factor serving niche applications requiring controlled dissolution rates or reduced dusting in handling.
- Paste:Concentrated in artisanal and small-batch processing where precise manual dosing and specific texture incorporation are required.
Procurement scale concentrates in Powder; application flexibility favors Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI labeling tightening and China's SAMR enforcement under GB standards are redirecting procurement toward locally certified production across the Asia-Pacific Food Additives Market. These regulatory shifts elevate compliance costs for imported formulations while creating preference windows for domestic compounders.
China
Dairy processors in the Yangtze River Delta are upgrading emulsifier specifications for export-ready infant nutrition lines under intensified SAMR scrutiny. GB standard maximum usage levels for imported colorants now require expanded tropical stability documentation, extending registration timelines for European suppliers. Contract manufacturers in Shanghai and Jiangsu clusters are consolidating procurement around bundled preservative-emulsifier systems.
India
FSSAI disclosure norm tightening is accelerating domestic production investments as importers face extended compliance timelines and local certification preference windows. Dairy and snack processors in Maharashtra and Gujarat are expanding procurement of shelf-life extenders to offset cold-chain intermittency risks. Mumbai-Pune processing corridors are witnessing supplier consolidation around ISO 22000-certified compounders.
Japan
MHLW notification system intensification is driving substitution pressure on chemical preservatives toward fermentation-derived biopreservatives. Umami additive demand from Kanto-region savory processors anchors production at Ajinomoto's fermentation facilities in Kawasaki and Tokai. The Chubu industrial belt is attracting capital for nisin and natamycin scale-up as clean-label reformulation accelerates.
Vietnam
Cold-chain intermittency across the Mekong Delta and Red River Delta is pulling accelerated investment in preservative and shelf-life extender systems from dairy processors. Ho Chi Minh City contract manufacturers are consolidating supplier relationships around bundled additive systems for ready-to-drink tea and functional beverages. The country's national food safety regulator is tightening import additive documentation requirements.
Thailand
Cargill Corporation leverages its corn-processing base in Nakhon Ratchasima to sustain regional sweetener supply continuity amid feedstock price volatility. Bangkok processing corridors are leading specification bundling of preservative-emulsifier-stabilizer systems, compressing trading-house margins. The Thai Food and Drug Administration is aligning enforcement with proposed ASEAN unified standards while retaining stricter domestic limits on synthetic colorants.
Asia-Pacific Food Additives Market Vendor Landscape
Listed leaders compete with private specialists across certification and fermentation capability dimensions, creating a tiered structure where scale advantages separate from technical service proximity. The vendor base clusters around three archetypes: integrated multinational compounders with captive fermentation infrastructure, regional trading houses pivoting toward technical advisory, and specialty biotech startups scaling controlled fermentation for biopreservatives. Dominant competitive moves include ISO 22000 certification acceleration to filter market access and strategic partnerships between ingredient suppliers and contract manufacturers for bundled formulation systems.
Within the integrated multinational tier, Cargill Corporation and Ajinomoto Co. Inc. exemplify divergent geographic anchoring strategies for feedstock security and fermentation scale. Cargill's Thai corn-processing presence represents upstream control over regional sweetener supply chains, while Ajinomoto's Japanese and Chinese fermentation infrastructure anchors umami additive production capacity. BASF SE occupies a position in synthetic colorant stability differentiation under tropical storage conditions. These three companies illustrate how raw material access, fermentation expertise, and climate-adapted formulation capabilities define competitive positioning in the Asia-Pacific Food Additives Market.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Ajinomoto Co. Inc. |
| Cargill Corporation |
| International Flavors & Fragrances, Inc. |
| Ingredion, Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Chr. Hansen Holding A/S |
| Kerry Group PLC |
| Others |
Supply Flow & Price Mechanics
Ninety-day registration timelines for SAMR pre-market dossiers concentrate pricing power with ISO 22000-certified compounders possessing integrated hazard management systems, while feedstock volatility in Thai corn markets compresses margins for sweetener specialists lacking upstream control.
Pricing Analysis
Certification level creates the primary spread across the Asia-Pacific Food Additives Market, with ISO 22000-grade formulations commanding premium positioning over uncertified alternatives. Three-tier pricing structure separates FSSAI-pre-certified domestic production from import-dependent formulations facing extended compliance timelines, and from commodity-grade spot offerings in unregulated segments. Pricing pressure stems from corn-derivative feedstock volatility tied to Thai and Indonesian climate variability. Dairy processors in Vietnam and Indonesia exhibit highest price sensitivity due to cold-chain intermittency costs, while export-ready snack manufacturers in China's eastern seaboard clusters prioritize specification grade over unit economics.
Supply Chain Analysis
Malacca Strait transit underwrites regional additive distribution, with concentrated fermentation capacity in Japan's Kanto region and China's Yangtze River Delta anchoring umami additive and biopreservative supply. Thai corn-processing infrastructure and Indonesian palm-derived feedstocks constitute critical raw material inputs. Single-geography bottleneck exposure concentrates in Japanese and Chinese fermentation hubs for nisin and natamycin production. Distribution runs through Bangkok and Ho Chi Minh City processing corridors where contract manufacturers consolidate bundled procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage sector buyer consolidation around bundled preservative-emulsifier-stabilizer systems has shifted negotiating leverage toward integrated compounders, fragmenting trading-house margins across Thailand's ready-to-drink tea corridors.
For Market Incumbents: Fortify fermentation scale advantages in Kawasaki and Tokai facilities against emerging biotech startup competition in nisin and natamycin production. Prioritize ISO 22000 certification acceleration for affiliated compounders to filter competitive access before India's FSSAI preference windows close. Defend margin position through backward integration into Thai corn-processing assets mirroring Cargill's upstream control model. For New Entrants and Emerging Players: FSSAI fast-track certification for domestic Indian production represents the most penetrable entry vector as importers face extended disclosure compliance timelines. Target plant-protein beverage emulsifier blends in oat and coconut milk segments where legacy dairy formulations prove inadequate. Pursue technical advisory partnerships with Ho Chi Minh City contract manufacturers seeking bundled additive systems under confidentiality constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates divesting synthetic colorant portfolios under Japan's MHLW notification system intensification. Five-to-ten year viability favors controlled fermentation specialists with downstream processing expertise. Monitor ASEAN harmonization gap closure between proposed unified standards and national retention of stricter domestic limits as inflection indicator for localized production service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Cargill's Thai base demonstrates upstream control insulating sweetener margins from climate-driven feedstock volatility. |
| ISO 22000 Certification Acceleration | Twelve-to-eighteen month implementation timelines filter competitive access for smaller compounders lacking integrated hazard systems. |
| Biopreservative Fermentation Scale-Up | Nisin and natamycin capacity expansion in Japan's Chubu belt captures substitution demand from chemical preservative scrutiny. |
| Bundled Additive System Partnerships | Thailand's beverage manufacturers consolidate procurement around integrated compounders, compressing discrete ingredient trading margins. |
| ASEAN Harmonization Advisory Services | Divergence between unified standards and stricter national limits creates compliance consulting openings in Thailand and Vietnam. |
Methodological Framework
The analysis maps preservatives, flavorings, colorants, and emulsifiers, each validated through fermentation technologists, FSSAI compliance officers, dairy procurement leads, and contract manufacturing executives. Primary interviews with plant-protein beverage formulators and secondary validation through SAMR GB standard filings, FSSAI notification databases, ASEAN food safety harmonization documents, and customs trade records support bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, functionality, and physical form alongside regulatory compliance tier. CAGRs were derived from historical trajectory analysis and forward-looking demand elasticity assessment. Forecast inputs incorporated cold-chain intermittency indices for Southeast Asian dairy distribution and fermentation capacity utilization rates in Japanese biotech hubs.
Decision-makers should treat outputs as directional under base assumptions of sustained FSSAI enforcement intensity and SAMR GB standard stability; material deviation in regulatory timelines or ASEAN harmonization progress would warrant model refresh. Practitioners should keep alternative scenarios live as corn-derivative feedstock volatility and plant-protein beverage formulation complexity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Spain Food Enzymes Market