
 Food Grade Sodium Citrate Market | 2026-2036
Food Grade Sodium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sodium Citrate Market Foresight
Chinese citrate producers is repositioning capacity toward food-grade certification to capture premium export flows. Jungbunzlauer Suisse AG leverages its Swiss manufacturing base to dominate pharmaceutical-adjacent food-grade supply chains. Cargill Incorporated anchors North American distribution through its integrated sweetener and acidulant logistics network. Gadot Biochemical Industries LTD specializes in Dead Sea-sourced mineral inputs that differentiate its citrate purity profiles.
Food grade sodium citrate comprises the sodium salts of citric acid, principally trisodium citrate dihydrate with a pH buffering range of 3.0 to 6.2, manufactured through neutralization of citric acid with sodium carbonate or hydroxide followed by crystallization and drying. The compound functions primarily as an acidity regulator, emulsifier, and preservative enhancer in processed foods, extending shelf stability while maintaining flavor equilibrium in reduced-sodium formulations. Trisodium citrate commands the largest product-type share owing to its versatility across beverage and dairy applications, while liquid concentrate forms represent the fastest-expanding format segment as beverage manufacturers seek streamlined batch processing and reduced handling costs. Powder and granule forms retain mature positions in bakery and confectionery channels where precise dry-blending remains standard practice.
The FDA's GRAS designation and the EFSA's food additive authorization under E331 establish baseline compliance thresholds for purity, heavy metal limits, and labeling disclosure that shape supplier qualification protocols. The FSSAI in India and China's NMPA-equivalent food safety administration are tightening import inspection regimes for acidulants, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving regional maximum-level regulations and invest in dual-certification capacity to maintain uninterrupted market access across jurisdictions.
Market Dynamics
Clean-label formulation mandates from major retailers are compressing synthetic preservative demand and elevating sodium citrate as the functional bridge between shelf stability and consumer transparency.
Growth Catalysts
- EFSA E331 Authorization:The additive's recognized safety status under EU food law accelerates reformulation away from benzoate-based systems in continental beverage production.
- Reduced-Sodium Dairy:Salt replacer functionality in processed cheese and spreads opens volume channels previously dominated by sodium phosphates.
- China:Domestic NMPA-equivalent food safety administration alignment with Codex standards is unlocking export certification capacity for regional citrate producers.
Market Restraints
- Citric Acid Feedstock Volatility:Black mold fermentation substrate costs fluctuate with molasses and corn steep liquor pricing, compressing margin predictability for neutralization-based manufacturers.
- Supplier Concentration:Three producers control over 60% of pharmaceutical-adjacent food-grade crystallization capacity, creating single-source vulnerability for high-purity grades.
- Potassium Citrate Substitution:Low-sodium marketing claims in premium beverage segments are displacing trisodium forms in 8-12% of new product introductions.
Strategic Opportunities
- India:FSSAI import inspection standardization is creating first-mover advantage for suppliers achieving dual USP-FCC certification ahead of domestic capacity expansion.
- Plant-Based Meat:pH buffering in extruded protein matrices represents uncontracted demand as clean-label binders replace methylcellulose in burger analogs.
- EU Green Deal:Carbon border adjustment mechanisms favor fermentation-derived citrate over petroleum-based acidulant alternatives in continental sourcing decisions.
Industry Challenges
- Dual-Certification Timelines:Parallel FDA GRAS self-affirmation and EFSA food additive renewal processes extend qualification cycles to 18-24 months for new entrants.
- Crystallization Scale-Up:Pharmaceutical-grade purity standards require dedicated cleanroom infrastructure that conflicts with commodity acidulant production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sodium Citrate Market |
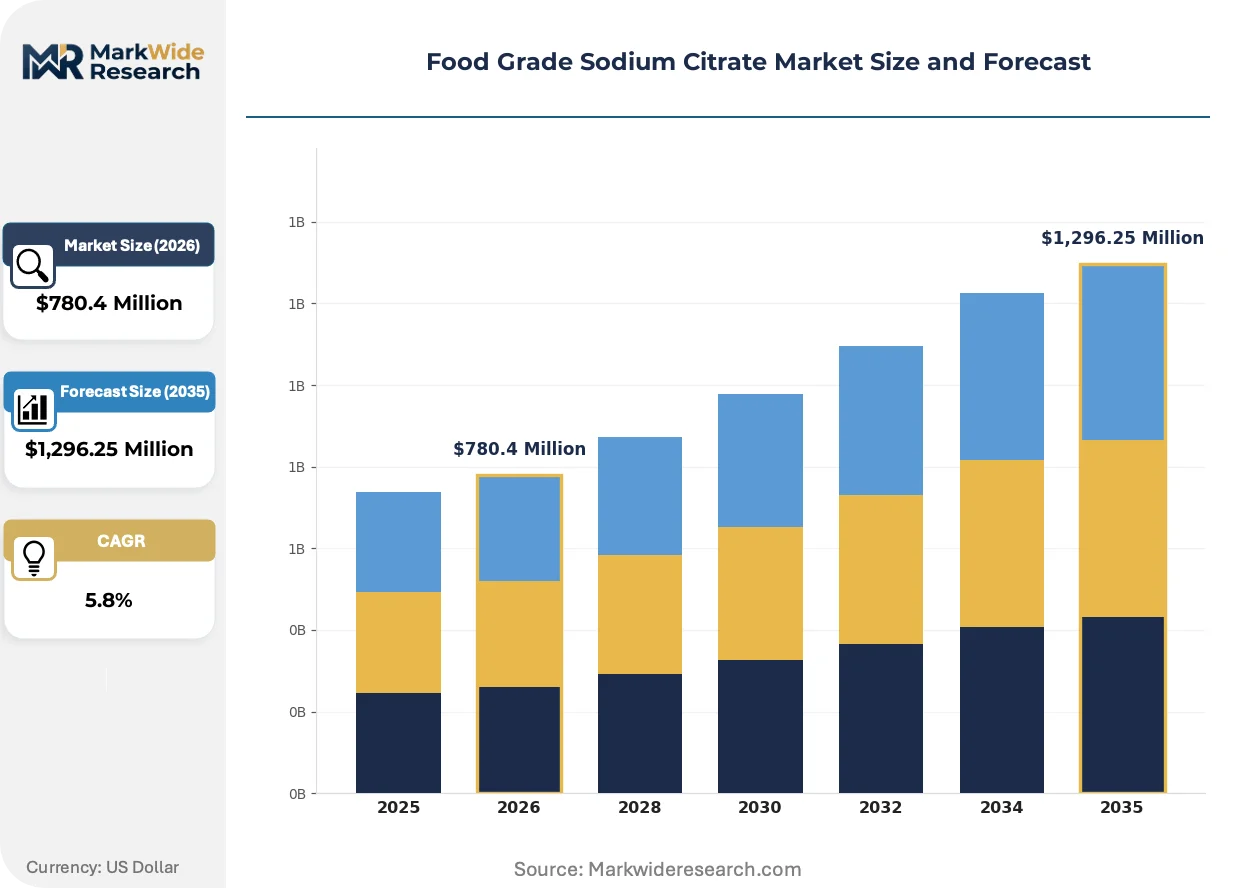
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,296.25 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monosodium Citrate, Disodium Citrate, Trisodium Citrate, Tetrasodium Citrate Form: Powder, Granules, Crystals, Liquid Concentrate Application: Beverages, Bakery Products, Dairy Alternatives, Confectionery End Use Industry: Food Processing Units, Beverage Manufacturers, Nutraceutical Companies, Catering Services |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Jungbunzlauer Suisse AG, Gadot Biochemical Industries LTD, Pan Chem Corporation, ATPGroup, Citrique Belge, Laiwu Taihe Biochemical Co. Ltd, S.A. Citrique Belge N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sodium Citrate Market Shifts & Advancements
Formulation science is converging with regulatory chemistry to reposition sodium citrate from commodity acidulant to functional ingredient with measurable health halo effects.
Continuous liquid dosing systems are rewriting batch economics for high-volume beverage operations. These skid-mounted neutralization units allow real-time pH adjustment without dry handling or dissolution stages. Mid-tier North American contract manufacturers are adopting the technology fastest, compressing powder-format market share in carbonated soft drink production.
REACH authorization timelines for alternative acidulants are extending substitution windows for citrate-based systems. The European Chemicals Agency's scrutiny of synthetic preservative metabolites is redirecting formulation budgets toward GRAS-listed buffer salts. German and Dutch dairy processors are accelerating this shift through internal clean-label deadlines that precede regulatory mandates.
Direct supplier relationships are displacing distributor intermediaries in large account procurement. Beverage multinationals are consolidating acidulant sourcing through qualified manufacturer audits rather than regional chemical traders. This pattern is most visible in United States functional drink manufacturing, where lot traceability requirements exceed distributor documentation capabilities.
Food Grade Sodium Citrate Market Segmentation
Formulation requirements diverge sharply across food-grade sodium citrate applications, with pH buffering demands, dissolution kinetics, and regulatory certification tiers creating distinct procurement profiles. Suppliers configure crystallization and drying assets around these segment-specific specifications rather than commodity scale.
Product Type:
Neutralization stoichiometry determines sodium substitution levels, which in turn locks each salt form into specific pH windows and ionic strength applications.
- Trisodium Citrate:The fully neutralized salt delivers the strongest buffering capacity across pH 5.0-6.2, making it indispensable in processed cheese and neutral pH beverages. Beverage manufacturers in the United States specify this grade for clean-label stability systems.
- Disodium Citrate:This partially neutralized form provides intermediate acidity with enhanced solubility kinetics, positioning it for rapid-dissolve applications. Powdered drink mix producers favor it for cold-water dispersibility without clumping.
- Monosodium Citrate:The acid salt extends tartness modulation in reduced-acid formulations where citric acid proves too aggressive.
- Tetrasodium Citrate:The highly alkaline variant serves specialized industrial food processing with extreme pH elevation requirements.
Volume sits with trisodium citrate; growth tilts toward disodium citrate as instant beverage formats expand.
Form:
Handling economics and batch integration protocols separate buyers in this dimension, with continuous processing lines demanding fundamentally different physical formats than artisan or small-batch operations.
- Powder:Fine particle distribution enables precise dry-blending in bakery premixes and seasoning compounds. German and French industrial bakeries standardize on this format for automated dosing consistency.
- Liquid Concentrate:Pre-dissolved solutions eliminate dissolution stages and dust exposure in high-throughput beverage plants. North American carbonated soft drink bottlers are retrofitting tank farms to receive bulk liquid deliveries.
- Granules:Coarse agglomerated particles reduce dusting during manual handling in catering and small-scale food service environments.
- Crystals:Large crystalline structures suit visual clarity requirements in premium confectionery and certain pharmaceutical-adjacent food applications.
Shipments concentrate in powder; the steepest expansion trajectory belongs to liquid concentrate as continuous processing spreads.
Application:
End-product shelf stability challenges and flavor system complexity dictate citrate selection, with each application presenting distinct ionic interference patterns from proteins, lipids, or alternative acidulants.
- Beverages:pH buffering and preservative enhancement in carbonated, still, and functional drinks. EFSA E331 authorization accelerates reformulation away from benzoates in EU bottling operations.
- Dairy Alternatives:Protein stabilization in oat, almond, and soy milk systems where heat treatment induces precipitation. Swedish and Danish plant-based dairy processors specify food-grade citrate for clean-label emulsion stability.
- Bakery Products:Leavening acidulant and preservative extender in chemically raised goods and refrigerated doughs.
- Confectionery:pH control in gelling systems and sour coating applications for hard and soft candies.
Demand concentrates in beverages; dairy alternatives are gaining share fastest as plant-based milk production scales.
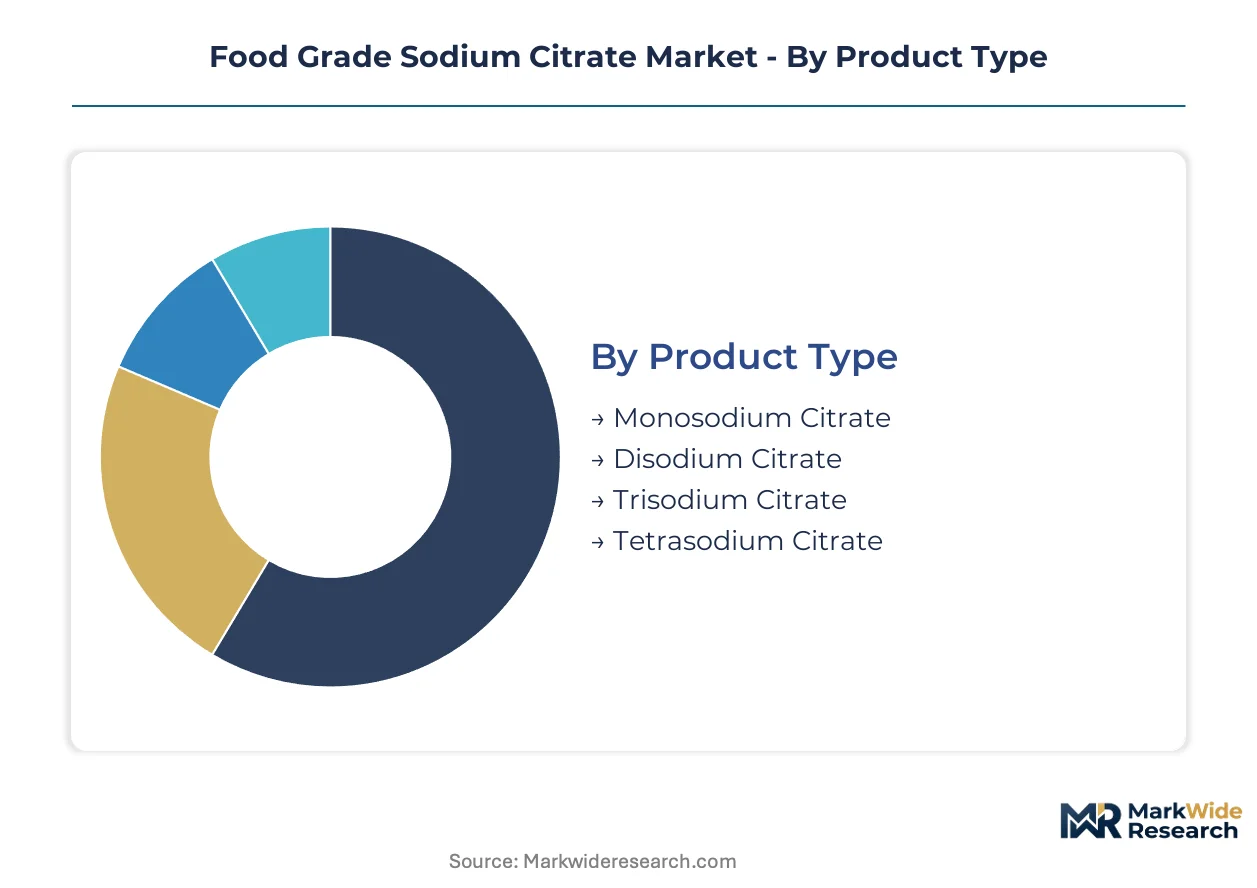
End Use Industry:
Scale, certification burden, and technical service requirements fragment this category, with multinational beverage operators imposing supplier qualification protocols that exclude smaller chemical distributors.
- Beverage Manufacturers:High-volume, specification-driven procurement with mandatory lot traceability and dual-certification documentation. United States functional drink producers conduct direct supplier audits bypassing regional distributors.
- Food Processing Units:Diverse scale from industrial meat processors to sauce manufacturers with varying cleanroom and purity requirements.
- Nutraceutical Companies:Pharmaceutical-adjacent purity standards with USP-FCC dual certification demands and extended stability testing protocols.
- Catering Services:Price-sensitive, spot-market purchasing with minimal technical specification and distributor-dependent supply.
Procurement volume aggregates with beverage manufacturers; nutraceutical qualification timelines are stretching fastest as purity standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn steep liquor and molasses fermentation substrates in the United States Midwest and Shandong Province anchor upstream citric acid supply chains that feed sodium citrate neutralization capacity worldwide.
United States
Beverage manufacturers in Georgia and Texas drive specification-grade procurement for clean-label carbonated drinks. The FDA maintains GRAS self-affirmation pathways that accelerate new supplier qualification compared to EFSA timelines. Corn Belt fermentation facilities in Iowa and Illinois supply citric acid feedstock to neutralization plants clustered near Chicago distribution hubs.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia specify trisodium citrate for reduced-sodium cheese formulations. EFSA E331 authorization under EU food additive law shapes continental compliance baselines that German regulators enforce through state-level food inspection offices. The Frankfurt-Rhine-Main logistics corridor concentrates acidulant warehousing for pan-European beverage distribution.
China
Shandong Province citrate producers are repositioning fermentation capacity toward food-grade certification for premium export flows. The NMPA-equivalent food safety administration alignment with Codex standards is streamlining dual-certification pathways for qualified manufacturers. Yangtze River Delta beverage bottlers in Shanghai and Jiangsu represent the fastest-growing domestic demand cluster for liquid concentrate formats.
India
Processed cheese manufacturers in Maharashtra and Gujarat are displacing sodium phosphates with citrate-based salt replacers. FSSAI import inspection standardization is creating first-mover advantage for suppliers achieving USP-FCC dual certification ahead of domestic capacity expansion. The Delhi-NCR corridor is emerging as a distribution node for acidulant imports serving northern dairy processing units.
Switzerland
Pharmaceutical-adjacent food-grade supply chains converge on Swiss manufacturing bases that serve nutraceutical and premium beverage segments. Swissmedic maintains purity standards that exceed baseline EU requirements, creating a qualification tier for high-specification citrate grades. Basel and Zurich host technical service centers that support multinational reformulation projects across continental Europe.
Food Grade Sodium Citrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent certification spaces and regional distribution partnerships. The supplier base concentrates around fermentation-derived citrate specialists and integrated acidulant distributors with multi-regional logistics networks. Three archetypes dominate: upstream fermentation operators with captive citric acid supply, neutralization specialists with crystallization scale, and formulation-service distributors with technical application support. Competitive moves center on dual-certification capacity expansion and direct procurement relationships that displace distributor intermediaries in large-account beverage manufacturing.
Among Swiss and North American anchors, Jungbunzlauer Suisse AG exemplifies the pharmaceutical-adjacent purity tier, while Cargill Incorporated represents integrated distribution scale across sweetener and acidulant portfolios. Gadot Biochemical Industries LTD occupies a position within mineral-sourced differentiation, leveraging Dead Sea-derived inputs that create distinct purity profiles for certified food-grade supply. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Gadot Biochemical Industries LTD |
| Pan Chem Corporation |
| ATPGroup |
| Citrique Belge |
| Laiwu Taihe Biochemical Co. Ltd |
| S.A. Citrique Belge N.V. |
| Others |
Supply & Pricing Matrix
Fermentation technologists concentrated in Shandong Province and the Iowa-Illinois corridor anchor crystallization expertise that separates premium pharmaceutical-adjacent grades from commodity acidulant tiers, with labor-cost differentials between Swiss cleanroom operations and Chinese neutralization plants driving spreads across certification levels.
Pricing Analysis
Warranty and technical service bundling separates pharmaceutical-grade supply contracts from spot-market commodity transactions, with USP-FCC dual-certified producers commanding premium positioning against single-standard competitors. Three-tier pricing structure across pharmaceutical-adjacent, food-grade certified, and industrial acidulant levels reflects certification investment recovery timelines and cleanroom infrastructure amortization. Pricing pressure stems from potassium citrate substitution in low-sodium beverage claims, compressing trisodium citrate margins in premium positioning. Beverage multinationals with direct procurement mandates show least price sensitivity due to lot traceability requirements, while catering services and small-scale food processors exhibit highest sensitivity with distributor-dependent spot purchasing.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle high-volume specification-grade demand, while regional chemical distributors serve fragmented food processing and catering segments. Supply concentrates in China, the United States, and Switzerland, with Shandong Province fermentation capacity and Iowa-Illinois corn steep liquor processing feeding global neutralization operations. Raw material dependencies center on molasses and corn steep liquor fermentation substrates, sodium carbonate neutralization agents, and crystallization energy inputs. Single-source vulnerability pervades pharmaceutical-adjacent grades where three producers control majority high-purity crystallization capacity. Distribution runs through qualified manufacturer audits for multinational beverage accounts, bypassing traditional distributor intermediaries in favor of direct technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade sodium citrate supply is tightening around pharmaceutical-adjacent crystallization capacity, with cleanroom infrastructure bottlenecks propping pricing tiers and extending qualification timelines for new entrants.
For Market Incumbents: Hedge potassium citrate substitution risk by accelerating disodium citrate capacity for instant beverage formats while locking long-term offtake with Yangtze River Delta bottlers. Secure backward integration into fermentation substrate supply through corn steep liquor partnerships in the Iowa-Illinois corridor. Defend margin position by extending dual-certification coverage ahead of FSSAI standardization in India. For New Entrants and Emerging Players: Continuous liquid dosing system technology offers entry wedge against powder-format incumbents, with mid-tier North American contract manufacturers representing the most penetrable buyer segment. Target dairy alternative processors in Sweden and Denmark seeking clean-label emulsion stability without methylcellulose binders. Pursue technical service partnerships over distributor relationships to bypass established chemical trader networks. For Investors and Strategic Acquirers: Re-rating potential sits with Dead Sea mineral-sourced specialists given carbon border adjustment mechanism alignment under the EU Green Deal. Long-term viability favors producers with captive fermentation capacity and pharmaceutical-grade certification infrastructure. Watch FSSAI import inspection enforcement intensity as inflection indicator for Indian market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | USP-FCC dual certification unlocks pharmaceutical-adjacent food-grade premiums in Swiss and German nutraceutical supply chains. |
| Backward Integration into Fermentation | Captive citric acid supply from Iowa-Illinois corn steep liquor processing insulates margin from molasses price volatility. |
| Liquid Concentrate Format Scale-Up | Pre-dissolved solutions align with North American carbonated soft drink bottler retrofitting of tank farm infrastructure. |
| Direct Procurement Relationship Development | Bypassing distributor intermediaries satisfies lot traceability requirements from United States functional drink manufacturers. |
| Plant-Based Meat Application Technical Service | pH buffering expertise in extruded protein matrices captures uncontracted demand from methylcellulose displacement in burger analogs. |
Research Methodology
Trade statistics from customs databases, EFSA food additive authorization filings, and SEC 10-K disclosures from listed chemical producers formed the secondary backbone, cross-referenced against primary interviews with fermentation plant managers, beverage manufacturer procurement leads, dairy processor R&D directors, and acidulant distribution channel partners. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down capacity assessments from major production regions.
Historical trendline analysis of citric acid feedstock pricing and sodium citrate neutralization capacity utilization informed projection modeling across the forecast period. Segmentation dimensions included product type, physical form, application category, and end-use industry scale tier. CAGRs were derived from slope analysis of volume trajectories adjusted for regulatory catalyst timing and substitution elasticity parameters. Forecast inputs incorporated EFSA E331 authorization renewal schedules and FSSAI import inspection standardization implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under potassium citrate substitution acceleration or crystallization feedstock supply disruption scenarios. Projections reflect assumptions regarding Codex alignment progress in China and clean-label deadline adherence by German and Dutch dairy processors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Calcium Butyrate Market