
 Edible and Soluble Films Market | 2026-2036
Edible and Soluble Films Market Size, Share, and Industry Trends Forecast 2026-2036
Edible and Soluble Films Market Foresight
Pharmaceutical distribution channels are reshaping how edible and soluble films reach end users, with direct-to-manufacturer supply agreements replacing traditional wholesale intermediaries. Cargill, Incorporated leverages its global agricultural supply base to secure raw material consistency for starch-derived film production. Monosol LLC anchors North American capacity for polyvinyl alcohol water-soluble films used in detergent and pharmaceutical pods. KURARAY CO., LTD. dominates Asian supply of specialty polymer resins that enable high-clarity edible film substrates.
Edible and soluble films comprise thin, flexible matrices typically 20 to 200 microns thick, formulated from hydrocolloids, lipids, or synthetic polymers that disintegrate upon contact with moisture or saliva; manufacturers cast, extrude, or spin-coat these materials to create barriers against oxygen, moisture, or microbial ingress in food and drug applications. Water-soluble films lead product type demand due to their established use in unit-dose pharmaceuticals and household products, while edible coatings capture expanding margin pools as fresh produce packers seek shelf-life extension without synthetic preservatives. Gelatin and starch materials compete for cost-sensitive applications, though alginate formulations gain traction in nutraceuticals where vegan positioning commands price premiums.
FDA regulations on food contact substances and pharmaceutical excipients govern film composition and migration limits in the United States, while EFSA evaluates novel food applications for edible coatings within Europe. REACH compliance in the European Union constrains synthetic polymer chemistries, pushing formulators toward bio-derived alternatives. ISO standards for biodegradable packaging provide third-party validation pathways that unlock retail channel access. Stakeholders must monitor evolving pharmacopeial monographs for film-forming polymers, as compendial recognition determines pharmaceutical procurement eligibility and shapes R&D investment priorities.
Market Dynamics
Pharmaceutical unit-dose reformulation is collapsing traditional blister-pack supply chains as FDA guidance on orally dissolving dosage forms accelerates film-based drug delivery adoption across generic and innovator portfolios.
Growth Catalysts
- REACH compliance deadlines:ECHA's 2025 substance restriction timelines are forcing European formulators toward bio-derived hydrocolloids, opening procurement windows for alginate and pullulan suppliers.
- Patient compliance economics:Pediatric and geriatric drug developers are prioritizing taste-masked film strips over liquid suspensions, reducing spillage and dosing errors in home settings.
- India's PLI scheme for pharmaceuticals:CDSCO fast-track approvals for novel excipients are attracting contract manufacturing investment into Mumbai and Hyderabad clusters.
Market Restraints
- Polyvinyl alcohol supply concentration:Asian resin producers control 70% of pharmaceutical-grade PVA capacity, creating single-source vulnerability for European pod manufacturers.
- Film-forming polymer cost volatility:Seaweed harvest variability in Southeast Asia drives alginate price swings that destabilize nutraceutical coating budgets.
- Migration testing burden:FDA's food contact notification requirements impose 18-24 month validation timelines that freeze formulation innovation cycles.
Strategic Opportunities
- Brazil's ANVISA expedited pathway:Orphan drug film formulations qualify for priority review, creating first-mover advantage in Latin American rare disease markets.
- Fresh produce shelf-life extension:Edible coatings for berries and stone fruits remain underdeployed in Australian export supply chains despite TGA novel food approvals.
- Dual carbon goals in China:NMPA's green manufacturing incentives favor water-soluble detergent films over polyethylene sachets in domestic household brands.
Industry Challenges
- Compendial monograph lag:USP and EP updates for novel film-forming polymers trail commercial innovation by 3-5 years, blocking pharmaceutical procurement eligibility.
- Spin-coating technician scarcity:Precision film thickness control requires operators trained in rheology and surface science, skills concentrated in German and Japanese equipment hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible and Soluble Films Market |
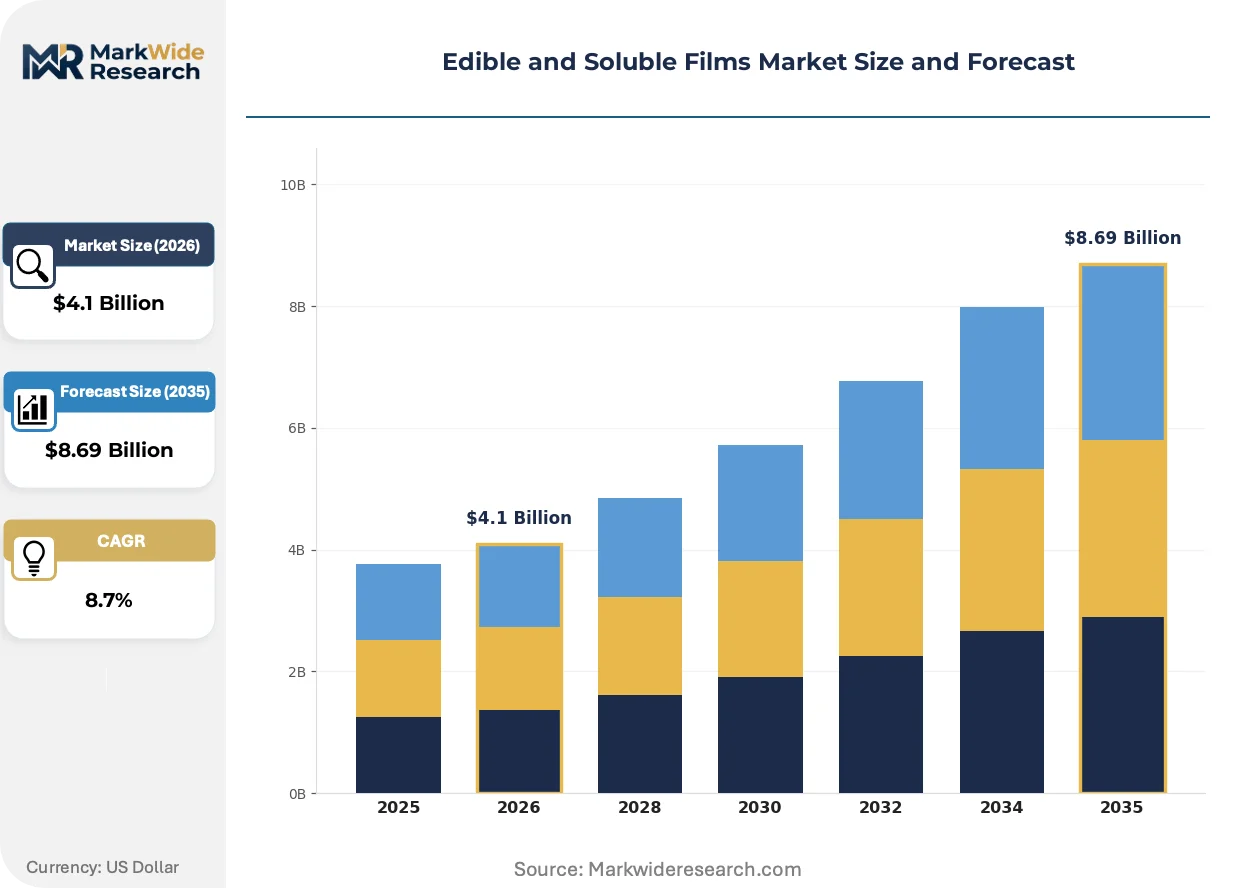
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Coatings, Microbial Films, Water-Soluble Films, Lipid-Based Films Application: Food Packaging, Nutraceuticals, Pharmaceuticals, Confectionery Material: Gelatin, Starch, Alginate, Cellulose End User: Food Industry, Pharmaceutical Companies, Cosmetics, Research Institutions |
| Companies Covered | Cargill, Incorporated, DuPont de Nemours Inc, Tate & Lyle PLC, Ingredion Incorporated, Monosol LLC, Archer-Daniels-Midland Company, KURARAY CO., LTD., SEKISUI CHEMICAL CO., LTD., AICELLO CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible and Soluble Films Market Shifts & Advancements
Active material science breakthroughs are compressing development cycles from laboratory casting to commercial extrusion, while regulatory convergence across FDA and EMA guidance documents is harmonizing validation protocols for multinational pharmaceutical launches.
Electrospinning nanofiber technology is collapsing the barrier between edible films and controlled-release matrices. Oral thin-film manufacturers are adopting electrospun scaffolds to embed poorly soluble APIs with 40% higher loading efficiency than solvent-casting methods. This convergence is collapsing the distinction between immediate-release films and extended-release depot formulations, enabling single-strip combination therapies previously requiring multiple dosage forms.
EMA's updated excipient guideline on plasticizers in orodispersible films is tightening migration limits for phthalate alternatives, forcing reformulators toward citrate esters and polyols. Industrial consequence includes 12-18 month reformulation cycles for legacy European products. Pediatric film specialists in Italy and Spain are responding with dedicated toxicology dossiers to secure Type II variations before 2026 implementation deadlines.
Hospital pharmacy buying groups are consolidating film-strip procurement through sole-source agreements with integrated dose-packaging services. This disintermediation is displacing traditional wholesale distribution for unit-dose pharmaceuticals. The shift is most visible in United States health system consolidation, where IDN-formulary committees now mandate film-based alternatives for ondansetron and melatonin where bioequivalence is established.
Edible and Soluble Films Market Segmentation
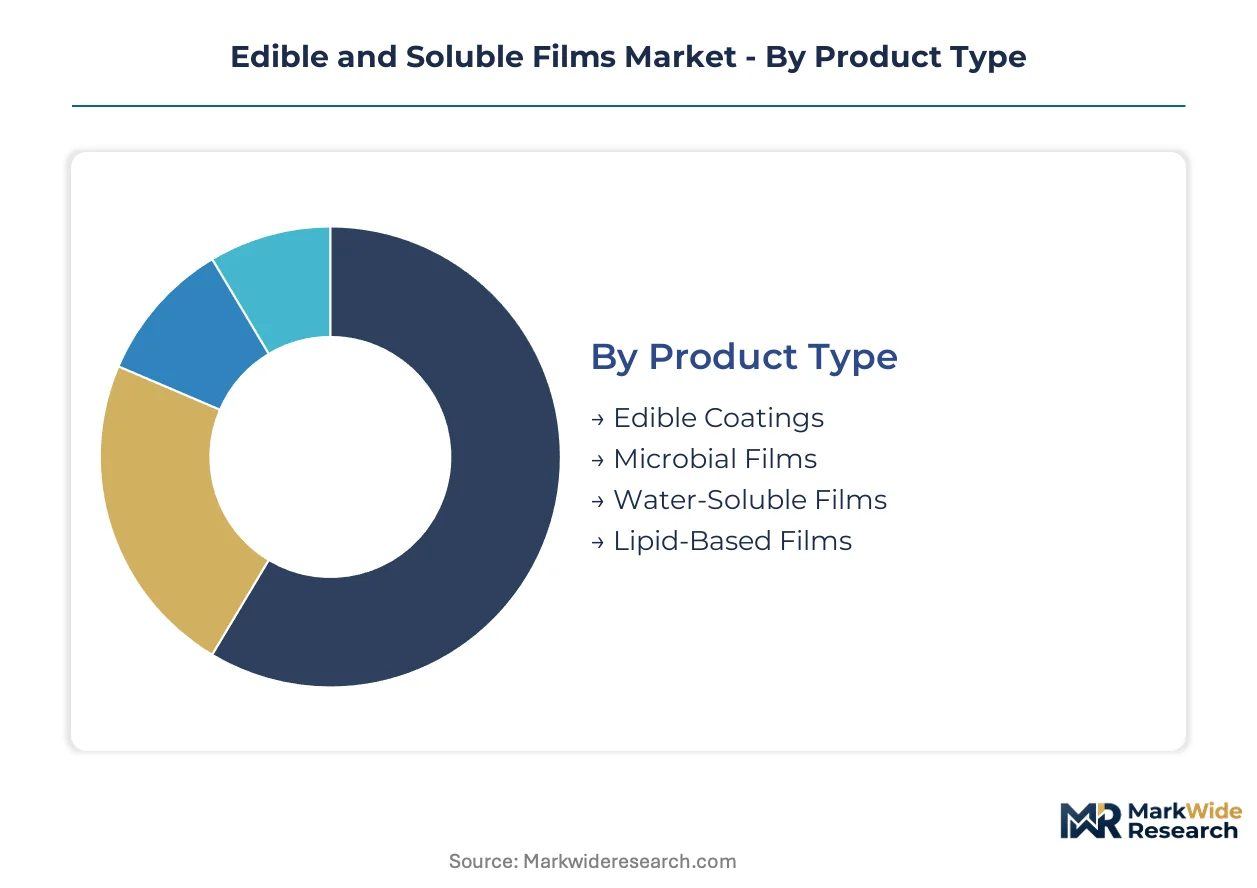
Edible and soluble films serve radically different performance requirements across food preservation, drug delivery, and industrial packaging. Segmentation reveals how formulation chemistry and end-use specifications create distinct margin pools and procurement channels.
Product Type:
Use-case spectrum spans moisture-triggered dissolution for pharmaceuticals to oxygen-barrier coatings for fresh produce, with each product type demanding specialized manufacturing infrastructure.
- Water-Soluble Films:Polyvinyl alcohol and pullulan matrices dissolve completely in aqueous environments without residue. Pharmaceutical unit-dose pods in Germany and household detergent sachets in China drive volume concentration, though resin supply bottlenecks in Southeast Asia constrain European manufacturers.
- Edible Coatings:Hydrocolloid and lipid barriers extend shelf life by reducing moisture loss and oxidative degradation in cut fruits and bakery items. Fresh produce exporters in Spain and Italy are adopting alginate-based formulations to replace synthetic waxes ahead of EFSA novel food evaluations.
- Microbial Films:Bacterial cellulose and fungal chitosan matrices offer biodegradable alternatives to petroleum-derived barriers. Research institutions in the Netherlands and Japan are scaling pilot production for premium food contact applications.
- Lipid-Based Films:Waxes and fatty acid esters create hydrophobic moisture barriers for confectionery and nut products. Brazilian and Malaysian palm-derived stearin supplies anchor cost-competitive production for chocolate enrobing.
The dominant share belongs to Water-Soluble Films, while Edible Coatings are closing the gap fastest.
Application:
Regulatory pathway complexity and reimbursement economics create tiered margin structures across end-use verticals.
- Pharmaceuticals:Orodispersible films and buccal strips require FDA Type II drug master files and EMA excipient qualifications. Pediatric and geriatric formulations in the United States command premium pricing due to bioequivalence validation requirements.
- Food Packaging:Active and intelligent packaging films incorporate antimicrobial agents and freshness indicators. Japanese convenience retail chains and French supermarket private labels are driving adoption of oxygen-scavenging coatings.
- Nutraceuticals:Vitamin and probiotic films mask bitter actives while enabling precise dosing. Vegan positioning in California and German markets favors pullulan over gelatin despite 15-20% cost premiums.
- Confectionery:Edible ink-printed films and dissolvable flavor strips target experiential consumption moments. Seasonal demand spikes in the United Kingdom and Mexico concentrate manufacturing capacity planning.
Pharmaceuticals capture the highest margin per kilogram, though Food Packaging generates the largest absolute volume.
Material:
Raw material sourcing geography and harvest volatility directly shape formulation cost stability and supply security.
- Gelatin:Bovine and porcine collagen hydrolysates provide film-forming capacity with established pharmaceutical compendial status. Brazilian and Argentine rendering supply chains face scrutiny from EMA transmissible spongiform encephalopathy guidelines.
- Starch:Native and modified corn, potato, and tapioca starches offer cost-effective barriers for moisture-sensitive foods. Cargill's North American supply base and Roquette's European wet-milling infrastructure anchor industrial-scale availability.
- Alginate:Brown seaweed extracts from Norwegian and Chilean harvests enable vegan, cold-water soluble films. Price volatility following 2023 Southeast Asian seaweed crop failures pushed nutraceutical formulators toward pullulan alternatives.
- Cellulose:Microcrystalline and nanofibrillated cellulose from wood pulp provide mechanical strength and thermal stability. Finnish and Swedish forestry-to-biorefinery integration supports pharmaceutical-grade HPMC supply.
Starch maintains volume leadership in cost-sensitive applications, while Alginate is expanding most quickly in premium vegan-positioned segments.
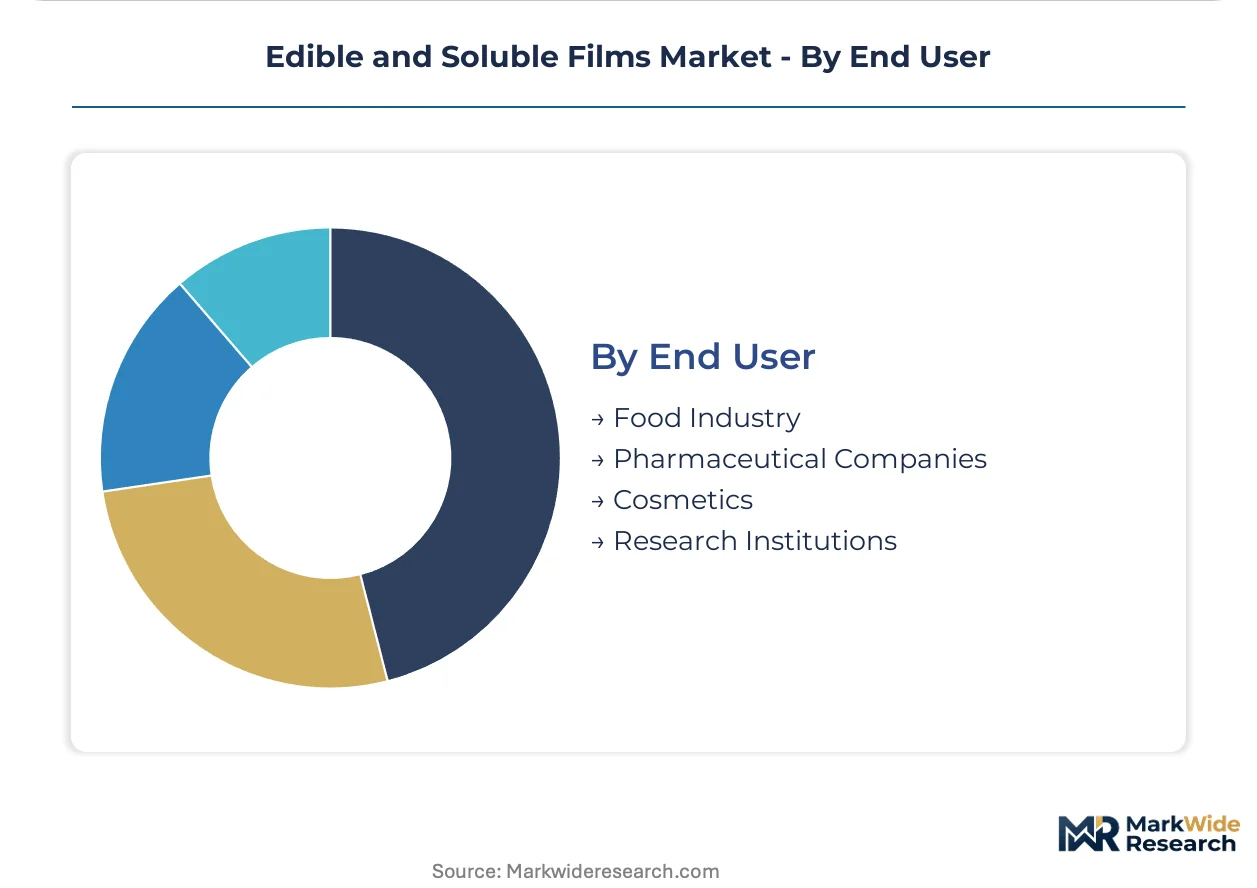
End User:
Procurement sophistication and technical specification rigor vary dramatically across buyer categories.
- Pharmaceutical Companies:Integrated dose-form developers require excipient master files, stability data, and audit trails. Contract manufacturers in India and Ireland are consolidating film-strip supply through sole-source agreements.
- Food Industry:Fresh produce packers and processed food manufacturers prioritize cost-per-unit and regulatory compliance over performance optimization. Brazilian meat exporters and Australian berry growers represent emerging coating adoption pockets.
- Cosmetics:Sheet mask and dissolvable patch brands in South Korea and France drive demand for ultra-thin, high-clarity films. Clean beauty positioning favors marine-derived over synthetic polymer substrates.
- Research Institutions:Universities and national laboratories pilot electrospun nanofibers and active-release matrices. German Fraunhofer institutes and Japanese NEDO programs anchor pre-commercial innovation pipelines.
Pharmaceutical Companies dominate value capture, while Food Industry procurement is climbing the fastest as coating technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on orally dissolving dosage forms anchors demand concentration in the United States, where pharmaceutical unit-dose reformulation accelerates film-based drug delivery adoption. Manufacturing infrastructure and regulatory clarity in specific national markets determine competitive positioning across edible and soluble film supply chains.
United States
Pharmaceutical companies prioritize taste-masked film strips for pediatric and geriatric formulations, reducing home dosing errors. FDA Type II drug master file requirements govern excipient qualifications for orodispersible films. Health system consolidation drives IDN-formulary committees in the Midwest and Southeast to mandate film-based alternatives for bioequivalent therapeutics.
Germany
Household detergent pods and pharmaceutical unit-dose applications consume polyvinyl alcohol film volumes. ECHA REACH compliance deadlines force formulators toward bio-derived hydrocolloids. Industrial clusters in North Rhine-Westphalia and Bavaria host extrusion capacity serving European pod manufacturers.
China
Domestic household brands shift from polyethylene sachets to water-soluble detergent films under NMPA green manufacturing incentives. Yangtze River Delta pharmaceutical contract manufacturers expand film-strip production for export markets. Shanghai and Suzhou clusters concentrate casting and extrusion equipment installation.
India
CDSCO fast-track approvals for novel excipients attract contract manufacturing investment into Mumbai and Hyderabad pharmaceutical clusters. PLI scheme subsidies support domestic film-forming polymer production. Fresh produce packers in Maharashtra pilot alginate coatings for export shelf-life extension.
Brazil
ANVISA expedited review pathways for orphan drug film formulations create first-mover positioning in Latin American rare disease markets. Palm-derived stearin supplies anchor cost-competitive lipid-based film production for confectionery applications. São Paulo state hosts the dominant pharmaceutical formulation capacity.
Edible and Soluble Films Market Competitive Landscape
Agricultural processors and specialty chemical manufacturers split the market into distinct capability tiers. Consolidation around raw material security and pharmaceutical-grade certification creates elevated barriers for new entrants. Integrated agribusiness conglomerates and focused polymer specialists represent the dominant archetypes. Capacity expansion in Asian resin production and backward integration into seaweed harvesting constitute the primary competitive vectors.
Among agricultural-derived film suppliers, Cargill, Incorporated and Archer-Daniels-Midland Company exemplify scale-driven hydrocolloid provision. Specialty polymer positioning is occupied by KURARAY CO., LTD. and SEKISUI CHEMICAL CO., LTD., which represent Japanese chemical conglomerate anchoring of pharmaceutical-grade water-soluble resin supply.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont de Nemours Inc |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Monosol LLC |
| Archer-Daniels-Midland Company |
| KURARAY CO., LTD. |
| SEKISUI CHEMICAL CO., LTD. |
| AICELLO CORPORATION |
| Others |
Supply & Pricing Matrix
Seaweed harvest volatility in Southeast Asia determines both the premium spread for alginate-based edible films and the geographic distribution of hydrocolloid manufacturing capacity. Buyers facing EFSA novel food compliance deadlines absorb 15-20% price premiums for pullulan alternatives when Chilean and Norwegian harvests tighten alginate supply.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade water-soluble films commands substantial premiums over standard food-packaging grades. Three-tier pricing structure across premium, standard, and economy levels separates FDA Type II drug master file holders from industrial pod manufacturers and commodity starch coating suppliers. Price differentiation hinges on compendial certification status and excipient qualification depth. Pricing pressure stems from Asian resin producers consolidating pharmaceutical-grade PVA capacity. Food industry buyers exhibit highest price sensitivity, while pediatric formulation developers accept premium positioning for taste-masked film strips.
Supply Chain Analysis
Contract manufacturing concentration in Mumbai and Hyderabad pharmaceutical clusters anchors film-strip production for export markets. Raw material supply draws from Southeast Asian seaweed harvests for alginate, North American corn wet-milling for starch derivatives, and Japanese petrochemical complexes for specialty PVA resins. Single-source vulnerability pervades pharmaceutical-grade PVA procurement, with Asian producers controlling dominant capacity shares. Distribution runs through direct-to-manufacturer supply agreements that displace traditional wholesale intermediaries for unit-dose pharmaceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as patient compliance economics splinter demand across pediatric, geriatric, and rare-disease niches with divergent formulation requirements.
For Market Incumbents: Entrench compendial certification advantages by accelerating USP and EP monograph submissions for novel film-forming polymers ahead of commercial launches. Backward integration into captive seaweed harvesting in Chile and Norway secures alginate supply against Southeast Asian crop volatility. Capacity expansion in Yangtze River Delta contract manufacturing clusters captures NMPA green manufacturing incentive flows.
For New Entrants and Emerging Players: Establish a beachhead in Australian fresh produce export coating applications where TGA novel food approvals exist but commercial deployment lags Spanish and Italian adoption curves. Target Brazilian orphan drug film formulations through ANVISA expedited review pathways before multinational incumbents consolidate Latin American rare disease positioning. Lead with vegan-certified alginate and pullulan formulations to capture premium positioning in California and German nutraceutical markets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors agricultural processors with pharmaceutical-grade certification capabilities and specialty polymer specialists with electrospinning nanofiber expertise. Acquisition target archetypes include electrospinning technology holders and seaweed harvesting operations with pharmaceutical-grade extraction capacity. The signal to watch is CDSCO fast-track approval velocity for novel excipients, which indicates contract manufacturing investment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Compendial Monograph Investment | USP and EP submissions unlock pharmaceutical procurement eligibility for film-forming polymer suppliers. |
| Seaweed Harvesting Integration | Chilean and Norwegian captive supply secures alginate cost stability against Southeast Asian volatility. |
| Electrospinning Capacity Buildout | Nanofiber scaffold production enables 40% API loading efficiency gains for oral thin-film manufacturers. |
| Direct-to-Manufacturer Distribution | IDN-formulary sole-source agreements displace wholesale intermediaries for unit-dose pharmaceuticals. |
| Green Manufacturing Certification | NMPA incentives favor water-soluble detergent films over polyethylene sachets in Chinese household brands. |
Research Methodology
The analysis maps water-soluble films, edible coatings, microbial films, and lipid-based barriers, each validated through film-formulation chemists, pharmaceutical procurement managers, fresh produce packers, and detergent pod manufacturers. Primary interviews with excipient qualification specialists and contract manufacturing executives combined with secondary validation from FDA Type II drug master file databases, EMA excipient qualification registers, CDSCO fast-track approval records, and customs trade data for hydrocolloid imports. Bottom-up capacity assessments and top-down demand modeling provided triangulation across segmentation dimensions.
Assumption sets held regulatory pathway timelines and raw material harvest yields fixed while varying pharmaceutical unit-dose adoption rates and fresh produce coating penetration curves across the analysis window. Segmentation modeling incorporated product type chemistry, application regulatory complexity, material sourcing geography, and end-user procurement sophistication. CAGRs derived from installed equipment capacity expansion plans and formulation development pipeline tracking. Electrospinning technology readiness and EMA plasticizer migration limit implementation schedules served as industry-specific forecast inputs.
Stress conditions across Southeast Asian seaweed harvest variability, PVA resin supply concentration, and FDA food contact notification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to compendial monograph lag and REACH compliance deadline acceleration. Quarterly review of CDSCO fast-track approval velocity and ECHA substance restriction implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Australia Food Colorants Market