
 Africa Food Hydrocolloids Market | 2026-2036
Africa Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Hydrocolloids Market Outlook
Nigeria's emerging hydrocolloid processing capacity is tilting supply dynamics across West Africa. Cargill leverages its integrated agricultural sourcing networks to secure guar gum and pectin supply chains from regional growers. Kerry Group anchors its technical service presence through application labs in Johannesburg and Lagos, supporting dairy and beverage formulation development.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, with typical usage levels ranging from 0.1% to 2.0% by weight depending on the desired rheological profile. These functional ingredients control water mobility, stabilize emulsions, and provide texture architecture in processed foods across thermal and shear processing conditions. Gelatin and pectin dominate current volume flows through established supply chains into dairy and bakery applications, while xanthan gum captures expanding share in beverage systems requiring acid stability and suspension performance. The powder form category sustains logistical advantages across Africa's fragmented cold chain infrastructure, though liquid hydrocolloid dispersions are gaining traction in industrial-scale food processing facilities near Lagos and Nairobi.
South Africa's Department of Health administers food additive approvals under the Foodstuffs, Cosmetics and Disinfectants Act, while the African Union's Continental Free Trade Area protocols are reshaping cross-border ingredient certification requirements. Compliance with CODEX Alimentarius standards, adopted reference-wise by multiple national food safety agencies, determines market access for imported hydrocolloid shipments from European and Asian suppliers. Stakeholders must monitor regulatory convergence timelines between the African Continental Free Trade Area's phased tariff reductions and emerging local content requirements for processed food ingredients.
Market Dynamics
Supply chain reconfiguration around South Africa's Department of Health additive compliance timelines is compressing procurement lead times across West Africa's processed food corridor, forcing ingredient distributors to pre-qualify alternative hydrocolloid sources before regulatory deadlines.
Growth Catalysts
- CODEX Alimentarius alignment:The African Union's harmonized food safety standards reduce cross-border certification duplication, accelerating hydrocolloid shipments between Ghana and Côte d'Ivoire.
- Dairy texture modification:Nigerian and Kenyan yogurt manufacturers are expanding hydrocolloid trials for thermal stability in ambient distribution networks lacking cold chain coverage.
- Xanthan gum acid stability:Beverage formulators in Lagos and Nairobi are adopting this hydrocolloid for suspension performance in low-pH juice systems.
Market Restraints
- Guar gum price volatility:Rainfall dependency across Rajasthan growing regions transmits directly to African import costs, destabilizing bakery margin structures.
- Gelatin supply concentration:Bovine and porcine-derived hydrocolloid sourcing clusters in South American rendering facilities create single-point vulnerability for halal-certified product lines.
- Powder-to-liquid conversion capex:Industrial-scale dispersion equipment requires capital outlays that mid-size Ghanaian processors defer, limiting formulation flexibility.
Strategic Opportunities
- Ethiopian bakery penetration:Teff-based injera industrialization creates untapped demand for hydrocolloid binders in gluten-free flatbread manufacturing.
- Plant-protein beverage stabilization:Pea and fava protein suspensions in Nigerian dairy alternatives require novel hydrocolloid synergies not yet optimized for local water chemistries.
- AfCFTA tariff phase-down:The African Continental Free Trade Area's staged duty elimination on processed food ingredients opens regional hub consolidation in Abidjan.
Industry Challenges
- Food technologist scarcity:Hydrocolloid rheology expertise concentrates in Johannesburg and Lagos, leaving secondary cities dependent on remote technical service.
- Halal certification latency:South Africa's Department of Health approval timelines for new gelatin sources extend 18-24 months, blocking product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Hydrocolloids Market |
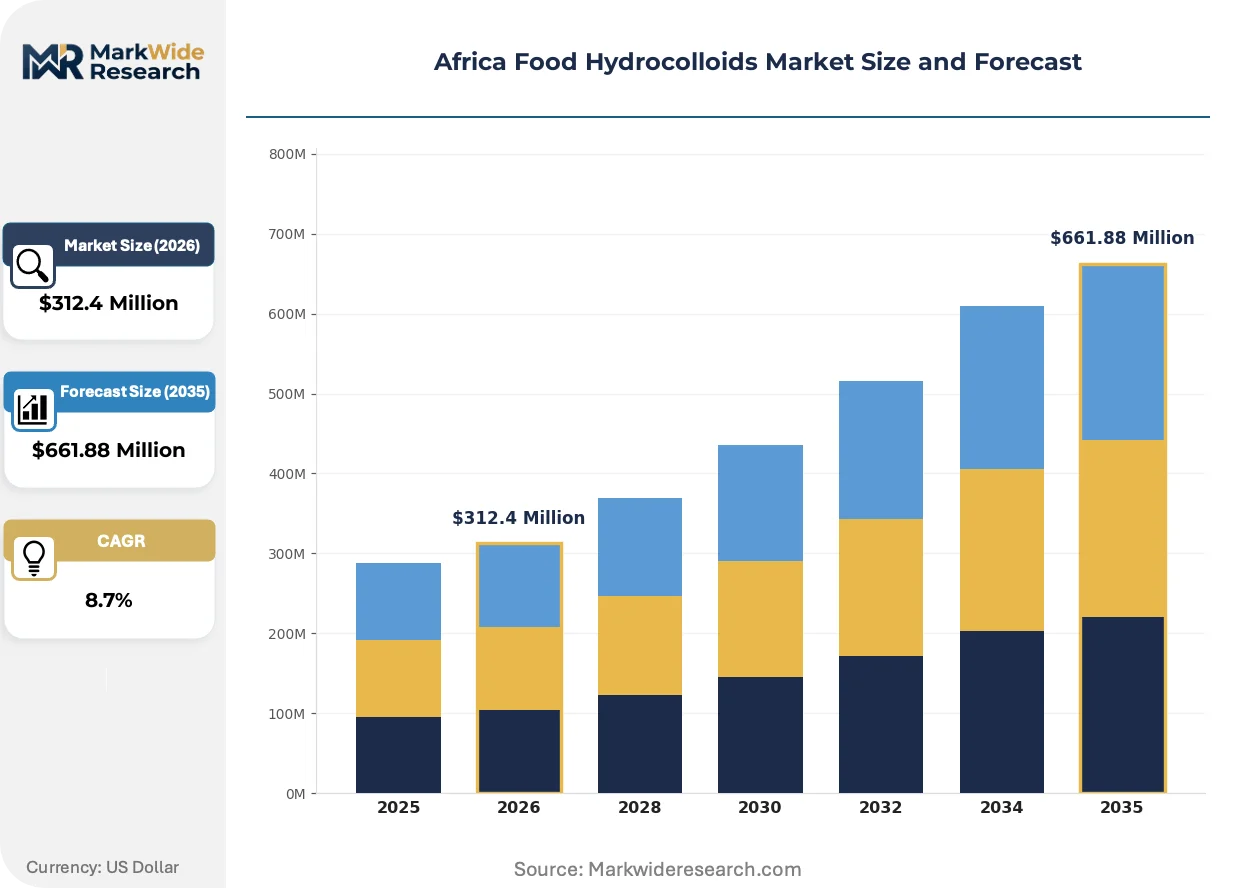
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Guar Gum, Pectin, Xanthan Gum Application: Dairy Products, Bakery, Beverages, Sauces Form: Powder, Liquid, Granule, Sheet End User: Food Processing, Catering Services, Retail, Food Service |
| Companies Covered | Cargill, Kerry Group, CP Kelco, Ingredion, DSM, DuPont de Nemours, Archer Daniels Midland Company, Tate & Lyle, Ashland, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Hydrocolloids Market Strategic Shifts
Formulation science is converging with supply chain pragmatism as African processors seek hydrocolloid systems that tolerate infrastructure gaps while meeting tightening safety standards.
Clean-label pectin-carrageenan blends are hybridizing traditional single-hydrocolloid applications in Nigerian dairy desserts. Lagos-based manufacturers are adopting these systems faster than Kenyan counterparts due to more fragmented cold chain reliability. The hybridization is compressing demand for conventional gelatin in ambient-stable yogurt categories where kosher and halal certifications intersect.
South Africa's Department of Health is tightening Foodstuffs Act enforcement on hydrocolloid maximum usage levels in infant nutrition. Industrial consequence includes mandatory third-party testing for acacia gum shipments entering paediatric formula channels. Nigerian importers are responding by pre-certifying suppliers through Johannesburg testing laboratories rather than European hubs.
Beverage concentrate buyers in Accra and Dar es Salaam are unbundling technical service from hydrocolloid supply contracts, awarding formulation support to independent labs while sourcing commodities via trading houses. This disintermediation is fragmenting supplier relationships that previously bundled application development with ingredient procurement. Kenyan juice processors exhibit the most advanced unbundling, separating xanthan gum supply from suspension stability troubleshooting.
Africa Food Hydrocolloids Market Segmentation
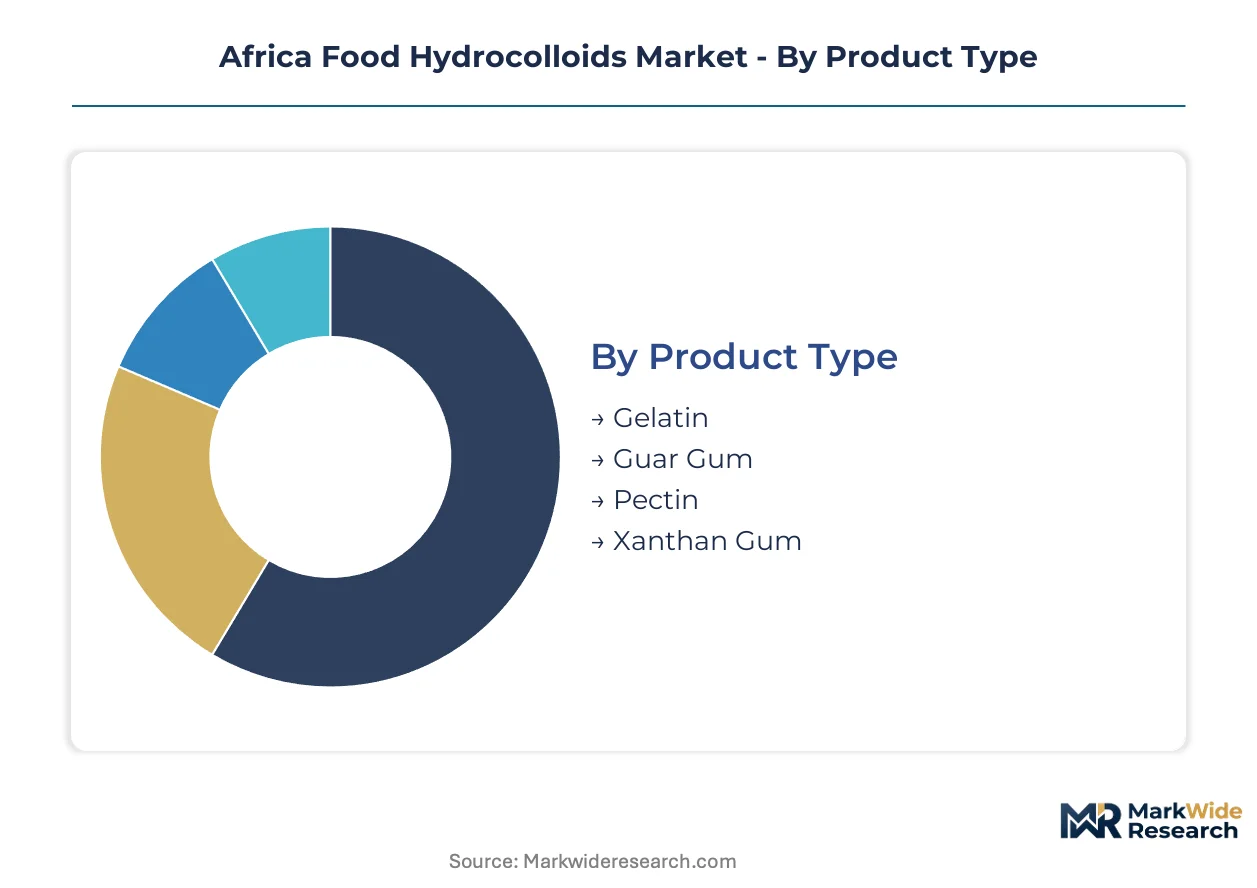
Segmentation in Africa's food hydrocolloids market reflects divergent supply chain realities across the continent. Product type splits reveal sourcing concentration risks, while application and form categories expose infrastructure-driven preferences that reshape procurement patterns.
Product Type:
Mature hydrocolloids anchor established supply chains, while emerging alternatives disrupt traditional procurement hierarchies through functional performance advantages.
- Gelatin:Derived from collagen hydrolysis of bovine and porcine tissues, this protein hydrocolloid delivers thermo-reversible gelation critical for confectionery and dairy desserts. Nigerian yogurt manufacturers source predominantly from South American rendering facilities, though halal certification latency stretches procurement cycles to 18-24 months.
- Guar Gum:A galactomannan polysaccharide extracted from Cyamopsis tetragonoloba seeds, valued for its cold-water solubility and viscosity-building capacity. Rainfall dependency across Rajasthan growing regions transmits price volatility directly to West African bakery margin structures, forcing Ghanaian processors to maintain dual-source inventories.
- Pectin:Citrus and apple-derived heteropolysaccharide forming gels in high-sugar, low-pH systems for jam and dairy applications.
- Xanthan Gum:Microbial exopolysaccharide produced via Xanthomonas campestris fermentation, prized for acid stability and shear-thinning rheology in beverage suspensions.
Gelatin handles the majority of throughput; xanthan gum is expanding most quickly on share.
Application:
Application splits trace the continent's processed food corridor expansion, with dairy and beverage investments outpacing traditional bakery concentration.
- Dairy Products:Hydrocolloids stabilize yogurt textures against thermal abuse in ambient distribution networks lacking cold chain coverage. Kenyan manufacturers trial pectin-carrageenan blends for thermal stability, while Nigerian processors prioritize gelatin for cost efficiency in cheese analogs.
- Beverages:Xanthan gum dominates low-pH juice systems requiring suspension performance without sedimentation. Lagos and Nairobi concentrate demand for acid-stable hydrocolloids in carbonated and still juice categories, with concentrate buyers in Accra unbundling technical service from supply contracts.
- Bakery:Guar gum and modified starches control moisture migration in extended-shelf-life bread.
- Sauces:Xanthan and locust bean gum synergies provide freeze-thaw stability in emulsified condiments.
Dairy products command the largest volume commitment; beverages are climbing the fastest on formulation sophistication.
Form:
Form selection exposes infrastructure constraints, with powder formats sustaining logistical advantages across fragmented cold chain networks.
- Powder:Dry hydrocolloid forms dominate procurement due to ambient storage compatibility and extended shelf stability. Industrial-scale facilities near Lagos and Nairobi maintain powder inventories, though dust handling and dispersion uniformity challenge mid-size Ghanaian processors.
- Liquid:Pre-hydrated dispersions eliminate dissolution equipment requirements but impose refrigerated transport constraints. Adoption concentrates in industrial-scale food processing facilities with captive cold chain segments, particularly beverage concentrate plants.
- Granule:Intermediate particle size reduces dusting versus powders while retaining dry handling logistics.
- Sheet:Gelatin sheets provide precise dosing for artisanal confectionery and premium dessert applications.
Powder formats sustain the dominant logistics footprint; liquid dispersions are gaining traction fastest among capital-equipped processors.
End User:
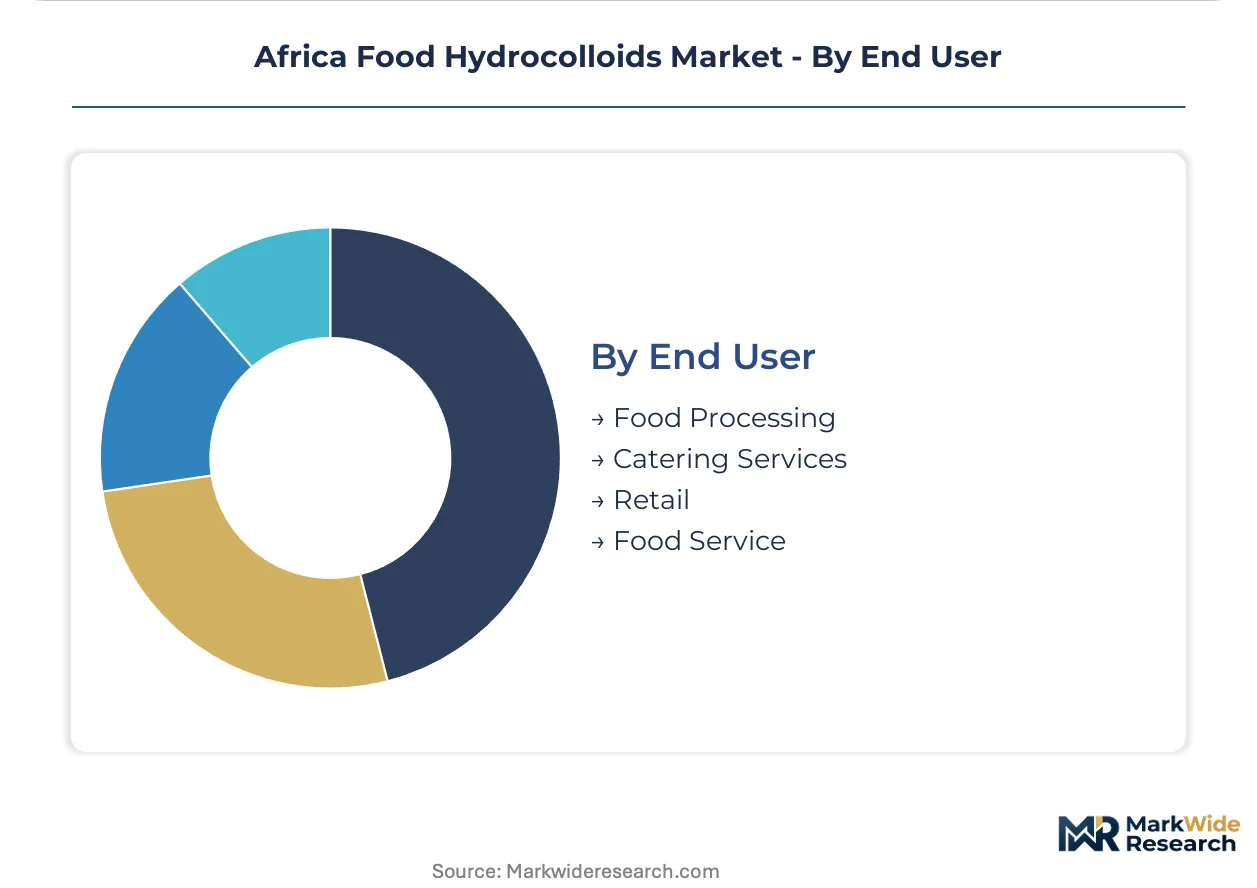
End user structure reflects Africa's bifurcated food economy, with industrial processing scaling while food service channels fragment.
- Food Processing:Industrial manufacturers of packaged foods, dairy, and beverages drive bulk hydrocolloid procurement through annual contracting. Nigerian and Kenyan yogurt producers expand technical trials for texture modification, while Ghanaian sauce manufacturers prioritize cost-optimized guar gum systems.
- Food Service:Chain restaurants and institutional catering source hydrocolloid-stabilized prepared ingredients through distributor networks. Demand concentrates in Lagos, Nairobi, and Johannesburg urban corridors where quick-service restaurant expansion outpaces supply chain standardization.
- Catering Services:Event and institutional catering sources pre-stabilized dessert and sauce bases.
- Retail:Consumer-packaged hydrocolloids for home cooking occupy niche premium positioning.
Food processing channels absorb the bulk of volume; food service is expanding fastest on quick-service restaurant penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guar gum supply chains from Rajasthan processing facilities dominate procurement economics across West Africa's processed food corridor. Nigerian and Ghanaian distributors maintain dual-source inventories to buffer monsoon-driven price volatility. South Africa's regulatory infrastructure anchors compliance certification for regional exporters.
Nigeria
Yogurt manufacturers in Lagos and Kano are expanding pectin-carrageenan trials for thermal stability in ambient distribution networks. The National Agency for Food and Drug Administration and Control (NAFDAC) enforces CODEX-aligned additive maximum usage levels through pre-shipment testing requirements. Industrial-scale beverage processing clusters near Lagos are adopting xanthan gum systems for acid-stable juice suspensions.
South Africa
Dairy dessert formulators in Johannesburg and Cape Town prioritize gelatin sourcing for cost-efficient texture modification in cheese analogs. The Department of Health administers Foodstuffs Act compliance timelines that compress procurement lead times for regional distributors. Technical service laboratories in Johannesburg anchor Kerry Group's application development support for Nigerian and Kenyan processors.
Ghana
Sauce manufacturers in Accra and Tema prioritize guar gum systems for emulsion stability in freeze-thaw condiment applications. Ghana Standards Authority adoption of African Union harmonized food safety standards reduces cross-border certification duplication with Côte d'Ivoire. Mid-size processors in the Tema industrial zone defer powder-to-liquid conversion capital outlays, limiting formulation flexibility.
Kenya
Nairobi-based yogurt producers trial hydrocolloid blends for ambient thermal stability in cold chain-deficient distribution networks. Kenya Bureau of Standards (KEBS) enforcement of additive labeling requirements accelerates third-party testing investments among importers. Juice concentrate buyers in Nairobi and Mombasa exhibit the most advanced unbundling of technical service from commodity supply contracts.
Ethiopia
Teff-based injera industrialization in Addis Ababa and Hawassa creates emerging demand for hydrocolloid binders in gluten-free flatbread manufacturing. Ethiopian Food and Drug Authority (EFDA) alignment with African Continental Free Trade Area protocols reshapes cross-border ingredient certification requirements. Bakery processing clusters in Addis Ababa represent untapped penetration opportunities for pectin and modified starch systems.
Africa Food Hydrocolloids Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in raw material extraction and primary processing. The vendor base separates into agricultural conglomerates with integrated sourcing networks, fermentation technology houses, and regional distribution specialists with formulation laboratories. Three archetypes dominate: integrated agricultural processors controlling seed-to-hydrocolloid value chains, microbial fermentation specialists producing consistent-grade exopolysaccharides, and technical service bundlers combining application development with commodity procurement. Capacity expansion and regulatory pre-certification partnerships constitute the dominant competitive moves across West and East Africa.
Among agricultural-integrated conglomerates, Cargill represents the upstream control archetype through its regional guar gum and pectin supply chain positioning. Kerry Group exemplifies the technical service bundler model with application laboratories in Johannesburg and Lagos supporting dairy and beverage formulation development. CP Kelco occupies a position within the microbial fermentation specialist tier, anchoring xanthan gum supply for acid-stable beverage systems in Nigerian and Kenyan processing facilities.
| Leading Market Players |
|---|
| Cargill |
| Kerry Group |
| CP Kelco |
| Ingredion |
| DSM |
| DuPont de Nemours |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Ashland |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Rajasthan guar gum processing facilities during monsoon-deficient cycles drives spot price spikes that cascade through West African bakery procurement budgets, forcing Nigerian and Ghanaian distributors to pre-position inventory ahead of seasonal rainfall patterns while suppliers extract premium pricing for guaranteed delivery windows.
Pricing Analysis
The Foodstuffs, Cosmetics and Disinfectants Act dictates the pricing tier structure across South African import channels, separating pharmaceutical-grade gelatin shipments from standard food-grade pectin and guar gum consignments. Certification latency under the Department of Health's 18-24 month approval timelines commands a 15-20% premium for pre-qualified suppliers versus spot-market alternatives. Cost compression in standard-grade hydrocolloids is intensifying because Ethiopian and Ghanaian processors are consolidating purchase volumes through regional trading houses. Mid-size Nigerian yogurt manufacturers exhibit the highest price sensitivity due to working capital constraints, while multinational beverage concentrate plants in Lagos prioritize supply security over unit cost minimization.
Supply Chain Analysis
Rainfall volatility across Rajasthan, Gujarat, and Haryana dominates procurement risk exposure for West African guar gum-dependent processors, with monsoon failures in any single state triggering cascading allocation disputes among Nigerian, Ghanaian, and Kenyan buyers. Raw material sourcing draws from Cyamopsis tetragonoloba seed harvests, citrus peel pectin extraction, and Xanthomonas campestris fermentation substrates. Single-source vulnerability concentrates in South American bovine gelatin rendering facilities serving halal-certified product lines. Distribution runs through Johannesburg compliance laboratories for pre-certification, then via Lagos and Mombasa port hubs to inland processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
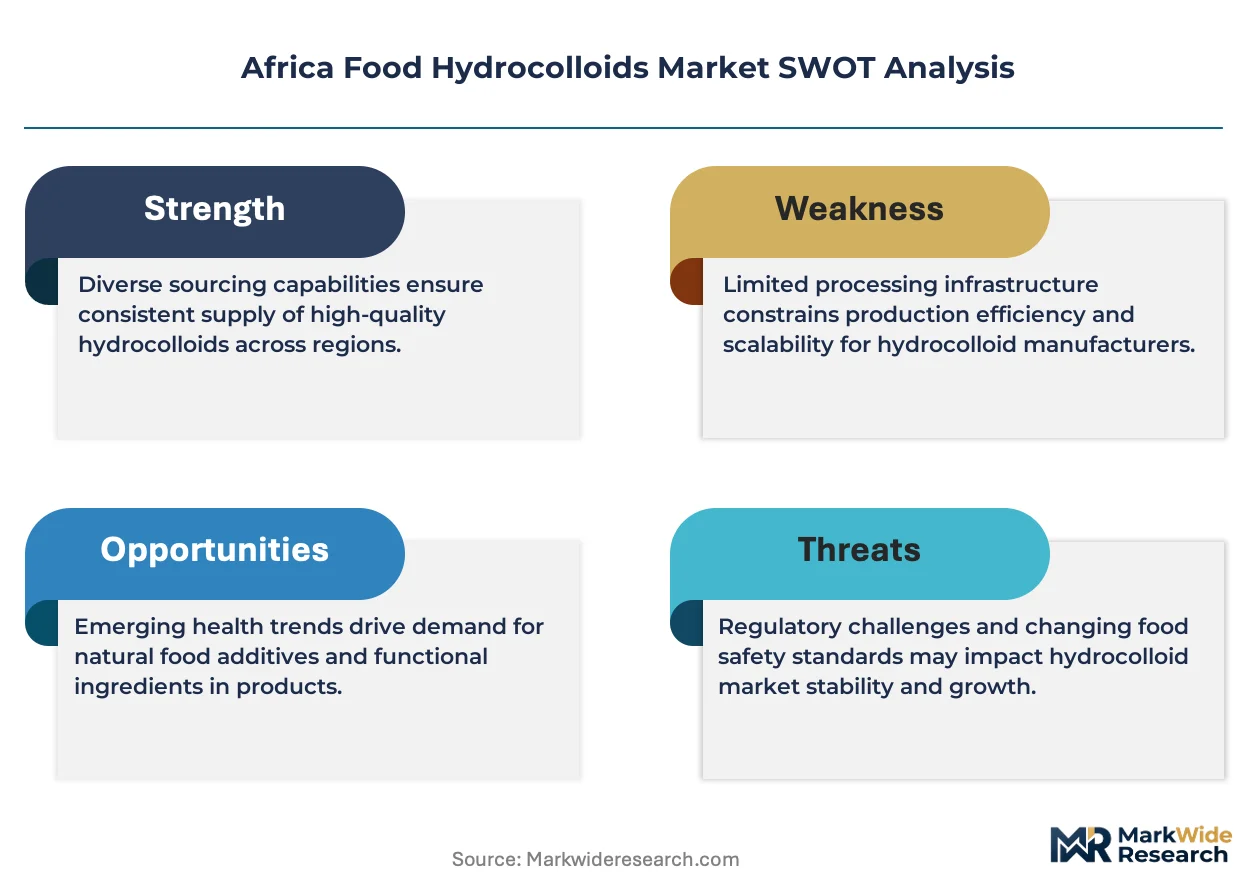
This market rewards regulatory entrenchment as a defensive moat, where 18-24 month certification timelines under South Africa's Department of Health create switching costs that lock in incumbent supplier relationships and deter speculative new entry.
For Market Incumbents: Harden technical service capabilities through application laboratory expansion in Nairobi and Accra, countering the unbundling trend that separates formulation support from commodity supply. Deepen backward integration into pectin extraction partnerships with Côte d'Ivoire and Ghana citrus processors to reduce European supply dependency. Prioritize CODEX Alimentarius pre-certification investments ahead of AfCFTA tariff phase-down deadlines to capture regional hub consolidation opportunities in Abidjan. For New Entrants and Emerging Players: Build out Ethiopian bakery sector penetration targeting teff-based injera industrialization clusters in Addis Ababa and Hawassa, where gluten-free hydrocolloid binder demand remains unserved by established suppliers. Target Nigerian plant-protein beverage manufacturers with novel hydrocolloid synergies optimized for local water chemistries, bypassing saturated dairy application segments. Lead with independent formulation laboratories that unbundle technical service from commodity procurement, mirroring the disintermediation pattern already advanced among Kenyan juice concentrate buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microbial fermentation capacity for xanthan gum production, as acid-stable beverage demand outstocks existing exopolysaccharide supply. Long-term viability favors technical service bundlers with captive application development capabilities rather than pure-play agricultural commodity traders. Acquisition targets should display regional laboratory footprints in at least two African markets plus pre-qualified supplier status under multiple national food safety regimes. The signal to watch is Department of Health approval timeline compression for new gelatin sources, which would erode incumbent certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Partnership | Department of Health approval timelines compress procurement lead times for compliant suppliers. |
| Application Laboratory Expansion | Technical service presence in Lagos and Nairobi supports dairy and beverage formulation development. |
| Backward Integration into Citrus Processing | Pectin extraction partnerships in Côte d'Ivoire reduce European supply chain dependency. |
| Regional Hub Consolidation | AfCFTA tariff phase-down opens Abidjan as West African distribution and compliance center. |
| Halal Certification Pipeline Investment | Pre-qualified bovine gelatin sourcing locks in confectionery and dairy dessert supply contracts. |
Study Parameters
Cross-validation between trade flow databases and regulatory filing records anchors the qualitative findings on supply chain reconfiguration dynamics. Primary interviews with hydrocolloid procurement managers at Nigerian dairy processors, Ghanaian sauce manufacturers, Kenyan beverage formulators, and South African regulatory affairs directors combined with secondary validation through customs declarations, CODEX Alimentarius national adoption schedules, and African Union harmonization protocol documents. Bottom-up volume estimates from application-level usage rates triangulate against top-down market sizing from import value flows.
Calibration against historical price volatility patterns in Rajasthan guar gum markets and Department of Health approval timeline distributions refines the projection framework across the analysis window. Segmentation dimensions modeled include hydrocolloid product type, application category, physical form, and end-user channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from elasticity-adjusted demand curves incorporating cold chain infrastructure development trajectories and processed food corridor expansion rates in West and East Africa.
Stress conditions across monsoon rainfall variability, AfCFTA implementation pace, and Department of Health enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory convergence timelines and infrastructure investment commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Alcohol Additives Market