
 Lung Stent Market | 2026-2036
Lung Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Stent Market Analysis
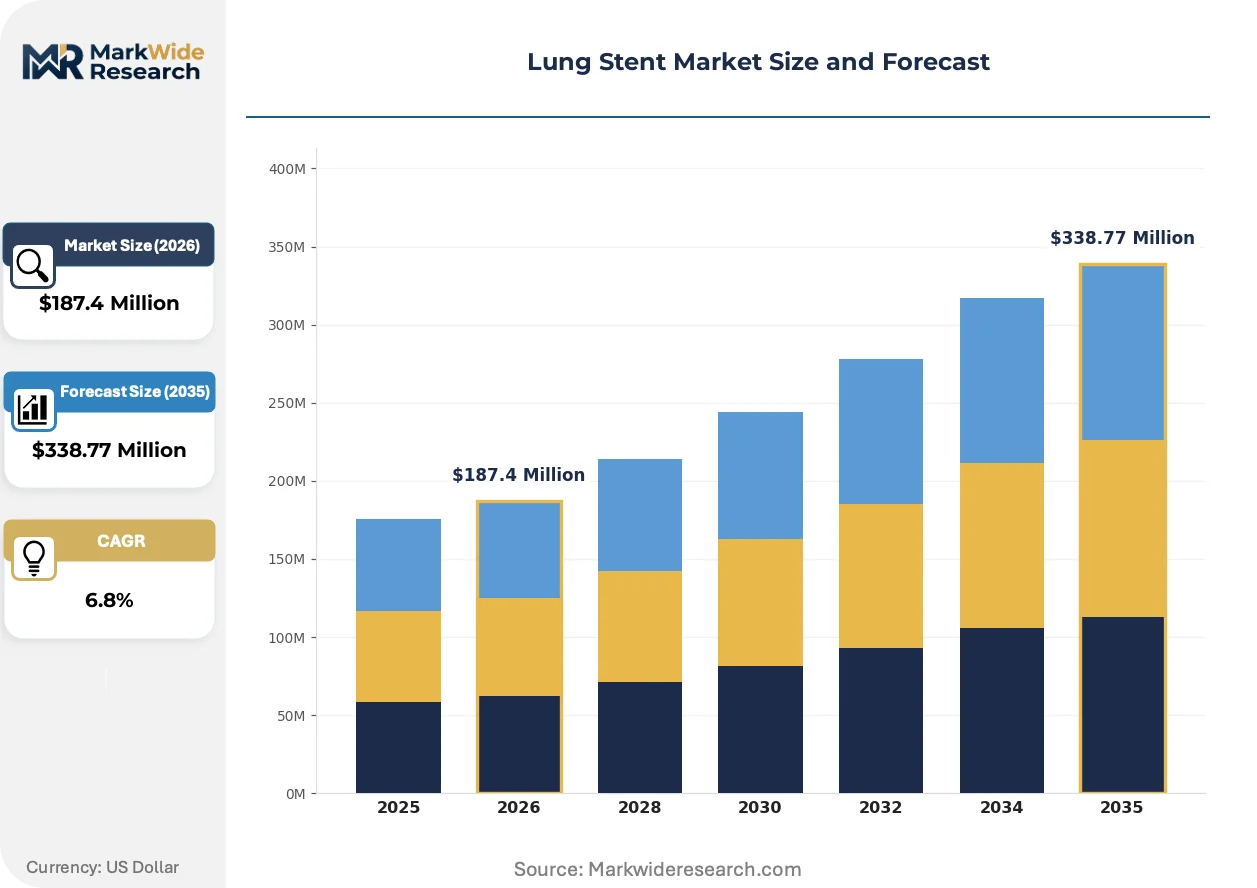
Hospital procurement consolidation is restructuring purchasing power across major healthcare systems, concentrating volume among integrated delivery networks and academic medical centers. Boston Scientific Corporation leverages its interventional pulmonology portfolio to anchor relationships with these consolidated buyers. Cook Group sustains competitive positioning through specialized airway stent manufacturing expertise and direct hospital contracting.
A lung stent is a tubular prosthesis typically constructed from nitinol, silicone, or hybrid polymers, designed to maintain patency within the trachea, bronchi, or bronchial subdivisions through radial force or external anchoring. The device serves to relieve extrinsic compression, restore airway lumen integrity, and enable ventilation in patients with benign or malignant stenosis. Metallic stents dominate current procedural volume due to their deployment efficiency and immediate radial strength, while drug-eluting variants represent the fastest-growing category as localized paclitaxel or sirolimus delivery reduces granulation tissue formation and restenosis rates. Covered stents command premium positioning in oncology applications where tumor ingrowth prevention determines clinical outcomes and reimbursement tiers.
FDA 510(k) clearance pathways and EU MDR Class III device requirements impose substantial clinical evidence and quality system burdens on manufacturers seeking market access. Japan's PMDA enforces stringent biocompatibility and fatigue testing standards that filter out lower-capability suppliers. Stakeholders must monitor evolving reimbursement codes for outpatient bronchoscopic stent placement and the shift toward value-based contracting for airway interventions.
Market Dynamics
Hospital procurement consolidation across the United States, Germany, and Japan is concentrating purchasing power among integrated delivery networks, forcing manufacturers to restructure contracting strategies and volume commitments around fewer, larger buyers with standardized device specifications.
Growth Catalysts
- Malignant Airway Obstruction Prevalence:Rising incidence of lung cancer and metastatic thoracic malignancies drives palliative intervention demand in oncology centers across the United States and Japan.
- EU MDR Class III Pathways:Streamlined conformity assessment procedures for established device categories accelerate market access for manufacturers with robust clinical evidence packages.
- Drug-Eluting Stent Technology:Localized paclitaxel and sirolimus delivery systems reduce granulation tissue formation, extending patency duration and lowering revision procedure frequency in tertiary care settings.
Market Restraints
- Nitinol Raw Material Concentration:Supply of nickel-titanium alloy for self-expanding stents concentrates among limited specialty metal processors, creating input cost volatility and lead time uncertainty.
- FDA 510(k) Clinical Evidence Burden:Substantial predicate device comparison requirements and quality system documentation impose protracted clearance timelines for novel stent designs.
- Silicone Stent Substitution Pressure:Removable silicone prostheses retain preference in benign stenosis cases, limiting metallic stent penetration in certain airway obstruction etiologies.
Strategic Opportunities
- India's Underpenetrated Interventional Pulmonology Sector:Limited bronchoscopic stent placement infrastructure in tier-2 and tier-3 cities creates whitespace for training partnerships and distributor expansion.
- Bioresorbable Polymer Convergence:Combining magnesium alloy scaffolds with programmable degradation profiles enables temporary airway support without permanent implant complications.
- Japan PMDA Innovation Fast Track:Priority review designation for breakthrough devices with demonstrated safety profiles accelerates reimbursement listing and hospital formulary adoption.
Industry Challenges
- Interventional Pulmonologist Training Bottlenecks:Specialized bronchoscopic stent deployment expertise remains concentrated among fellowship-trained specialists, constraining procedural capacity expansion.
- EU MDR Technical Documentation Recertification:Legacy device portfolios require substantial clinical data regeneration and notified body re-audit, compressing margin profiles during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Stent Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Stents, Drug-Eluting Stents, Biodegradable Stents, Covered Stents End User: Hospitals, Outpatient Clinics, Long-term Care Facilities, Home Care Settings Technology: Laser Technology, Balloon-Expandable, Self-Expanding, Hybrid Systems Application: Oncology, Pulmonology, Emergency Care, Palliative Care |
| Companies Covered | Boston Scientific Corporation, Cook Group, Medtronic, Taewoong Medical, Micro-Tech (Nanjing), Endo-Flex GmbH, Merit Medical Systems, Novatech SA, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Stent Market Emerging Trajectories
Device architecture is pivoting from permanent metallic implants toward bioengineered solutions that synchronize with tissue healing timelines, while regulatory frameworks and purchasing models co-evolve to accommodate these technological transitions.
Hybrid polymer-nitinol composite stents are converging with 3D patient-specific airway modeling to enable anatomically matched prosthesis deployment. Academic medical centers in Germany and Japan are adopting these customized workflows for complex tracheobronchial malformation cases. The convergence is compressing revision surgery rates and shifting competitive advantage toward manufacturers with integrated imaging partnerships.
Japan's PMDA has tightened biocompatibility and fatigue testing standards for implantable airway devices, filtering out suppliers lacking sophisticated materials characterization capabilities. Manufacturers must now submit extended cyclic loading data and surface chemistry analyses. European and US firms with established quality systems are capturing share as Japanese domestic suppliers face compliance cost escalation.
Integrated delivery networks in the United States are unbundling device procurement from procedural reimbursement, forcing stent manufacturers to demonstrate standalone value through outcome guarantees. Hospitals now negotiate separate contracts for stent acquisition and bronchoscopy service lines. This bifurcation is most advanced in California and Texas health systems with capitated oncology contracts.
Lung Stent Market Segmentation
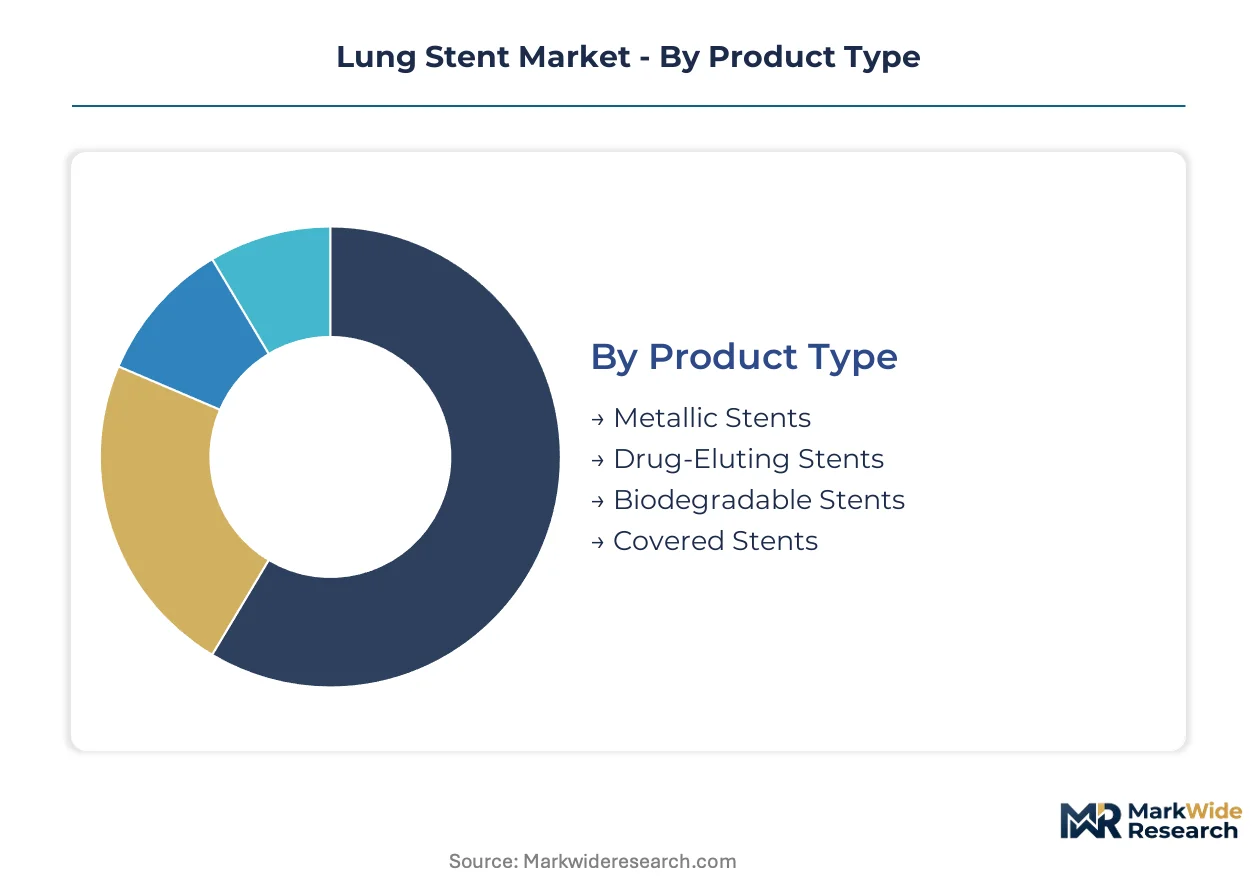
Lung stent segmentation reveals how technical specifications align with clinical workflows and procurement economics. Manufacturers configure product portfolios around deployment environments, reimbursement codes, and physician training requirements rather than pursuing undifferentiated scale.
Product Type:
Supply concentration in nitinol processing and polymer coating capabilities shapes competitive positioning across stent categories, with specialized metal processors and drug-polymer conjugation facilities creating tiered access barriers.
- Metallic Stents:Nitinol self-expanding scaffolds deliver immediate radial force for malignant airway obstruction cases. Demand concentrates in United States academic medical centers where interventional pulmonologists prioritize deployment speed over long-term patency. Silicone stent substitution pressure limits penetration in benign stenosis applications.
- Drug-Eluting Stents:Paclitaxel or sirolimus-eluting polymer coatings suppress granulation tissue formation at the stent-tissue interface. Germany's oncology centers and Japan's tertiary hospitals drive adoption as revision procedure costs factor into value-based contracting frameworks. These systems command premium positioning where patency duration determines reimbursement tiers.
- Biodegradable Stents:Magnesium alloy scaffolds with programmable degradation profiles enable temporary airway support without permanent implant complications.
- Covered Stents:Polymer membrane barriers prevent tumor ingrowth in malignant obstruction cases.
Today's leader: Metallic Stents. Tomorrow's challenger: Drug-Eluting Stents.
End User:
Procurement authority and procedure reimbursement rates create distinct customer tiers with diverging specification requirements and contracting behaviors.
- Hospitals:Integrated delivery networks in the United States and Germany's university hospitals concentrate purchasing volume through standardized device specifications. These buyers negotiate outcome guarantees and unbundle device procurement from procedural reimbursement, forcing manufacturers to demonstrate standalone clinical value.
- Outpatient Clinics:Ambulatory bronchoscopy centers in California and Texas health systems with capitated oncology contracts represent the fastest-expanding placement volume. Cost sensitivity and limited inventory space drive preference for universal sizing systems and streamlined deployment platforms.
- Long-term Care Facilities:Palliative care units manage chronic airway obstruction with reduced interventional capacity.
- Home Care Settings:Remote monitoring integration enables post-placement surveillance outside acute facilities.
Hospital systems dominate procurement value. Outpatient clinics are climbing the fastest.
Technology:
Deployment mechanism selection depends on airway anatomy complexity, physician training background, and available imaging infrastructure.
- Self-Expanding:Nitinol thermal shape memory enables deployment without balloon inflation, reducing procedure time in emergency airway obstruction cases. Japan's PMDA fatigue testing standards filter out suppliers lacking sophisticated materials characterization capabilities.
- Balloon-Expandable:Controlled diameter adjustment suits benign stenosis with predictable anatomy.
- Laser Technology:Precision cutting enables ultra-thin strut designs and customized mesh patterns.
- Hybrid Systems:Combined mechanical and thermal deployment mechanisms address complex tracheobronchial malformations.
Self-Expanding systems anchor procedural volume. Hybrid Systems are gaining share fastest.
Application:
Clinical indication determines stent selection criteria, with malignant versus benign etiology creating fundamentally different performance requirements and replacement timelines.
- Oncology:Covered stents with tumor ingrowth prevention dominate lung cancer and metastatic thoracic malignancy cases. United States and Japan oncology centers drive palliative intervention demand as rising cancer incidence expands addressable patient populations.
- Pulmonology:Benign stenosis management favors removable silicone prostheses in academic medical centers with fellowship-trained specialists.
- Emergency Care:Rapid deployment metallic systems address acute airway compromise.
- Palliative Care:Comfort-focused specifications prioritize symptom relief over long-term patency.
Oncology commands premium positioning. Palliative Care is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA enforces stricter biocompatibility standards than the FDA, filtering suppliers and reshaping competitive access, while Germany's university hospitals drive adoption of customized stent workflows through integrated imaging partnerships.
United States
Integrated delivery networks in California and Texas concentrate oncology procurement through capitated contracts, unbundling device acquisition from procedural reimbursement. FDA 510(k) clearance pathways impose predicate comparison burdens on novel nitinol designs. Academic medical centers in Boston and Houston anchor interventional pulmonology training capacity and stent placement volume.
Germany
University hospitals in Munich and Heidelberg adopt hybrid polymer-nitinol composites paired with 3D airway modeling for complex tracheobronchial malformations. EU MDR Class III conformity assessments accelerate market access for manufacturers with robust clinical evidence packages. The Baden-Württemberg medical technology cluster hosts specialized coating facilities serving drug-eluting stent production.
Japan
Tertiary hospitals in Tokyo and Osaka drive premium positioning for paclitaxel-eluting systems where patency duration determines reimbursement tiers. PMDA fatigue testing standards filter out suppliers lacking sophisticated materials characterization capabilities. The Kansai region's precision metal processors supply nitinol wire to domestic and international stent manufacturers.
India
Tier-2 and tier-3 cities present whitespace for bronchoscopic stent placement infrastructure expansion through distributor partnerships and physician training programs. CDSCO medical device regulations impose quality system documentation requirements on imported implantable devices. Maharashtra's Mumbai-Pune corridor concentrates private hospital capacity for interventional pulmonology services.
South Korea
Seoul's tertiary oncology centers generate demand for covered stents in lung cancer palliative care applications. MFDS enforces biocompatibility and sterilization validation standards aligned with international harmonization initiatives. The Seoul Capital Area hosts domestic stent manufacturers serving regional export markets.
Lung Stent Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale-driven portfolios anchor integrated delivery network contracts while niche manufacturers capture complex airway malformation cases. The vendor base organizes around three archetypes: diversified medical device conglomerates with interventional pulmonology divisions, specialized airway stent manufacturers with dedicated coating capabilities, and regional fabricators serving price-sensitive procurement channels. Competitive moves concentrate on strategic partnerships with imaging platform vendors and backward integration into nitinol wire processing to secure supply continuity.
Among diversified conglomerates, Boston Scientific Corporation and Medtronic occupy positions anchoring relationships with consolidated hospital buyers through broad interventional portfolios. Cook Group exemplifies the specialized manufacturer archetype, sustaining competitive positioning through dedicated airway stent manufacturing expertise and direct hospital contracting models. Taewoong Medical represents the Asia-based fabricator tier, serving regional markets with cost-optimized production configurations.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Group |
| Medtronic |
| Taewoong Medical |
| Micro-Tech (Nanjing) |
| Endo-Flex GmbH |
| Merit Medical Systems |
| Novatech SA |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
Nitinol alloy spot prices and nickel futures volatility cascade through lung stent manufacturing tiers, compressing margins for processors lacking long-term offtake agreements with German or Japanese specialty metal suppliers while amplifying pricing power for integrated manufacturers with captive nitinol wire production.
Pricing Analysis
Capacity additions in South Korea and China's precision metal sectors are reshaping price floors for standard nitinol self-expanding stents, though FDA 510(k) predicate device requirements and EU MDR Class III certification tiers sustain premium-mid-economy pricing differentiation. Price differentiation hinges on biocompatibility certification grade and volume scale commitments to integrated delivery networks. Cost compression in the standard tier intensifies as Chinese manufacturers achieve PMDA fatigue testing compliance. Outpatient clinics in capitated oncology contracts exhibit highest price sensitivity; academic medical centers with fellowship training programs show lowest sensitivity due to outcome guarantee requirements.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks and Germany's university hospital procurement committees require qualified nitinol wire suppliers from both the Kansai region's precision metal processors and Baden-Württemberg's medical technology cluster. Raw material dependencies center on nickel-titanium alloy feedstock, paclitaxel-polymer conjugates, and silicone membrane sheeting. Single-source vulnerability concentrates in Japanese domestic suppliers facing PMDA compliance cost escalation. Distribution runs through specialized interventional pulmonology distributors serving tertiary hospitals and direct contracting with consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lung stent market functions as a geographic-arbitrage play where manufacturers with EU MDR pre-certified portfolios capture margin premiums in Japan's reimbursement-tiered system while cost-optimized configurations penetrate India's underpenetrated tier-2 and tier-3 cities.
For Market Incumbents: Anticipate bioresorbable magnesium alloy scaffolds displacing permanent metallic implants in benign stenosis applications by deepening backward integration into nitinol wire processing and securing Kansai-region alloy supply commitments. Prioritize PMDA innovation fast-track qualification for drug-eluting variants to defend formulary positioning against emerging Korean manufacturers. For New Entrants and Emerging Players: Distributor partnerships with India's Maharashtra-based private hospital networks offer the most penetrable whitespace, bypassing interventional pulmonologist training bottlenecks through bronchoscopic simulation center sponsorships. Target ambulatory bronchoscopy centers in Texas and California capitated contracts with universal sizing systems and streamlined deployment platforms priced below standard metallic stent tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating facilities possessing drug-polymer conjugation capabilities and PMDA fatigue testing infrastructure, as EU MDR recertification burdens compress legacy device margins and create distressed acquisition opportunities. Watch for PMDA priority review designations as inflection indicators for reimbursement listing velocity and hospital formulary adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Innovation Fast-Track Submission | Priority review designation accelerates reimbursement listing in Tokyo and Osaka tertiary hospitals. |
| Backward Integration into Nitinol Processing | Captive alloy supply from Kansai-region processors insulates against nickel price volatility and lead time uncertainty. |
| Hospital System Partnership | Direct contracting with California and Texas integrated delivery networks unbundles device procurement from bronchoscopy service lines. |
| 3D Airway Modeling Integration | Partnerships with German university hospital imaging platforms enable patient-specific stent deployment for complex malformations. |
| Reimbursement Strategy | Outcome guarantees for patency duration align with Germany's value-based contracting frameworks and Japan's premium tier reimbursement. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and South Korea, with primary inputs from each market combining structured interviews with interventional pulmonologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, PMDA approval databases, EU MDR notified body audit records, hospital procurement databases, and CMS Medicare reimbursement codes. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, modeling lung stent demand by product type (metallic, drug-eluting, biodegradable, covered), end user (hospitals, outpatient clinics, long-term care, home care), deployment technology (self-expanding, balloon-expandable, laser-cut, hybrid), and clinical application (oncology, pulmonology, emergency care, palliative care). CAGRs derive from procedure volume trajectories, replacement frequency assumptions, and reimbursement tier migration patterns, with nitinol raw material cost indices and regulatory approval timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA fatigue testing standard evolution, EU MDR recertification timelines for legacy devices, and hospital procurement consolidation velocity in United States oncology contracts. Deviation in nitinol alloy supply concentration or interventional pulmonologist training pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Arterial Cannula Market