
 Global Ventricular Assist Device Market | 2026-2036
Global Ventricular Assist Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ventricular Assist Device Market Foresight
The capital-intensity divergence between centrifugal-flow and axial-flow platform developers is reorganizing competitive hierarchies in ventricular assist device manufacturing. Abbott Laboratories leverages its fully integrated structural heart portfolio to control supply chain costs across pump, controller, and driveline components. Medtronic sustains R&D intensity through dedicated heart failure franchises in Minneapolis and Dublin. Berlin Heart GmbH anchors European market access with specialized pediatric VAD expertise that larger competitors have not replicated.
A ventricular assist device is an electromechanical pump implanted to support cardiac circulation in patients with end-stage heart failure, typically featuring a titanium-alloy housing, biocompatible inflow cannula, and transcutaneous power transfer across a 5–7 mm skin exit site. The primary purpose is to restore systemic perfusion while reducing ventricular preload, either as temporary circulatory support or long-term alternative to transplant. Implantable LVAD systems dominate value capture due to their established reimbursement pathways and expanding destination therapy eligibility, while external VAD configurations retain niche utility in acute cardiogenic shock settings where rapid deployment outweighs ambulatory convenience. Bridge to transplant indications remain the largest patient indication segment by procedure volume, though destination therapy is deepening its margin pool as payers extend coverage to INTERMACS profile 4–7 candidates.
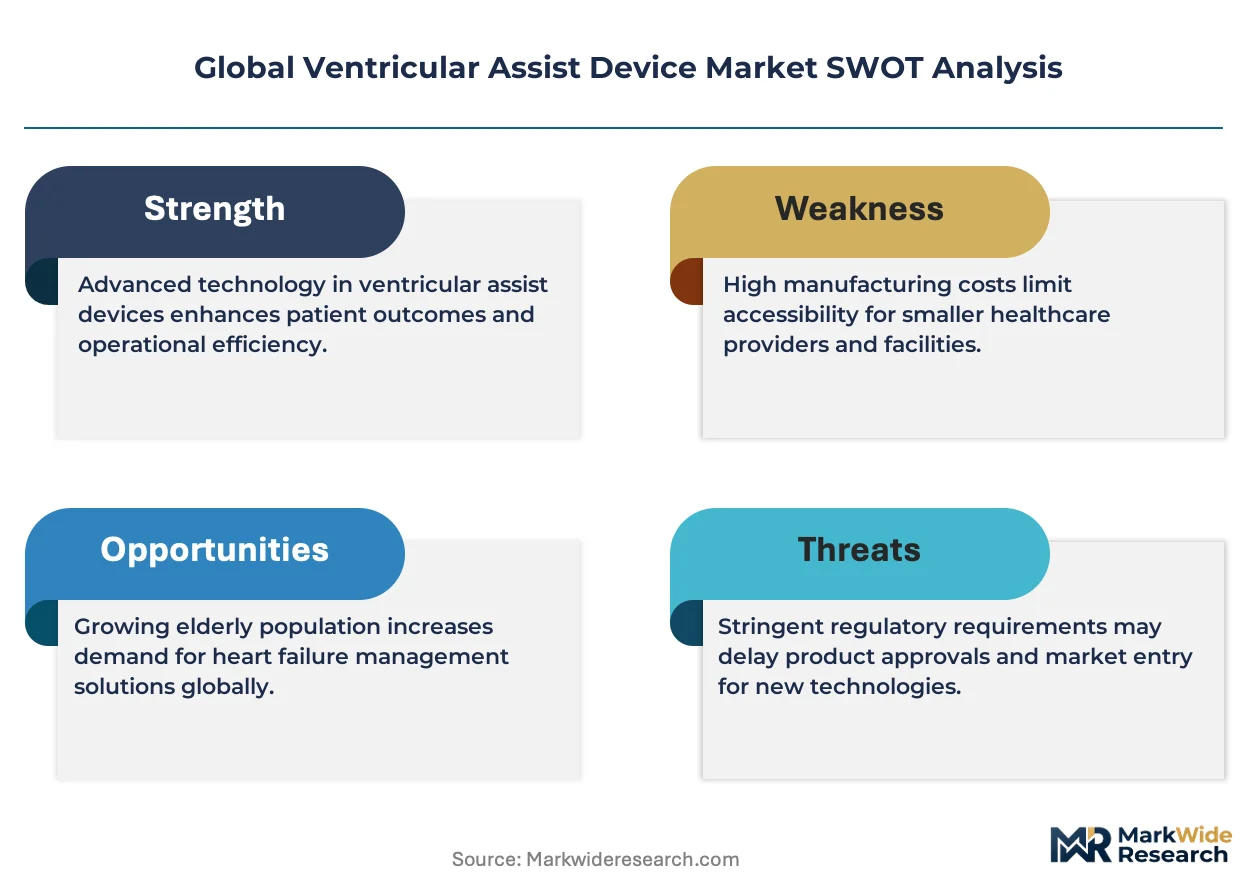
FDA premarket approval requirements and EU MDR technical documentation mandates shape product development timelines and clinical evidence thresholds for all active manufacturers. ISO 14708-5 active implantable medical device standards further constrain electromagnetic compatibility and battery failover specifications. Japan's PMDA sakigake designation pathway offers accelerated review for novel VAD technologies, creating regulatory arbitrage opportunities for firms with existing FDA clearance. Stakeholders must monitor evolving INTERMACS registry outcomes data and corresponding payer coverage determinations to anticipate which device configurations will secure preferred reimbursement status.
Market Dynamics
Destination therapy eligibility expansion is compressing bridge-to-transplant volumes while forcing manufacturers to reconfigure clinical trial endpoints around long-term durability metrics rather than short-term survival outcomes.
Growth Catalysts
- EU MDR compliance acceleration:Stricter post-market surveillance requirements in Europe are filtering out marginal device developers and consolidating procurement around established manufacturers with robust quality management systems.
- Pediatric VAD specialization:Berlin Heart GmbH's Berlin EXCOR platform addresses an underserved neonatal and pediatric segment where transplant waitlist mortality remains critically elevated.
- Biocompatible inflow cannula materials:Advancements in textured titanium surfaces and heparin coatings are reducing thromboembolic complications and extending device longevity in ambulatory patients.
Market Restraints
- Titanium-alloy supply concentration:Aerospace and medical device demand for Grade 5 titanium concentrates sourcing through a limited supplier base in Japan and Russia, exposing pump housing manufacturers to input volatility.
- FDA premarket approval timelines:The agency's evolving evidentiary standards for durability testing and adverse event reporting extend development cycles beyond typical cardiovascular device benchmarks.
- Transcatheter heart valve substitution:Structural heart interventions that delay or prevent end-stage heart failure progression reduce the addressable population for permanent mechanical circulatory support.
Strategic Opportunities
- Japan's PMDA sakigake pathway:Accelerated regulatory review for breakthrough VAD technologies creates first-mover advantages for firms with existing FDA clearance seeking Asian market entry.
- Home-based power management systems:Portable controller units with wireless monitoring capabilities enable discharge protocols that shift care delivery from tertiary centers to outpatient settings.
- India's cardiac surgery infrastructure expansion:Greenfield hospital developments in Chennai, Hyderabad, and Mumbai are installing dedicated heart failure programs without legacy transplant center dependencies.
Industry Challenges
- Electromagnetic compatibility engineering:ISO 14708-5 active implantable device standards constrain battery failover architecture and wireless telemetry integration, requiring specialized firmware development talent.
- INTERMACS registry data harmonization:Variability in adverse event definitions across international registries complicates pooled safety analyses for regulatory submissions.
- Driveline infection management protocols:Transcutaneous power transfer through 5–7 mm skin exit sites creates persistent infection risk requiring coordinated nursing and infectious disease specialist training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ventricular Assist Device Market |
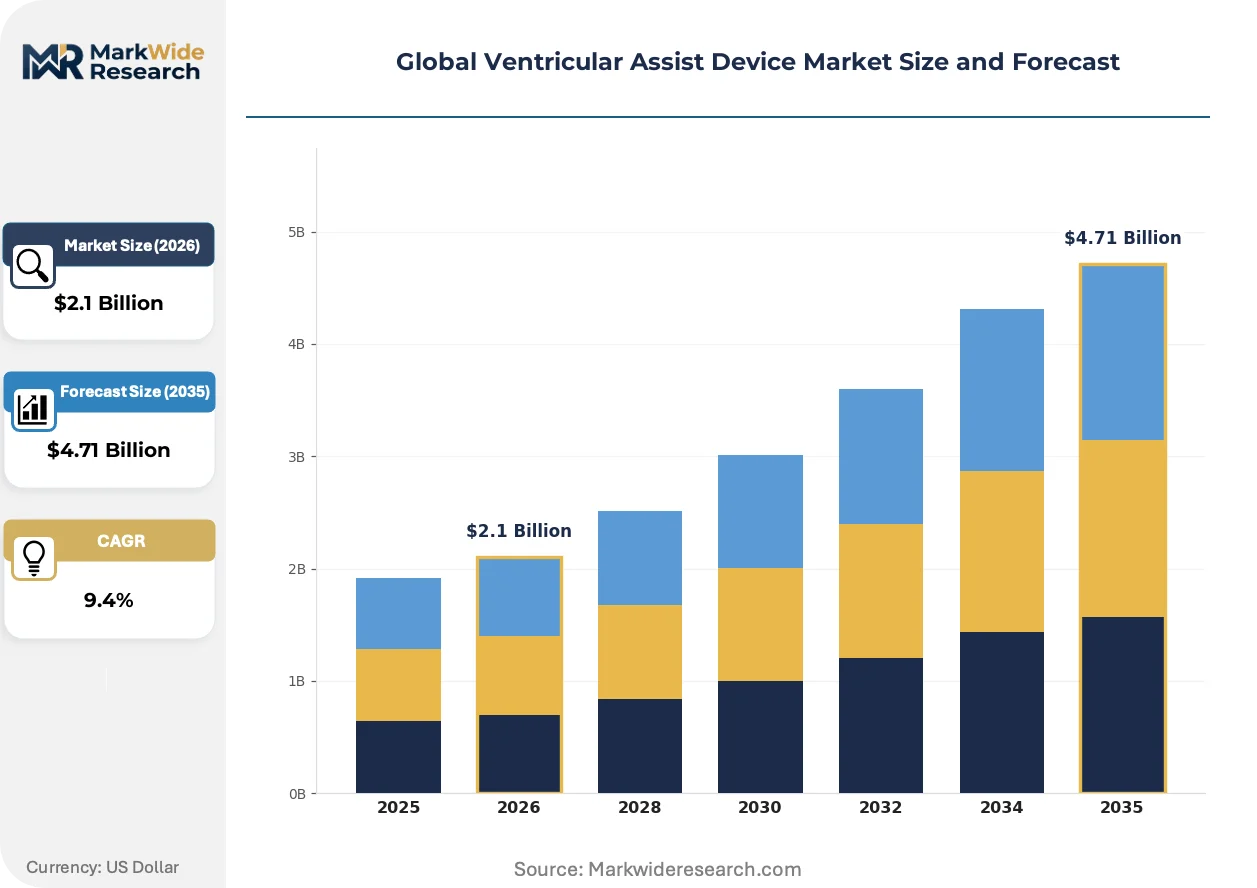
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Implantable LVAD, Implantable RVAD, Implantable BiVAD, External VAD Patient Indication: Bridge to Transplant, Destination Therapy, Bridge to Recovery, Bridge to Candidacy End User: Cardiac Surgery Centers, Specialty Cardiac Hospitals, Research Institutions, Ambulatory Surgical Centers Deployment Type: Inpatient Facilities, Outpatient Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Abbott Laboratories, Medtronic, Berlin Heart GmbH, Abiomed, Jarvik Heart, Inc., SynCardia Systems, Terumo Corporation, Evaheart, Inc., LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ventricular Assist Device Market Shifts & Advancements
Magnetic levitation bearing systems and fully transcutaneous energy transfer architectures are displacing mechanical contact points and percutaneous drivelines as the dominant innovation vectors in next-generation pump design.
Magnetically suspended impeller technology eliminates mechanical bearing wear as a failure mode in continuous-flow pumps. Cleveland Clinic and Texas Heart Institute investigators are prioritizing these platforms for destination therapy candidates anticipated to require support beyond five years. The technology is fragmenting competitive positioning between established axial-flow incumbents and centrifugal-flow challengers willing to absorb higher R&D intensity.
FDA breakthrough device designation compresses premarket review timelines for novel VAD configurations addressing unmet needs in biventricular support. The pathway's evidentiary flexibility is accelerating humanitarian use device conversions and pediatric indication expansions. EU MDR technical documentation mandates are simultaneously forcing European notified bodies to recalibrate conformity assessment bandwidth, creating temporary regulatory arbitrage for US-cleared devices.
Hospital value analysis committees are unbundling device procurement from mandatory service contracts and demanding transparent component-level pricing for controllers, batteries, and backup power systems. Tertiary cardiac centers in Germany and Japan are piloting consignment inventory models that transfer obsolescence risk to manufacturers. This restructuring is most visible in United States academic medical centers where supply chain teams now benchmark total cost of ownership across implantable and external VAD configurations.
Global Ventricular Assist Device Market Segmentation
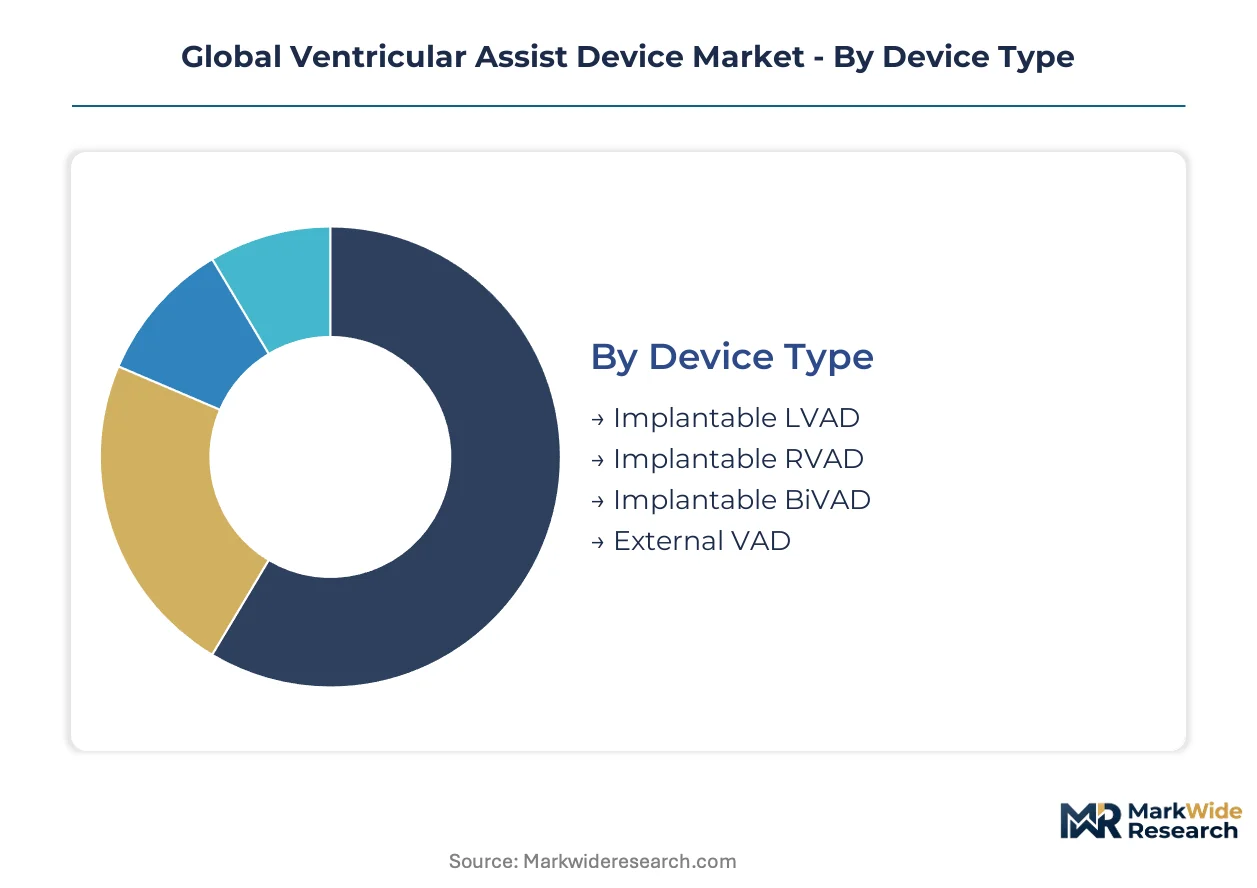
Ventricular assist device procurement varies sharply across clinical settings and patient acuity levels. Manufacturers configure pump platforms, controller systems, and service models to match the operational constraints of cardiac surgery centers versus ambulatory environments. Understanding these segment boundaries clarifies where pricing power concentrates and which configurations face commoditization pressure.
Device Type:
Implantable LVAD systems dominate domestic hospital procurement in the United States and Germany, while external VAD configurations serve export markets with less developed transplant infrastructure.
- Implantable LVAD:Titanium-alloy housing with continuous-flow impeller design supports systemic circulation from the left ventricle. Demand concentrates in Cleveland Clinic, Houston Methodist, and German Heart Center Berlin where destination therapy programs have expanded INTERMACS 4-7 eligibility. Reimbursement density and specialized surgical expertise sustain premium positioning.
- Implantable RVAD:Right ventricular support systems address biventricular failure through separate pump implantation or integrated BiVAD configurations. Procurement runs through transplant centers in Japan and the United States facing rising rates of post-LVAD right heart failure requiring mechanical rescue.
- Implantable BiVAD:Dual-pump systems provide synchronous left and right ventricular support.
- External VAD:Paracorporeal pumps deployed via sternotomy or peripheral cannulation for acute cardiogenic shock.
Implantable LVAD commands the established base. The steepest expansion runs through external VAD configurations.
Patient Indication:
Cost tier stratification separates bridge-to-transplant candidates—typically covered by comprehensive transplant center bundled payments—from destination therapy patients requiring durable support without transplant eligibility.
- Bridge to Transplant:Temporary circulatory support maintaining organ perfusion during transplant waitlist periods. Centers in the United States, Germany, and Japan account for the majority of procedure volume where organ allocation systems and specialized surgical infrastructure converge.
- Destination Therapy:Permanent mechanical support for transplant-ineligible end-stage heart failure. Medicare coverage expansion and private payer alignment in the United States have deepened this segment's margin pool as INTERMACS profiles broaden.
- Bridge to Recovery:Short-term support enabling myocardial rest and potential weaning.
- Bridge to Candidacy:Stabilization therapy converting initially ineligible patients to transplant candidates.
Bridge to transplant commands the established base. The steepest expansion runs through destination therapy.
End User:
Customer type determines service intensity requirements, with cardiac surgery centers demanding 24/7 clinical engineering support while research institutions prioritize protocol flexibility and data access.
- Cardiac Surgery Centers:High-volume implant programs with dedicated VAD coordinators and standardized discharge protocols. Texas Heart Institute, Mayo Clinic Rochester, and Heidelberg University Hospital anchor procurement concentration in the United States and Germany.
- Specialty Cardiac Hospitals:Focused heart failure institutions without full transplant certification. Berlin Heart GmbH maintains strong positioning in European pediatric specialty centers where EXCOR platforms address neonatal mechanical support.
- Research Institutions:Academic medical centers conducting IDE trials and post-market surveillance.
- Ambulatory Surgical Centers:Limited VAD penetration due to implant complexity and regulatory constraints.
Cardiac surgery centers command the established base. The steepest expansion runs through specialty cardiac hospitals.
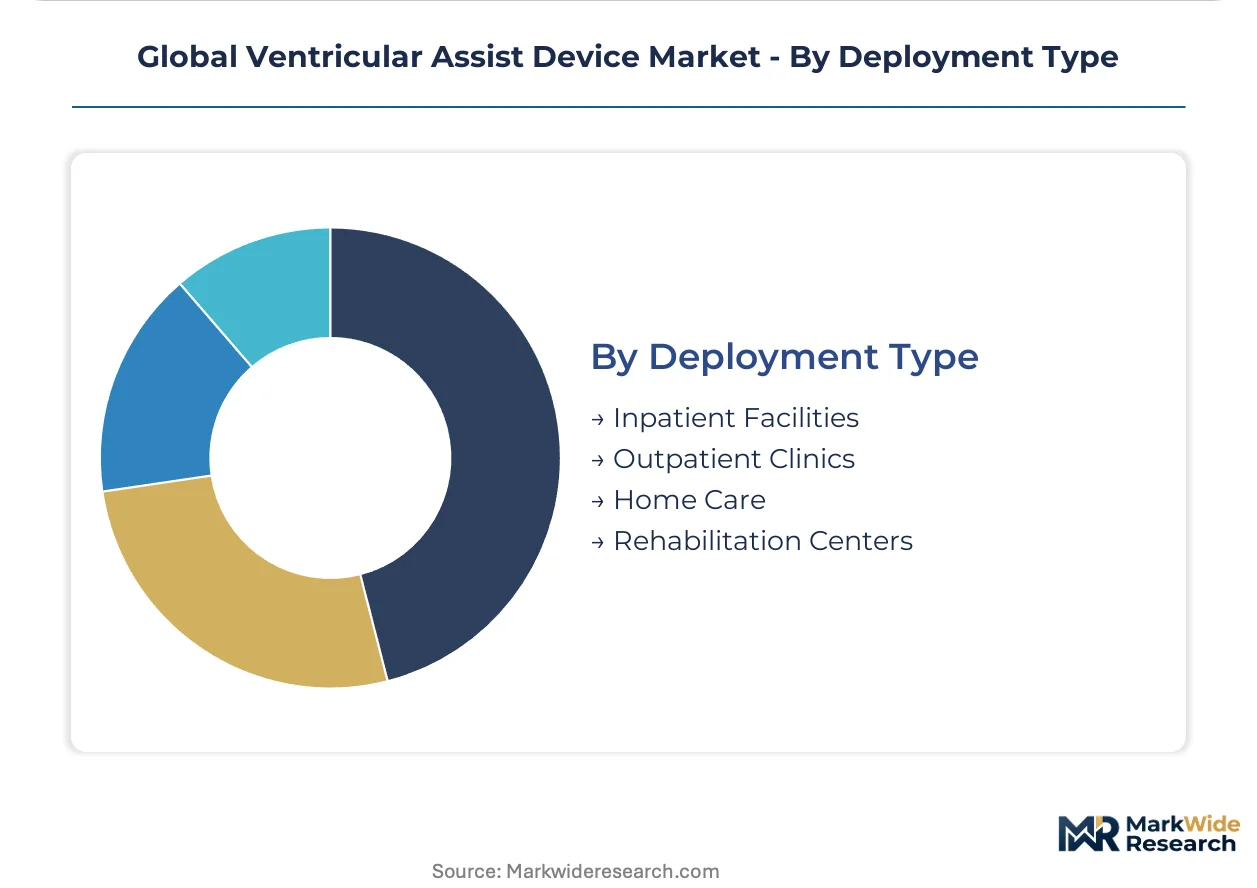
Deployment Type:
Volume concentration in inpatient facilities is giving way to outpatient and home-based models as controller portability and remote monitoring capabilities mature.
- Inpatient Facilities:Tertiary cardiac centers managing acute implantation, complications, and end-of-life transitions. Major clusters in Houston, Cleveland, Berlin, and Tokyo concentrate global implant volume and drive manufacturer clinical trial site selection.
- Outpatient Clinics:Specialized heart failure clinics managing stable VAD patients through scheduled monitoring and driveline care. Expansion in United States Medicare Advantage networks and German ambulatory cardiology practices.
- Home Care:Patient or caregiver-managed power systems and alarm response with telemedicine backup.
- Rehabilitation Centers:Post-acute physical therapy and device education during VAD patient recovery.
Inpatient facilities command the established base. The steepest expansion runs through home care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where destination therapy reimbursement density sustains premium procurement, while Japanese and Indian markets operate on compressed margin structures tied to national health insurance fee schedules and cash-pay constraints.
United States
Cleveland Clinic and Houston Methodist anchor implant volume through expanded INTERMACS 4-7 eligibility criteria. FDA premarket approval requirements shape product development timelines and clinical evidence thresholds for all active manufacturers. Medicare Advantage networks in Texas and Ohio are piloting outpatient VAD management protocols that shift care delivery from tertiary centers to ambulatory settings.
Germany
German Heart Center Berlin and Heidelberg University Hospital concentrate European procedure volume through specialized heart failure programs. EU MDR technical documentation mandates filter out marginal device developers and consolidate procurement around established manufacturers with robust quality management systems. Bavaria and North Rhine-Westphalia are installing dedicated mechanical circulatory support infrastructure without legacy transplant center dependencies.
Japan
Tokyo and Osaka cardiac centers drive Asia-Pacific demand through PMDA sakigake designation pathway access for breakthrough VAD technologies. METI coordinates national health insurance reimbursement revisions that compress device pricing while accelerating regulatory review timelines. The Kanto region concentrates specialized surgical expertise and clinical trial site selection for manufacturers seeking Asian market entry.
India
Chennai, Hyderabad, and Mumbai are installing dedicated heart failure programs through greenfield hospital developments without legacy transplant center dependencies. CDSCO medical device regulations are harmonizing with ISO 14708-5 active implantable standards to streamline import clearance for established manufacturers. Maharashtra and Telangana are attracting cardiac surgery infrastructure investment through state-level healthcare privatization incentives.
Global Ventricular Assist Device Market Competitive Landscape
Concentration sits with diversified cardiovascular conglomerates controlling integrated structural heart portfolios. The vendor base organizes around three strategic archetypes: diversified medtech conglomerates with captive supply chain control, specialized mechanical circulatory support developers with pediatric niche expertise, and regional Asian manufacturers leveraging cost-advantaged production. Dominant competitive moves include backward integration into titanium-alloy component sourcing and technology licensing partnerships for magnetic levitation bearing systems.
Among diversified cardiovascular conglomerates, Abbott Laboratories and Medtronic exemplify the integrated-platform archetype through control across pump, controller, and driveline component supply chains. Berlin Heart GmbH occupies a distinct position within the specialized-developer tier, anchoring European market access through pediatric VAD expertise that larger competitors have not replicated.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Berlin Heart GmbH |
| Abiomed |
| Jarvik Heart, Inc. |
| SynCardia Systems |
| Terumo Corporation |
| Evaheart, Inc. |
| LivaNova |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day lead times for Grade 5 titanium pump housings concentrate procurement leverage among Japanese and Russian suppliers, compressing margin flexibility for centrifugal-flow platform developers while amplifying pricing power for axial-flow incumbents with captive inventory buffers. This inventory-to-pricing dynamic forces second-tier manufacturers toward consignment models that transfer obsolescence risk upstream.
Pricing Analysis
Configured-to-order pricing for magnetic levitation bearing systems commands a forty-to-sixty percent premium over standard mechanical bearing configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by INTERMACS patient acuity profile and bundled clinical engineering support intensity. Cost compression in economy-tier external VAD configurations is intensifying because Indian and Southeast Asian hospital buyers are consolidating procurement around transparent component-level pricing. Pediatric specialty centers in Germany and Japan exhibit the lowest price sensitivity due to non-substitutable EXCOR platform dependence.
Supply Chain Analysis
Seventy-five-day inventory cycles for biocompatible inflow cannula materials expose manufacturers to aerospace demand spikes that divert Grade 5 titanium allocations. Supply concentrates in Japan, Russia, and the United States for pump housing forgings, with controller electronics sourcing anchored in Taiwan and South Korea. Single-source vulnerability runs through specialized heparin coating applicators in Switzerland and Germany. Distribution runs through GPO-negotiated contracts with tertiary cardiac centers, though direct-to-hospital consignment models are displacing traditional distributor markups in German and United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in destination therapy eligibility expansion, where INTERMACS 4-7 patient volume is splintering procurement authority from transplant centers to community heart failure programs without legacy VAD infrastructure.
For Market Incumbents: Fortify controller firmware development capabilities against electromagnetic compatibility engineering constraints that ISO 14708-5 standards impose. Deepen backward integration into titanium-alloy component sourcing to offset Grade 5 supply concentration in Japan and Russia. Prioritize hospital system partnership density in Texas and Ohio where Medicare Advantage outpatient VAD management protocols are shifting care delivery models. For New Entrants and Emerging Players: Japan's PMDA sakigake designation offers accelerated regulatory review for breakthrough magnetic levitation platforms without requiring duplicate FDA evidentiary packages. Pediatric VAD specialization in European neonatal centers remains the most penetrable white-space segment given Berlin Heart GmbH's non-replicable EXCOR positioning. Target greenfield hospital developments in Chennai and Hyderabad with portable controller units that enable discharge protocols without transplant center dependencies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates with underutilized heart failure franchise assets in Minneapolis and Dublin. Long-term viability over the next decade hinges on magnetic levitation bearing system adoption curves and corresponding durability testing data. Watch INTERMACS registry adverse event definition harmonization across European and Japanese registries as the inflection signal for pooled safety analysis regulatory acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Levitation Platform Development | Eliminates mechanical bearing wear failure modes in continuous-flow pumps for destination therapy candidates. |
| PMDA Sakigake Pathway Submission | Accelerates Asian market entry for FDA-cleared devices through Japan's breakthrough designation review. |
| Home-Based Power Management Launch | Enables discharge protocols shifting care from Cleveland Clinic and Houston Methodist to outpatient settings. |
| Pediatric VAD Indication Expansion | Addresses transplant waitlist mortality in neonatal segments where Berlin Heart GmbH maintains specialized expertise. |
| EU MDR Technical Documentation Compliance | Filters marginal developers and consolidates German procurement around quality management system-certified manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VAD coordinators at Cleveland Clinic and Houston Methodist, biomedical engineers at German Heart Center Berlin, GPO contracts managers, and pediatric cardiac surgeons at Heidelberg University Hospital. Secondary validation drew from FDA premarket approval filings, PMDA sakigake designation records, INTERMACS registry outcome datasets, EU MDR technical documentation filings, and CMS Medicare reimbursement determinations. Bottom-up implant volume estimates triangulated against top-down market value reconstructions.
Across the analysis window, the forecasting framework modeled pump platform type, patient indication acuity, deployment setting, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from procedure volume trajectories weighted by reimbursement density and surgical infrastructure expansion timelines. Magnetic levitation adoption curves, destination therapy eligibility expansion rates, and titanium-alloy supply availability served as industry-specific forecast inputs.
Underlying assumptions cover INTERMACS profile distribution stability and payer coverage alignment, with deviation risk concentrated in FDA evidentiary standard evolution for durability testing and EU MDR notified body conformity assessment bandwidth constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market