
 Dual Therapy Stent Market | 2026-2036
Dual Therapy Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Therapy Stent Market Foresight
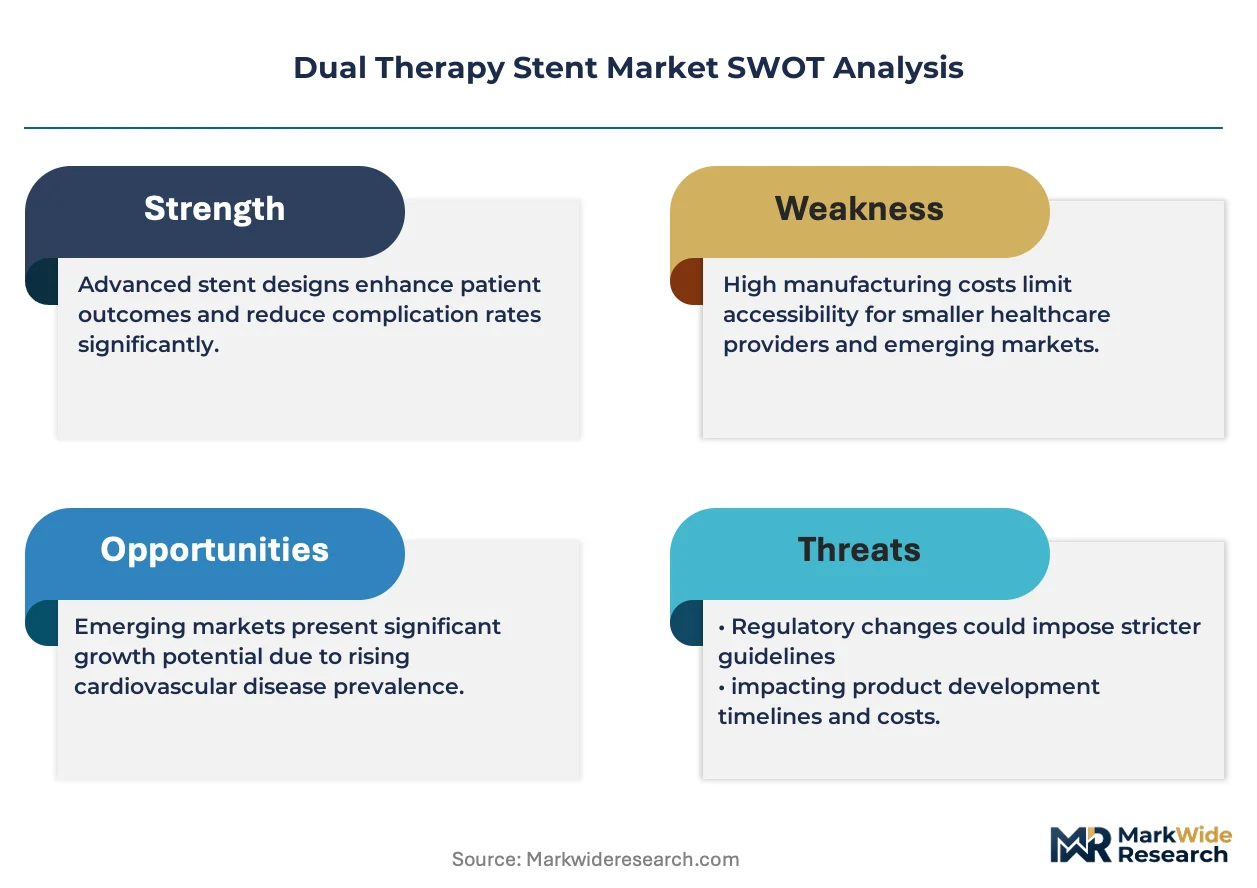
CE marking under the EU Medical Device Regulation is reorganizing which manufacturers can serve European patients. Abbott Laboratories leverages its vascular portfolio breadth to sustain clinical trial investment across dual therapy platforms. Boston Scientific Corporation anchors its position through specialized coronary interventional sales forces in key markets. Medtronic plc competes via integrated cath lab system offerings that bundle stent delivery with imaging guidance.
Dual Therapy Stents combine drug-eluting and bioresorbable technologies in a single endovascular scaffold, typically incorporating sirolimus analogues or everolimus within poly-lactic acid matrices that degrade over 24-36 months to restore natural vessel function. Their primary purpose is reducing both acute thrombosis and late restenosis in complex coronary lesions. Drug-eluting stents occupy the mature revenue base while hybrid stents represent the fastest-growing segment as clinicians seek tailored polymer degradation profiles. Coronary artery disease applications dominate procedure volumes, though peripheral artery disease indications are widening addressable patient pools through below-the-knee approvals.
The FDA premarket approval process and EMA's Medical Device Regulation both enforce stringent clinical evidence thresholds for combination product stents, directly shaping R&D budgets and launch timelines. Japan's PMDA adds a separate layer of domestic trial requirements that filters market access for non-Japanese manufacturers. Stakeholders must monitor how evolving MDR notified body capacity in Europe and FDA breakthrough device designations alter competitive speed-to-market for next-generation platforms.
Market Dynamics
Polymer degradation engineering now dictates competitive positioning in dual therapy stent development, as manufacturers race to tune sirolimus release kinetics against vessel healing timelines. The FDA's premarket approval pathway for combination device-drug products compresses launch windows for firms with robust clinical data packages.
Growth Catalysts
- Complex coronary lesion prevalence:Aging demographics in Germany and Japan expand the addressable patient pool for multi-layered revascularization solutions. Cardiac clinics in these markets prioritize platforms reducing repeat intervention rates.
- MDR notified body capacity expansion:CE marking under the EU Medical Device Regulation is streamlining market access for manufacturers with established quality management systems. European patients gain faster access to next-generation scaffolds.
- Below-the-knee peripheral approvals:Expanded indications for infrapopliteal artery disease are opening new procedure volumes outside traditional coronary applications. Interventional cardiologists in the United States are cross-training for peripheral interventions.
Market Restraints
- Platinum-iridium alloy cost volatility:Stent radiopacity requirements tie manufacturers to precious metal markets subject to supply concentration in South Africa and Russia. Input price swings compress gross margins on standard device tiers.
- PMDA domestic trial mandates:Japan's pharmaceutical regulator requires Japan-specific clinical evidence for combination product approval, filtering market access for non-Japanese manufacturers. Duplicative trial infrastructure inflates R&D budgets.
- Balloon angioplasty resurgence:Drug-coated balloon technology is capturing select lesion subsets previously stented, particularly in small vessel disease. Interventionalists weigh restenosis rates against permanent implant risks.
Strategic Opportunities
- India cath lab infrastructure buildout:Government-funded cardiac care expansion in tier-2 cities creates first-mover advantages for stent manufacturers with localized pricing strategies. Private hospital chains are consolidating procurement.
- Bioresorbable-polymer convergence:Integration of tyrosine-derived polycarbonate with everolimus matrices enables tunable 18-month degradation profiles. Research consortia in Switzerland and the Netherlands are advancing preclinical platforms.
- FDA breakthrough device designation:Expedited review pathways for novel scaffold designs compress time-to-revenue for innovators with compelling early-phase data. Designation signals credibility to hospital value analysis committees.
Industry Challenges
- Polymer chemistry talent scarcity:Specialized expertise in biodegradable material science concentrates in academic medical centers and select contract research organizations. Manufacturers compete for limited formulation scientists.
- MDR technical documentation burden:The EU Medical Device Regulation demands exhaustive clinical evaluation reports and post-market surveillance systems. Smaller firms face compliance timeline compression.
- Legacy stent inventory obsolescence:Hospital cath labs must manage device shelf-life against rapid generational turnover in dual therapy platforms. Capital allocation between inventory and new technology adoption strains procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Therapy Stent Market |
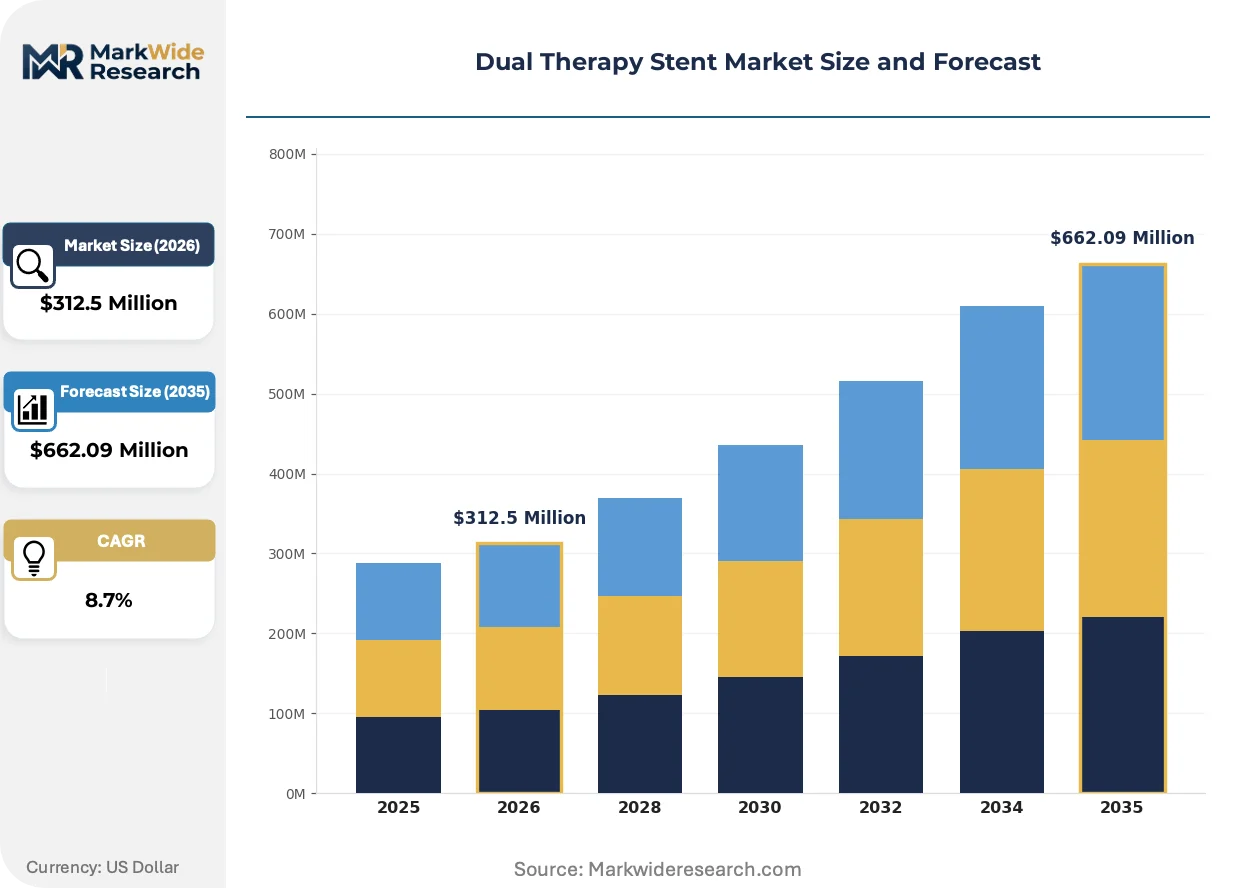
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DES, BRS, Hybrid Stents, Bare Metal Stents Application: Coronary Artery Disease, Peripheral Artery Disease, Drug Eluting Indication, Patients with Diabetes End User: Hospitals, Cardiac Clinics, Outpatient Surgery Centers, Research Institutions Delivery Mode: Transluminal, Intracoronary, Percutaneous, Surgical Intervention |
| Companies Covered | Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, Biosensors International Group Ltd., Terumo Corporation, Biotronik SE & Co. KG, MicroPort Scientific Corporation, Lepu Medical Technology, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Therapy Stent Market Shifts & Advancements
Endovascular scaffold engineering is pivoting toward patient-specific lesion matching, with polymer degradation profiles now calibrated to individual vessel healing trajectories rather than population averages. This shift is compressing development cycles and reshaping clinical trial design.
Strut thickness reduction is miniaturizing. Ultra-thin cobalt-chromium platforms below 60 micrometers maintain radial force while improving deliverability in tortuous anatomy. Interventional cardiologists in Japan and Germany are adopting these profiles for calcified lesions previously requiring rotational atherectomy. The technology is miniaturizing access requirements and expanding same-day discharge eligibility.
CE marking under the EU Medical Device Regulation is reorganizing competitive entry. The MDR's heightened clinical evidence requirements and notified body capacity constraints are extending approval timelines for combination products. European manufacturers with legacy device portfolios face retrospective clinical data generation burdens, while new entrants invest in prospective trial infrastructure.
Hospital value analysis committees are consolidating stent procurement across multi-hospital systems. United States health systems now negotiate enterprise-wide contracts spanning coronary and peripheral portfolios, displacing physician-preference purchasing. This concentration is most visible in the southeastern United States, where Catholic health networks and for-profit chains dominate interventional cardiology service line planning.
Dual Therapy Stent Market Segmentation
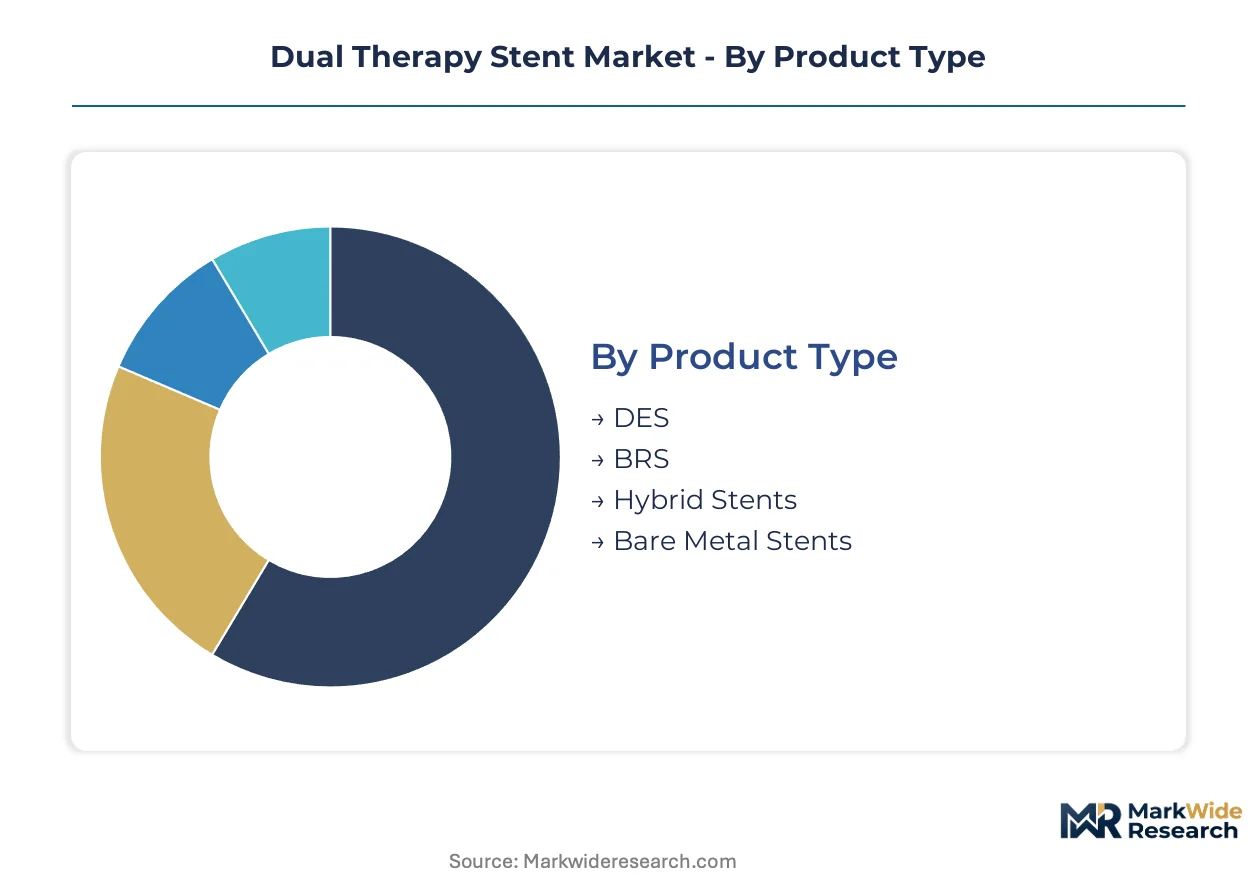
Dual therapy stent manufacturers navigate distinct regulatory pathways and clinical use cases across product architectures. Segmentation reveals where polymer engineering investments concentrate and which patient populations drive procedure economics.
Product Type:
FDA premarket approval timelines diverge sharply between permanent implants and bioresorbable platforms, compressing competitive windows for combination products.
- DES:Sirolimus and everolimus matrices within durable polymer coatings dominate current procedure volumes. Cardiac clinics in the United States prioritize these platforms for their established restenosis data and streamlined reimbursement pathways.
- BRS:Poly-l-lactic acid scaffolds degrade over 24-36 months to restore natural vessel function. Japan's PMDA domestic trial mandates filter market access, concentrating adoption in Germany and Switzerland where CE marking under MDR has streamlined entry.
- Hybrid Stents:Tunable degradation profiles combining drug-elution with bioresorbable backbones.
- Bare Metal Stents:Cobalt-chromium platforms without pharmacological coating for cost-sensitive acute interventions.
Established volume favors DES; emerging adoption favors BRS.
Application:
Procedure reimbursement tiers separate coronary from peripheral indications, with below-the-knee approvals commanding premium positioning.
- Coronary Artery Disease:Complex lesion subsets in aging populations drive multi-vessel revascularization demand. German interventional cardiology centers report highest per-capita utilization rates for multi-layered scaffolds.
- Peripheral Artery Disease:Infrapopliteal artery disease approvals are widening addressable patient pools outside traditional cardiac applications. United States clinicians are cross-training for below-the-knee interventions as hospital systems consolidate peripheral service lines.
- Drug Eluting Indication:Specific pharmacological coating approvals for high-risk lesion morphologies.
- Patients with Diabetes:Accelerated restenosis risk profiles requiring tailored polymer degradation kinetics.
Coronary procedures anchor current revenue; peripheral indications are climbing the fastest.
End User:
Capital equipment requirements and cath lab infrastructure determine which settings can support dual therapy platform adoption.
- Hospitals:Enterprise-wide procurement contracts spanning coronary and peripheral portfolios concentrate purchasing power. Southeastern United States health systems negotiate multi-hospital agreements displacing physician-preference purchasing.
- Cardiac Clinics:Specialized interventional facilities in Germany and Japan prioritize platforms reducing repeat intervention rates. These settings drive adoption of next-generation scaffolds with tunable degradation profiles.
- Outpatient Surgery Centers:Same-day discharge eligibility requirements favor ultra-thin strut platforms below 60 micrometers.
- Research Institutions:Academic medical centers with polymer chemistry expertise conduct preclinical bioresorbable-polymer convergence studies.
Hospital procurement dominates transaction volume; cardiac clinics are gaining share fastest for premium platforms.
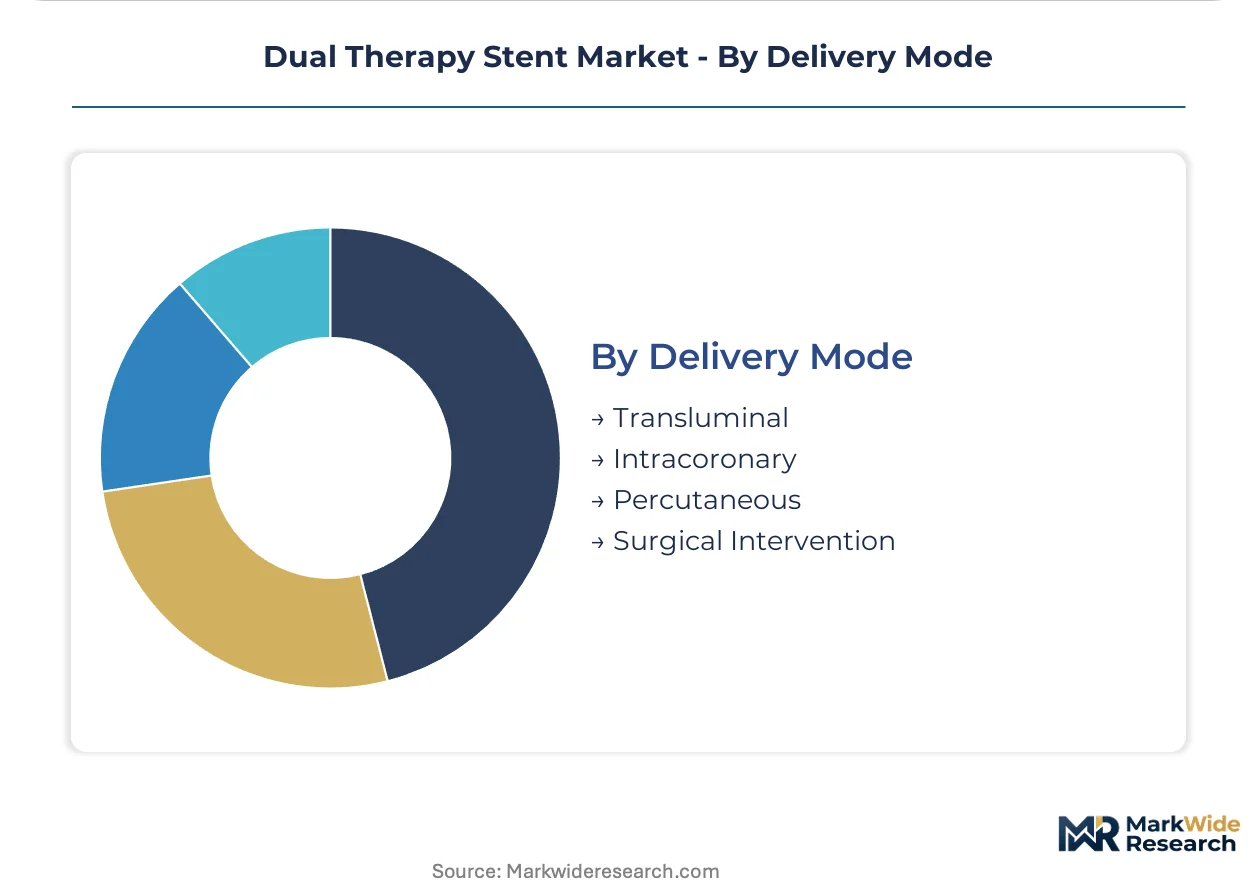
Delivery Mode:
Access route selection shapes device deliverability specifications and operator training requirements.
- Transluminal:Femoral and radial access approaches for standard percutaneous coronary intervention workflows.
- Intracoronary:Direct vessel engagement for calcified lesions requiring rotational atherectomy adjuncts.
- Percutaneous:Minimally invasive entry methods expanding same-day discharge eligibility across United States ambulatory settings.
- Surgical Intervention:Hybrid operating room environments for complex multi-vessel disease requiring concomitant procedures.
Percutaneous delivery anchors procedure volume; transluminal approaches retain preference in established cardiac centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded cardiac care expansion and streamlined regulatory pathways are reshaping geographic demand patterns for dual therapy stents. Reimbursement tiers and cath lab infrastructure density separate mature markets from emerging adoption zones.
United States
Hospital value analysis committees now negotiate enterprise-wide contracts spanning coronary and peripheral portfolios, displacing physician-preference purchasing across southeastern health systems. The FDA's premarket approval pathway for combination device-drug products compresses launch windows for firms with robust clinical data packages. Interventional cardiologists in Cleveland Clinic and Mayo Clinic settings drive adoption of ultra-thin strut platforms.
Germany
Interventional cardiology centers report highest per-capita utilization rates for multi-layered scaffolds treating complex lesion subsets. CE marking under the EU Medical Device Regulation streamlines market access for manufacturers with established quality management systems. The Munich-Berlin corridor concentrates polymer chemistry research consortia advancing bioresorbable-polymer convergence studies.
Japan
Aging demographics expand the addressable patient pool for multi-layered revascularization solutions in cardiac clinics prioritizing platforms reducing repeat intervention rates. The PMDA domestic trial mandates filter market access for non-Japanese manufacturers, concentrating adoption among established local partners. Tokyo-Osaka metropolitan areas anchor cath lab infrastructure supporting premium stent uptake.
India
Government-funded cardiac care expansion in tier-2 cities creates first-mover advantages for stent manufacturers with localized pricing strategies. The CDSCO regulatory framework governs combination product approvals while private hospital chains consolidate procurement. Maharashtra and Gujarat private hospital networks are expanding interventional cardiology service lines fastest.
Switzerland
Research consortia in Basel and Zurich academic medical centers advance preclinical platforms integrating tyrosine-derived polycarbonate with everolimus matrices. Swissmedic maintains stringent clinical evidence thresholds that align with EMA MDR requirements for combination products. The country's polymer chemistry talent concentration supports biodegradable material science innovation pipelines.
Dual Therapy Stent Market Competitive Landscape
Player mix skews toward diversified cardiovascular device conglomerates with integrated cath lab system offerings. The vendor base concentrates around three strategic archetypes: broad vascular portfolio holders, specialized coronary interventional firms, and integrated imaging-guidance bundlers. Competitive moves center on clinical trial infrastructure investment and M&A targeting polymer chemistry capabilities.
Within the diversified cardiovascular conglomerate tier, Abbott Laboratories, Medtronic plc, and Boston Scientific Corporation exemplify scale-driven positions. Abbott leverages vascular portfolio breadth to sustain clinical trial investment across dual therapy platforms. Medtronic competes via integrated cath lab system offerings that bundle stent delivery with imaging guidance. Boston Scientific anchors its position through specialized coronary interventional sales forces in key markets. These three represent the archetype of full-stack cardiovascular device manufacturers competing on integrated service line capture rather than single-product positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Boston Scientific Corporation |
| Biosensors International Group Ltd. |
| Terumo Corporation |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| Lepu Medical Technology |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
FDA premarket approval pathways for combination device-drug products simultaneously gate supply qualification and price differentiation, compressing competitive windows for manufacturers lacking robust clinical data packages while amplifying premiums for certified tiers.
Pricing Analysis
Certification level (FDA-grade/CE marking/Japan PMDA-compliant) creates the primary spread between premium dual therapy stents and standard drug-eluting platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by polymer degradation profile and clinical evidence depth. Pricing pressure stems from balloon angioplasty resurgence in small vessel disease, squeezing margins on mid-tier devices. Cardiac clinics in Germany and Japan show lowest price sensitivity, prioritizing repeat intervention reduction over per-procedure cost.
Supply Chain Analysis
South Africa and Russia anchor platinum-iridium alloy supply for stent radiopacity requirements, while Germany and Switzerland concentrate polymer chemistry formulation capabilities. Manufacturers draw from poly-l-lactic acid suppliers in the Netherlands and cobalt-chromium strut fabricators in the United States. Single-source vulnerability in precious metal markets exposes margin compression from geopolitical supply disruptions. Distribution runs through hospital value analysis committees and GPO contracts rather than physician-direct purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual therapy stent market fragmentation creates opportunity as hospital procurement consolidation and lesion-specific polymer engineering multiply addressable niches beyond incumbent strongholds.
For Market Incumbents: Consolidate polymer chemistry capabilities through targeted capability acquisition in Switzerland and Netherlands research consortia. Deepen backward integration into bioresorbable polymer supply to defend against tyrosine-derived polycarbonate shortages. Lock in long-term platinum-iridium offtake agreements before South African supply volatility intensifies. For New Entrants and Emerging Players: Differentiate on tunable degradation profiles for diabetic patient subsets currently underserved by population-average polymer kinetics. Target tier-2 Indian cities where government-funded cath lab buildout outpaces established manufacturer pricing adaptation. Pursue CDSCO fast-track pathways with localized clinical evidence generation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bioresorbable scaffold segments as MDR clinical documentation burdens and PMDA domestic trial mandates compound R&D infrastructure requirements. Acquisition targets center on mid-scale polymer formulation specialists with existing notified body relationships. Watch FDA breakthrough device designation velocity as inflection signal for platform credibility and time-to-revenue compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses launch timelines for novel scaffold designs with compelling early-phase data. |
| CE Marking Pathway Investment | MDR notified body capacity expansion accelerates European market access for quality-system-ready manufacturers. |
| Hospital System Partnership | Enterprise-wide procurement contracts in southeastern United States displace physician-preference purchasing concentration. |
| Polymer Chemistry Acquisition | Specialized biodegradable material science expertise concentrates in Swiss and Dutch academic medical centers. |
| Reimbursement Strategy | Below-the-knee peripheral indications command premium positioning through expanded procedure reimbursement tiers. |
Research Methodology
Desk research of FDA premarket approval filings, EMA Medical Device Regulation technical documentation, and PMDA clinical trial registries preceded structured interviews with interventional cardiologists, hospital purchasing committee directors, polymer chemistry R&D leads, and cath lab operations managers. Secondary validation drew from SEC 10-K cardiovascular segment disclosures, CMS Medicare procedure databases, and GPO contract repositories. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across product type, application, end user, and delivery mode segmentation dimensions drove analytical framework construction over the projection horizon. CAGRs derived from procedure volume elasticity to aging demographic penetration and regulatory approval velocity. Forecast inputs incorporated platinum-iridium price volatility scenarios and MDR notified body capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained CE marking streamlining or PMDA trial requirement relaxation would require recalibration. Forecasts reflect assumptions of stable reimbursement pathways and cath lab infrastructure buildout continuity. Recalibration cycles align with material shifts in FDA breakthrough designation patterns and polymer degradation engineering breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Interventional Cardiology Market