
 Inotropic Agent Market | 2026-2036
Inotropic Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Inotropic Agent Market Analysis
The gap between premium biologic inotropes and commodity generic sympathomimetics is shifting as hospital formularies tighten reimbursement tiers. Pfizer Inc. leverages its manufacturing scale to dominate the milrinone supply chain for intensive care units. GSK plc anchors its position through sustained R&D investment in cardiac-renal comorbidity protocols. Novartis AG differentiates via specialized distribution networks for post-operative care settings.
Inotropic agents are pharmacological compounds that modulate myocardial contractility through calcium sensitization or cyclic AMP pathway activation, typically administered as intravenous infusions with precise titration parameters for acute hemodynamic stabilization. The dobutamine segment occupies the largest volume share due to its established role in low-output heart failure, while milrinone generates disproportionate margin contribution from its phosphodiesterase-III inhibition profile in postcardiotomy shock. Cardiology clinics represent the fastest-growing end-user channel as ambulatory inotropic therapy programs expand for chronic heart failure management.
The FDA enforces stringent cardiovascular outcome study requirements under its ICH E14 guidance, compelling sponsors to demonstrate arrhythmia safety profiles before approval. EMA's MDR framework and the EU F-Gas Regulation govern device-drug combination delivery systems and inhalation propellant standards respectively. Stakeholders must monitor evolving pharmacovigilance mandates and therapeutic substitution policies that will determine portfolio prioritization across acute and chronic care settings.
Market Dynamics
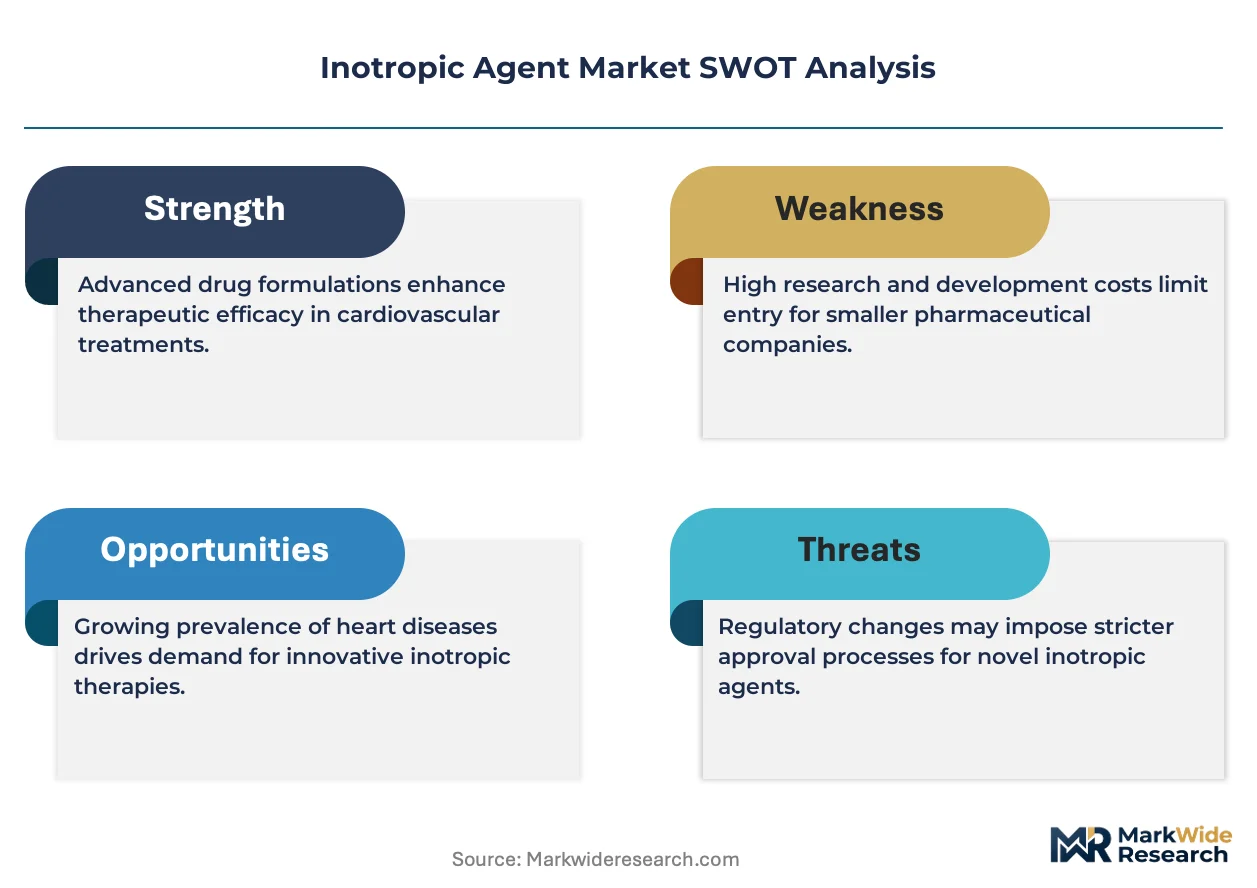
Hospital formulary consolidation is compressing margins for intravenous inotropes as pharmacy and therapeutics committees enforce stricter tiered reimbursement protocols across acute cardiac care settings.
Growth Catalysts
- Aging Demographics:The United States population aged 65 and above is expanding rapidly, sustaining demand for acute hemodynamic stabilization in coronary care units and cardiac surgery recovery wards.
- ICH E14 Guidance:The FDA's arrhythmia safety requirements have paradoxically strengthened sponsor confidence by establishing clear cardiovascular outcome study benchmarks for new molecular entities.
- Phosphodiesterase-III Inhibition:Milrinone's established efficacy in postcardiotomy shock continues to drive utilization in open-heart surgery protocols, particularly across advanced catheterization laboratory networks.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for milrinone and dobutamine concentrates in a limited number of specialized chemical synthesis facilities, creating vulnerability to single-source disruptions.
- EU F-Gas Regulation:Inhalation propellant standards for device-drug combination delivery systems impose compliance burdens on nebulized inotropic formulations, limiting product line extensions.
- Generic Substitution Pressure:Commodity sympathomimetics face aggressive therapeutic substitution policies from pharmacy benefit managers, eroding branded product viability in chronic heart failure management.
Strategic Opportunities
- Cardiology Clinic Expansion:Ambulatory inotropic therapy programs represent underpenetrated territory for chronic heart failure management, with specialized infusion centers emerging in suburban United States markets.
- Cardiac-Renal Comorbidity Protocols:Integrated treatment pathways addressing simultaneous heart and kidney dysfunction create demand for precision-dosed inotropic regimens with biomarker-guided titration.
- EMA MDR Framework:The Medical Device Regulation's emphasis on clinical evidence for combination products incentivizes investment in smart infusion pump compatibility, differentiating premium formulations.
Industry Challenges
- Clinical Pharmacist Shortage:Specialized expertise in hemodynamic monitoring and vasoactive titration is scarce across intensive care units, constraining safe expansion of inotropic therapy programs.
- Legacy EMR Integration:Electronic medical record systems in older United States hospital networks lack interoperability with modern infusion pump data streams, complicating adverse event documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inotropic Agent Market |
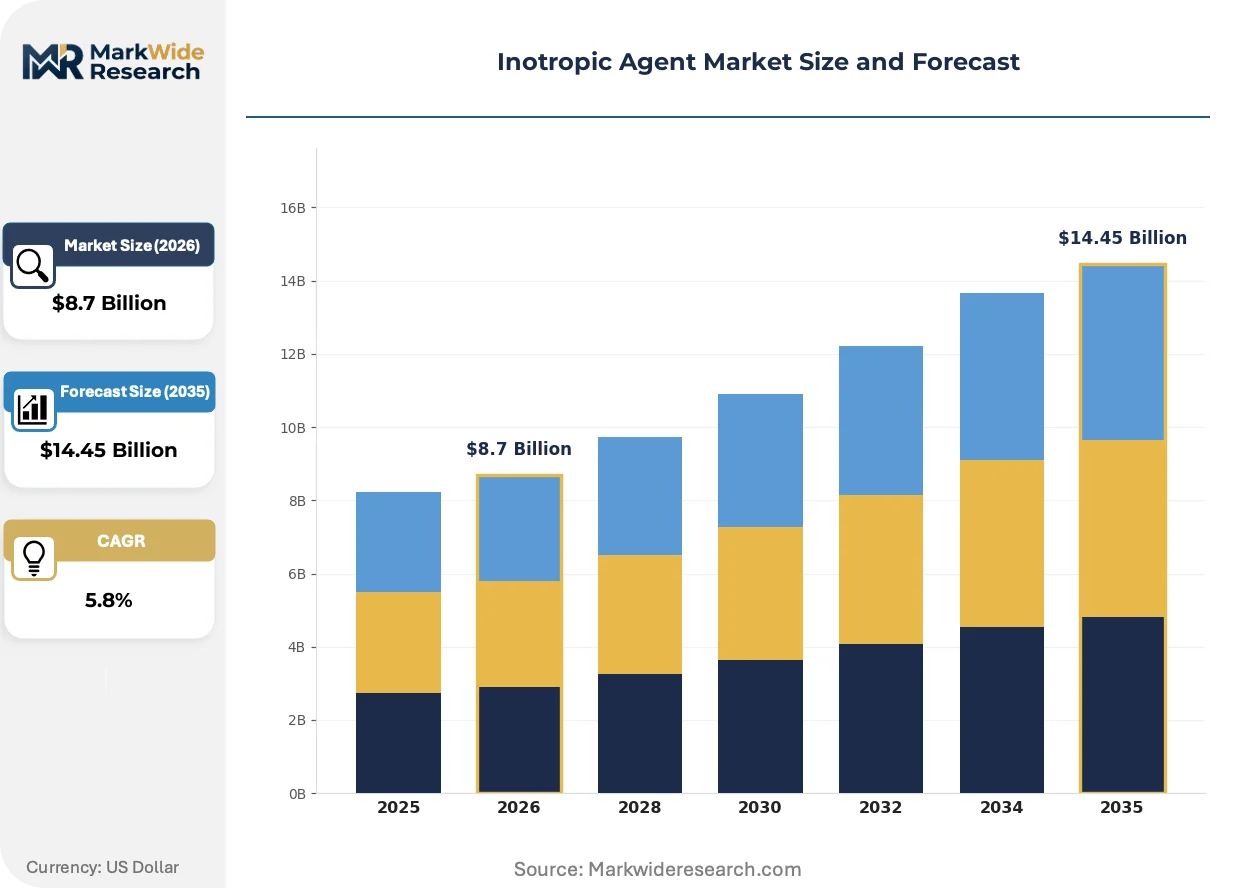
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dobutamine, Dopamine, Milrinone, Isoproterenol End User: Hospitals, Cardiology Clinics, Rehabilitation Centers, Emergency Services Therapy Area: Cardiac Arrest, Heart Failure, Shock, Post-Operative Care Administration Route: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Pfizer Inc., GSK plc, Novartis AG, Boehringer Ingelheim International GmbH, AstraZeneca, Bristol-Myers Squibb Company, Merck & Co., Bayer AG, Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inotropic Agent Market Emerging Trajectories
Digital health integration is reconfiguring how inotropic therapies are monitored, dosed, and reimbursed, with real-time hemodynamic data streams becoming central to clinical decision support.
Closed-loop infusion systems with integrated arterial pressure and cardiac output sensors are automating titration protocols previously managed by bedside nurses. Cardiac surgery units in tertiary United States hospitals are piloting these platforms for postcardiotomy shock management. The technology is automating dose adjustments every 15-60 seconds, compressing recovery timelines and reducing pharmacist intervention frequency.
EMA's MDR framework now mandates post-market clinical follow-up for all device-drug combination delivery systems, including infusion pumps used for inotropic administration. Manufacturers must submit periodic safety update reports with real-world evidence on arrhythmia incidence. European hospital procurement committees are prioritizing MDR-certified pump systems, forcing formulary reevaluations of legacy device pairings.
Hospital systems are consolidating pharmaceutical purchasing through centralized pharmacy and therapeutics committees with delegated authority from individual facility formularies. Independent community hospitals are ceding autonomy to integrated delivery networks with standardized protocols. This concentration is most visible across United States metropolitan markets where Catholic health systems and for-profit chains dominate acute cardiac care capacity.
Inotropic Agent Market Segmentation
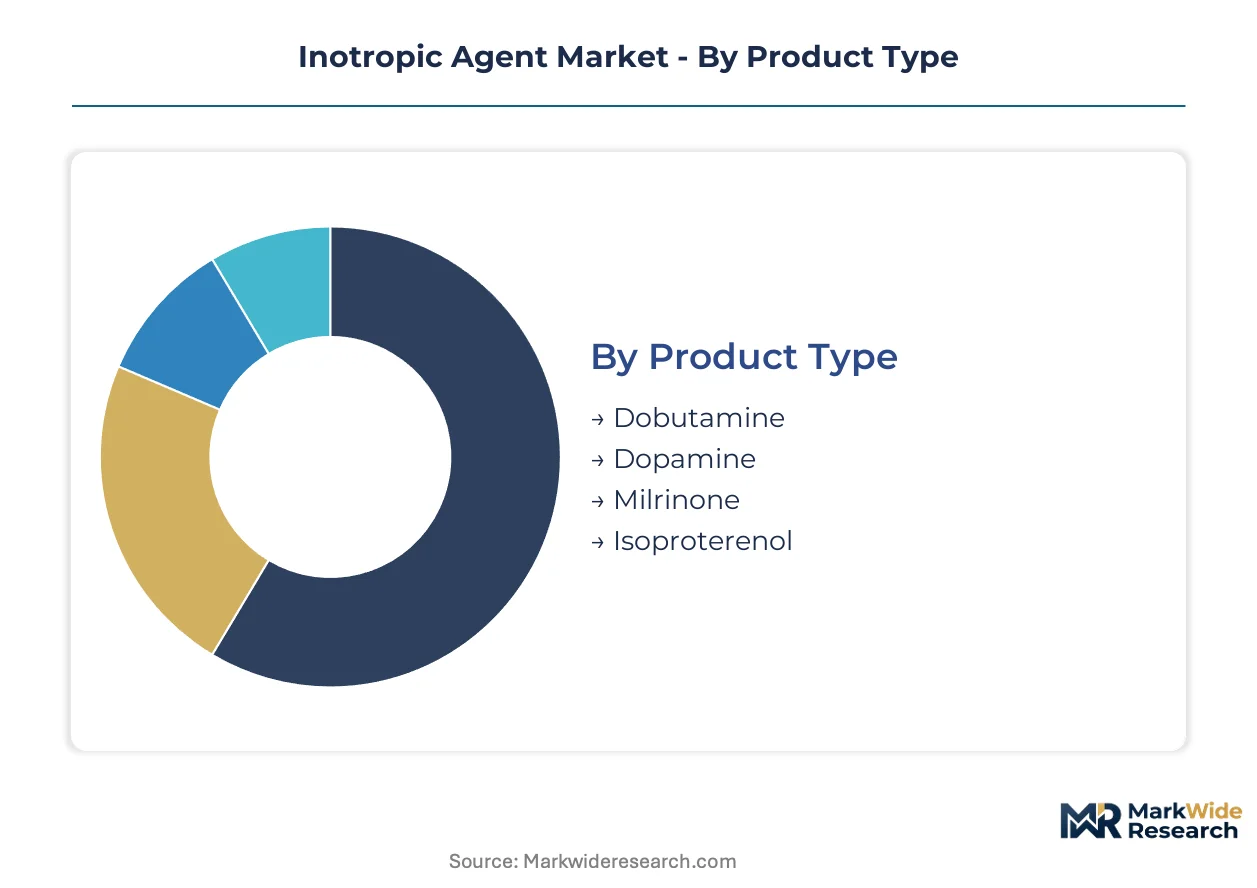
Inotropic agents fragment across pharmacological classes, care settings, and delivery methods that each carry distinct regulatory burdens. Segmentation reveals where FDA cardiovascular outcome requirements and EMA device-drug combination rules concentrate compliance costs.
Product Type:
FDA ICH E14 arrhythmia safety guidance applies differentially across sympathomimetic and phosphodiesterase inhibitor classes, with new molecular entities facing distinct cardiovascular outcome study thresholds.
- Milrinone:Phosphodiesterase-III inhibitor with established postcardiotomy shock efficacy. Demand concentrates in United States tertiary cardiac surgery centers where cath lab infrastructure supports precise hemodynamic monitoring and automated infusion protocols.
- Dobutamine:Beta-1 adrenergic agonist administered via continuous intravenous infusion with established low-output heart failure protocols. United States coronary care units sustain high utilization rates through standardized titration algorithms and pharmacist-driven dosing programs.
- Dopamine:Catecholamine precursor with dose-dependent receptor activity spanning alpha, beta, and dopaminergic effects. Renal perfusion dosing protocols in septic shock management.
- Isoproterenol:Non-selective beta agonist reserved for bradyarrhythmia and torsades de pointes. Limited production runs due to narrow therapeutic index.
Dobutamine sits at the top of the volume ranking, with milrinone climbing the fastest through premium pricing in surgical recovery protocols.
End User:
Cost tier stratification separates acute inpatient reimbursement from emerging ambulatory payment models.
- Hospitals:Intensive care units and cardiac surgery wards dominate acute hemodynamic stabilization with centralized pharmacy and therapeutics committee oversight. United States integrated delivery networks enforce tiered formulary protocols that compress generic sympathomimetic margins.
- Cardiology Clinics:Ambulatory inotropic therapy programs with specialized infusion centers. Suburban United States markets expanding chronic heart failure management outside traditional hospital walls.
- Rehabilitation Centers:Post-acute transition facilities with limited vasoactive titration expertise. Standardized weaning protocols for step-down care.
- Emergency Services:Pre-hospital cardiac arrest and shock management with constrained monitoring capabilities. Protocol-driven bolus administration.
Hospitals retain the dominant revenue position, while cardiology clinics gain share fastest through Medicare reimbursement shifts toward site-neutral payment.
Therapy Area:
Application severity determines whether EMA MDR post-market clinical follow-up requirements trigger for device-drug combinations.
- Heart Failure:Chronic low-output states with guideline-directed medical therapy escalation. United States aging demographics sustain demand for acute decompensation management.
- Post-Operative Care:Cardiac surgery recovery with postcardiotomy shock protocols. Tertiary centers in United States metropolitan markets deploy automated closed-loop titration systems.
- Shock:Septic, cardiogenic, and distributive etiologies requiring rapid hemodynamic restoration. Emergency department and ICU convergence.
- Cardiac Arrest:Advanced cardiovascular life support algorithms with epinephrine co-administration. Resuscitation protocol standardization.
Heart failure commands the largest addressable population, with post-operative care showing the steepest expansion trajectory through surgical volume recovery.
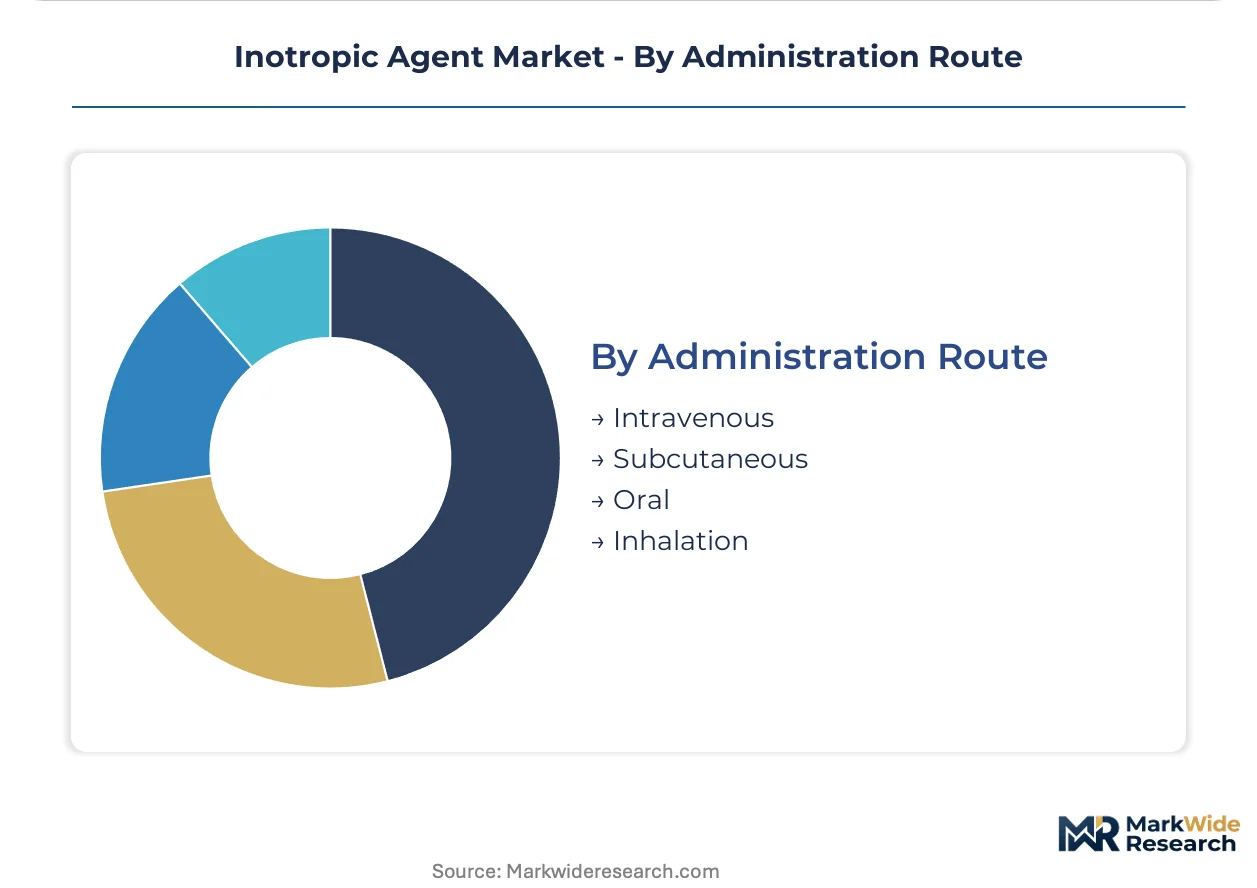
Administration Route:
Supply concentration varies sharply between infusion pump-dependent delivery and emerging nebulized formulations facing EU F-Gas Regulation constraints.
- Intravenous:Continuous infusion with precise titration parameters and arterial line monitoring. United States hospital formularies standardize on smart pump interoperability with electronic medical record systems.
- Subcutaneous:Emerging chronic heart failure ambulatory programs with patient-administered bolus protocols. Cardiology clinic expansion in suburban markets.
- Oral:Limited bioavailability for chronic inotropic support. Digoxin legacy positioning outside acute care.
- Inhalation:Nebulized delivery for pulmonary hypertension and right ventricular failure. EU F-Gas Regulation propellant standards constrain product line extensions.
Intravenous delivery maintains absolute volume dominance, with subcutaneous routes expanding most quickly through ambulatory therapy program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac intensivists and specialized infusion pharmacists concentrate in tertiary hospital clusters across mature healthcare systems. Their expertise anchors regional utilization patterns for intravenous inotropic protocols.
United States
Aging demographics and advanced catheterization laboratory infrastructure sustain acute hemodynamic stabilization demand. FDA ICH E14 guidance shapes cardiovascular outcome study requirements for new molecular entities. The Cleveland Clinic and Mayo Clinic cardiac surgery networks deploy automated closed-loop milrinone titration systems.
Germany
Postcardiotomy shock management protocols in university hospitals drive phosphodiesterase-III inhibitor utilization. EMA MDR framework mandates post-market clinical follow-up for device-drug combination infusion pumps. The Heidelberg and Berlin-Brandenburg cardiac surgery clusters standardize on MDR-certified smart pump systems.
Japan
PMDA cardiovascular safety requirements align with ICH E14 arrhythmia guidance for new inotropic approvals. METI industrial policy supports domestic pharmaceutical manufacturing resilience. The Tokyo-Kanto region's university hospitals maintain high dobutamine utilization rates in coronary care units.
Switzerland
Swissmedic precision-dosing standards reinforce demand for biomarker-guided inotropic titration. The country's pharmaceutical manufacturing heritage sustains active pharmaceutical ingredient synthesis capabilities. Basel and Zurich hospital networks integrate cardiac-renal comorbidity protocols into chronic heart failure management.
United Kingdom
NHS England site-neutral payment reforms accelerate ambulatory inotropic therapy program expansion. MHRA post-Brexit regulatory autonomy maintains alignment with EMA pharmacovigilance standards. London and Manchester integrated care systems pilot suburban cardiology clinic infusion centers.
Inotropic Agent Market Vendor Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light specialty distributors across the inotropic agent supply chain. The market structure concentrates around three tiers: integrated multinationals with captive API synthesis, regional hospital formulary specialists, and commodity generic sympathomimetic suppliers. Dominant competitive moves include manufacturing scale consolidation and therapeutic substitution defense through smart infusion pump compatibility certification.
Among integrated pharmaceutical multinationals, Pfizer Inc. and GSK plc occupy positions exemplifying scale-driven manufacturing archetypes. Novartis AG sits within the specialized distribution tier, anchoring post-operative care channel positioning. These three entities represent contrasting strategic postures: manufacturing depth versus therapeutic protocol integration versus niche channel control.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Merck & Co. |
| Bayer AG |
| Cipla Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital pharmacy and therapeutics committees in United States integrated delivery networks enforce contract-based long-term offtake agreements that compress margins for generic sympathomimetics while preserving premium pricing for phosphodiesterase-III inhibitors with smart pump compatibility certification.
Pricing Analysis
Drug-device bundled service contracts separate premium milrinone formulations with automated titration support from commodity dobutamine supplied under basic infusion protocols. Price differentiation hinges on FDA ICH E14 arrhythmia safety documentation and EMA MDR-certified pump interoperability. Pricing pressure stems from therapeutic substitution policies aggressively promoted by pharmacy benefit managers. Chronic heart failure ambulatory programs exhibit highest price sensitivity; postcardiotomy shock protocols in tertiary cardiac surgery centers demonstrate lowest sensitivity due to outcome-based reimbursement.
Supply Chain Analysis
Cold chain logistics and specialized freight handling for intravenous inotropic formulations elevate distribution costs for cardiology clinic networks outside metropolitan hospital clusters. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland for milrinone and dobutamine hydrochloride. Manufacturing rests on concentrated pyridine derivative and catecholamine precursor feedstocks. Single-source vulnerability pervades phosphodiesterase-III inhibitor API production. Distribution runs through specialty pharmaceutical wholesalers with GMP-certified warehousing for temperature-controlled biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inotropic agent market compounds steadily as aging demographics in developed economies sustain procedural volume in cardiac surgery and acute decompensated heart failure management.
For Market Incumbents: Deepen backward integration into phosphodiesterase-III inhibitor API synthesis to insulate against single-source disruption risks from Indian and Chinese chemical manufacturers. Expand MDR-certified smart pump compatibility programs to defend formulary positioning against generic substitution pressure from pharmacy benefit managers. For New Entrants and Emerging Players: Closed-loop automated titration algorithms with integrated hemodynamic sensors offer a technology-first wedge into postcardiotomy shock management protocols at United States tertiary cardiac surgery centers. Target suburban cardiology clinic infusion centers for chronic heart failure ambulatory programs. Pursue hospital-at-home reimbursement pathway partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Integrated delivery networks with centralized pharmacy and therapeutics committees are the most active acquirer in this space, consolidating community hospital formularies under standardized protocols. Long-term viability centers on positioning for chronic heart failure ambulatory expansion rather than acute inpatient share capture. Monitor Medicare site-neutral payment reform implementation as the critical inflection signal for ambulatory therapy program economics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR-Certified Pump Compatibility Program | EMA post-market clinical follow-up mandates force formulary reevaluations of legacy device pairings in European hospital procurement. |
| Cardiac-Renal Comorbidity Protocol Development | Biomarker-guided precision dosing addresses simultaneous heart and kidney dysfunction in aging United States patient populations. |
| Suburban Cardiology Clinic Network Expansion | Medicare site-neutral payment reforms accelerate ambulatory inotropic therapy program development outside traditional hospital walls. |
| API Manufacturing Resilience Investment | Domestic synthesis capabilities reduce vulnerability to single-source disruptions from concentrated Indian and Chinese chemical facilities. |
| Closed-Loop Infusion System Integration | Automated titration protocols every 15-60 seconds compress recovery timelines and reduce pharmacist intervention frequency in tertiary centers. |
Methodological Framework
Bottom-up hospital and cardiology clinic demand modeling reconciled against top-down API production and pharmaceutical distribution tracking forms the analytical core of this study. Primary interviews with cardiac intensivists, hospital pharmacy directors, formulary committee chairs, and infusion pump biomedical engineers combined with secondary validation from FDA ICH E14 guidance documents, EMA MDR framework submissions, CMS Medicare reimbursement databases, and United States hospital procurement records. Triangulation across these sources ensures segmentation integrity across pharmacological classes and care settings.
Historical utilization trendline analysis in acute cardiac care units and cardiac surgery wards established baseline growth patterns extrapolated across the projection horizon. Segmentation dimensions modeled include pharmacological mechanism, administration route, therapy area severity, and regional regulatory cluster. CAGRs derive from procedural volume forecasting in coronary care units and cardiac surgery recovery wards, cross-referenced against formulary tier placement trajectories and ambulatory therapy program expansion rates.
The model holds under stable FDA and EMA regulatory frameworks with sustained Medicare reimbursement for acute hemodynamic stabilization; deviation in site-neutral payment reform implementation or phosphodiesterase-III inhibitor API supply disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Pantoprazole Market