
 Europe Electrophysiology Market | 2026-2036
Europe Electrophysiology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electrophysiology Market Analysis
Hospital electrophysiology departments is rotating toward ambulatory surgical centers as faster throughput and lower fixed costs attract payer attention. Biosense Webster (Johnson & Johnson) leverages its integrated mapping and ablation platform to dominate complex atrial fibrillation procedures across Western European tertiary centers. Abbott Laboratories sustains competitive positioning through catheter diversification and cryoablation technology depth. BIOTRONIK SE & Co. KG anchors its presence with strong cardiac rhythm management installed base relationships that extend into electrophysiology device pull-through.
Europe electrophysiology encompasses the diagnostic and therapeutic discipline addressing cardiac electrical conduction disorders through catheter-based mapping, recording, and ablation of arrhythmogenic tissue using radiofrequency, cryothermal, or pulsed field energy delivery. Catheters represent the largest product category by revenue contribution, with irrigated radiofrequency and cryoballoon platforms capturing disproportionate margin pools due to single-use disposability and procedure volume growth in paroxysmal atrial fibrillation. Radiofrequency technology leads current utilization while cryoablation occupies the fastest-expanding segment as simplified balloon-based pulmonary vein isolation protocols reduce operator learning curves and procedure time variability.
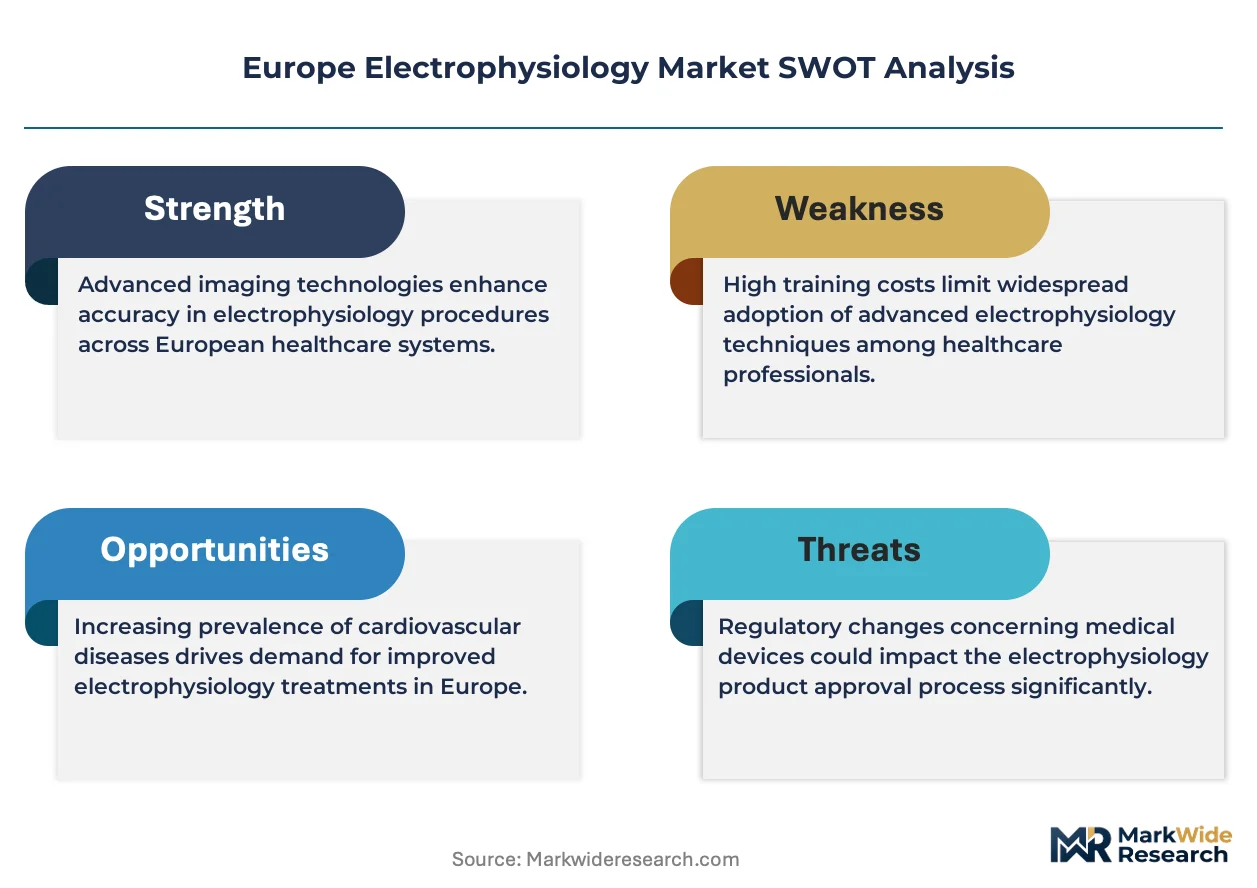
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies in Germany, the Netherlands, and France are extending clinical evaluation requirements and post-market surveillance obligations for active implantable electrophysiology devices. EMA coordination with national competent authorities shapes pharmacovigilance expectations for combination products integrating drug-coated ablation surfaces. Stakeholders must monitor notified body capacity constraints and evolving harmonized standards under the EU AI Act as machine learning algorithms increasingly embed into electroanatomic mapping systems.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product launch timelines and elevating clinical evidence burdens for catheter and mapping system manufacturers, forcing portfolio rationalization and notified body capacity competition.
Growth Catalysts
- First-line ablation protocols:Cardiology societies across Germany, France, and the Netherlands now recommend catheter ablation ahead of antiarrhythmic drug therapy for paroxysmal atrial fibrillation, expanding eligible patient pools.
- CE marking pathway centralization:Notified bodies in Germany and the Netherlands have consolidated electrophysiology device reviews, reducing approval fragmentation and accelerating market access for compliant manufacturers.
- Pulsed field energy maturation:Next-generation cardiac ablation platforms utilizing irreversible electroporation are entering clinical validation, promising selective myocardial tissue destruction without thermal collateral damage.
Market Restraints
- Platinum-iridium electrode supply concentration:Mining and refining of these critical catheter electrode materials concentrates in South Africa and Russia, exposing manufacturers to geopolitical supply interruptions and price volatility.
- MDR clinical evaluation costs:The EU Medical Device Regulation mandates expanded post-market clinical follow-up and periodic safety update reports, increasing regulatory compliance expenditure for active implantable electrophysiology devices.
- Fluoroscopy dependence:Many electrophysiology labs retain workflow architectures built around X-ray guidance, slowing adoption of zero-fluoroscopy magnetic and impedance-based navigation systems that reduce radiation exposure.
Strategic Opportunities
- Ambulatory surgical center migration:Payer pressure and throughput economics are driving simple ablation procedures out of hospital electrophysiology labs into dedicated outpatient facilities in Germany and Switzerland.
- EU AI Act algorithmic mapping:Machine learning-integrated electroanatomic mapping systems face new conformity assessment pathways under the EU AI Act, creating first-mover advantage for compliant platform developers.
- Cryoablation protocol simplification:Balloon-based pulmonary vein isolation reduces operator training duration and procedure time variability, expanding addressable physician populations beyond specialized electrophysiologists.
Industry Challenges
- Electrophysiologist training pipeline:Complex three-dimensional mapping and ablation procedures require 2-3 year subspecialty fellowships, and graduation rates lag procedure volume growth across European tertiary centers.
- Legacy system integration:New catheter and mapping platforms must interface with installed base recording systems from multiple manufacturers, creating interoperability validation burdens and delayed deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electrophysiology Market |
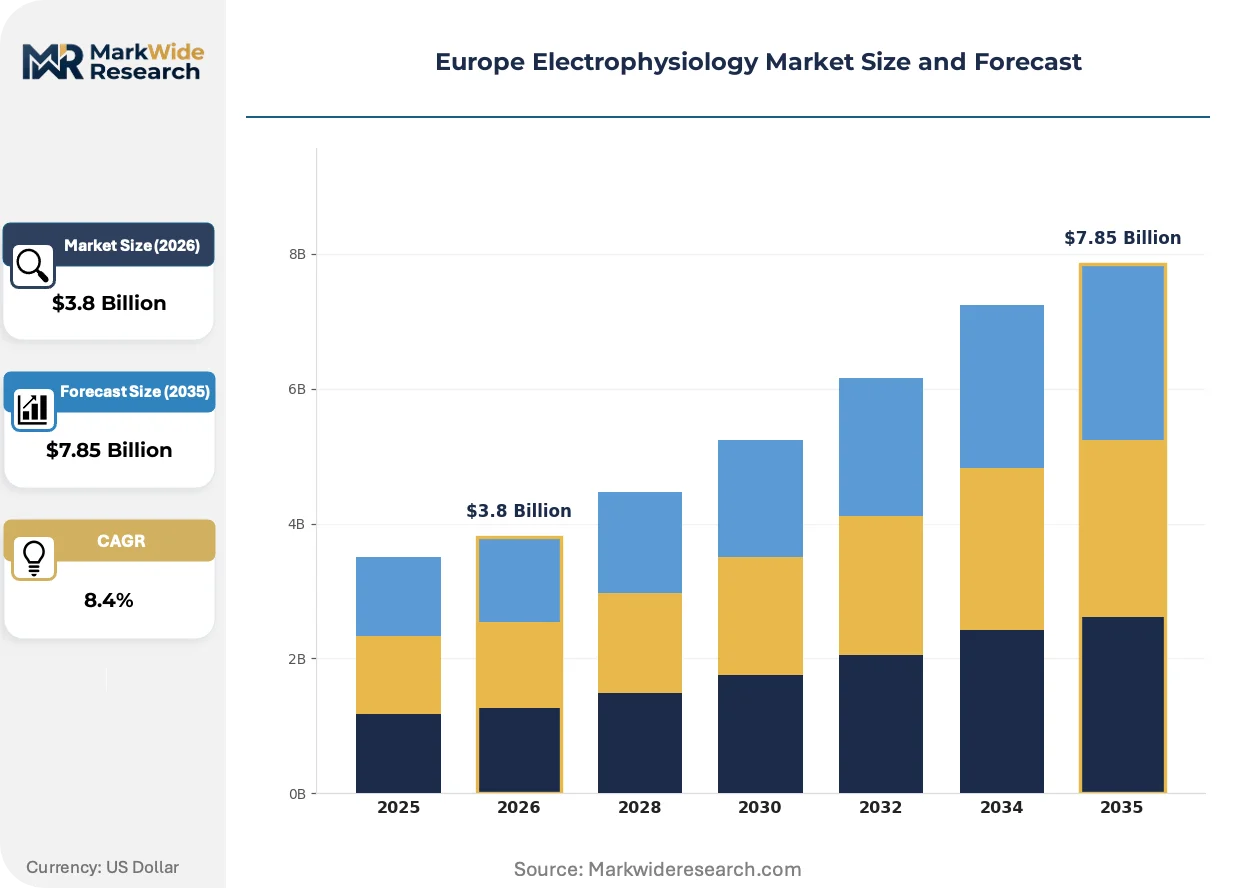
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Electrophysiology Systems, Mapping Systems, Accessories Application: Arrhythmia Management, Ablation, Diagnostics, Monitoring End User: Hospitals, Clinics, Research Institutions, Surgical Centers Technology: Cryoablation, Radiofrequency, Laser, Ultrasound |
| Companies Covered | Boston Scientific Corporation, GE Healthcare, Biosense Webster (Johnson & Johnson), Siemens Healthineers AG, Koninklijke Philips N.V., Abbott Laboratories, BIOTRONIK SE & Co. KG, Microport Scientific Corporation, Medtronic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electrophysiology Market Emerging Trajectories
Technology convergence and regulatory algorithmic governance are restructuring how electrophysiology devices are developed, validated, and deployed across European healthcare systems.
Pulsed field ablation technology is decomposing the traditional thermal ablation market by enabling faster pulmonary vein isolation with reduced esophageal and phrenic nerve injury risk. Tertiary cardiac centers in Germany and the Netherlands are piloting these systems for persistent atrial fibrillation cases previously considered too complex for efficient treatment. The technology is compressing average procedure times from three hours toward ninety minutes while expanding treatable patient anatomies.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on electroanatomic mapping systems employing machine learning for arrhythmia substrate identification. Manufacturers must now document algorithmic training data provenance, performance metrics across demographic subgroups, and human oversight protocols before CE marking. German notified bodies are developing specialized review capacities for these software-as-medical-device submissions, creating regulatory differentiation between compliant and non-compliant platform vendors.
Hospital procurement departments are consolidating electrophysiology device purchasing through framework agreements and single-source contracts, displacing traditional multi-vendor relationships. University hospitals in France and Belgium are leading this concentration, negotiating multi-year ablation catheter supply commitments in exchange for volume discounts and dedicated clinical training support. The shift is visible most acutely in paroxysmal atrial fibrillation procedure segments where product standardization carries lower clinical risk.
Europe Electrophysiology Market Segmentation
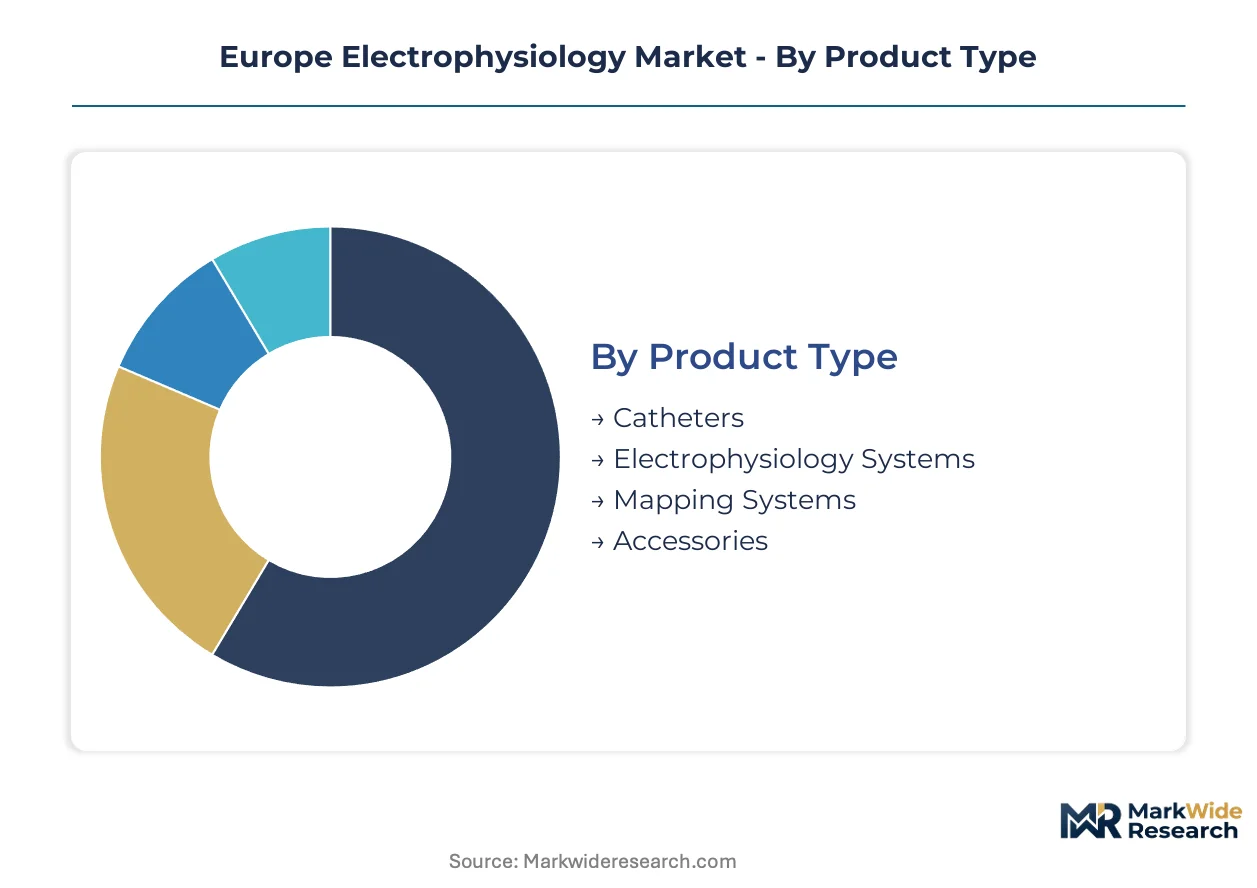
Electrophysiology market segmentation reveals how procedure economics, reimbursement pathways, and technology maturation concentrate margin pools across distinct product and service categories. Understanding these divisions enables targeted positioning for manufacturers navigating divergent clinical workflows and capital expenditure cycles.
Product Type:
Catheters command the largest margin pools due to single-use disposability and high replacement frequency in repeat ablation procedures.
- Catheters:Irrigated radiofrequency and cryoballoon designs dominate procedural volumes. German university hospitals anchor demand for advanced catheter platforms as they centralize complex atrial fibrillation referrals from surrounding regions.
- Electrophysiology Systems:Integrated recording and stimulation platforms form the capital backbone of hospital labs. Procurement centralization across French hospital networks is compressing vendor margins while extending contract durations.
- Mapping Systems:Three-dimensional electroanatomic mapping enables precise arrhythmia substrate localization. CE marking under the EU AI Act is extending validation timelines for machine learning-integrated platforms.
- Accessories:Sheaths, connectors, and disposable patches complete procedural setups. Demand concentrates in high-throughput centers in the Netherlands where case volumes justify bulk purchasing arrangements.
The dominant share belongs to Catheters, while Mapping Systems is closing the gap fastest as AI-integrated platforms gain clinical validation.
Application:
Volume concentration varies sharply between emergent therapeutic interventions and established diagnostic protocols across European cardiac centers.
- Arrhythmia Management:Comprehensive treatment pathways combining pharmacologic and interventional approaches. Belgian and Dutch cardiology societies now recommend catheter ablation as first-line therapy for paroxysmal atrial fibrillation, expanding eligible patient populations.
- Ablation:Catheter-based tissue destruction using thermal or pulsed field energy. Pulsed field ablation systems are gaining traction in German tertiary centers for persistent atrial fibrillation cases previously considered too complex for efficient treatment.
- Diagnostics:Electrophysiology study and event monitoring for rhythm disorder characterization. Demand is concentrating in outpatient cardiology practices across Switzerland where streamlined referral networks enable rapid specialist consultation.
- Monitoring:Long-term rhythm surveillance through implantable and external devices. Post-ablation monitoring protocols are extending device utilization periods across French hospital follow-up programs.
Ablation procedures generate the highest revenue per patient encounter, though Diagnostics delivers the steadiest volume base across ambulatory settings.
End User:
Capital intensity and reimbursement differentials create distinct purchasing behaviors across institutional settings.
- Hospitals:Tertiary cardiac centers with dedicated electrophysiology labs performing complex procedures. University hospitals in Germany anchor regional referral networks and drive adoption of advanced mapping and ablation platforms.
- Clinics:Outpatient cardiology practices handling diagnostic workup and post-procedural follow-up. Swiss and German clinic networks are expanding simple ablation capacity as payer pressure shifts appropriate cases from hospital settings.
- Research Institutions:Academic medical centers conducting clinical trials and technology validation studies. EMA coordination with national competent authorities shapes pharmacovigilance expectations for novel ablation technologies tested in these facilities.
- Surgical Centers:Dedicated ambulatory facilities focused on high-throughput routine procedures. Germany and Switzerland are pioneering this migration as framework agreements enable predictable case flow and dedicated staffing models.
Hospitals retain the dominant procedure volume, though Surgical Centers are expanding most quickly as payer economics favor site-of-care migration.
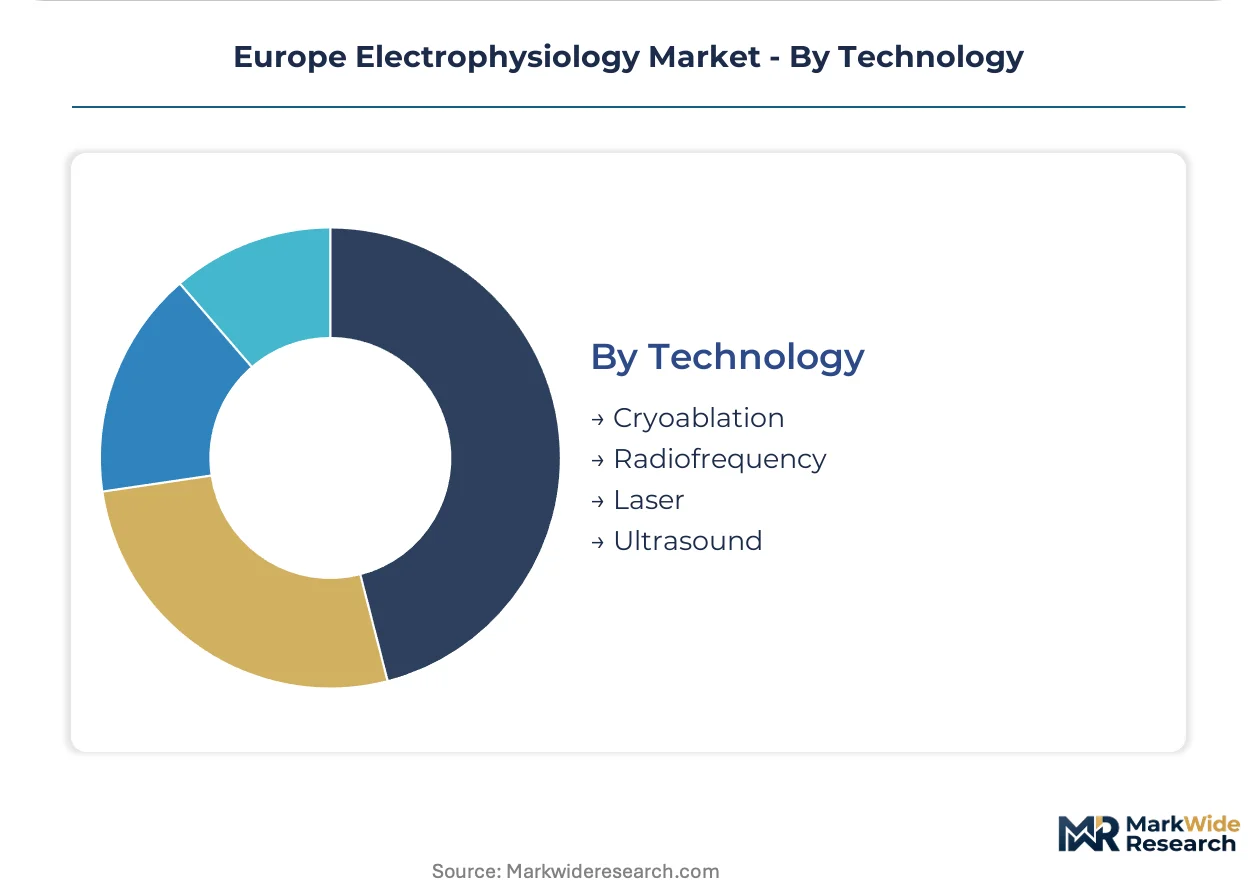
Technology:
Energy delivery modalities are restructuring around thermal safety profiles and procedure efficiency metrics.
- Cryoablation:Balloon-based cryothermal energy delivery for pulmonary vein isolation. Simplified operator protocols are reducing training duration and enabling procedure expansion beyond specialized electrophysiologists in French and Belgian centers.
- Radiofrequency:Resistive heating through irrigated or non-irrigated electrode designs. Current utilization leadership reflects decades of clinical validation and established reimbursement codes across European healthcare systems.
- Laser:Photocoagulation for precise tissue destruction with minimal collateral thermal spread. Niche applications persist in specific anatomical challenges where balloon-based approaches face technical limitations.
- Ultrasound:High-intensity focused energy for transmural lesion creation. Development activity concentrates in research partnerships with German engineering clusters seeking alternatives to thermal energy delivery.
Radiofrequency maintains installed base dominance, while Cryoablation is gaining share fastest through simplified workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrophysiology device manufacturers export catheter and mapping platforms to hospital networks across France, Belgium, and the Netherlands, establishing a north-south trade corridor that concentrates procurement decisions in Rhine-Ruhr and Parisian purchasing consortia.
Germany
University hospitals in Munich and Heidelberg anchor complex atrial fibrillation referral networks that drive demand for advanced ablation catheters and three-dimensional mapping systems. The Federal Institute for Drugs and Medical Devices enforces MDR conformity assessment pathways that extend clinical evidence requirements for active implantable devices. The Rhine-Ruhr metropolitan region concentrates electrophysiology lab capital expenditure through centralized procurement frameworks negotiated by hospital purchasing alliances.
France
Parisian hospital networks are consolidating electrophysiology device purchasing through multi-year framework agreements that displace traditional multi-vendor relationships. ANSM coordinates with EMA on pharmacovigilance expectations for combination products integrating drug-coated ablation surfaces. The Île-de-France region hosts pilot programs for pulsed field ablation systems targeting persistent atrial fibrillation cases previously considered too complex for efficient treatment.
Netherlands
High-throughput cardiac centers in Amsterdam and Rotterdam justify bulk purchasing arrangements for disposable electrophysiology accessories and catheter inventory. The Dutch Health and Youth Care Inspectorate aligns notified body reviews with German and French regulators to reduce approval fragmentation for CE marking pathways. The Randstad urban corridor leads ambulatory surgical center migration for simple ablation procedures as payer economics favor site-of-care shifts from hospital settings.
Switzerland
Swiss clinic networks are expanding simple ablation capacity as payer pressure shifts appropriate cases from tertiary hospital electrophysiology labs. Swissmedic maintains independent device authorization pathways while recognizing MDR harmonized standards for electrophysiology systems. The Zurich-Geneva axis concentrates private cardiology practice investment in diagnostic electrophysiology studies and post-ablation monitoring protocols.
Belgium
Belgian cardiology societies have elevated catheter ablation to first-line therapy status for paroxysmal atrial fibrillation, expanding eligible patient populations beyond antiarrhythmic drug candidates. The Federal Agency for Medicines and Health Products enforces post-market surveillance obligations for active implantable electrophysiology devices under MDR transitional provisions. The Leuven-Brussels corridor anchors clinical trial activity for next-generation cryoballoon platforms seeking simplified pulmonary vein isolation protocols.
Europe Electrophysiology Market Vendor Landscape
Listed leaders compete with private specialists across technology platform development and hospital procurement channel access, creating a tiered structure where scale-driven corporations face nimble catheter-focused competitors. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with integrated electrophysiology divisions, pure-play electrophysiology device specialists, and cardiac rhythm management incumbents extending into ablation technologies. Dominant competitive moves include M&A activity targeting mapping system capabilities and strategic partnerships with university hospitals for clinical validation studies.
Among diversified medical technology conglomerates, Boston Scientific Corporation, Abbott Laboratories, and Medtronic occupy positions that exemplify scale-driven platform integration across catheter, mapping, and implantable device categories. These listed entities anchor competitive dynamics through hospital purchasing consortium relationships and dedicated clinical training support programs. Their market presence reflects archetypal strategies of portfolio breadth and installed base leverage rather than singular technology specialization.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| GE Healthcare |
| Biosense Webster (Johnson & Johnson) |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Abbott Laboratories |
| BIOTRONIK SE & Co. KG |
| Microport Scientific Corporation |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Hospital purchasing alliance consolidation across the Rhine-Ruhr corridor and Parisian networks compresses vendor margins while extending contract durations, creating scale thresholds that marginalize smaller catheter manufacturers and anchor price floors to multi-year framework volumes rather than spot-market transactions.
Pricing Analysis
Radiofrequency catheter platforms command premium positioning against cryoballoon alternatives, while pulsed field systems enter at super-premium tiers pending MDR clinical validation completion. Three-tier pricing structure across premium irrigated RF, standard non-irrigated designs, and economy diagnostic catheters reflects CE marking tier differentiation and procedural complexity reimbursement bands. Pricing pressure stems from Dutch and French hospital procurement centralization demanding volume discounts for multi-year commitments. Ambulatory surgical centers exhibit highest price sensitivity due to fixed-case reimbursement caps, whereas German university hospitals prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Just-in-time catheter inventory models face 8-12 week lead time extensions when platinum-iridium electrode shipments from South African refiners encounter logistics interruptions. Manufacturing concentration in Germany, Ireland, and Costa Rica feeds European distribution hubs, with polymer catheter shafts and braided torque cables sourced from specialized extrusion houses in Minnesota and Massachusetts. Single-source vulnerability concentrates in electrode precious metal supply chains exposed to geopolitical export restrictions. Distribution runs through hospital purchasing consortia and GPO frameworks rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter reprocessing validation services and electrophysiology lab staffing contracts expand faster than hardware replacement cycles, creating recurring revenue pools that offset capital equipment margin compression across European hospital networks.
For Market Incumbents: Fortify installed base lock-in by embedding proprietary connector interfaces into next-generation mapping systems, raising switching costs for hospital labs contemplating multi-vendor environments. Deepen backward integration into platinum-iridium electrode supply through offtake agreements with South African refiners, insulating production continuity against export restriction scenarios. Prioritize MDR clinical evaluation investment for pulsed field platforms to maintain premium pricing tiers as thermal ablation commoditizes.
For New Entrants and Emerging Players: Post-ablation remote monitoring service gaps where incumbents under-serve present white-space entry points for cloud-native rhythm surveillance platforms unencumbered by legacy hardware integration burdens. Target Swiss and Dutch ambulatory surgical center networks with simplified cryoballoon protocols requiring minimal electrophysiologist specialization. Pursue CE marking pathway specialization under EU AI Act algorithmic governance to capture mapping system compliance premiums ahead of established competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pulsed field ablation specialists with de novo clinical evidence packages rather than thermal platform incumbents facing replacement pressure. Long-term viability across the analysis window hinges on MDR compliance infrastructure and notified body relationship depth rather than patent portfolios alone. Monitor German notified body queue lengths as inflection indicator for CE marking timeline compression and first-mover advantage realization.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Investment | Extended post-market follow-up satisfies BfArM requirements for active implantable device class upgrades. |
| Hospital System Partnership | Multi-year framework agreements with Parisian purchasing consortia lock out competing catheter vendors. |
| Software Companion Development | AI-integrated electroanatomic mapping platforms face EU AI Act conformity assessment pathway differentiation. |
| CE Marking Pathway Specialization | German notified body capacity concentration accelerates market access for compliant algorithmic systems. |
| Reimbursement Strategy | First-line ablation protocol recognition by Dutch and Belgian cardiology societies expands addressable patient pools. |
Methodological Framework
Operator-level perspectives from electrophysiology lab directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary validation from EMA MDR guidance documents, notified body capacity disclosures, hospital procurement databases, and CE marking registry filings. Bottom-up catheter volume modeling and top-down market sizing converged through iterative reconciliation across German, French, and Dutch national healthcare expenditure reports.
Sensitivity analysis around procedure volume assumptions and reimbursement rate trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, energy delivery technology, application indication, end-user facility tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns for cryoablation and pulsed field platforms. Industry-specific forecast inputs incorporated electrophysiologist fellowship graduation rates and MDR transition timeline uncertainty.
Underlying assumptions cover MDR notified body capacity stabilization, platinum-iridium supply continuity, and first-line ablation protocol adoption curves, with deviation risk concentrated in geopolitical export restrictions and EU AI Act implementation timeline delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market