
 Beta-Propeller Phytases Market | 2026-2036
Beta-Propeller Phytases Market Size, Share, and Industry Trends Forecast 2026-2036
Beta-Propeller Phytases Market Insights
China is rewriting capacity dynamics in beta-propeller phytases through aggressive fermentation infrastructure expansion and state-backed biotechnology parks. Novozymes A/S anchors Northern European enzyme innovation with deep R&D pipelines in thermostable variants. BASF SE leverages its global nutrition platform to control distribution into integrated livestock operations. DuPont de Nemours, Inc. competes through backward integration into proprietary strain development, while Vland Biotech Group dominates price-sensitive Asian markets with manufacturing scale.
Beta-propeller phytases are a class of six-bladed propeller-fold enzymes, typically derived from Bacillus species, that hydrolyze phytic acid to liberate bioavailable phosphorus in monogastric digestive systems; industrial formulations now achieve thermal stability exceeding 85°C to survive pelleting processes. Microbial phytases occupy the largest revenue pool due to established cost curves and validated performance in broiler and swine rations, while recombinant phytases represent the fastest-growing category as CRISPR-edited strains deliver superior pH profiles and substrate specificity. Animal feed applications generate the dominant volume share, though food processing interest is rising for mineral fortification in plant-based alternatives.
The EU Green Deal and REACH frameworks constrain phosphate discharge limits, compelling feed compounders to specify certified low-phytate or phytase-supplemented formulations. China's Ministry of Agriculture and Rural Affairs enforces feed additive registration under stricter biosafety protocols, slowing market entry for unvalidated strains. India's FSSAI and BIS are developing parallel standards for enzyme use in human nutrition, creating dual compliance pathways for manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and secure preferential market access.
Market Dynamics
CRISPR-edited Bacillus strains are compressing enzyme development cycles from years to months, forcing manufacturers to choose between accelerated R&D spending and obsolescence risk as thermal stability benchmarks reset above 90°C.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory phosphorus discharge reductions in the Netherlands, Denmark, and Germany compel feed compounders to specify certified phytase-supplemented formulations, creating regulatory pull-through for thermostable variants.
- Fermentation infrastructure expansion:State-backed biotechnology parks in China are scaling submerged fermentation capacity for microbial phytase production, lowering unit costs and displacing traditional solid-state methods.
- Poultry protein demand:Brazilian and Vietnamese integrators are expanding phytase adoption in broiler rations to meet export certification requirements while reducing dicalcium phosphate imports.
Market Restraints
- Input cost volatility:Corn steep liquor and soybean meal prices fluctuate with biofuel policy shifts, squeezing margins for fermentation-based producers dependent on agricultural feedstocks.
- Supply concentration risk:Three Chinese manufacturers control over 60% of bulk microbial phytase powder output, creating single-source vulnerability for European compounders seeking spot volumes.
- Regulatory friction:China's Ministry of Agriculture and Rural Affairs enforces stricter biosafety protocols for feed additive registration, extending validation timelines for unedited wild-type strains.
Strategic Opportunities
- Plant-based dairy fortification:Oat and pea protein processors in North America are testing beta-propeller phytases to liberate bound minerals in beverage formulations, opening human nutrition channels beyond animal feed.
- India's FSSAI enzyme standards:Parallel regulatory pathways for food-grade phytase certification create first-mover advantages for manufacturers with existing GMP infrastructure.
- CRISPR-pH profile convergence:Engineered strains combining gastric stability with ileal release characteristics enable premium pricing in swine diet segments previously served by generic additives.
Industry Challenges
- Strain characterization backlog:Whole-genome sequencing and proteomic validation for novel Bacillus isolates require 18-24 month timelines, delaying commercial launch schedules.
- Thermostability-pH tradeoff:Achieving 95°C pellet survival without compromising gastric pH activity demands iterative directed evolution cycles that consume limited R&D headcount.
- Legacy system integration:Feed mills running 1990s-era pelleting lines lack precise temperature control, forcing enzyme suppliers to formulate broader stability windows at higher cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta-Propeller Phytases Market |
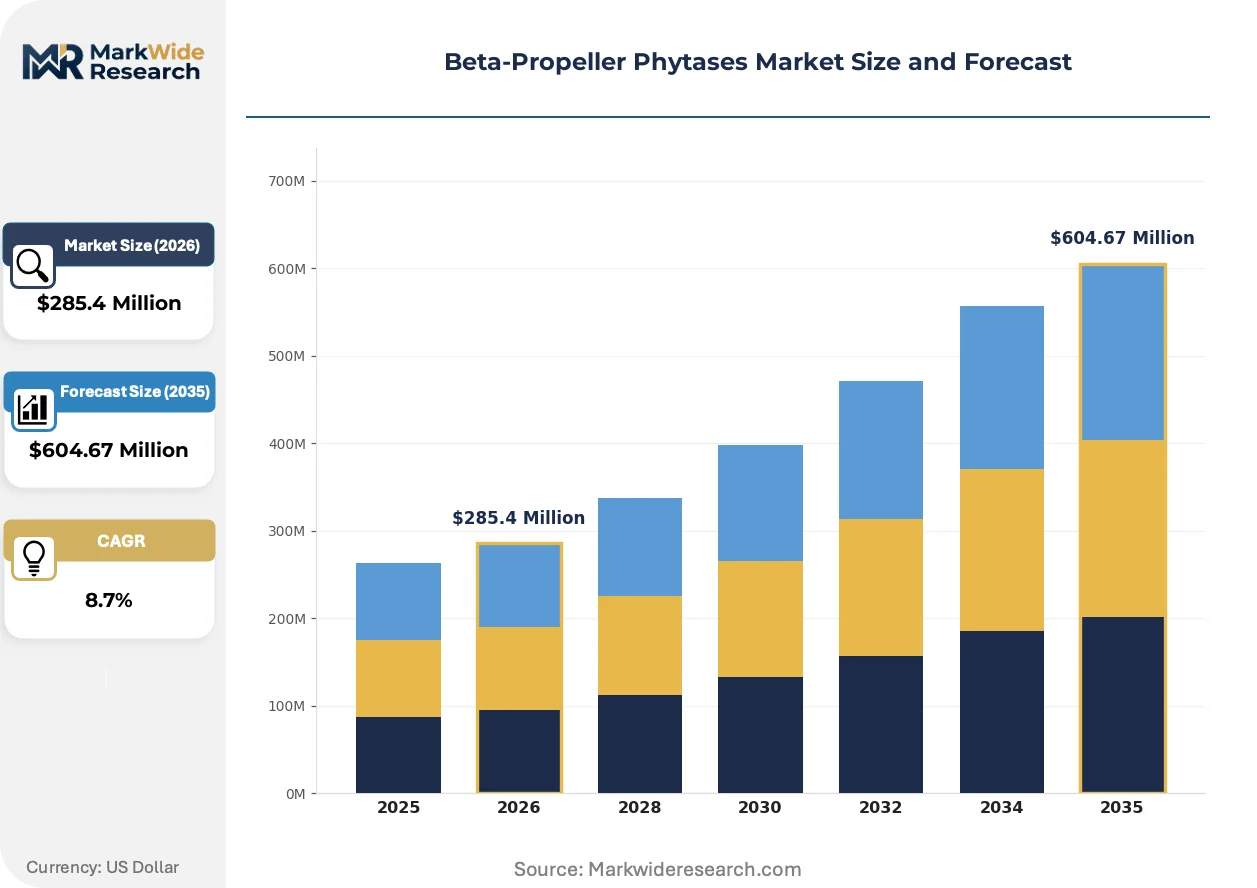
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Phytases, Plant Phytases, Recombinant Phytases, Non-Recombinant Phytases Application: Animal Feed, Human Nutrition, Agricultural Biotechnology, Food Processing End User: Livestock Producers, Food Manufacturers, Beverage Industry, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DuPont de Nemours, Inc., BASF SE, Novozymes A/S, Koninklijke DSM N.V., AB Enzymes, Aumgene Biosciences, Vland Biotech Group, Biocatalysts, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta-Propeller Phytases Market Trends and Innovations
Enzyme engineering is compressing the gap between laboratory strain development and industrial-scale validation, with three interconnected shifts redefining competitive advantage in phytase manufacturing.
Directed evolution platforms are migrating from academic consortia to captive industrial pipelines. Novozymes and BASF have internalized iterative mutagenesis workflows that previously relied on university partnerships. This migration from open innovation to proprietary strain libraries is accelerating thermostability improvement cycles and widening the capability gap between integrated manufacturers and formulation-only competitors.
REACH framework amendments are tightening ecotoxicity documentation requirements for enzyme preparations used in aquaculture feed. ECHA's revised guidance demands chronic toxicity data for non-target marine organisms, forcing reformulators to resubmit dossiers. Nordic salmon feed producers are responding by specifying phytase grades with third-party environmental fate certification, bifurcating the market between documented and undifferentiated supply.
Integrated livestock operations are consolidating procurement authority at the headquarters level, displacing decentralized mill-level purchasing. Brazilian poultry giants JBS and BRF now negotiate multi-year enzyme supply agreements directly, bypassing regional distributors. This concentration of buying power is visible most acutely in Mato Grosso and Paraná, where contract volumes determine access to technical service resources and co-development programs.
Beta-Propeller Phytases Market Segmentation
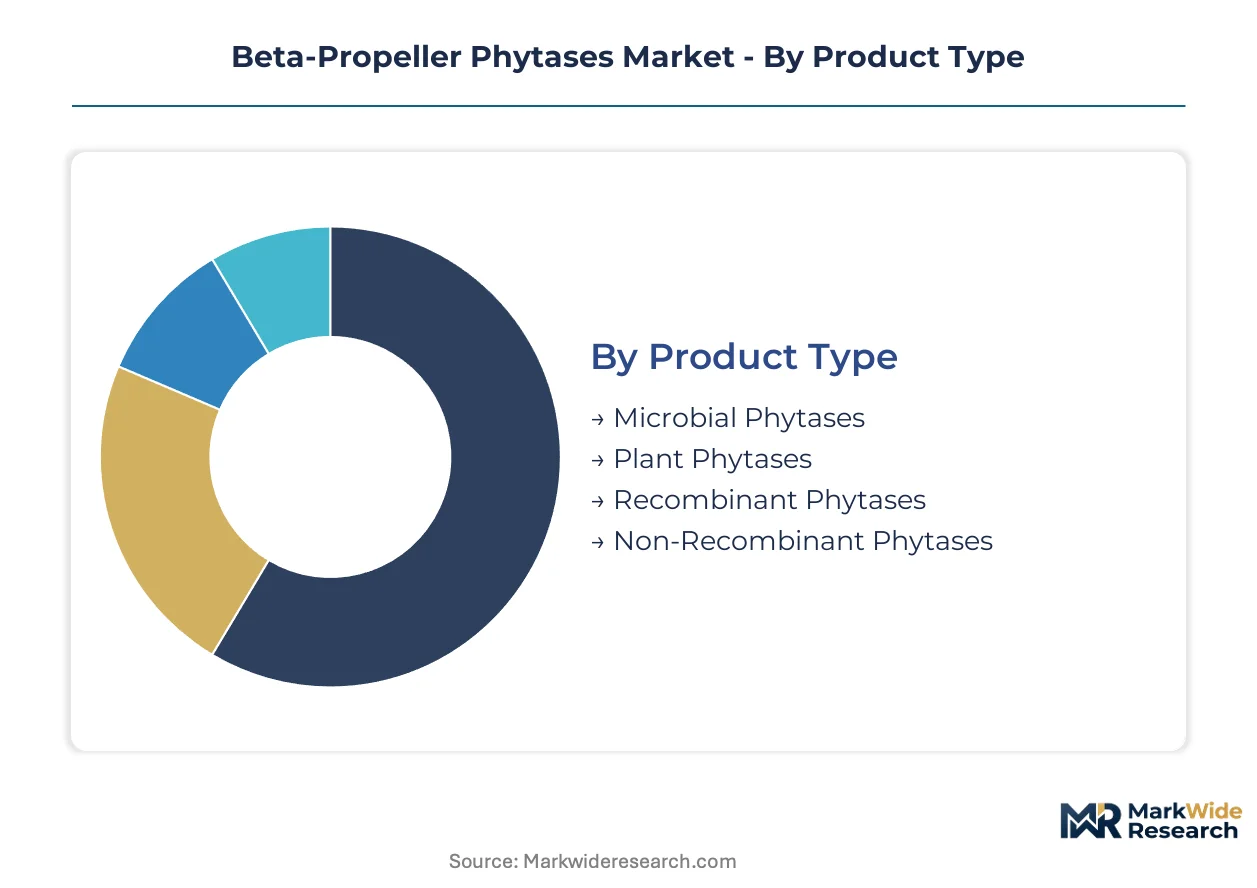
Segmentation in beta-propeller phytases reveals how technical specifications, regulatory pathways, and procurement patterns fragment demand across divergent value pools. Manufacturers must align strain engineering and distribution architecture to the performance thresholds and compliance requirements of each distinct buyer category.
Product Type:
Cost tier differentiation separates commodity-grade formulations from precision-engineered variants with divergent margin structures and R&D amortization profiles.
- Microbial Phytases:Fermentation-derived enzymes from Bacillus subtilis and Aspergillus niger dominate volume production with established cost curves. Demand concentrates in Brazilian and Vietnamese broiler operations seeking phosphate reduction without premium pricing. Thermal stability benchmarks at 85°C limit reformulation flexibility for older pelleting infrastructure.
- Recombinant Phytases:CRISPR-edited strains deliver superior pH activity profiles and substrate specificity through directed evolution. Swine integrators in Denmark and the Netherlands specify these variants to meet EU Green Deal phosphorus discharge mandates. The segment commands pricing premiums justified by reduced dicalcium phosphate supplementation rates.
- Plant Phytases:Naturally occurring variants from wheat and rice bran serve niche organic certification pathways with limited industrial scale.
- Non-Recombinant Phytases:Wild-type Bacillus isolates retain relevance in price-sensitive Asian markets with less stringent biosafety registration requirements.
Microbial phytases hold installed capacity. Recombinant phytases are rotating up the share rankings.
Application:
Application scope spans monogastric nutrition, human mineral fortification, and crop biotechnology with divergent regulatory validation burdens and performance specifications.
- Animal Feed:Poultry and swine rations absorb the dominant volume share, driven by phosphorus bioavailability requirements in corn-soybean meal diets. Brazilian integrators JBS and BRF negotiate multi-year supply agreements directly with enzyme manufacturers, consolidating procurement authority. REACH ecotoxicity documentation requirements for aquaculture variants are bifurcating supply between certified and undifferentiated grades.
- Food Processing:Oat and pea protein processors in North America are piloting beta-propeller phytases to liberate bound minerals in plant-based dairy alternatives. India's FSSAI is developing parallel enzyme standards for human nutrition, creating dual compliance pathways for manufacturers with existing GMP infrastructure.
- Human Nutrition:Mineral fortification applications remain nascent pending regulatory clarity on GRAS and novel food designations.
- Agricultural Biotechnology:Seed treatment and soil inoculation applications face longer validation timelines due to environmental release concerns.
Animal feed maintains volume dominance. Food processing is climbing the fastest as plant-based protein processors test mineral liberation protocols.
End User:
Customer type determines technical service intensity, contract structure, and co-development opportunity access across fragmented versus concentrated buying centers.
- Livestock Producers:Integrated poultry and swine operations in Mato Grosso and Paraná now centralize enzyme procurement at headquarters level, displacing mill-level purchasing. Technical service resources and strain co-development programs flow preferentially to contract volume leaders. Three Chinese manufacturers control bulk powder supply, creating single-source vulnerability for European compounders.
- Food Manufacturers:Plant-based dairy formulators require food-grade phytase certification with third-party validation of mineral bioavailability claims.
- Beverage Industry:Mineral-fortified oat and pea milk processors represent an emerging specification channel with distinct stability requirements.
- Agriculture:Crop biotechnology applications remain speculative pending field trial data on soil microbiome impacts.
Livestock producers command procurement leverage. Food manufacturers are gaining specification influence as human nutrition pathways mature.
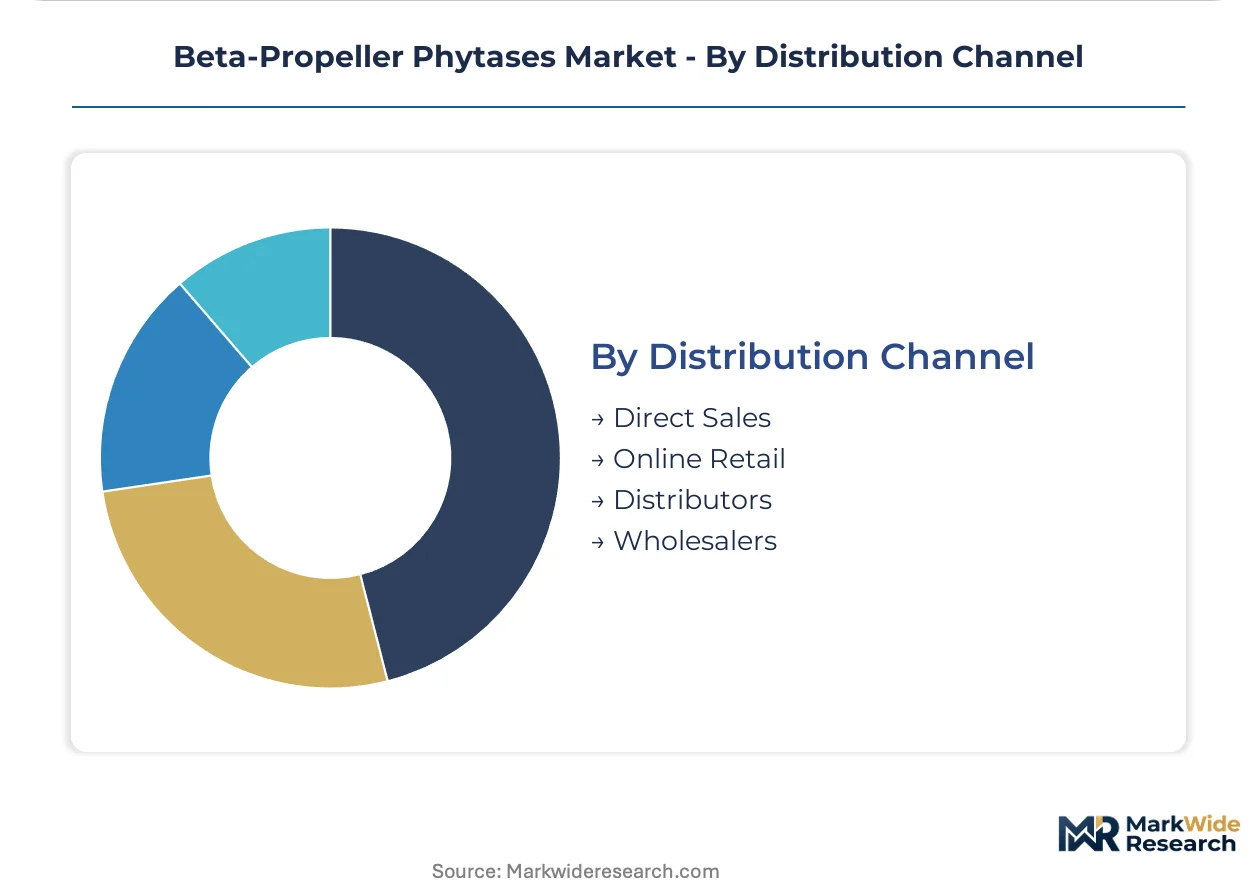
Distribution Channel:
Channel structure reflects customer concentration, technical complexity, and geographic proximity to fermentation capacity.
- Direct Sales:Integrated livestock operations and multinational feed compounders negotiate multi-year agreements with manufacturers. Novozymes and BASF deploy technical service teams to support strain selection and diet formulation optimization.
- Distributors:Regional feed additive distributors retain relevance in fragmented Southeast Asian and Latin American markets with decentralized mill infrastructure.
- Online Retail:E-commerce penetration remains minimal due to cold-chain requirements and technical consultation needs.
- Wholesalers:Bulk powder traders serve spot market demand from smaller compounders lacking direct manufacturer relationships.
Direct sales capture contract value. Distributors defend position in geographically fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters heavily in Chinese biotechnology parks, while demand pull concentrates in European regulatory jurisdictions and Brazilian protein export corridors. Novozymes anchors Northern European enzyme innovation, BASF leverages global nutrition platforms, and DuPont competes through proprietary strain development.
China
State-backed biotechnology parks in Jiangsu and Shandong provinces are scaling submerged fermentation capacity for microbial phytase production, displacing traditional solid-state methods. The Ministry of Agriculture and Rural Affairs enforces stricter biosafety protocols for feed additive registration, extending validation timelines for unedited wild-type strains. Zhengzhou and Guangzhou clusters host manufacturers controlling bulk powder output for Asian markets.
Brazil
Poultry integrators JBS and BRF in Mato Grosso and Paraná negotiate multi-year enzyme supply agreements directly, consolidating procurement authority at headquarters level. Export certification requirements for broiler rations mandate phosphate reduction protocols, driving phytase specification in corn-soybean meal diets. São Paulo-based distributors retain relevance in fragmented regional mill infrastructure.
Germany
The EU Green Deal's Farm to Fork Strategy compels feed compounders in Lower Saxony and Bavaria to specify certified phytase-supplemented formulations, creating regulatory pull-through for thermostable variants. ECHA's REACH framework amendments demand chronic ecotoxicity data for aquaculture enzyme preparations. Cologne and Hamburg host technical service teams supporting strain selection optimization.
India
Livestock producers in Haryana and Punjab expand phytase adoption in poultry and swine diets to meet protein demand while reducing phosphorus runoff. The FSSAI and BIS are developing parallel standards for enzyme use in human nutrition, creating dual compliance pathways for manufacturers. Maharashtra-based compounders seek spot volumes amid supply concentration risks.
United States
Oat and pea protein processors in the Midwest and Pacific Northwest pilot beta-propeller phytases to liberate bound minerals in plant-based dairy alternatives. FDA and USDA oversight of GRAS designations for food-grade enzyme applications remains pending regulatory clarity. Chicago and Minneapolis clusters concentrate beverage industry procurement influence.
Beta-Propeller Phytases Market Competitive Landscape
Integrated multinationals and specialized enzyme houses split the market between global distribution platforms and regional manufacturing scale. Consolidation pressure intensifies as CRISPR-edited strain development cycles compress from years to months. Three archetypes dominate: captive R&D integrators with proprietary fermentation networks, formulation specialists leveraging toll manufacturing, and price-competitive Asian producers with state-backed capacity expansion. Competitive moves center on backward integration into strain libraries and multi-year supply contract capture with integrated livestock operations.
Within the captive R&D tier, Novozymes A/S and DuPont de Nemours, Inc. exemplify archetypes anchored in Northern European and US biotechnology corridors respectively, while Vland Biotech Group occupies a position among Chinese manufacturers with fermentation scale advantages. These entities represent divergent strategic postures: thermostable variant development versus cost-curve positioning versus global nutrition platform leverage.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| BASF SE |
| Novozymes A/S |
| Koninklijke DSM N.V. |
| AB Enzymes |
| Aumgene Biosciences |
| Vland Biotech Group |
| Biocatalysts |
| Alltech |
| Others |
Pricing and Supply Chain Analysis
Three Chinese manufacturers controlling bulk microbial phytase powder output anchor upstream concentration, compressing margin pools for European compounders forced to absorb spot market volatility or lock in premium direct contracts. This supply asymmetry funnels pricing power toward fermentation-scale players while fragmenting downstream formulation margins.
Pricing Analysis
The EU Green Deal's Farm to Fork Strategy dictates the pricing tier structure across the beta-propeller phytases market, bifurcating supply between certified thermostable variants and undifferentiated commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects thermal stability benchmarks, REACH ecotoxicity documentation, and volume scale. Pricing pressure stems from corn steep liquor and soybean meal input cost volatility squeezing fermentation-based producers. Spot market buyers in Southeast Asia exhibit highest price sensitivity, while integrated livestock operations in Brazil and Denmark accept premiums for multi-year technical service bundles.
Supply Chain Analysis
Corn steep liquor, soybean meal, and specialized Bacillus culture media anchor raw material dependencies for fermentation-based phytase production. Supply concentrates in Chinese biotechnology parks in Jiangsu and Shandong provinces, with secondary capacity clusters in Denmark and the United States. Single-source vulnerability runs through the three dominant Chinese bulk powder manufacturers controlling spot market liquidity. Distribution runs through direct sales channels for integrated livestock operations and regional distributors serving fragmented mill infrastructure in Southeast Asia and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and strain co-development programs represent the fastest-expanding recurring-revenue layer, outpacing commodity enzyme sales as Brazilian and Danish integrators consolidate procurement authority at headquarters level.
For Market Incumbents: Insulate proprietary strain libraries through accelerated CRISPR-edited development cycles and captive fermentation capacity in Chinese biotechnology parks. Backward integration into genome-edited Bacillus platforms neutralizes formulation-only competitors while REACH ecotoxicity documentation requirements raise compliance barriers. Direct multi-year supply agreements with JBS and BRF secure volume commitment and technical service attach rates. For New Entrants and Emerging Players: India's FSSAI enzyme standards development creates first-mover white space for food-grade phytase certification. Plant-based dairy fortification in North American oat and pea protein processing offers penetrable application expansion beyond saturated animal feed channels. Partner with existing GMP infrastructure holders to bypass 18-24 month strain characterization timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial fermentation specialists lacking CRISPR-edited strain pipelines. Five-to-ten year viability hinges on thermostability-pH profile convergence capabilities and direct contract penetration with integrated livestock operations. Monitor ECHA REACH framework amendment implementation as inflection indicator for environmental fate certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Library Expansion | Accelerated thermostability development cycles widen capability gaps against formulation-only competitors. |
| REACH Ecotoxicity Certification | Third-party environmental fate documentation bifurcates supply between certified and undifferentiated grades. |
| Direct Supply Agreement Capture | Multi-year contracts with Brazilian poultry integrators consolidate procurement authority and technical service flows. |
| Food-Grade GMP Infrastructure | Parallel FSSAI certification pathways in India create dual compliance leverage for human nutrition expansion. |
| Fermentation Capacity Scale-Up | State-backed biotechnology parks in China displace solid-state methods and lower unit production costs. |
Research Methodology
Desk research of SEC enzyme manufacturer filings, ECHA REACH dossier submissions, and feed industry trade publications preceded structured interviews with fermentation plant managers, feed compounder procurement leads, regulatory affairs directors at enzyme houses, and technical service heads at integrated livestock operations. Primary fieldwork with Brazilian poultry integrators and Danish swine operations validated secondary data on contract structures and specification trends. Bottom-up strain-level production estimates triangulated against top-down animal feed additive market allocations.
Assumptions held regulatory timelines and CRISPR development cycle compression within observed patterns while varying corn steep liquor price trajectories and Chinese biosafety protocol enforcement intensity across scenario branches. Segmentation modeling spanned product type, application, and end-user concentration with regional production hub clustering as an industry-specific dimension. CAGRs derived from iterative convergence of demand-pull estimates and supply-side capacity buildout schedules, incorporating thermal stability benchmark evolution and phosphate discharge limit trajectories as enzyme-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese biotechnology parks or accelerated FDA GRAS designations for food-grade applications would shift outcomes beyond modeled ranges. Cross-checking against customs export data from Zhengzhou and Guangzhou fermentation clusters is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Trypsin Market