
 Brown Algae Protein Market | 2026-2036
Brown Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Brown Algae Protein Market Analytics
Direct sales channels from coastal extraction facilities to nutraceutical compounders is tilting as specialty distributors consolidate procurement across the Atlantic and Pacific basins. Cargill leverages its existing marine ingredient logistics network to sustain bulk supply contracts with European food manufacturers. Acadian Seaplants Limited anchors North Atlantic sourcing through its Nova Scotia harvesting operations. Algaia competes on fucoidan purity grades for pharmaceutical-grade buyers in France and Japan.
Brown algae protein encompasses protein isolates, hydrolysates, and whole-cell concentrates derived from Laminaria and Ascophyllum species, typically containing 30-50% crude protein with substantial sulfated polysaccharide fractions; manufacturers employ aqueous extraction or enzymatic hydrolysis to preserve bioactive functionality for human and animal nutrition applications. Sodium alginate dominates product type revenue due to its entrenched role in food texturization and pharmaceutical encapsulation, while fucoidan commands premium positioning in nutraceutical formulations targeting immune modulation. Food and beverage applications retain volume leadership through meat analog and dairy alternative formulations, though aquaculture feed represents the fastest-growing application as salmon and shrimp producers seek fishmeal substitution pathways.
EFSA novel food assessments and FDA GRAS self-affirmation pathways shape ingredient commercialization timelines for European and American entrants, while China's NMPA and SAMR oversee functional food ingredient registrations under GB standards. The EU F-Gas Regulation and REACH chemical safety protocols additionally constrain solvent-based extraction methods, favoring supercritical CO2 and enzyme-based processing investments. Stakeholders must monitor regulatory divergence between jurisdictions to align extraction technology choices with market access requirements.
Market Dynamics
EU F-Gas Regulation constraints on solvent-based extraction are forcing Atlantic basin processors to retool toward enzymatic hydrolysis and supercritical CO2 systems, compressing capital recovery timelines for brown algae protein manufacturers.
Growth Catalysts
- Novel Food Pathways:EFSA streamlined assessments for Laminaria-derived ingredients accelerate European market entry timelines for kelp protein isolates targeting dairy alternative formulations.
- Fishmeal Substitution Mandates:Norwegian and Scottish salmon aquaculture operators are expanding long-term procurement contracts for Ascophyllum protein concentrates to meet sustainability certification requirements.
- Fermentation-Assisted Extraction:Cell-free enzymatic systems developed at South Korean marine biotechnology institutes are improving fucoidan recovery yields without thermal degradation of protein fractions.
Market Restraints
- Wild Harvest Volatility:North Atlantic kelp beds face seasonal biomass fluctuations that constrain year-round raw material availability for Nova Scotia and Brittany processing facilities.
- Input Cost Concentration: Seaweed farming lease rates in Norwegian fjords have escalated as aquaculture and biorefinery operators compete for limited coastal tenure permits.
- Technical Purity Ceilings:Current aqueous extraction methods struggle to reduce heavy metal bioaccumulation below pharmaceutical-grade thresholds without multi-stage purification that erodes margins.
Strategic Opportunities
- Underpenetrated Feed Markets:Brazilian shrimp aquaculture represents a nascent demand pocket where brown algae protein could displace soy concentrate imports if import tariff structures align.
- Regulatory Tailwinds:China's dual carbon goals and SAMR functional food registrations create parallel pathways for kelp-derived ingredients in reduced-carbon meat analog formulations.
- Convergence of Biorefinery Models:Integration of alginate extraction with protein recovery is collapsing unit economics for integrated coastal processors in France and Japan.
Industry Challenges
- Specialized Talent Scarcity:Marine enzymology and phycochemistry expertise concentrates in a handful of European and East Asian university clusters, constraining R&D scaling for new market entrants.
- Certification Timeline Compression:FDA GRAS self-affirmation documentation requirements and EFSA novel food dossier preparation consume 18-36 months, delaying revenue recognition for ingredient innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brown Algae Protein Market |
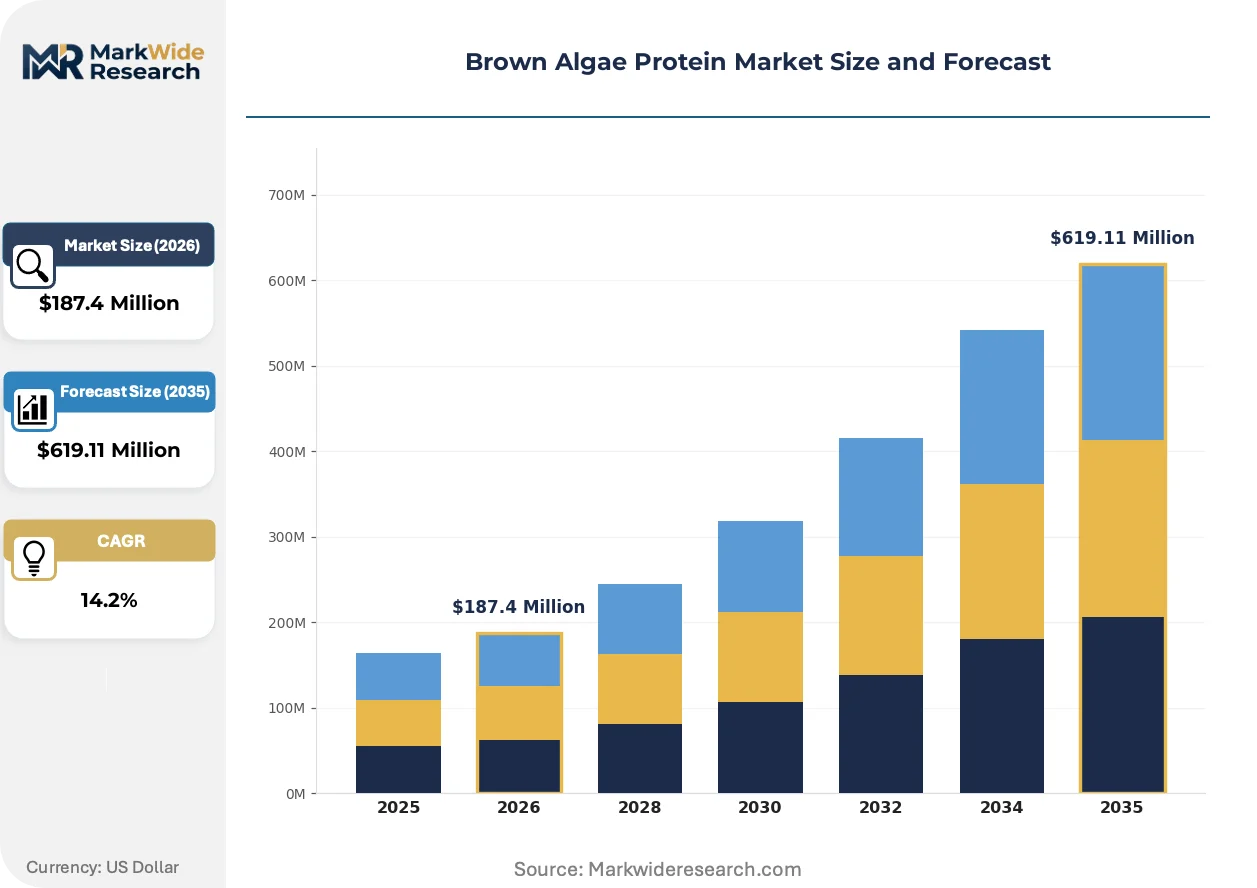
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Fucoidan, Laminaria, Kelp Powder Application: Food & Beverage, Nutraceuticals, Animal Feed, Cosmetics End User: Food Manufacturers, Health Supplements, Cosmetics Companies, Aquaculture Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Cargill, DuPont Nutrition & Biosciences, Cyanotech Corporation, Corbion, Earthrise Nutritionals, Far East Bio-Tec, Algaia, CP Kelco U.S., Inc., Acadian Seaplants Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brown Algae Protein Market Evolving Landscape
Processing technology convergence with precision fermentation and novel food regulatory harmonization are compressing the pathway from kelp biomass to commercial protein ingredient.
Enzymatic hydrolysis using immobilized cellulase and protease cocktails is collapsing the cost differential between brown algae protein isolates and conventional pulse proteins. European meat analog manufacturers are piloting these ingredients at industrial scale. The technology is collapsing extraction yield thresholds that previously relegated kelp proteins to niche nutraceutical applications.
REACH chemical safety protocols and the EU F-Gas Regulation are constraining halogenated solvent use in marine ingredient processing. Supercritical CO2 systems are displacing legacy hexane-based extraction in Atlantic basin facilities. Pharmaceutical-grade fucoidan producers in France and Japan are responding with capital commitments to enzyme-based purification trains.
Compounders are consolidating procurement through specialty distributors with integrated cold-chain logistics rather than contracting directly with coastal extraction facilities. North American nutraceutical formulators are shifting toward distributors offering bundled certification documentation and lot traceability. This pattern is most visible in California and New York State, where FDA cGMP compliance costs favor outsourced supplier qualification.
Brown Algae Protein Market Segmentation
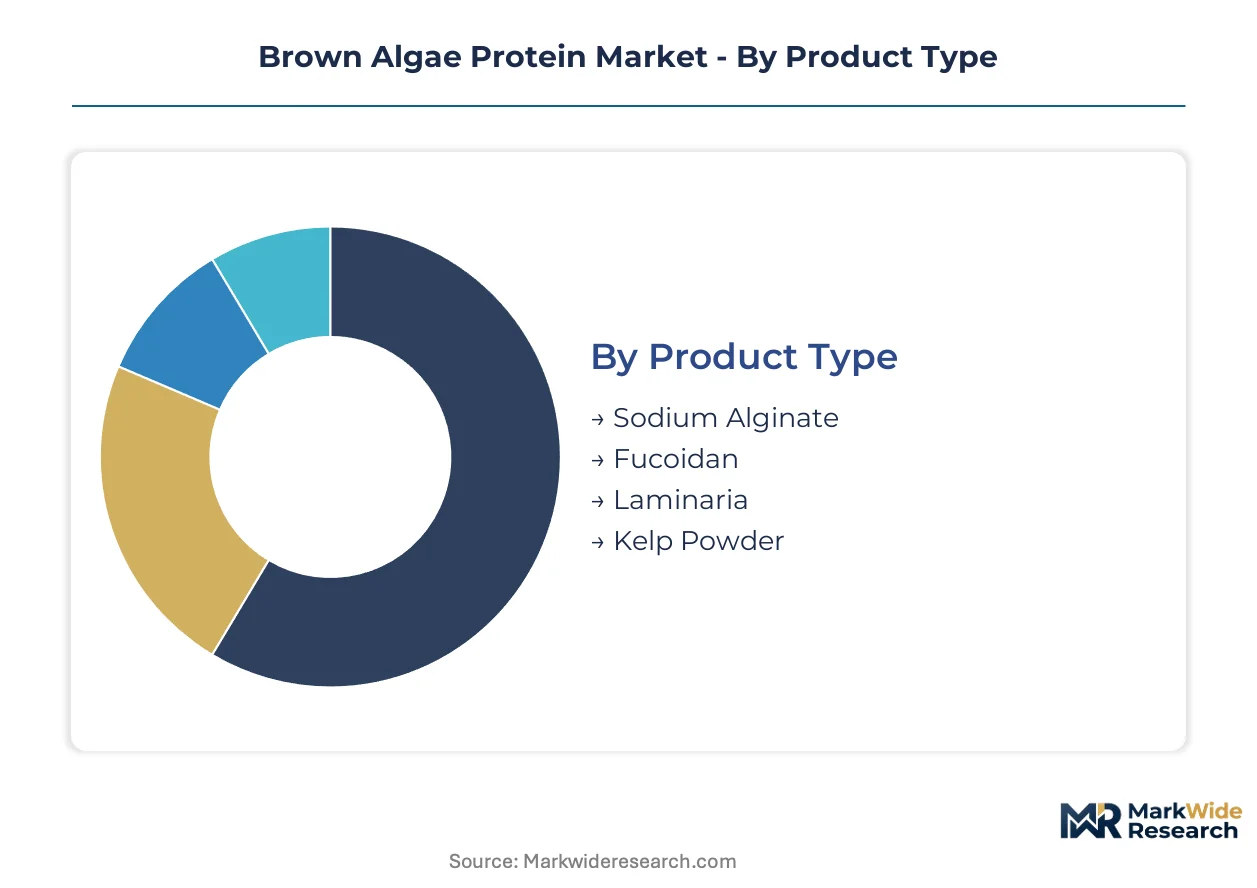
Brown algae protein markets fragment across extraction chemistry, regulatory pathway, and customer technical requirements. Each segmentation dimension carries distinct margin structures and certification burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans industrial texturizers to pharmaceutical-grade bioactives with purity thresholds that determine market access.
- Sodium Alginate:Sulfated polysaccharide extracted via alkaline processing delivers viscosity control and encapsulation functionality. Food manufacturers in France and Japan sustain procurement volumes for dairy stabilization and meat analog binding despite REACH solvent constraints compressing extraction margins.
- Fucoidan:High-molecular-weight sulfated polysaccharide requiring multi-stage purification to meet pharmaceutical-grade heavy metal thresholds. Nutraceutical compounders in South Korea and Japan absorb premium pricing for immune-modulation formulations where EFSA novel food dossiers and FDA GRAS self-affirmations govern commercialization timelines.
- Laminaria:Whole kelp biomass concentrates containing 30-50% crude protein with residual alginate fractions. Aquaculture feed blenders in Norway leverage Laminaria protein concentrates for salmon diet formulations targeting sustainability certification requirements.
- Kelp Powder:Minimally processed dried biomass retaining full polysaccharide and mineral content. Health supplement distributors in California and New York State source kelp powder for iodine-rich formulations where lot traceability and cGMP documentation outweigh purity premiums.
Established volume favors sodium alginate; emerging adoption favors fucoidan.
Application:
Cost tier separation reflects regulatory intensity and formulation complexity rather than raw material differentiation alone.
- Food & Beverage:Plant-based meat analog and dairy alternative manufacturers in Europe pilot enzymatically hydrolyzed kelp proteins at industrial scale. EFSA streamlined novel food assessments for Laminaria-derived ingredients compress European market entry timelines relative to legacy extraction methods.
- Nutraceuticals:Immune modulation and gut health formulations command premium positioning where fucoidan purity grades determine customer qualification. Japanese pharmaceutical-grade buyers enforce heavy metal thresholds below 0.5 ppm through multi-stage purification trains that erode processor margins.
- Animal Feed:Salmon and shrimp aquaculture operators in Norway and Scotland expand procurement contracts for Ascophyllum protein concentrates. Fishmeal substitution mandates under sustainability certification schemes drive fastest application expansion across Atlantic basin coastal processors.
- Cosmetics:Marine bioactive inclusion in anti-aging and hydration formulations concentrates in South Korean and French premium skincare markets. Moisture-retention claims align with alginate film-forming properties though regulatory divergence between EU REACH and China's SAMR cosmetic ingredient registrations fragments commercialization pathways.
Feed applications gain share fastest; nutraceuticals defend margin concentration.
End User:
Customer type determines procurement modality and certification burden intensity.
- Food Manufacturers:Industrial-scale meat analog and dairy alternative producers in Germany and the Netherlands contract directly with Atlantic basin extraction facilities for sodium alginate and hydrolyzed protein isolates.
- Health Supplements:Compounders in California and New York State consolidate procurement through specialty distributors offering bundled FDA cGMP documentation and cold-chain logistics rather than direct coastal facility contracts.
- Cosmetics Companies:French and South Korean formulators source pharmaceutical-grade fucoidan through distributors with integrated lot traceability systems.
- Aquaculture:Norwegian and Scottish salmon producers negotiate long-term supply agreements for Ascophyllum protein concentrates under sustainability certification procurement policies.
Direct coastal contracting favors aquaculture; distributor-mediated procurement favors health supplements.
Distribution Channel:
Channel selection reflects customer scale, certification requirements, and geographic concentration.
- Online Retail:Direct-to-consumer kelp powder and supplement formulations concentrate in California and New York State where wellness consumer density supports e-commerce fulfillment economics.
- Direct Sales:Coastal extraction facilities in Nova Scotia and Brittany maintain direct relationships with European food manufacturers and Norwegian aquaculture operators for bulk sodium alginate and protein concentrate contracts.
- Distributors:Specialty marine ingredient distributors with integrated cold-chain and certification documentation capabilities consolidate procurement across North American nutraceutical compounders.
- Specialty Stores:Premium skincare and wellness retail channels in South Korea and France stock fucoidan and kelp powder formulations targeting consumer willingness to pay for marine bioactive positioning.
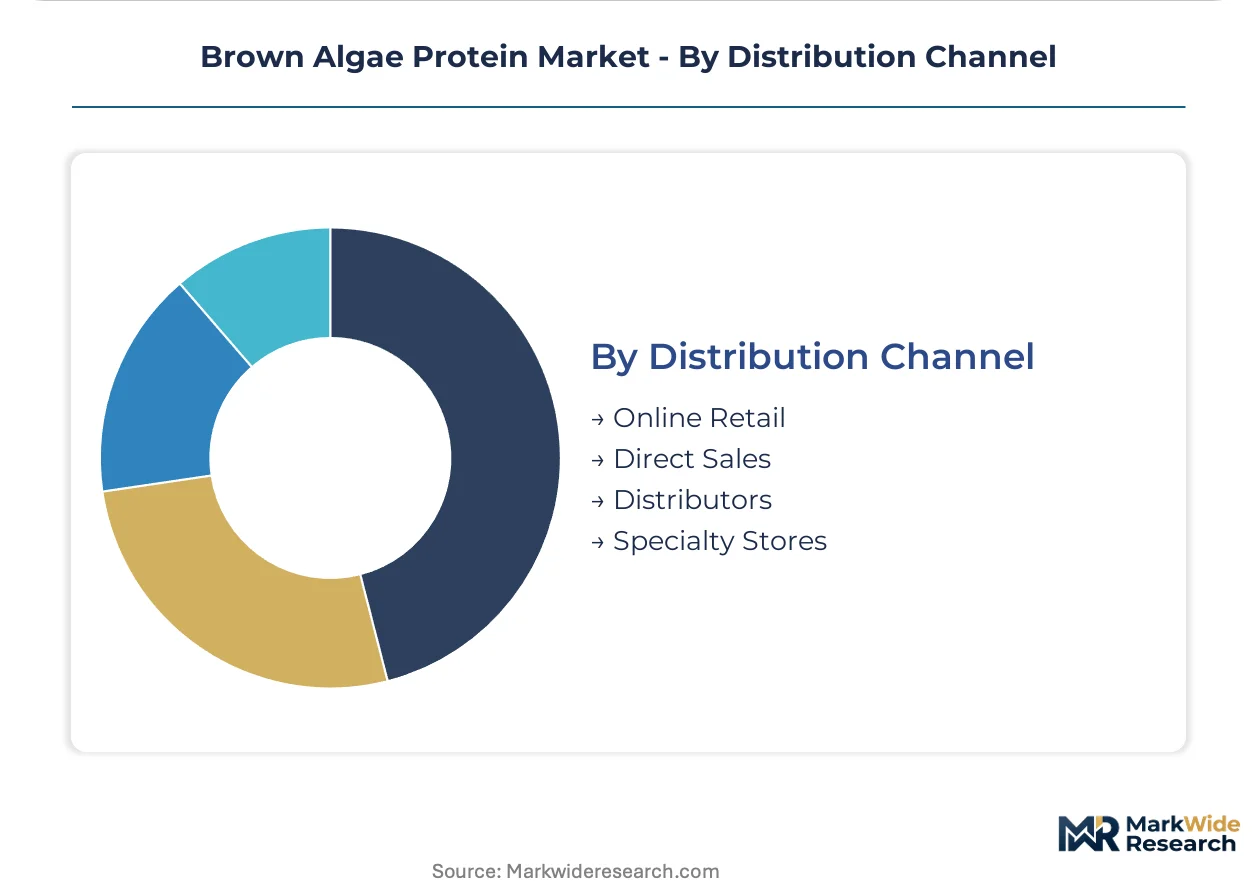
Direct sales anchor industrial volume; distributor consolidation reshapes nutraceutical access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium fucoidan pricing in Japan exceeds Atlantic basin kelp protein benchmarks by a substantial margin, creating arbitrage incentives for French and Norwegian processors. Chinese coastal biorefineries exploit this asymmetry through dual-carbon-aligned capacity expansions.
Norway
Salmon aquaculture operators in Bergen and Trondheim fjords drive Ascophyllum protein concentrate procurement under ASC sustainability certification mandates. The Norwegian Food Safety Authority enforces strict heavy metal thresholds for feed ingredients. Biorefinery clusters in Nordland county integrate alginate extraction with protein recovery to collapse unit economics.
France
Pharmaceutical-grade fucoidan demand from nutraceutical compounders concentrates in Brittany and Normandy coastal zones. ANSM and EFSA novel food pathways govern commercialization timelines for kelp-derived ingredients. Roscoff marine biology institutes anchor enzyme-based purification technology development for premium bioactive fractions.
South Korea
MFDS functional food registrations and marine biotechnology R&D investments accelerate fucoidan commercialization for immune-modulation formulations. Busan-Ulsan coastal processors deploy cell-free enzymatic systems developed at national marine science institutes. Jeju Island kelp farming operations expand to meet domestic nutraceutical and cosmetic ingredient demand.
United States
FDA GRAS self-affirmation pathways and California wellness consumer density sustain direct-to-consumer kelp powder markets. FDA cGMP compliance costs in New York State and California favor distributor-mediated procurement over direct coastal contracting. Pacific Northwest cold-chain logistics providers consolidate nutraceutical ingredient distribution.
China
NMPA and SAMR functional food registrations under GB standards create parallel commercialization pathways for reduced-carbon meat analog formulations. Shandong Peninsula and Dalian coastal biorefineries scale kelp protein capacity under dual carbon policy incentives. Qingdao marine biotechnology clusters advance fermentation-assisted extraction technologies.
Brown Algae Protein Market Competitive Landscape
Integrated marine ingredient conglomerates and specialized phycochemical processors split the market between volume efficiency and purity premium capture. The vendor base concentrates around coastal extraction infrastructure with cold-chain logistics capabilities. Three archetypes dominate: Atlantic basin harvester-processors with direct aquaculture relationships, Asian biorefinery operators leveraging fermentation technology, and distributor-consolidators bundling certification documentation. Competitive moves center on backward integration into seaweed farming leases and enzymatic hydrolysis technology licensing.
Within the integrated processor tier, Cargill and Acadian Seaplants Limited occupy positions that exemplify Atlantic basin sourcing consolidation. Algaia represents the specialized phycochemical archetype focused on premium-grade bioactive fractions. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Cargill |
| DuPont Nutrition & Biosciences |
| Cyanotech Corporation |
| Corbion |
| Earthrise Nutritionals |
| Far East Bio-Tec |
| Algaia |
| CP Kelco U.S., Inc. |
| Acadian Seaplants Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity in Norwegian fjord seaweed farming is compressing processor margins while amplifying pricing power for coastal leaseholders. This utilization squeeze feeds directly into contract structures, with long-term offtake agreements commanding premium terms over spot procurement.
Pricing Analysis
Configured-to-order fucoidan pricing commands spreads exceeding threefold against standard kelp powder grades. Pharmaceutical-grade buyers in Japan and South Korea absorb premiums for heavy metal thresholds below 0.5 ppm, while aquaculture feed blenders in Norway prioritize volume scale over purity certification. Cost compression in standard-grade sodium alginate is intensifying as REACH solvent constraints erode extraction margins. Health supplement distributors in California exhibit highest price sensitivity, whereas French nutraceutical compounders defend premium positioning for immune-modulation formulations.
Supply Chain Analysis
Export-control scrutiny on enzymatic hydrolysis equipment from South Korean marine biotechnology institutes is constraining technology transfer to Atlantic basin processors. Raw material flows concentrate in Norway, France, and South Korea, with coastal processing infrastructure tethered to seasonal kelp biomass availability. Supply chains draw from wild North Atlantic harvests, Jeju Island farmed kelp, and Shandong Peninsula cultivated biomass. Single-source vulnerability runs through Nova Scotia and Brittany extraction facilities dependent on shared North Atlantic kelp beds. Distribution runs through specialty marine ingredient distributors with integrated cold-chain logistics and bundled certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brown algae protein sits in early-cycle expansion as fishmeal substitution mandates in Atlantic salmon aquaculture accelerate ingredient penetration. Novel food regulatory harmonization between EFSA and FDA pathways is compressing commercialization timelines for kelp-derived formulations.
For Market Incumbents: Build captive seaweed farming moats through long-term fjord lease consolidation in Norway and Brittany. Secure backward integration into enzymatic hydrolysis technology licensing from South Korean marine institutes to defend against fermentation-assisted extraction entrants. Expand cold-chain distribution partnerships with North American nutraceutical compounders to lock in channel control before specialty distributor consolidation accelerates.
For New Entrants and Emerging Players: Brazilian shrimp aquaculture feed markets represent the most penetrable entry point, with import tariff alignment creating arbitrage opportunity against soy concentrate incumbents. China's reduced-carbon meat analog formulations under SAMR functional food registrations offer parallel white-space expansion. Lead with fermentation-assisted extraction technology licensing rather than capital-intensive coastal processing infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biorefinery operators with captive seaweed supply and multi-product alginate-protein recovery trains. Long-term viability favors processors with enzymatic purification capabilities serving pharmaceutical-grade fucoidan demand. Monitor EFSA novel food assessment throughput velocity as the primary inflection signal for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Long-term fjord lease consolidation in Norway secures raw material supply against seasonal volatility. |
| Enzymatic Hydrolysis Technology Licensing | Cell-free extraction systems from South Korean institutes displace solvent-based processing under EU F-Gas constraints. |
| Pharmaceutical-Grade Fucoidan Capacity Expansion | Multi-stage purification trains in France and Japan capture premium pricing from immune-modulation nutraceutical buyers. |
| Distributor Consolidation Partnerships | Specialty marine ingredient distributors with cold-chain logistics bundle FDA cGMP documentation for California compounders. |
| Fermentation-Assisted Extraction R&D | Qingdao and Busan-Ulsan biotechnology clusters advance yield improvements without thermal protein degradation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction facility operators, nutraceutical formulators, and aquaculture feed procurement managers; and secondary validation through EFSA novel food dossiers, FDA GRAS notifications, customs trade data on marine ingredient flows, and SEC filings from integrated ingredient conglomerates. Bottom-up volume modeling across extraction chemistry tiers was triangulated against top-down expenditure estimates from food manufacturer R&D disclosures.
Forecast inputs spanned regulatory pathway velocity, enzymatic technology adoption curves, and aquaculture certification scheme penetration. Segmentation dimensions included product type purity grades, application regulatory intensity, end-user procurement modality, and distribution channel certification bundling. CAGRs were derived from fitted adoption curves across the projection horizon, with cross-validation against coastal processing capacity expansion announcements and seaweed farming lease rate trajectories.
Practitioners should monitor EFSA assessment queue lengths, Norwegian fjord lease auction prices, and South Korean equipment export licensing delays for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Papain Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Trypsin Market