
 Bangladesh Starch and Starch Derivative Market | 2026-2036
Bangladesh Starch and Starch Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Starch and Starch Derivative Market Outlook
Pharmaceutical formulators are unwinding their historical reliance on textile mill buyers as the dominant starch consumers. Bangladesh Maize Products Limited leverages its captive wet-milling infrastructure to anchor supply contracts with generic drug manufacturers across the Dhaka pharmaceutical cluster. Gulshan Polyols Limited specializes in sorbitol-starch derivative blends that compete directly with imported excipients. FLAMINGO AGRO-TECH LTD dominates the northern maize-belt procurement network, sustaining cost advantages through backward integration into farmer-level collection.
Starch and starch derivatives comprise polysaccharide extracts—primarily amylose and amylopectin chains ranging from 10% to 30% amylose content—derived from corn, wheat, or tapioca through wet-milling, drying, and enzymatic or chemical modification processes. These ingredients function as thickeners, binders, film-formers, and moisture-retention agents across food, pharmaceutical, and industrial applications. Modified starch commands the deepest margin pools due to its premium pricing in pharmaceutical and personal care applications, while native starch remains the volume backbone serving animal feed and basic food processing. Starch syrups are gaining fastest in the beverage end use industry as local soft drink bottlers reformulate with domestic sweetener sources.
The Bangladesh Food Safety Authority enforces additive purity standards that restrict unmodified import channels, while the Bangladesh Standards and Testing Institution certifies moisture and ash content thresholds for industrial starch grades. The Department of Environment mandates effluent treatment for wet-milling operations, raising capital barriers for new entrants. Stakeholders must monitor how BIS-equivalent certification timelines and Dhaka's pharmaceutical export growth reshape sourcing decisions between local mills and regional suppliers.
Market Dynamics
The Bangladesh Starch and Starch Derivative Market pivots on pharmaceutical formulators displacing textile mills as the dominant demand anchor, with wet-milling capacity racing to capture excipient-grade certification before import substitution timelines tighten.
Growth Catalysts
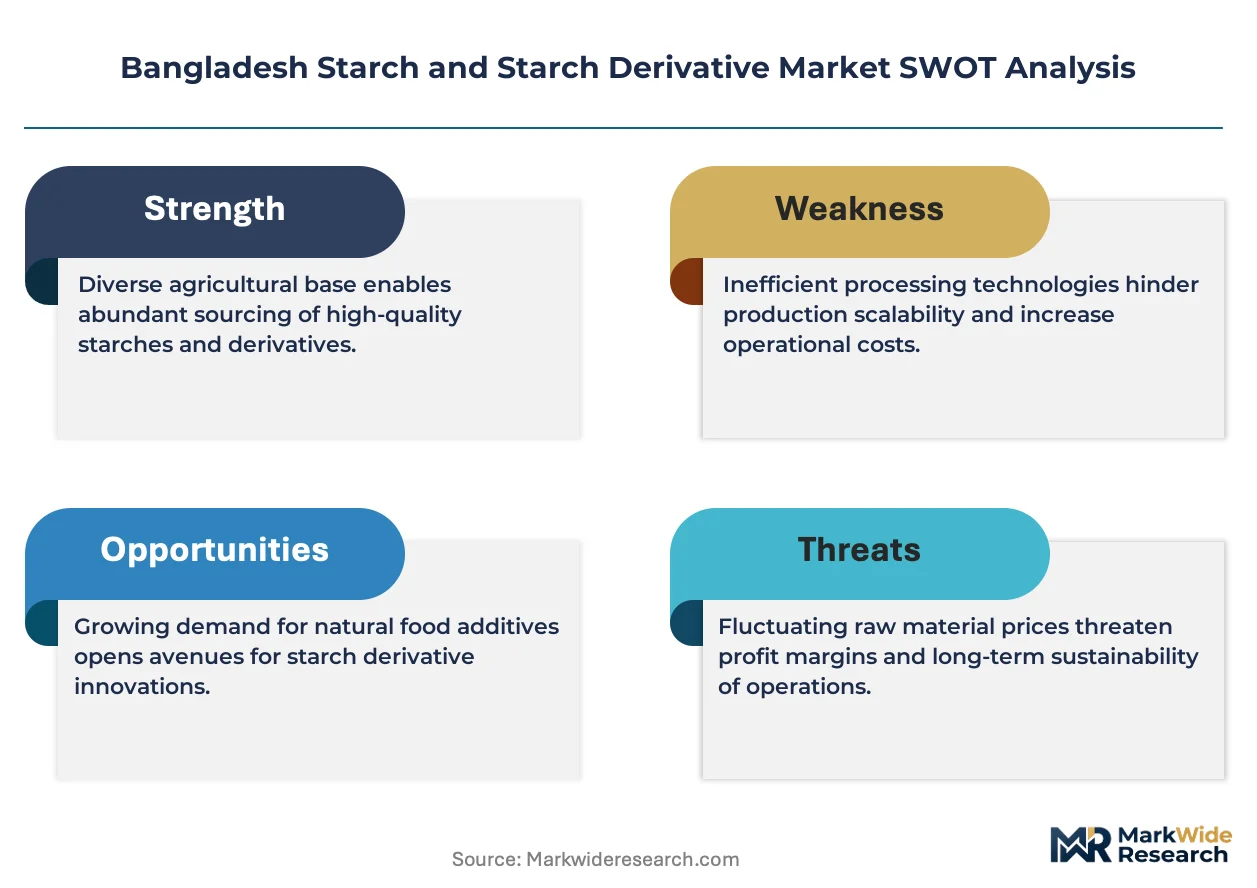
- Pharmaceutical Excipient Localization:The Bangladesh Food Safety Authority's additive purity standards restrict unmodified import channels, compelling generic drug manufacturers across Dhaka to source certified native starch from domestic wet-mills.
- Beverage Reformulation:Local soft drink bottlers are accelerating purchases of starch syrups as domestic sweetener sources, reducing reliance on imported high-fructose alternatives.
- Dhaka-Chittagong Processing Corridor:Food manufacturing clusters in these cities are scaling modified starch procurement for instant noodle and sauce applications, concentrating demand within a 300-kilometer radius.
Market Restraints
- Maize Input Volatility:Northern belt weather patterns and farmer-level collection inefficiencies create price swings for the primary feedstock, compressing margin predictability for wet-millers.
- Effluent Treatment Mandates:The Department of Environment requires capital-intensive wastewater systems for wet-milling operations, erecting barriers for new entrants lacking captive infrastructure.
- Modified Starch Technical Ceiling:Local producers struggle to achieve pharmaceutical-grade etherification consistency, forcing excipient buyers to blend domestic supply with imported premium grades.
Strategic Opportunities
- Chittagong Port Zone Expansion:Underutilized industrial land near the port offers tariff-advantaged positioning for starch derivative exporters targeting ASEAN pharmaceutical markets.
- Tablet Binder Application Growth:Local generic drug manufacturers are expanding tablet production lines, creating white space for pregelatinized starch contracts with guaranteed offtake volumes.
- Bangladesh Standards and Testing Institution Fast-Track:Accelerated BIS-equivalent certification timelines for industrial starch grades enable faster market entry against regional Thai and Indian suppliers.
Industry Challenges
- Enzymatic Modification Skill Scarcity:Wet-milling operations lack sufficient process engineers trained in alpha-amylase and glucoamylase control systems for consistent dextrose equivalent outputs.
- Legacy Equipment Integration:Retrofitting 1990s-era drying lines with automated moisture control systems requires extended downtime that conflicts with pharmaceutical contract delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Starch and Starch Derivative Market |
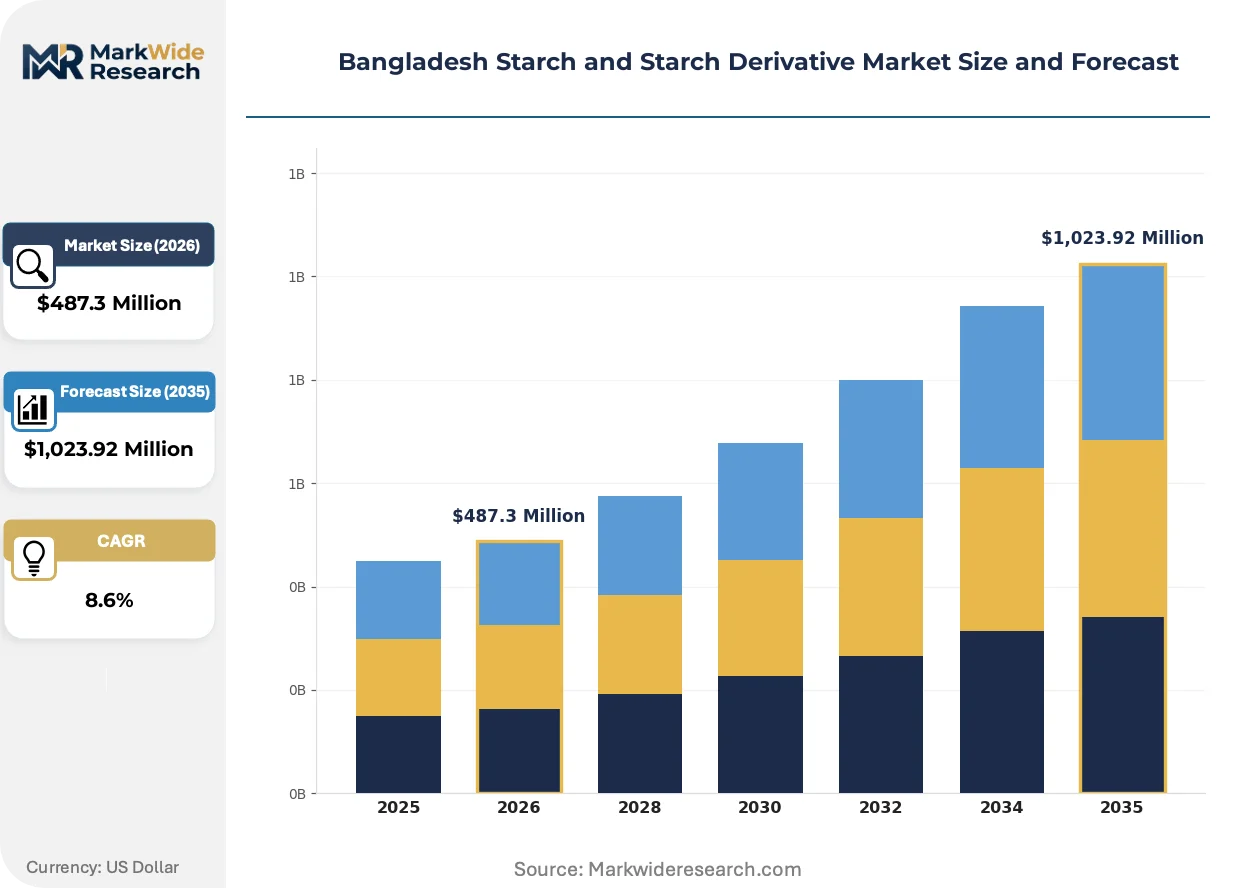
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Starch Syrups, Dextrins Application: Food Processing, Pharmaceuticals, Animal Feed, Adhesives End Use Industry: Bakery, Confectionery, Beverage, Personal Care Form: Powder, Granule, Liquid, Gel |
| Companies Covered | FLAMINGO AGRO-TECH LTD, Gulshan Polyols Limited, Maize Advanced Agro Refinery, Bangladesh Maize Products Limited, JTA Group, Paperex BD, Cargill Inc, KMC, Biswas Agro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Starch and Starch Derivative Market Strategic Shifts
Active pharmaceutical ingredient manufacturers are rewriting starch procurement specifications faster than wet-milling technology can adapt, creating a capability gap that favors first-movers in excipient-grade production.
Enzymatic modification protocols for pregelatinized starch are bifurcating the supplier base into pharmaceutical-certified specialists and commodity-grade generalists. Generic drug manufacturers in Dhaka's Tejgaon cluster now demand Certificate of Analysis documentation for every batch, forcing wet-millers to invest in in-house laboratory infrastructure or forfeit contracts. This technical split is compressing margins for undifferentiated native starch while enabling premium pricing for validated excipient grades.
The Bangladesh Food Safety Authority's tightened additive labeling rules are mandating traceability from farm to finished excipient, with compliance deadlines accelerating facility audits. Industrial starch producers must now document moisture and ash content thresholds certified by the Bangladesh Standards and Testing Institution for every production lot. Pharmaceutical formulators are responding by consolidating supplier lists to three qualified domestic mills, reducing qualification overhead while concentrating volume risk.
Tablet binder procurement is consolidating around annual framework contracts with volume guarantees, displacing spot-market purchasing that dominated the 2015-2020 period. Generic drug manufacturers are unbundling technical service from material supply, hiring independent formulation consultants rather than relying on starch vendor laboratories. This pattern is most visible in Dhaka's pharmaceutical export zone, where companies preparing for WHO prequalification are standardizing excipient sourcing to reduce audit variability.
Bangladesh Starch and Starch Derivative Market Segmentation
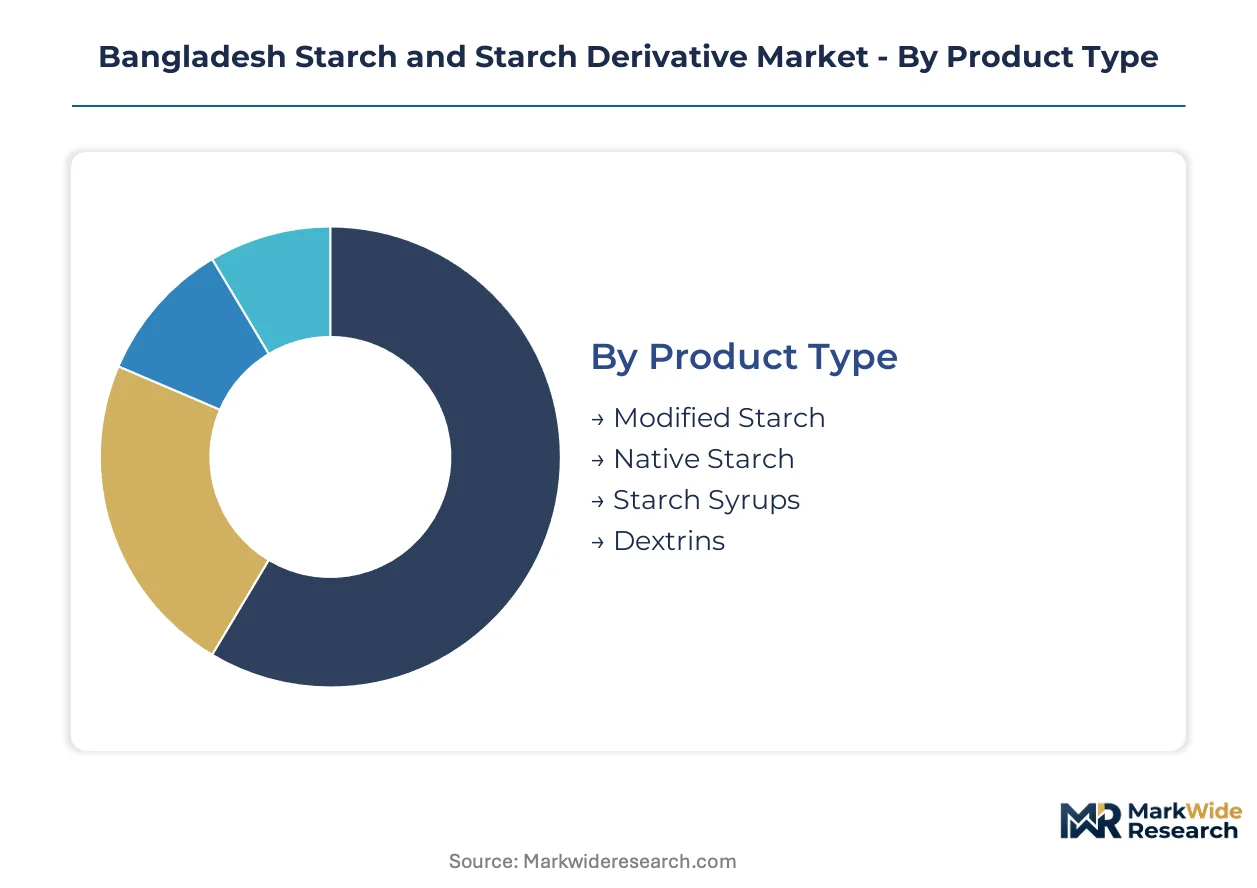
Starch derivative procurement in Bangladesh fragments across four distinct category axes, each commanding different margin profiles and certification requirements. Wet-millers prioritize product type and application tiering when allocating capital between commodity volume and pharmaceutical-grade capacity.
Product Type:
Margin pools concentrate deepest in chemically modified grades where pharmaceutical excipient certification commands premium positioning over commodity native starch.
- Modified Starch:Etherified and esterified polysaccharide variants achieve pharmaceutical-grade consistency through controlled cross-linking. Dhaka's generic drug manufacturers now specify pregelatinized grades for tablet binding, displacing textile mills as the dominant demand anchor.
- Native Starch:Unmodified amylose-amylopectin extracts from wet-milled maize serve as the volume backbone. Northern belt collection networks supply animal feed compounders and basic food processors across Rajshahi and Rangpur divisions.
- Starch Syrups:Enzymatically hydrolyzed glucose polymers with defined dextrose equivalent ratings. Beverage bottlers in Dhaka reformulate with domestic syrup sources to reduce imported high-fructose dependence.
- Dextrins:Roasted starch fragments with reduced molecular weight for adhesive applications. Industrial paperboard manufacturers in Chittagong source dextrin for corrugated bonding.
Modified starch holds installed capacity. Starch syrups are rotating up the share rankings.
Application:
Application tiering separates certified excipient supply from commodity volume, with pharmaceutical formulators now rewriting procurement specifications faster than wet-milling infrastructure can adapt.
- Food Processing:Thickening and moisture-retention functions in instant noodles, sauces, and fried snacks. Processing clusters across Narayanganj and Gazipur scale modified starch procurement for convenience food manufacturing.
- Pharmaceuticals:Tablet binding, disintegration control, and film-coating applications. The Bangladesh Food Safety Authority's additive purity standards restrict unmodified import channels, compelling domestic sourcing.
- Animal Feed:Energy-dense carbohydrate supplementation for poultry and aquaculture operations. Feed mills in Mymensingh and Comilla absorb native starch volumes from northern belt wet-mills.
- Adhesives:Dextrin and modified starch formulations for paper, textile, and woodworking bonding. Chittagong's packaging corridor sustains industrial adhesive demand.
Pharmaceutical applications capture the steepest expansion trajectory. Animal feed maintains volume dominance.
End Use Industry:
End-use fragmentation maps directly to Bangladesh's manufacturing geography, with Dhaka-Chittagong corridors concentrating premium demand while northern divisions absorb commodity flows.
- Bakery:Bread improvers and cake structuring agents using oxidized starch variants. Urban bakeries in Dhaka and Chittagong specify moisture-retention grades for extended shelf life.
- Confectionery:Gelling agents and anti-sticking powders for traditional sweets and packaged candy. Khulna's confectionery manufacturers source native starch for cost-sensitive production.
- Beverage:Starch syrup sweeteners and clouding agents for soft drinks and fruit juices. Local bottlers accelerate domestic syrup purchases under reformulation timelines.
- Personal Care:Absorbent powders and film-formers for talcum products and cosmetic creams. Small-batch manufacturers in Dhaka's consumer goods cluster import premium grades pending local certification.
Beverage end-use is climbing the fastest. Bakery maintains the broadest supplier base.
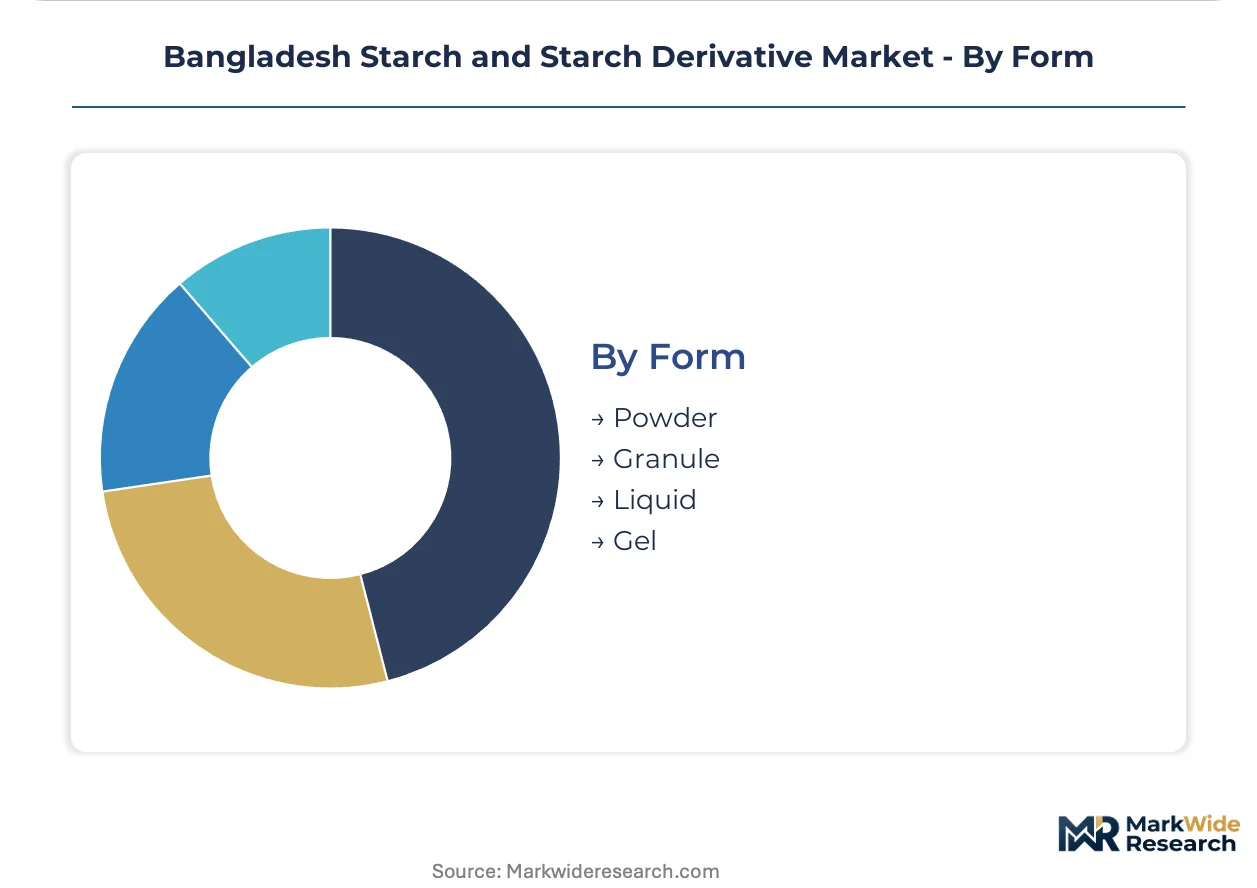
Form:
Physical form selection determines logistics economics and handling infrastructure requirements, with powder dominance eroding as liquid syrup systems gain beverage penetration.
- Powder:Dried starch with controlled particle size distribution for free-flowing applications. Pharmaceutical tablet pressing and dry food premixing sustain powder demand across Tejgaon industrial zone.
- Granule:Agglomerated starch with reduced dusting and improved dissolution. Animal feed compounders prefer granule for pelleting operations.
- Liquid:Suspended or dissolved starch systems for continuous-process manufacturing. Beverage bottlers adopt liquid syrup delivery to eliminate reconstitution steps.
- Gel:Pre-hydrated starch preparations for ready-to-use industrial applications. Textile sizing operations in Narayanganj utilize gel form for warp preparation.
Powder form holds installed capacity. Liquid form is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maize wet-milling infrastructure concentrates across Bangladesh's northern belt, while pharmaceutical formulators in Dhaka and Chittagong drive demand for certified excipient grades. Regional supply chains fragment between feedstock collection networks and finished product certification corridors.
Dhaka Division
Pharmaceutical tablet manufacturers in Tejgaon and Gazipur industrial zones scale pregelatinized starch procurement for generic drug exports. The Bangladesh Food Safety Authority enforces additive purity documentation for every production lot. Wet-millers within a 50-kilometer radius of the capital capture premium pricing through BIS-equivalent certification.
Chittagong Division
Food processing clusters in Narayanganj and the port zone absorb modified starch volumes for instant noodle and sauce applications. The Department of Environment mandates effluent treatment systems for wet-milling operations near the Karnaphuli River. Industrial adhesive manufacturers in the packaging corridor sustain dextrin demand for corrugated paperboard bonding.
Rajshahi Division
Animal feed compounders in Mymensingh and Bogra absorb native starch volumes from northern belt collection networks. Weather volatility across the maize-growing belt creates feedstock price swings that compress wet-miller margins. Farmer-level procurement inefficiencies force millers to extend collection infrastructure deeper into Rangpur division.
Khulna Division
Confectionery manufacturers in Jessore and Khulna city source cost-sensitive native starch for traditional sweet production. The Bangladesh Standards and Testing Institution certifies moisture and ash content thresholds for industrial grades entering food channels. Beverage bottlers in the division accelerate starch syrup purchases under soft drink reformulation timelines.
Barisal Division
Aquaculture feed operations across Patuakhali and Bhola districts consume native starch for shrimp and fish pellet formulations. Limited wet-milling capacity forces regional processors to rely on rail and river transport from Rajshahi division mills. The geography's fragmented infrastructure elevates logistics costs relative to Dhaka-connected buyers.
Bangladesh Starch and Starch Derivative Market Competitive Environment
Concentration sits with integrated wet-millers possessing captive maize procurement networks and pharmaceutical certification infrastructure. The supplier base fragments between excipient-grade specialists and commodity native starch producers serving animal feed channels. Three archetypes dominate: backward-integrated agricultural processors, pharmaceutical-certified derivative specialists, and regional trading houses bridging import gaps. Competitive moves center on BIS-equivalent certification acceleration and annual framework contract consolidation with generic drug manufacturers.
Within the integrated processing tier, Bangladesh Maize Products Limited and FLAMINGO AGRO-TECH LTD exemplify archetypes built on northern belt feedstock control and pharmaceutical supply relationships. Gulshan Polyols Limited occupies a derivative-specialist position focused on sorbitol-starch blends. These three anchors illustrate how certification timelines and procurement consolidation are compressing the viable supplier base toward qualified domestic mills.
| Leading Market Players |
|---|
| FLAMINGO AGRO-TECH LTD |
| Gulshan Polyols Limited |
| Maize Advanced Agro Refinery |
| Bangladesh Maize Products Limited |
| JTA Group |
| Paperex BD |
| Cargill Inc |
| KMC |
| Biswas Agro |
| Others |
Value Chain & Pricing Dynamics
Captive wet-milling capacity across Bangladesh's northern maize belt generates scale economies that compress unit costs below import-parity levels, concentrating supply power among three qualified domestic mills and establishing price floors that regional Thai and Indian suppliers struggle to undercut.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-certified, food-grade, and feed-grade levels governs contract negotiations, with Bangladesh Food Safety Authority certification tier and volume scale serving as the primary price differentiation drivers. Pricing pressure stems from maize input volatility across the northern belt, where weather-induced feedstock swings compress margin predictability for wet-millers. Animal feed compounders exhibit highest price sensitivity due to commoditized native starch sourcing, while pharmaceutical formulators accept premium positioning for excipient-grade consistency.
Supply Chain Analysis
Chittagong port congestion and container availability constraints on the Singapore-Dhaka trade lane elevate inbound logistics costs for imported modified starch grades, reinforcing domestic wet-miller competitiveness. Supply concentrates in Bangladesh, India, and Thailand, with raw material dependencies on northern belt maize, enzymatic processing inputs, and laboratory certification infrastructure. Single-source vulnerability around pharmaceutical-grade etherification capability poses structural risk. Distribution runs through direct mill-to-manufacturer contracts for certified grades, supplemented by regional trading houses for commodity native starch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh's starch market is cycling through a recovery phase anchored by pharmaceutical export expansion, as generic drug manufacturers displace textile mills as the dominant demand anchor and tighten certification requirements.
For Market Incumbents: Consolidate supplier relationships with Dhaka's Tejgaon pharmaceutical cluster through multi-year framework contracts with guaranteed offtake volumes, defending against emerging Indian excipient exporters. Accelerate BIS-equivalent certification investment to maintain three-qualified-mill status as the Bangladesh Food Safety Authority tightens additive labeling rules. Backward integration into farmer-level collection infrastructure in Rangpur division secures feedstock cost advantages.
For New Entrants and Emerging Players: Lead with pregelatinized starch specialization targeting tablet binder applications, where local generic drug manufacturers are expanding production lines and seeking qualified domestic alternatives. The beverage reformulation segment offers penetrable white space as soft drink bottlers accelerate domestic starch syrup purchases. Establish technical service partnerships with independent formulation consultants rather than competing on laboratory infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wet-millers with captive maize procurement and pharmaceutical certification infrastructure over commodity-grade generalists. Long-term viability over the next decade rests on excipient-grade production capability as import substitution timelines tighten. Monitor Bangladesh Standards and Testing Institution fast-track certification approvals as the inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Collection | Captive maize sourcing from Rangpur division insulates wet-millers against northern belt weather volatility. |
| Pharmaceutical Certification Investment | BIS-equivalent approval from Bangladesh Standards and Testing Institution unlocks premium excipient-grade pricing. |
| Long-term Supply Agreement | Annual framework contracts with Tejgaon generic drug manufacturers reduce qualification overhead and volume risk. |
| Capacity Expansion | Additional pregelatinized starch lines capture tablet binder demand from expanding Dhaka pharmaceutical exports. |
| Joint Venture | Partnerships with enzymatic modification technology providers close pharmaceutical-grade etherification capability gaps. |
Study Parameters
Operator-level perspectives from wet-milling plant managers, pharmaceutical procurement officers at generic drug manufacturers, Bangladesh Food Safety Authority regulatory inspectors, and animal feed compounder supply planners anchored the qualitative base. Primary interview findings triangulated against secondary sources including Bangladesh Standards and Testing Institution certification records, Department of Environment effluent compliance filings, customs import data for starch derivatives, and pharmaceutical export statistics. Bottom-up capacity utilization estimates across northern belt wet-mills reconciled with top-down demand projections from end-use industry consumption patterns.
Sensitivity analysis tested forecast robustness across maize price volatility scenarios, certification timeline delays, and pharmaceutical export growth trajectories over the projection horizon. Segmentation modeling incorporated product type, application tier, end-use industry, and physical form dimensions alongside regional production hub clustering. CAGRs derived from trend extrapolation of historical volume flows adjusted for structural shifts in buyer concentration and regulatory enforcement intensity. Industry-specific inputs included wet-milling capacity expansion pipelines, pharmaceutical formulation outsourcing trends, and beverage bottler reformulation commitments.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical export growth, stable northern belt maize yields, or accelerated BIS-equivalent certification timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and wet-miller technical capability progression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Genistein Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Papain Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Asia Pacific Eubiotics Market