
 Trans-Galactooligosaccharides Market | 2026-2036
Trans-Galactooligosaccharides Market Size, Share, and Industry Trends Forecast 2026-2036
Trans-Galactooligosaccharides Market Analytics
European dairy cooperative processing capacity is hardening as prebiotic ingredient demand intensifies. FrieslandCampina Ingredients leverages its Netherlands-based lactose supply chain to anchor regional production economics. Kerry Group plc sustains formulation partnerships across multiple end-use categories. Clasado Ltd specializes in precision oligosaccharide research, differentiating its Bimuno platform through targeted molecular profiles.
Trans-galactooligosaccharides comprise short-chain carbohydrates synthesized from lactose via enzymatic transgalactosylation, typically containing two to eight galactose units with terminal glucose. These non-digestible prebiotics selectively stimulate bifidobacterial growth in the human colon, serving infant nutrition, gut health supplements, and functional food fortification. Powder formulations dominate current manufacturing output due to superior stability in dry-blend applications and extended shelf compatibility. Nutraceutical applications represent the fastest-expanding consumption channel as consumers prioritize microbiome-targeted wellness. Dairy products retain the largest established volume base, though beverage integration is gaining formulation traction among major brand owners.
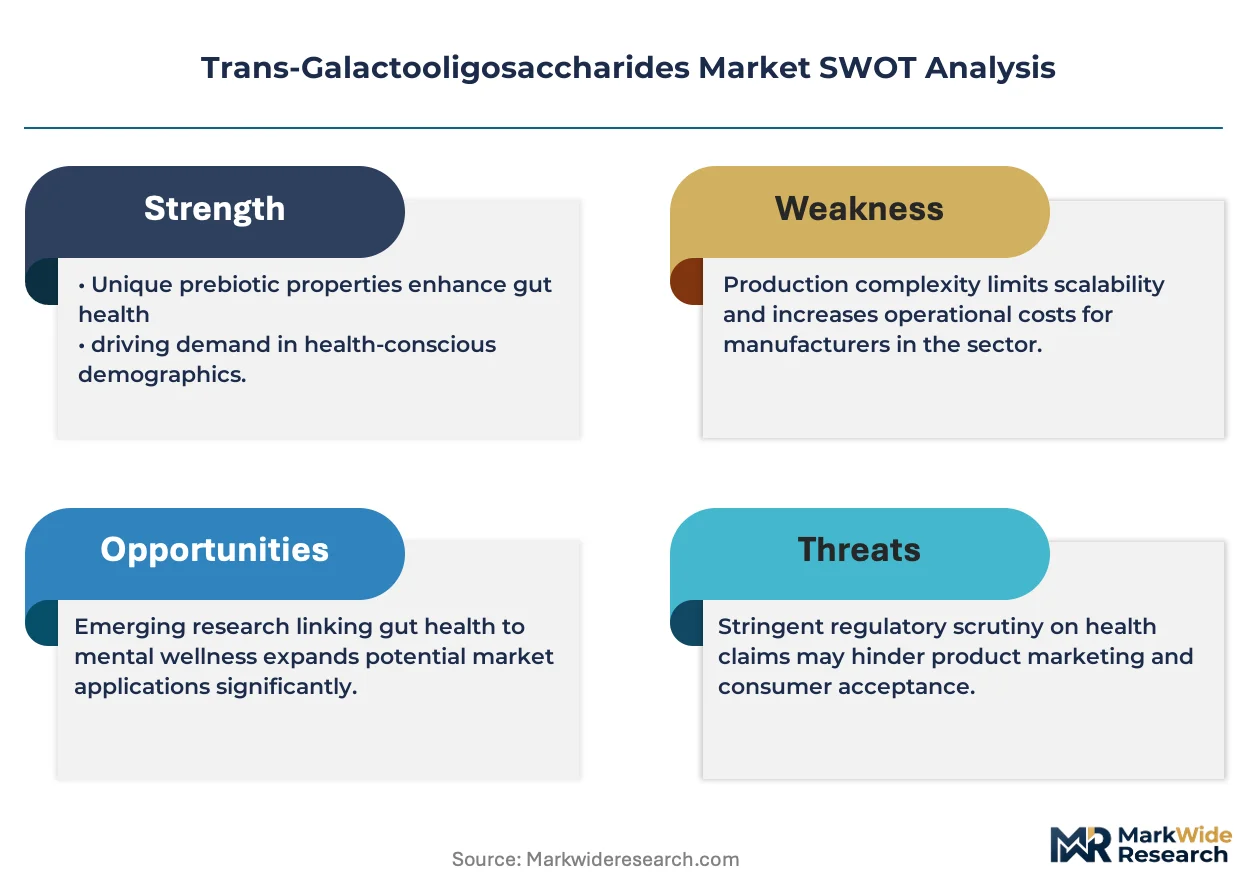
EFSA novel food assessments shape ingredient market access timelines for European suppliers, while FDA GRAS notifications govern US commercialization pathways for trans-galactooligosaccharide entrants. Japan's FOSHU regulatory framework creates distinct compliance requirements for prebiotic health claims in functional foods and beverages. Stakeholders must monitor evolving infant formula standards from Codex Alimentarius and national regulators, as tightening purity specifications and clinical substantiation demands will reshape supplier qualification criteria and capital deployment priorities across production networks.
Market Dynamics
Enzymatic transgalactosylation efficiency gains are compressing production costs while EFSA novel food pathways accelerate ingredient commercialization timelines across European supply chains.
Growth Catalysts
- EFSA Novel Food Streamlining:The European Food Safety Authority's consolidated assessment procedures reduce approval timelines for oligosaccharide suppliers, enabling faster market entry for prebiotic ingredients.
- Infant Formula Fortification:Dutch and German manufacturers are expanding prebiotic sourcing for early-life nutrition products, creating dedicated demand corridors around Rotterdam and Cologne processing clusters.
- Microbiome Research Maturation:Clinical substantiation of bifidobacterial stimulation mechanisms is strengthening health claim substantiation for gut-targeted formulations.
Market Restraints
- Lactose Feedstock Volatility:Dairy commodity price swings in European cooperative networks transmit directly to trans-galactooligosaccharide production economics.
- Enzyme Supply Concentration:Specialized β-galactosidase production remains concentrated among limited biotech suppliers, creating input bottlenecks.
- Fructooligosaccharide Substitution:FOS alternatives compete on cost and established supply chains in functional food applications.
Strategic Opportunities
- Beverage Format Expansion:Ready-to-drink wellness products in German and Dutch markets present underexploited application channels beyond traditional dairy.
- Japan FOSHU Compliance:Prebiotic health claim authorization under Japan's functional food framework creates premium positioning potential for substantiated ingredients.
- Powder-to-Liquid Conversion:Solubility-enhanced formulations are integrating into beverage manufacturing lines previously limited to dry-blend applications.
Industry Challenges
- Clinical Validation Timelines:EFSA health claim substantiation demands extended human intervention studies, compressing R&D-to-revenue cycles.
- Cross-Contamination Controls:Infant-grade purity specifications require segregated production infrastructure, elevating capital intensity for multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trans-Galactooligosaccharides Market |
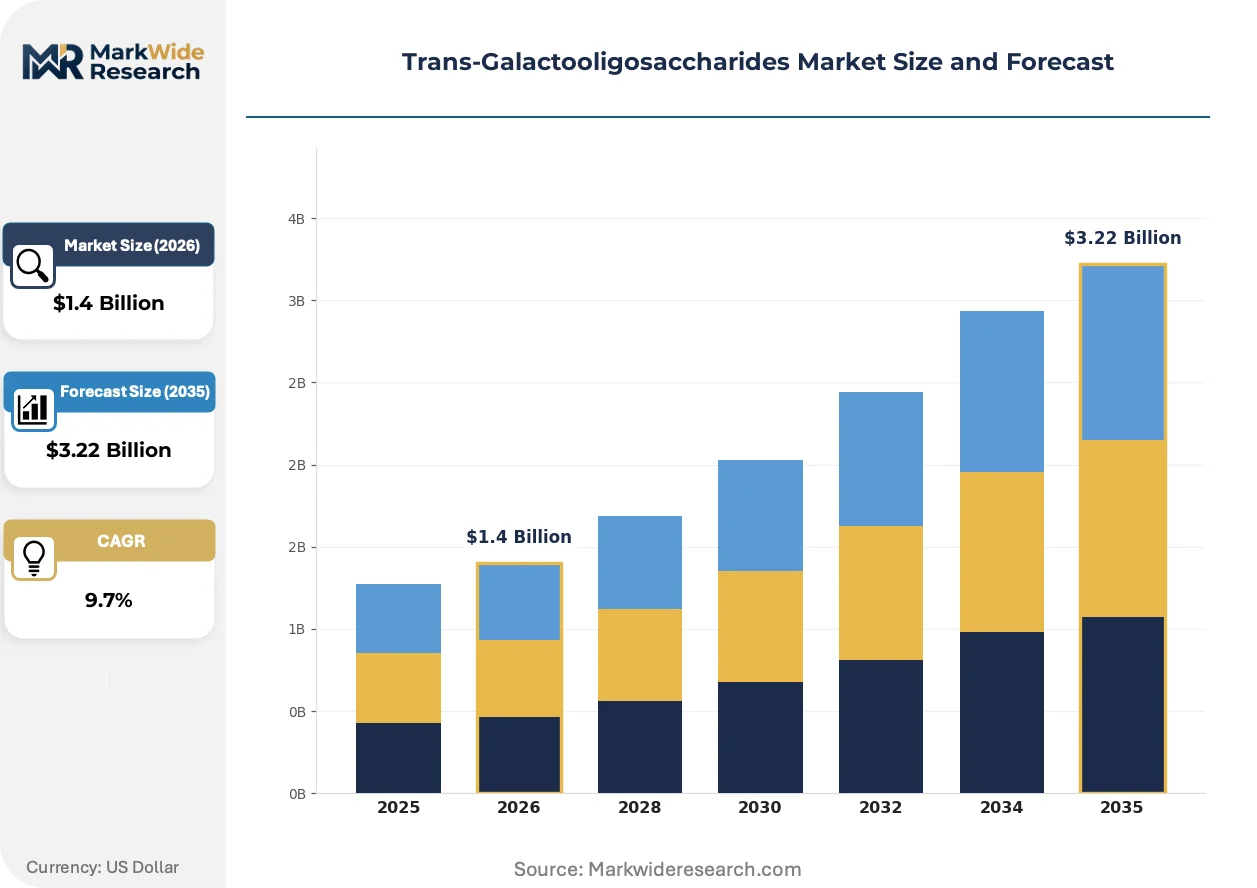
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Syrup Application: Dairy Products, Bakery Products, Nutraceuticals, Beverages End User: Food Industry, Pharmaceutical Companies, Dietary Supplement Manufacturers, Beverage Companies Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | FrieslandCampina Ingredients, Yakult Pharmaceutical Industry Co. Ltd., Kerry Group plc, Ingredion Incorporated, Clasado Ltd, Nissin Sugar Co. Ltd, Samyang Genex Co, BeneoOrafti, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trans-Galactooligosaccharides Market Evolving Landscape
Continuous enzymatic processing and precision fermentation are reshaping production economics while regulatory harmonization efforts accelerate cross-border ingredient commercialization.
Immobilized enzyme reactor systems are integrating into commercial manufacturing lines, enabling lactose conversion with reduced enzyme consumption and simplified downstream purification. Infant formula processors in the Netherlands are adopting these systems at pilot scale. The technology is integrating solvent-free production pathways that eliminate organic extraction steps, compressing capital requirements for new entrants.
REACH registration requirements for novel enzymatic catalysts are tightening substance documentation obligations for European suppliers. Industrial biotech firms are responding with expanded toxicology dossiers and exposure assessments. Powder-grade ingredient categories face the most acute compliance burdens as registrants navigate substance identity definitions for complex oligosaccharide mixtures.
Direct-to-manufacturer ingredient sourcing is displacing traditional distributor intermediaries in nutraceutical supply chains. German functional food formulators around Düsseldorf are establishing captive procurement relationships with oligosaccharide producers. This pattern concentrates most visibly in gut health supplement segments where batch traceability and certificate-of-analysis transparency command premium positioning.
Trans-Galactooligosaccharides Market Segmentation
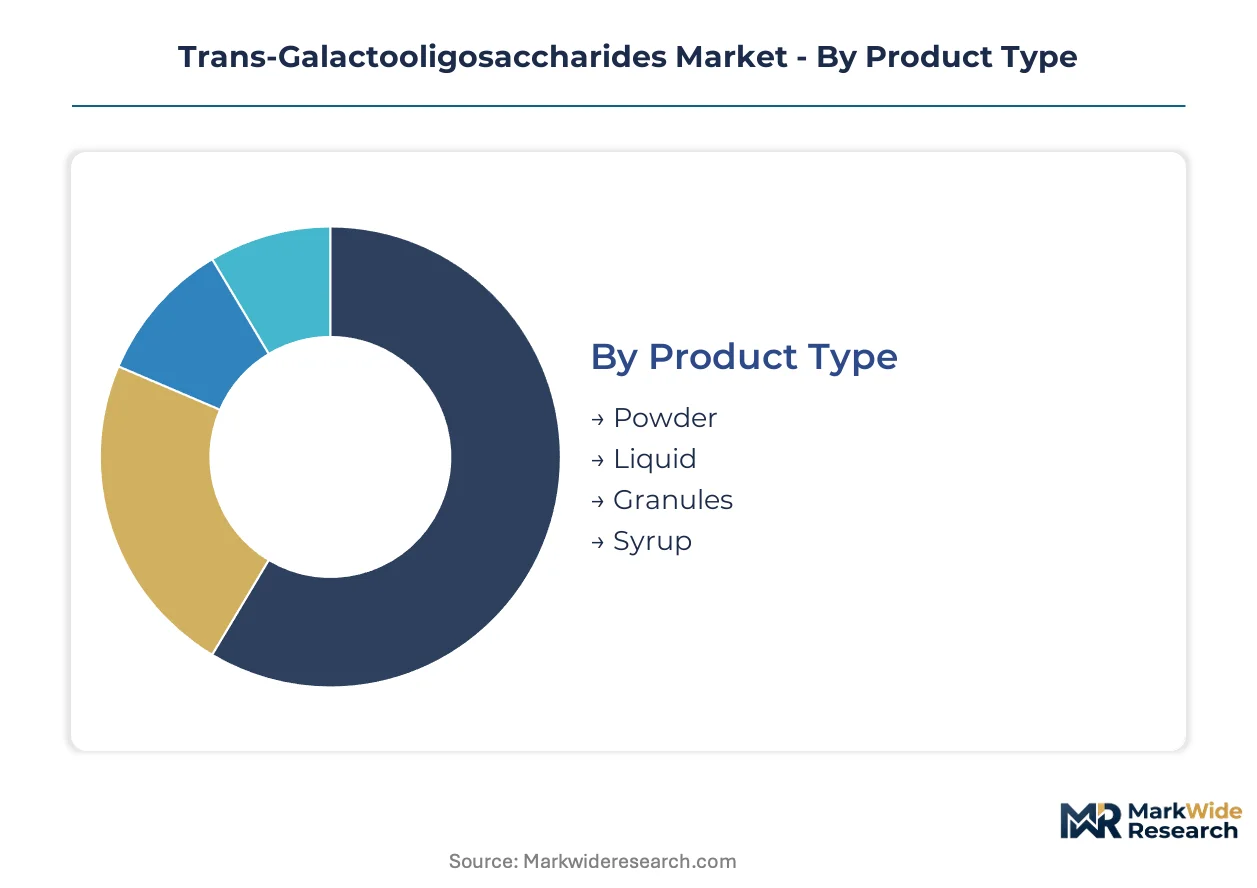
Segmentation in trans-galactooligosaccharides markets reveals how enzymatic production flexibility, formulation stability requirements, and end-use certification standards create distinct commercial corridors. Each dimension carries specific regulatory and technical constraints that reshape supplier positioning.
Product Type:
Standardization dominates powder and liquid grades, while granules and syrup formats require customized drying protocols and viscosity specifications tailored to customer integration equipment.
- Powder:Spray-dried formulations with moisture content below 5% enable extended shelf stability and seamless dry-blend incorporation into infant formula and supplement manufacturing. Dutch dairy processors around Rotterdam specify powder grades for their automated blending lines, though hygroscopicity management demands climate-controlled handling infrastructure.
- Liquid:Aqueous solutions at 70-75% solids content serve beverage fortification and liquid supplement applications where immediate solubility eliminates reconstitution steps. German functional drink manufacturers near Düsseldorf are integrating liquid TOS directly into pasteurized product streams, constrained by shorter shelf life and refrigerated distribution requirements.
- Granules:Agglomerated particles reduce dust generation during handling, addressing occupational exposure concerns in high-volume manufacturing environments.
- Syrup:Viscous concentrates suit artisanal bakery and confectionery applications requiring controlled humectant properties without powder dispersion challenges.
Growing fastest: Liquid formats in beverage integration. Leading the category by volume: Powder grades for dry-blend compatibility.
Application:
Cost tier separation runs from commodity dairy fortification through premium nutraceutical positioning, with each application carrying distinct clinical substantiation burdens and margin structures.
- Dairy Products:Infant formula represents the volume anchor, with EFSA novel food authorization enabling prebiotic claims in early-life nutrition. FrieslandCampina Ingredients leverages captive lactose supply for integrated TOS production serving Dutch and German formula manufacturers, though Codex Alimentarius purity specifications demand dedicated production lines.
- Nutraceuticals:Gut health supplements command premium pricing through targeted bifidobacterial stimulation claims supported by human intervention studies. Kerry Group plc formulates TOS into synbiotic capsules and sachets, with batch-specific certificate-of-analysis documentation replacing traditional distributor relationships in German procurement channels.
- Bakery Products:Prebiotic bread and cereal applications compete on cost with established fiber ingredients, limiting penetration outside premium positioning.
- Beverages:Ready-to-drink wellness products in German and Dutch markets present underexploited channels as solubility-enhanced formulations overcome previous dry-blend limitations.
Expanding most quickly: Nutraceuticals through microbiome wellness positioning. Dominating established volume: Dairy Products, particularly infant formula segments.
End User:
Customer type fragmentation separates multinational formulators with captive technical teams from mid-tier manufacturers relying on supplier formulation support.
- Food Industry:Large dairy and bakery manufacturers specify TOS for functional positioning in mainstream retail products, with procurement concentrated through direct supplier relationships.
- Dietary Supplement Manufacturers:Specialized gut health and synbiotic formulators drive precision oligosaccharide demand, with Clasado Ltd's Bimuno platform serving this segment through defined molecular profiles.
- Pharmaceutical Companies:Clinical nutrition and medical food applications impose pharmacopeial-grade purity requirements with extended documentation obligations.
- Beverage Companies:Functional drink specialists seek solubility-optimized grades for clear-label positioning in wellness-oriented product lines.
Concentrating procurement fastest: Dietary Supplement Manufacturers via direct-to-manufacturer sourcing. Anchoring volume demand: Food Industry integration into dairy applications.
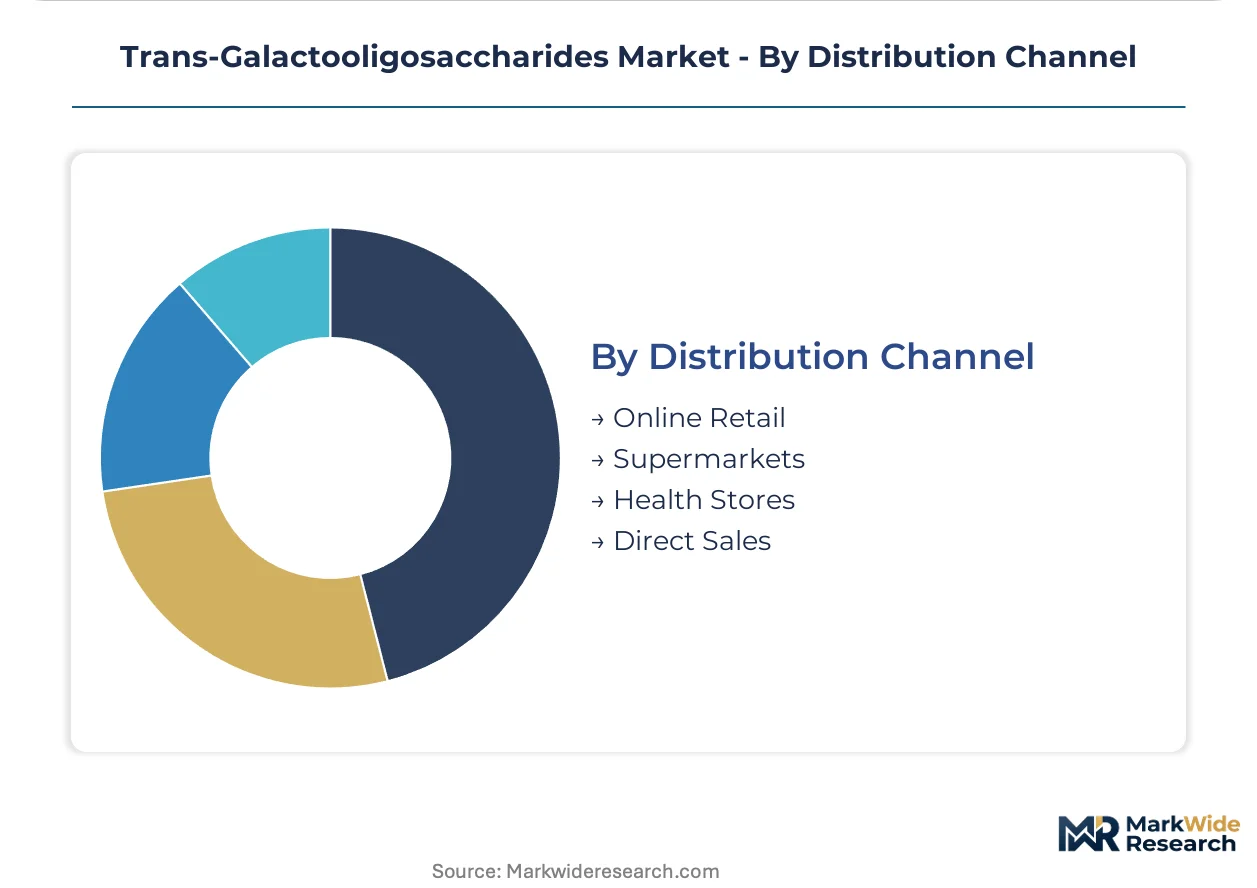
Distribution Channel:
Supply concentration varies from high-touch direct sales for infant-grade specifications to automated online procurement for standard nutraceutical grades.
- Direct Sales:Technical ingredient supply to major formulators involves dedicated account management, joint formulation development, and locked-in volume commitments. German functional food clusters around Cologne and Düsseldorf exhibit this pattern most visibly.
- Online Retail:E-procurement platforms serve mid-tier supplement manufacturers with standardized powder grades, offering batch traceability and competitive pricing transparency.
- Health Stores:Branded prebiotic ingredients reach small-scale formulators and compounding pharmacies through specialized ingredient distributors.
- Supermarkets:Limited to finished prebiotic supplements rather than bulk ingredient supply, reflecting retail channel positioning.
Displacing intermediaries fastest: Direct Sales relationships with traceability documentation. Retaining volume concentration: Online Retail for standard-grade procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European dairy cooperative networks supply the lactose feedstock anchoring trans-galactooligosaccharide production economics across multiple continents. Manufacturing concentration clusters around enzymatic processing hubs with access to specialized β-galactosidase supply chains and infant-grade certification infrastructure.
Netherlands
Rotterdam and Amsterdam harbor zones concentrate enzymatic conversion capacity serving infant formula manufacturers across the Rhine corridor. EFSA novel food authorization pathways streamline ingredient commercialization timelines for domestic suppliers. FrieslandCampina Ingredients leverages captive lactose supply from cooperative dairy networks to anchor regional production economics.
Germany
Cologne and Düsseldorf processing clusters drive functional food formulation demand for prebiotic fortification in ready-to-drink wellness products. REACH registration requirements for enzymatic catalysts tighten substance documentation obligations for industrial biotech firms. German beverage manufacturers are integrating liquid TOS grades directly into pasteurized product streams.
United States
FDA GRAS notification pathways govern commercialization timelines for trans-galactooligosaccharide entrants targeting nutraceutical and infant nutrition segments. Domestic dairy processing regions in Wisconsin and California supply lactose feedstock to enzymatic conversion facilities. Kerry Group plc maintains formulation partnerships across multiple end-use categories through US-based technical service operations.
Japan
METI oversight of FOSHU regulatory frameworks creates distinct compliance requirements for prebiotic health claims in functional foods and beverages. Yakult Pharmaceutical Industry Co. Ltd. anchors domestic bifidobacteria research linkages to oligosaccharide applications. Tokyo and Osaka metropolitan areas concentrate finished product formulation for gut health positioning.
China
SAMR and NMPA oversight of novel food ingredients shapes market access timelines for imported prebiotic suppliers. Yangtze River Delta manufacturing zones concentrate dairy processing capacity with expanding prebiotic ingredient sourcing. Domestic enzyme suppliers are scaling β-galactosidase production to reduce import dependency.
Trans-Galactooligosaccharides Market Competitive Landscape
Global majors compete with regional champions across enzymatic processing technology and infant-grade certification capabilities. Market structure tilts toward consolidated supply at the premium purity tier while standard nutraceutical grades fragment across mid-tier enzyme houses and dairy cooperative derivatives. Three archetypes dominate: captive dairy processors with backward lactose integration, specialized oligosaccharide research houses, and diversified ingredient formulators. Capacity expansion and direct-to-manufacturer procurement relationships constitute the dominant competitive moves reshaping distribution economics.
Within the captive dairy processor archetype, FrieslandCampina Ingredients represents integrated supply chain positioning through cooperative lactose access. Clasado Ltd exemplifies the specialized research house model with its UK-based precision oligosaccharide platform. Kerry Group plc occupies the diversified formulator tier with multi-category technical service capabilities spanning infant nutrition through functional beverages.
| Leading Market Players |
|---|
| FrieslandCampina Ingredients |
| Yakult Pharmaceutical Industry Co. Ltd. |
| Kerry Group plc |
| Ingredion Incorporated |
| Clasado Ltd |
| Nissin Sugar Co. Ltd |
| Samyang Genex Co |
| BeneoOrafti |
| Tate & Lyle PLC |
| Others |
Value Network & Pricing Analysis
Infant-grade certification tiers bifurcate trans-galactooligosaccharide pricing into premium and commodity strata, with EFSA novel food authorization and Codex Alimentarius purity specifications commanding substantial premiums while standard nutraceutical grades compete on volume scale. This certification ladder shapes supply chain configurations, as dedicated production lines for infant formula segments require segregated infrastructure that feeds into long-term offtake contracts with Dutch and German dairy processors.
Pricing Analysis
Certificate-of-analysis bundling separates premium infant-grade supply from unbundled standard nutraceutical procurement, with full documentation packages justifying substantial markups over bare powder grades. Three-tier pricing structure across pharmaceutical-grade, infant-formula-certified, and standard nutraceutical levels tracks purity specifications and clinical substantiation depth. Cost compression in standard nutraceutical tiers intensifies as fructooligosaccharide alternatives compete on established supply chains. Dietary supplement manufacturers exhibit highest price sensitivity, while infant formula processors prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from German functional food formulators and Dutch infant nutrition manufacturers require β-galactosidase enzyme qualification across multiple biotech suppliers, reducing single-source vulnerability. Production gravity centers on the Netherlands, Germany, and Belgium, drawing from European dairy cooperative lactose networks. Specialized enzymatic catalyst supply rests on limited industrial biotech houses, creating input concentration risk. Distribution runs through direct technical sales relationships for infant-grade segments, with e-procurement platforms serving standardized nutraceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trans-galactooligosaccharide supply is consolidating as EFSA health claim substantiation demands compress R&D-to-revenue cycles, forcing capital-constrained enzyme houses toward acquisition or exit.
For Market Incumbents: Anticipate fructooligosaccharide substitution pressure in functional food applications by deepening captive lactose supply through cooperative dairy network expansion in the Netherlands and Belgium. Prioritize REACH registration completion for novel immobilized enzyme catalysts to defend technical differentiation against emerging precision fermentation entrants. Joint formulation partnerships with German beverage manufacturers around Düsseldorf anchor volume commitments through locked-in supply agreements. For New Entrants and Emerging Players: Direct-to-manufacturer e-procurement channels offer the most penetrable entry vector for standardized nutraceutical powder grades, bypassing established distributor relationships where traceability documentation commands premium positioning. Target mid-tier dietary supplement manufacturers in German gut health clusters seeking batch-specific certificate-of-analysis transparency without incumbent technical service overhead. Solubility-enhanced liquid formulations for ready-to-drink wellness applications present white-space expansion beyond traditional dry-blend dairy fortification. For Investors and Strategic Acquirers: Re-rating potential sits with specialized oligosaccharide research houses possessing defined molecular profile platforms and EFSA novel food dossiers, given accelerating infant formula standard tightening from Codex Alimentarius. Long-term viability favors assets with backward lactose integration or precision fermentation capabilities that de-couple from dairy commodity volatility. Watch for bifidobacteria clinical substantiation pipeline advancement as the signal indicating which ingredient suppliers will capture premium health claim positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Completion | Accelerates market access timelines for prebiotic ingredient commercialization across European supply chains. |
| Immobilized Enzyme Reactor Deployment | Reduces enzyme consumption and downstream purification costs for Dutch dairy processors at pilot scale. |
| Direct-to-Manufacturer Procurement Relationships | Displaces traditional distributor intermediaries in German nutraceutical supply chains seeking batch traceability. |
| Precision Fermentation Scale-Up | De-risks lactose feedstock dependency for trans-galactooligosaccharide production economics. |
| FOSHU Regulatory Compliance Investment | Unlocks premium positioning potential in Japan's functional food and beverage health claim framework. |
Research Methodology
Independent corroboration across primary interviews with infant formula procurement directors, enzymatic processing plant managers, and regulatory affairs specialists at EFSA novel food consultancies underwrites the qualitative findings. Secondary validation draws from EFSA scientific opinions, REACH registration databases, Codex Alimentarius standards, and European dairy cooperative processing disclosures. Bottom-up triangulation across enzymatic conversion capacity and top-down demand estimation from infant nutrition and nutraceutical formulators were reconciled to anchor volume and value outputs.
Rate-of-change decomposition across the analysis window separates volume expansion from price trajectory shifts, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs were derived from enzymatic processing efficiency gains, EFSA regulatory timeline compression, and infant formula fortification intensity trends. Industry-specific forecast inputs include β-galactosidase enzyme supply expansion rates and bifidobacterial clinical substantiation pipeline maturity.
Inputs from EFSA novel food approval tracking and European dairy cooperative lactose supply disclosures were available through the study window; gaps in real-time enzyme production capacity utilization introduce uncertainty bands around near-term supply elasticity assumptions. Deviation in EFSA health claim substantiation timelines or Codex Alimentarius purity specification tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Apigenin Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Cultured Meat Market