
 Salmon Polynucleotide (PN) Market | 2026-2036
Salmon Polynucleotide (PN) Market Size, Share, and Industry Trends Forecast 2026-2036
Salmon Polynucleotide (PN) Market Insights
South Korea is fragmenting as domestic biotech firms scale salmon-derived polynucleotide extraction while competing with import channels from Italy and China. Rejuran anchors premium positioning through proprietary salmon DNA fractionation. Mastelli competes via established European distribution for tissue repair applications. PharmaResearch Products leverages vertical integration from raw material sourcing to finished ampoule production.
Salmon polynucleotide comprises fragmented DNA chains extracted from Oncorhynchus keta (chum salmon) roe or milt, typically ranging from 50 to 2000 base pairs in length, and functions primarily as a tissue regeneration biostimulator promoting fibroblast proliferation and extracellular matrix remodeling in aesthetic and wound-healing applications. The application dimension shows molecular biology and diagnostics commanding established volume, while biotechnology applications sustain the fastest trajectory as cell therapy developers integrate PN into culture media formulations. Research laboratories occupy the dominant end-user channel, though pharmaceutical companies are deepening procurement for preclinical regenerative medicine programs.
South Korea's Ministry of Food and Drug Safety and the EU Medical Device Regulation impose divergent purity and sterility benchmarks that shape cross-border product registration timelines and compliance costs. The US FDA classifies injectable polynucleotides under biologic or device pathways depending on structural claims, creating jurisdictional complexity for multi-market entrants. Stakeholders must monitor how emerging cell therapy manufacturing standards redefine raw material qualification protocols for salmon-derived nucleic acids.
Market Dynamics
EU Medical Device Regulation purity mandates are compressing supplier margins while accelerating consolidation among salmon-derived polynucleotide extractors capable of meeting injectable-grade sterility benchmarks.
Growth Catalysts
- MFDS aesthetic medicine protocols:South Korea's regulator has cleared PN-based skin rejuvenation for outpatient dermatology use, expanding reimbursable indication scope and clinic adoption rates in Seoul's Gangnam cluster.
- Cell therapy manufacturing integration:Bioprocess developers are incorporating salmon-derived polynucleotides into serum-free culture media formulations for mesenchymal stem cell expansion, creating pull-through demand from contract development organizations.
- Fibroblast proliferation mechanisms:Published dermatology research on extracellular matrix remodeling is driving physician preference for PN biostimulators over hyaluronic acid fillers in tissue regeneration protocols.
Market Restraints
- Raw material concentration:Oncorhynchus keta roe and milt sourcing concentrates in North Pacific fisheries, exposing processors to seasonal catch volatility and marine ecosystem regulatory closures.
- EU MDR compliance costs:Injectable polynucleotide reclassification as Class III medical devices imposes clinical evidence requirements that extend registration timelines and exhaust mid-cap manufacturer capital reserves.
- Enzymatic degradation limits:Unformulated PN chains exhibit rapid serum nuclease breakdown, necessitating complex encapsulation or cross-linking that degrades cost-positioning against synthetic alternatives.
Strategic Opportunities
- Wound healing extension:Diabetic ulcer and burn center procurement channels in Germany and France remain underpenetrated by salmon PN suppliers focused on aesthetic indications.
- ISO 13485 contract manufacturing:Emerging cell therapy developers lack in-house nucleic acid purification capabilities, creating white space for toll manufacturers with validated salmon DNA extraction protocols.
- CRISPR guide RNA synthesis:Fragmented salmon DNA serves as template feedstock for enzymatic generation of synthetic guide sequences, opening molecular biology supply contracts with genome editing tool developers.
Industry Challenges
- Bioprocess engineering talent scarcity:Purification of 50-2000 base pair fractions requires chromatography specialists with nucleic acid chemistry expertise that concentrates in academic and large-pharma settings.
- Endotoxin removal validation:Salmon-derived raw materials carry lipopolysaccharide contamination risks that demand costly limulus amebocyte lysate testing and affinity resin optimization for injectable-grade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salmon Polynucleotide (PN) Market |
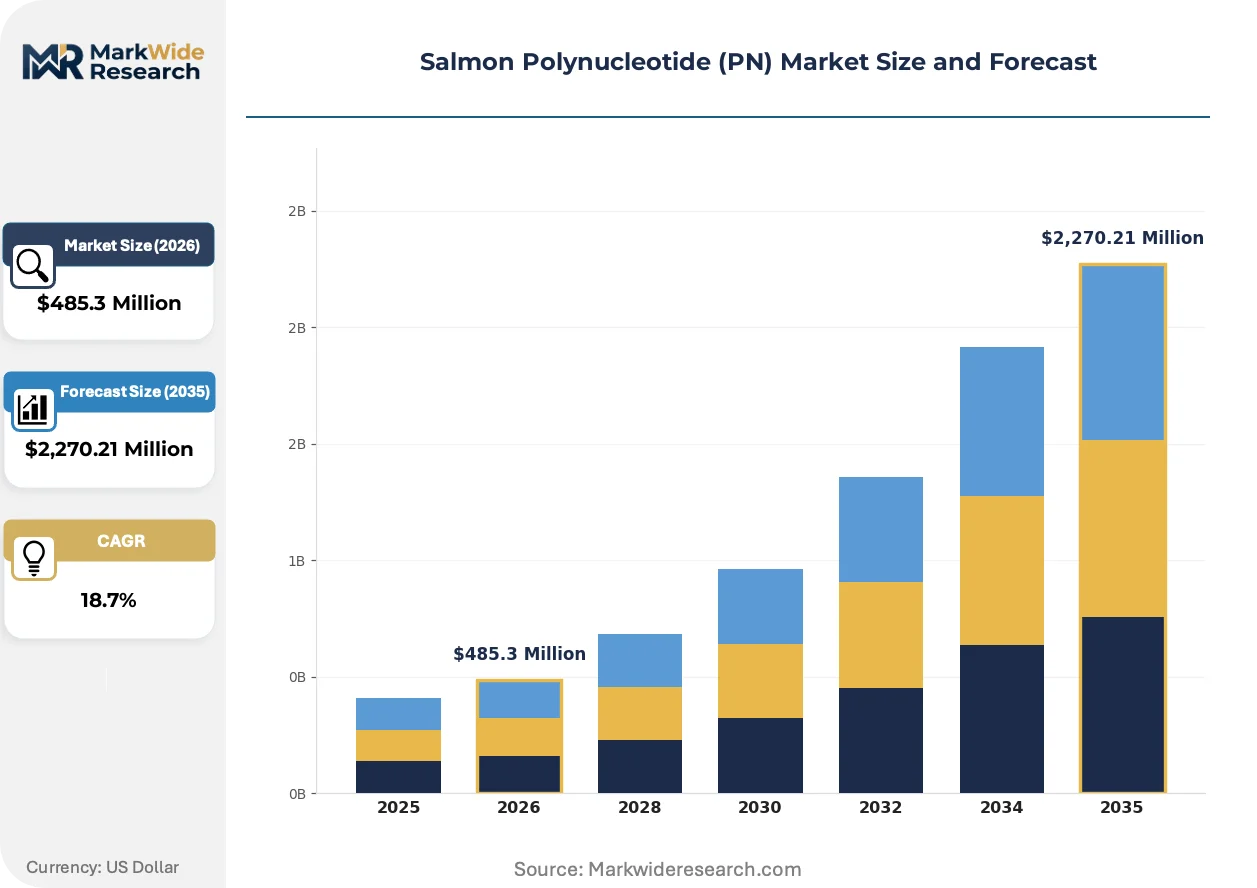
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $2,270.21 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon DNA, RNA Extracts, Enzymes, Amplification Kits Application: Molecular Biology, Genetic Research, Biotechnology, Diagnostics End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Clinical Laboratories Form: Liquid, Powder, Lyophilized, Gel |
| Companies Covered | BioPlus Co., Ltd., Rejuran, Mastelli, Caregen, ZK MEDIGROUP CO. LTD., Croma-Pharma GmbH, Ruijiming Biological, BR PHARM, PharmaResearch Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salmon Polynucleotide (PN) Market Trends and Innovations
Continuous chromatography and precision enzymatic fractionation are collapsing traditional batch-processing economics while regulatory data harmonization efforts reshape cross-border product registration strategies.
Size-exclusion chromatography paired with tangential flow filtration is collapsing the cost-structure gap between research-grade and clinical-grade polynucleotide production. Bioprocess equipment vendors in Germany and Switzerland are deploying integrated skid systems that reduce purification cycle times from days to hours. Contract manufacturers adopting these platforms are compressing quoted prices for GMP-grade salmon PN by half, enabling mid-scale cell therapy developers to internalize raw material production.
EU Medical Device Regulation Annex I general safety and performance requirements are forcing salmon PN suppliers to generate clinical data on immunogenicity and degradation kinetics that exceeds prior notified body expectations. Italian and South Korean manufacturers with legacy CE certificates face renewal cliffs requiring prospective studies. The aesthetic injectables segment is responding by consolidating formulation development with full-service CROs capable of managing MDR technical documentation.
Seoul's Gangnam clinic cluster is rotating procurement authority from individual dermatologists toward centralized purchasing consortia negotiating multi-year supply agreements. These buying groups are unbundling device-and-consumable bundles that previously locked clinics into single-source relationships. The shift is most visible among multi-location aesthetic chains expanding into Busan and Daegu, where procurement officers now demand transparent COGS breakdowns and audit rights over salmon sourcing fisheries.
Salmon Polynucleotide (PN) Market Segmentation
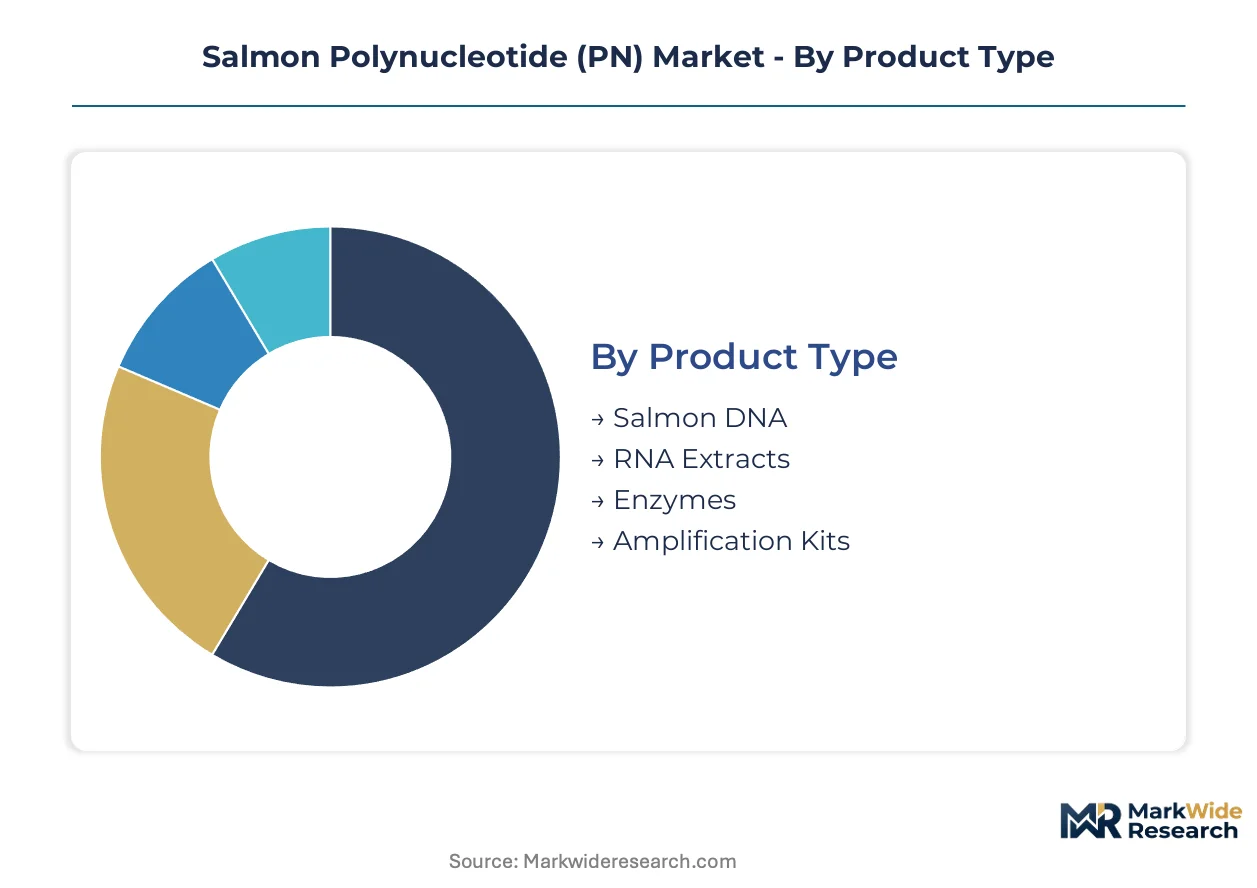
Segmentation in salmon polynucleotide markets reveals how purification grades, application protocols, and end-user sophistication stratify procurement requirements. Each dimension carries distinct regulatory burdens and pricing elasticity that shape supplier positioning.
Product Type:
Cost tier stratification in salmon-derived nucleic acids separates research-grade from clinical-grade purification standards, with endotoxin limits and chain-length precision driving price multiples.
- Salmon DNA:Fragmented double-stranded chains from Oncorhynchus keta roe, typically 50-2000 base pairs, undergo size-exclusion chromatography to meet injectable-grade specifications. Seoul's Gangnam aesthetic clinic cluster consumes premium fractions for fibroblast proliferation protocols, with MFDS clearance accelerating outpatient dermatology adoption.
- RNA Extracts:Single-stranded transcripts require more stringent cold-chain handling and RNase-free processing environments. Cell therapy developers in Germany and Switzerland integrate salmon-derived RNA into mesenchymal stem cell culture media, creating pull-through demand from contract manufacturing organizations lacking in-house extraction capabilities.
- Enzymes:Restriction endonucleases and polymerases purified from salmon tissue support molecular biology workflows.
- Amplification Kits:Pre-formulated PCR and isothermal amplification reagents reduce protocol development burden for diagnostic laboratories.
Salmon DNA commands the established base. The steepest expansion runs through RNA extracts.
Application:
Application maturity across salmon PN markets spans commoditized research consumables through emerging therapeutic bioprocessing, with regulatory complexity escalating at each tier.
- Molecular Biology:Established protocols for PCR, cloning, and sequencing consume standardized 50-500 base pair fractions with minimal purity requirements. Research laboratories in South Korea and Italy represent volume anchors, though price compression from synthetic oligonucleotide alternatives constrains margin expansion.
- Biotechnology:Serum-free cell culture media formulations and regenerative medicine applications demand GMP-grade material with validated endotoxin removal. EU MDR Annex I requirements for injectable polynucleotides impose clinical evidence burdens that favor suppliers with backward integration into fishery sourcing.
- Genetic Research:CRISPR template generation and gene expression studies utilize mid-tier purified fractions.
- Diagnostics:Nucleic acid amplification tests for infectious disease and oncology companion diagnostics require lot-to-lot consistency.
Molecular biology anchors current procurement volumes. Biotechnology gains share fastest as cell therapy manufacturing scales.
End User:
Customer type determines specification stringency, with pharmaceutical companies imposing the most exhaustive supplier qualification protocols.
- Research Laboratories:Academic and government facilities prioritize catalog breadth and technical support over certification depth. Procurement concentrates through distributors serving the EU and South Korea, with price sensitivity limiting adoption of clinical-grade material for exploratory protocols.
- Pharmaceutical Companies:Preclinical regenerative medicine programs and cell therapy developers require auditable supply chains from North Pacific fisheries through GMP finishing. EU MDR technical documentation and MFDS registration dossiers demand dedicated regulatory affairs investment that excludes smaller suppliers.
- Academic Institutions:Grant-funded research groups balance reagent cost against publication-grade reproducibility.
- Clinical Laboratories:Diagnostic service providers seek ISO 13485-certified material for in-house assay development.
Research laboratories dominate transaction volume. Pharmaceutical companies drive the steepest specification escalation.
Form:
Physical presentation of salmon polynucleotides trades stability against reconstitution convenience, with cold-chain economics shaping geographic reach.
- Liquid:Ready-to-use formulations suit high-throughput automated platforms in clinical diagnostic settings. South Korean aesthetic clinics prefer liquid ampoules for immediate injection, though shelf-life limitations restrict export radius from manufacturing sites.
- Lyophilized:Freeze-dried presentation eliminates cold-chain burden for international shipment to cell therapy developers in Germany and Switzerland. Reconstitution protocols add preparation time but enable ambient distribution to research laboratories lacking ultralow-temperature infrastructure.
- Powder:Bulk unpurified or partially purified material supports toll manufacturing relationships.
- Gel:Cross-linked formulations extend residence time for tissue regeneration applications.
Liquid formats capture the installed base. Lyophilized presentations climb fastest as cross-border cell therapy supply chains mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Pacific fisheries supply raw Oncorhynchus keta material to processing clusters in South Korea, Italy, and China. Regulatory divergence between MFDS, EMA, and FDA pathways fragments registration strategies and shapes where clinical-grade manufacturing concentrates.
South Korea
Seoul's Gangnam aesthetic clinic cluster drives injectable PN consumption for fibroblast proliferation protocols. MFDS clearance of outpatient dermatology applications accelerated clinic adoption rates. PharmaResearch Products and BR PHARM anchor domestic manufacturing with backward integration into fishery sourcing.
Italy
Mastelli sustains European distribution networks for tissue repair applications through established CE-marked pathways. EMA's tightening MDR Annex I requirements force clinical evidence generation on immunogenicity profiles. Milan-based formulation specialists consolidate technical documentation with full-service CROs.
Germany
Cell therapy developers in Heidelberg and Cologne integrate salmon-derived PN into mesenchymal stem cell culture media. ISO 13485 contract manufacturers serve bioprocess developers lacking in-house nucleic acid purification. Bavarian equipment vendors deploy integrated chromatography skids that collapse GMP-grade production cycle times.
China
Ruijiming Biological and Zhengzhou-area extractors scale salmon DNA fractionation for domestic aesthetic and research markets. NMPA biologic classification pathways for injectable polynucleotides remain less defined than device routes. Yangtze River Delta toll manufacturers develop validated extraction protocols for export-bound cell therapy supply chains.
United States
FDA jurisdictional splits between biologic and device pathways for injectable PN create registration complexity for multi-market entrants. Boston and San Diego regenerative medicine clusters import GMP-grade material for preclinical programs. US-based CMOs lack domestic salmon-derived nucleic acid purification capacity, forcing reliance on Asian and European suppliers.
Salmon Polynucleotide (PN) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. South Korean and Italian manufacturers dominate clinical-grade supply through captive fishery relationships and validated purification protocols. Three archetypes define competitive positioning: vertically integrated biotech firms with raw material control, European distributors leveraging legacy CE certificates, and Chinese toll manufacturers scaling research-grade output. Consolidation accelerates as EMA MDR compliance costs exhaust mid-cap capital reserves, while strategic partnerships between extractors and cell therapy developers lock in multi-year supply agreements.
Among South Korea-based integrated producers, PharmaResearch Products and BR PHARM exemplify the backward-integrated archetype with control from Oncorhynchus keta sourcing through finished ampoule production. Mastelli occupies a position representing European distribution strength for tissue repair applications. Rejuran anchors premium-tier positioning through proprietary salmon DNA fractionation technology. These three patterns—captive supply, continental distribution, and premium formulation—illustrate how competitive advantage crystallizes around regulatory navigation capability and fishery access rather than manufacturing scale alone.
| Leading Market Players |
|---|
| BioPlus Co., Ltd. |
| Rejuran |
| Mastelli |
| Caregen |
| ZK MEDIGROUP CO. LTD. |
| Croma-Pharma GmbH |
| Ruijiming Biological |
| BR PHARM |
| PharmaResearch Products |
| Others |
Pricing and Supply Chain Analysis
Busan-to-Rotterdam refrigerated container lanes carry Oncorhynchus keta-derived polynucleotides whose freight volatility directly compresses margin structures for mid-tier extractors while amplifying price spreads between GMP-certified and research-grade tiers.
Pricing Analysis
EU MDR Annex I dictates the pricing tier structure across injectable-grade salmon polynucleotide markets. Three-tier pricing separates GMP-certified clinical material from ISO-standard research fractions and bulk unpurified feedstock. Price differentiation hinges on endotoxin certification depth and fishery-to-facility traceability documentation. Cost compression in the research-grade segment is intensifying because synthetic oligonucleotide substitutes erode volume commitments. Academic laboratories exhibit highest price sensitivity; cell therapy developers demonstrate lowest sensitivity due to regulatory qualification lock-in costs.
Supply Chain Analysis
Tariff exposure between South Korea and China dominates supply chain risk calculus for salmon polynucleotide processors. Raw material sourcing concentrates in Russia, Japan, and Alaska fisheries. Extraction depends on chromatography resins, pharmaceutical-grade ethanol, and cold-chain logistics infrastructure. Single-source vulnerability characterizes validated GMP finishing capacity. Distribution runs through Seoul's Gangnam clinic consortia, Heidelberg cell therapy clusters, and Milan-based CRO formulation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The salmon polynucleotide market is recovering from a cyclical trough driven by EU MDR compliance cost absorption periods that forced mid-cap manufacturer consolidation.
For Market Incumbents: Pre-empt synthetic nucleic acid displacement by locking multi-year supply agreements with cell therapy developers before CRISPR guide RNA synthesis commoditizes fragmented DNA feedstock. Capture fishery sourcing rights in North Pacific waters ahead of marine ecosystem regulatory closures. Backward integration into precision enzymatic fractionation equipment insulates against German and Swiss bioprocess vendor pricing power. For New Entrants and Emerging Players: Pursue toll manufacturing contracts with ISO 13485 certification for cell therapy developers lacking in-house nucleic acid purification capabilities. Diabetic ulcer procurement channels in France and Germany remain the most penetrable wound-healing segment. Lead with transparent COGS breakdowns and audit rights over salmon sourcing fisheries to dislodge incumbent clinic relationships. For Investors and Strategic Acquirers: Contract manufacturers with validated salmon DNA extraction protocols and existing GMP infrastructure represent the highest-conviction acquisition archetype. Long-term viability rests on regulatory navigation capability rather than manufacturing scale alone. Watch for MFDS aesthetic medicine protocol expansions beyond Seoul's Gangnam cluster as the inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Consolidation | Italian and South Korean manufacturers with legacy CE certificates face renewal cliffs requiring prospective immunogenicity studies. |
| Continuous Chromatography Platform Deployment | German and Swiss equipment vendors collapse purification cycle times from days to hours for GMP-grade production. |
| Backward Integration into Fishery Sourcing | PharmaResearch Products and BR PHARM anchor competitive positioning through captive Oncorhynchus keta supply. |
| CRISPR Guide RNA Synthesis Supply Contracts | Fragmented salmon DNA templates open molecular biology supply relationships with genome editing tool developers. |
| Centralized Clinic Procurement Consortium Formation | Seoul's Gangnam aesthetic chains unbundle device-and-consumable bundles and demand transparent cost breakdowns. |
Research Methodology
Desk research of MFDS registration dossiers, EU MDR technical documentation, and fishery catch statistics preceded structured interviews with cell therapy bioprocess directors, dermatology clinic procurement officers, chromatography equipment vendors, and GMP contract manufacturing quality leads. Secondary validation drew from clinical trial registries, seafood trade databases, and bioprocess engineering literature. Bottom-up demand modeling triangulated against top-down regulatory pathway analysis.
Assumptions held fixed include current EU MDR Annex I enforcement intensity and MFDS aesthetic medicine protocol scope; varied assumptions encompass marine ecosystem regulatory closure severity and CRISPR template synthesis adoption curves. The analytical framework segmented by purification grade, application protocol, end-user sophistication, and physical presentation form across the analysis window. CAGRs derived from logistic diffusion curves fitted to clinic adoption rates and cell therapy manufacturing scale-up trajectories. Industry-specific inputs included limulus amebocyte lysate testing cost trends and size-exclusion chromatography yield improvements.
Sensitivities concentrate around EU MDR clinical evidence requirement tightening and North Pacific fishery quota reductions. Forecasts reflect assumptions about regulatory harmonization progress and bioprocess equipment depreciation cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Genistein Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Biotech Flavors Market