
 Bovine Colostrum Market | 2026-2036
Bovine Colostrum Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Colostrum Market Analysis
New Zealand's dairy processing infrastructure is reconfiguring global colostrum supply availability as processors expand fractionation capacity. PanTheryx, Inc. leverages vertical integration from farm-level collection to finished ingredient manufacturing. Glanbia PLC anchors premium nutritional ingredient supply through controlled dairy cooperative sourcing. NOW Foods competes on brand recognition and broad retail distribution across North American health channels.
Bovine colostrum constitutes the antibody-rich mammary secretion produced by cows during the first 72 hours post-calving, containing immunoglobulin G concentrations typically exceeding 15% by mass alongside growth factors and antimicrobial peptides; manufacturers employ low-temperature spray drying or freeze-drying to preserve bioactive protein integrity for human and animal nutritional applications. Dried powder formulations dominate ingredient supply due to superior shelf stability and formulation flexibility across downstream products. Sports nutrition end users represent the fastest-expanding demand pool as functional recovery positioning displaces commodity protein alternatives. Immune support applications command premium positioning through clinically substantiated immunoglobulin content claims.
FDA New Dietary Ingredient notifications and EFSA health claim substantiation requirements create divergent compliance pathways that filter market entrants by technical documentation capability. ISO 17025 laboratory accreditation and WHO Codex Alimentarius dairy hygiene standards further constrain supplier qualification for international ingredient trade. Stakeholders must monitor evolving immunoglobulin assay standardization and emerging gut microbiome clinical evidence to sustain premium positioning against commoditizing protein alternatives.
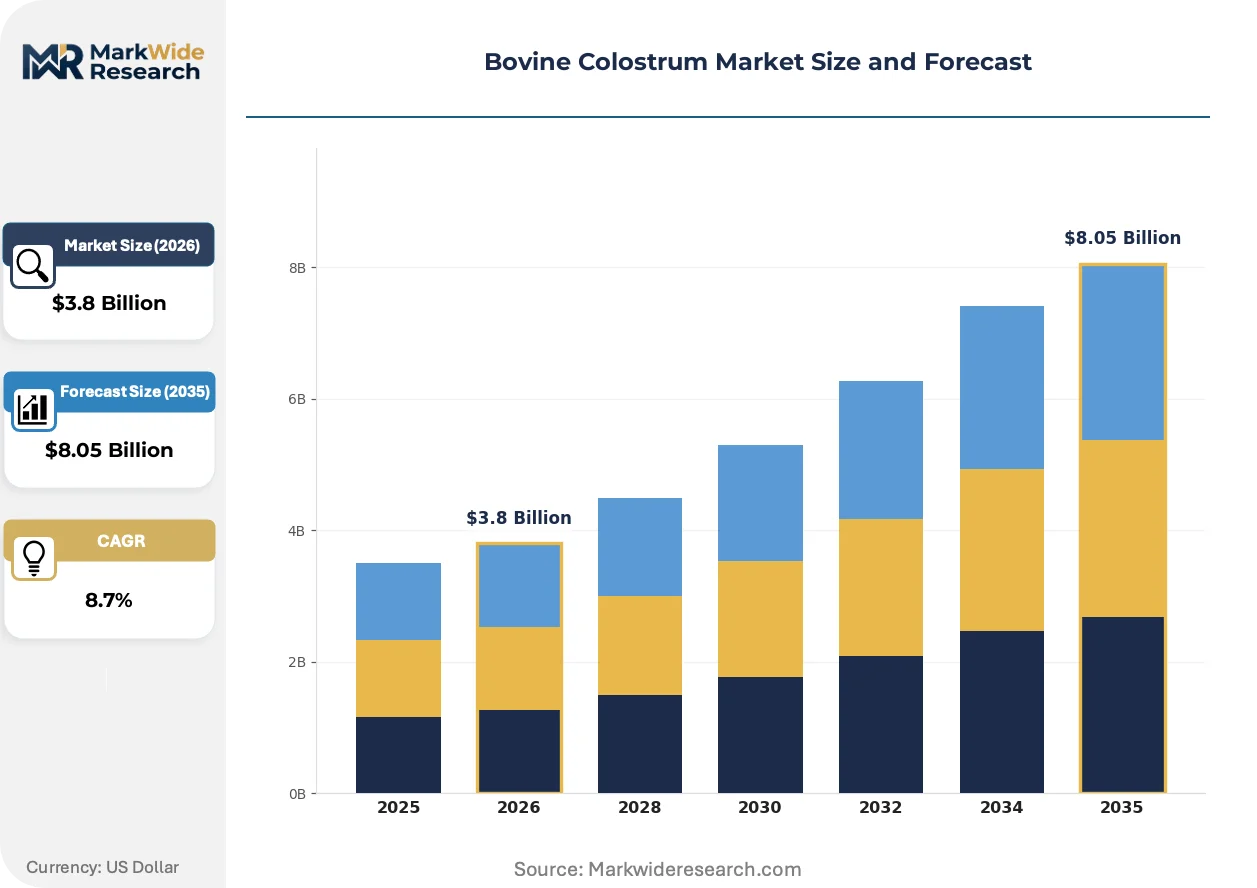
Market Dynamics
Fractionation capacity expansion across New Zealand's dairy processing infrastructure is redistributing global supply availability while sports nutrition brands accelerate colostrum-based formulation development for athlete recovery positioning.
Growth Catalysts
- Sports Nutrition End-Use Expansion:Functional recovery positioning in athletic supplements is displacing commodity protein alternatives. Immunoglobulin-rich formulations command premium shelf placement in direct-to-consumer channels.
- Immune Support Clinical Substantiation:EFSA health claim substantiation requirements are filtering market entrants by technical documentation capability. Validated immunoglobulin content claims sustain pricing power against generic alternatives.
- Controlled Dairy Cooperative Sourcing:Premium nutritional ingredient suppliers anchor supply security through backward integration into farm-level collection networks. This upstream control ensures consistent bioactive protein integrity.
Market Restraints
- FDA New Dietary Ingredient Notification Friction:Pre-market notification requirements for novel ingredients create extended compliance timelines and documentation costs that disadvantage smaller entrants lacking regulatory affairs infrastructure.
- Seasonal Raw Material Concentration:First 72-hour post-calving collection windows constrain annual production volumes. Supply concentrates in Northern Hemisphere spring calving periods, creating inventory management complexity.
- Plant-Based Protein Substitution:Fermented and precision fermentation-derived alternatives are capturing immune-support positioning in mass-market channels, pressuring bovine-derived ingredient volume in price-sensitive segments.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Traditional Chinese Medicine integration pathways and rising functional food expenditure in South Korea create expansion vectors for clinically positioned colostrum ingredients.
- Gut Microbiome Clinical Evidence:Emerging research on antimicrobial peptides and growth factor interactions with intestinal flora supports new positioning beyond immune modulation into digestive health applications.
- Specialized Health Retail Channel Development:Practitioner-exclusive distribution and compounded pharmacy integration enable premium pricing outside commoditized mass-market protein positioning.
Industry Challenges
- Immunoglobulin Assay Standardization Gaps:Inconsistent analytical methods across ISO 17025 laboratories create batch-to-batch variability disputes between suppliers and finished product manufacturers.
- Cold Chain Integrity for Liquid Concentrates:Temperature excursion risks during international shipping of non-dried formulations limit market penetration in regions lacking pharmaceutical-grade logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Colostrum Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Powder, Capsules, Liquid, Chewable Tablets End User: Healthcare, Sports Nutrition, Supplements, Animal Feed Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales Application: Immune Support, Gut Health, Muscle Recovery, Nutritional Supplements |
| Companies Covered | PanTheryx, Inc., Glanbia PLC, NOW Foods, Biostrum Nutritech Pvt. Ltd., Colostrum BioTec GmbH, APS BioGroup, Ingredia SA, Saskatoon Colostrum Company Ltd., SwissBioColostrum AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Colostrum Market Emerging Trajectories
Low-temperature processing technologies and assay standardization efforts are converging to redefine quality differentiation mechanisms while regulatory documentation requirements reshape competitive entry barriers.
Microfiltration and low-temperature spray drying systems are collapsing the traditional trade-off between bioactive protein preservation and manufacturing throughput. Sports nutrition contract manufacturers are retrofitting production lines to accommodate these gentler processing parameters. The technology is collapsing cost structures for mid-tier suppliers previously dependent on freeze-drying capacity constraints.
EFSA health claim substantiation requirements are tightening evidentiary standards for immunoglobulin content declarations on finished products. Manufacturers must now commission human intervention studies rather than relying on compositional analysis alone. European sports nutrition brands are responding by consolidating supplier relationships around vertically integrated processors with captive clinical research capabilities.
Direct-to-consumer subscription models are displacing traditional health food store distribution for premium colostrum formulations. Athlete influencers and functional medicine practitioners are driving trial through educational content rather than retail shelf presence. This channel rotation is most visible in United States and Australian markets where telehealth integration enables practitioner-supervised dispensing.
Bovine Colostrum Market Segmentation
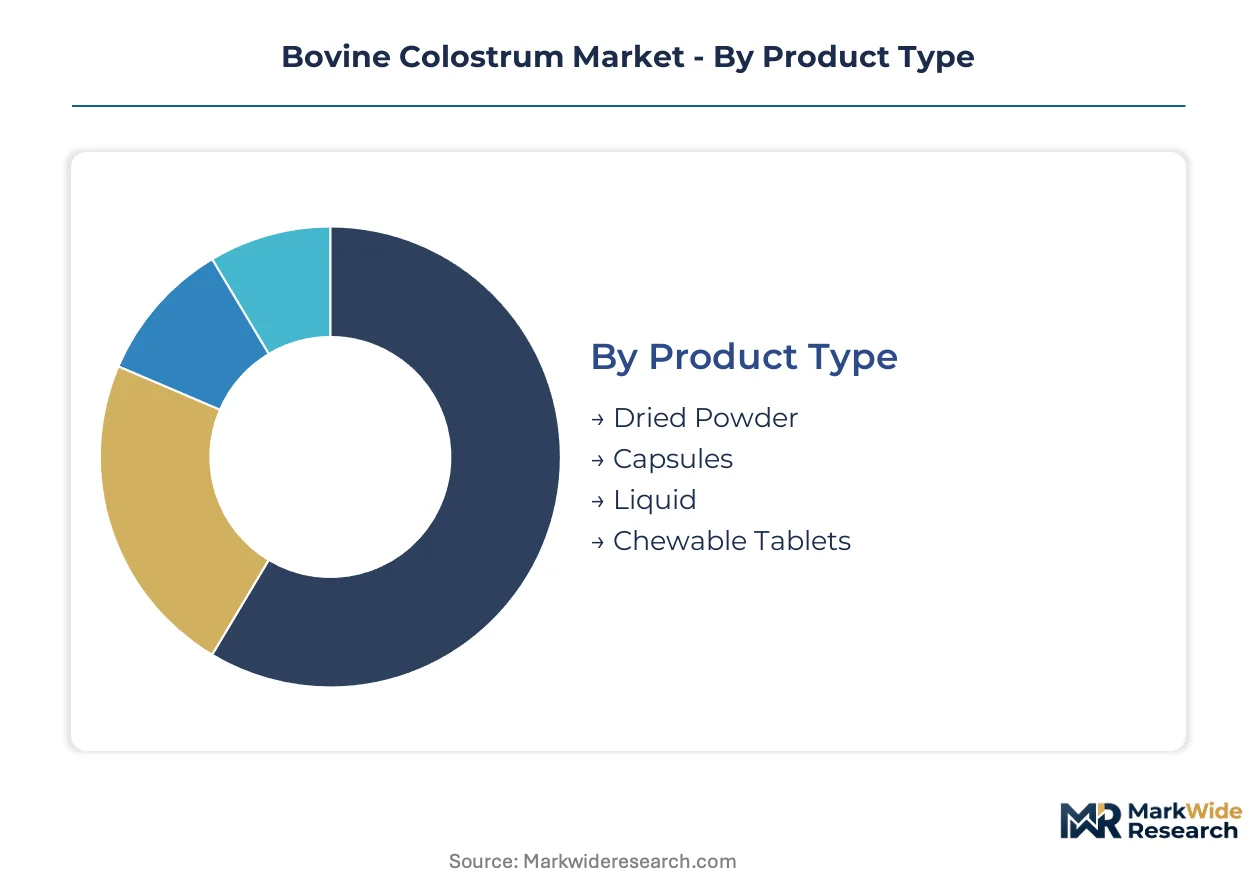
Bovine colostrum's bioactive protein fragility creates sharp formulation trade-offs across delivery formats. Each segment carries distinct cold-chain requirements, shelf-stability profiles, and regulatory substantiation burdens that reshape competitive entry costs.
Product Type:
Mature drying technologies anchor the bulk of commercial volume, while emerging delivery formats target convenience-seeking consumer segments with differentiated absorption claims.
- Dried Powder:Low-temperature spray-dried or freeze-dried concentrates preserve immunoglobulin G integrity above 80% retention, enabling bulk ingredient supply to sports nutrition contract manufacturers and functional food formulators. Demand concentrates in North American direct-to-consumer channels where athletes blend unflavored powders into recovery shakes.
- Capsules:Encapsulation protects bioactive peptides from gastric degradation while enabling precise dosing for immune support positioning; South Korean and Australian markets show concentrated uptake among practitioner-supervised protocols requiring compliance tracking.
- Liquid:Refrigerated concentrates retain native protein structures but require pharmaceutical-grade cold chain logistics that limit distribution to urban clusters with reliable infrastructure.
- Chewable Tablets:Palatability-focused formats target pediatric and geriatric compliance segments where swallowing difficulties constrain capsule adoption.
Dried powder retains volume leadership; chewable tablets hold the steepest expansion curve.
End User:
Application maturity varies sharply by clinical substantiation depth and regulatory pathway clarity.
- Healthcare:Hospital and clinical settings leverage colostrum for immunocompromised patient protocols, requiring FDA New Dietary Ingredient documentation or EFSA health claim validation for institutional procurement approval.
- Sports Nutrition:Functional recovery formulations displace commodity whey in premium athlete segments; immunoglobulin-rich positioning commands shelf placement in United States and United Kingdom specialty retail.
- Supplements:Mass-market immune support SKUs compete with fermented alternatives on price-per-serving metrics in price-sensitive channels.
- Animal Feed:Calf nutrition and companion animal applications utilize lower-grade colostrum fractions excluded from human-grade specifications.
Sports nutrition is climbing the fastest; animal feed maintains baseline volume absorption.
Distribution Channel:
Channel economics reflect customer acquisition cost divergence between digital-native and brick-and-mortar infrastructures.
- Online Retail:Subscription models and athlete influencer partnerships drive trial in United States and Australian markets where telehealth integration enables practitioner-supervised dispensing.
- Pharmacies:Behind-the-counter positioning in Germany and Switzerland requires pharmaceutical-grade GMP certification that filters supplier qualification.
- Health Stores:Traditional retail shelf presence faces margin compression from direct-to-consumer disintermediation in mature North American markets.
- Direct Sales:Multi-level marketing networks retain traction in Asia-Pacific markets where personal recommendation outweighs digital discovery.
Online retail is expanding most quickly; pharmacies retain premium pricing power.
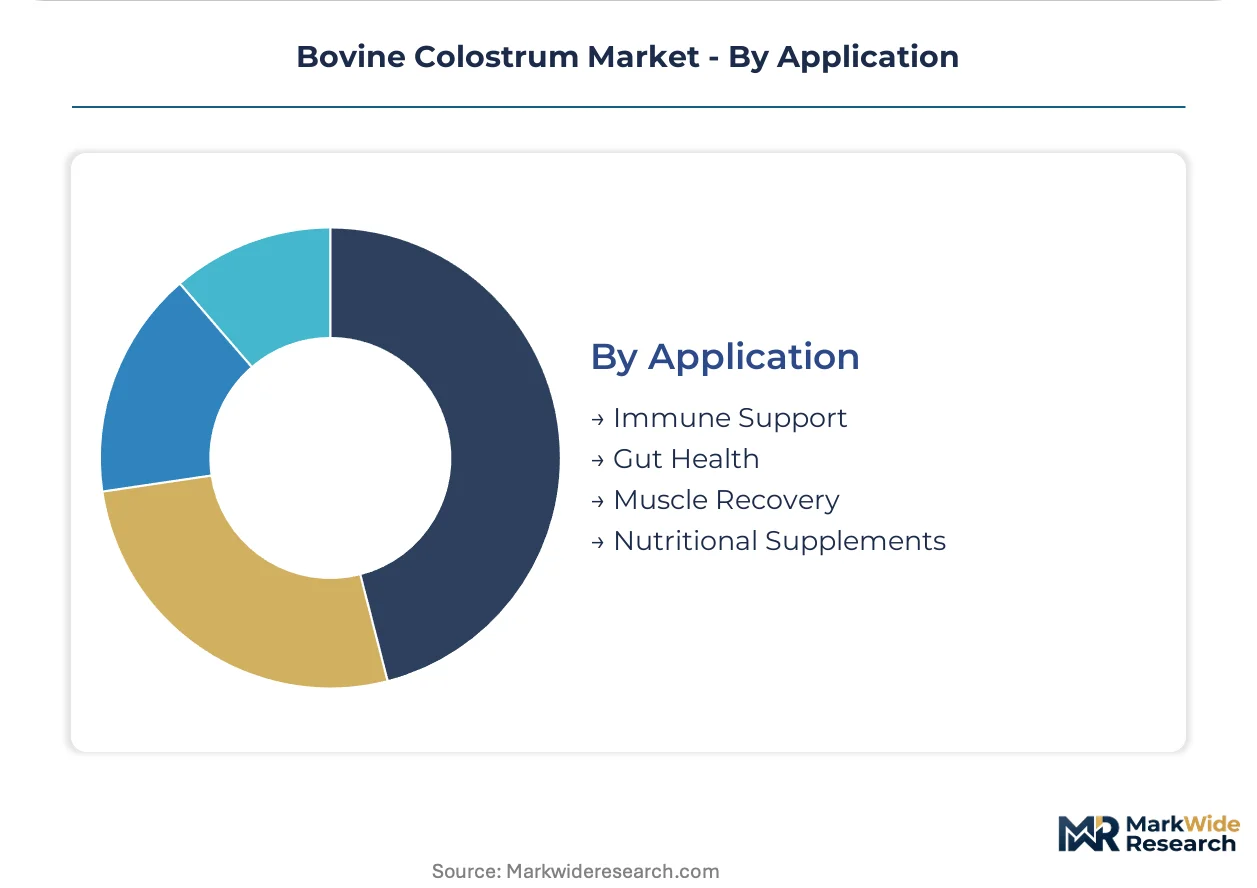
Application:
Clinical evidence depth determines margin tier and regulatory defensibility across positioning strategies.
- Immune Support:Immunoglobulin content claims require ISO 17025-validated assays and human intervention studies for EFSA substantiation; European brands consolidate supplier relationships around processors with captive research capabilities.
- Gut Health:Emerging antimicrobial peptide and growth factor research supports digestive health positioning beyond traditional immune modulation, with South Korean functional food expenditure driving formulation innovation.
- Muscle Recovery:Post-exercise protein synthesis claims compete with established sports nutrition ingredients on bioavailability metrics.
- Nutritional Supplements:General wellness positioning faces commoditization pressure from plant-based protein alternatives in mass-market channels.
Immune support commands premium tier pricing; gut health shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes sports nutrition recovery formulations, while Germany and South Korea emphasize clinical immune protocols. Australia blends both applications through practitioner-supervised channels.
United States
Athlete recovery formulations and direct-to-consumer subscription models dominate demand. FDA New Dietary Ingredient notifications filter market entry for novel colostrum fractions. Denver and Austin clusters host sports nutrition contract manufacturers retrofitting lines for low-temperature processing.
Germany
Behind-the-counter pharmacy positioning and pharmaceutical-grade GMP certification requirements shape procurement. EFSA health claim substantiation rules tighten evidentiary standards for immunoglobulin content declarations. Munich and Frankfurt pharmaceutical hubs consolidate supplier relationships around vertically integrated processors.
South Korea
Functional food expenditure and Traditional Chinese Medicine integration pathways accelerate gut health positioning. MFDS regulations govern health functional food certification for bioactive peptide claims. Seoul metropolitan area drives formulation innovation through antimicrobial peptide research programs.
Australia
Telehealth-integrated practitioner dispensing and athlete influencer partnerships expand premium channels. TGA therapeutic goods regulations classify high-immunoglobulin products under complementary medicine pathways. Sydney and Melbourne health retail networks pivot toward subscription models.
New Zealand
Dairy cooperative sourcing networks and fractionation capacity expansion redistribute global ingredient supply. WHO Codex Alimentarius dairy hygiene standards constrain export qualification. Waikato and Canterbury processing regions scale low-temperature spray drying infrastructure for international trade.
Bovine Colostrum Market Vendor Landscape
Capability concentration sits with vertically integrated processors; scale advantage sits with broad-ingredient conglomerates. The market structures around three tiers: farm-level collectors, specialized fractionators, and finished-product brands. Two strategic archetypes dominate—backward-integrated dairy cooperatives and clinical-research-capable ingredient suppliers. Competitive moves center on captive supply chain construction and EFSA-compliant clinical study commissioning.
Among North American specialists, PanTheryx, Inc. and APS BioGroup occupy positions anchored in farm-level collection networks. European processors Glanbia PLC and Ingredia SA exemplify cooperative-backed supply security. NOW Foods represents brand-driven distribution scale across health retail channels. These named entities illustrate the capability-scale trade-off: research-intensive fractionation versus shelf-presence velocity.
| Leading Market Players |
|---|
| PanTheryx, Inc. |
| Glanbia PLC |
| NOW Foods |
| Biostrum Nutritech Pvt. Ltd. |
| Colostrum BioTec GmbH |
| APS BioGroup |
| Ingredia SA |
| Saskatoon Colostrum Company Ltd. |
| SwissBioColostrum AG |
| Others |
Supply Flow & Price Mechanics
New Zealand's dairy cooperative concentration anchors upstream colostrum supply, directing margin pools toward vertically integrated processors with captive fractionation capacity and ISO 17025-validated immunoglobulin assays.
Pricing Analysis
Long-term offtake contracts dominate premium ingredient procurement, with sports nutrition brands locking in multi-year supply agreements to secure consistent immunoglobulin G concentrations above 15% by mass. Price differentiation rests on certification tier—EFSA health claim substantiation commands 40-60% premiums over generic compositional claims—and volume scale, where bulk dried powder purchases compress unit economics for contract manufacturers. Cost compression in standard-grade fractions is intensifying as plant-based protein alternatives capture immune-support positioning in mass-market channels. Mass-market supplement buyers exhibit highest price sensitivity, while practitioner-supervised protocols in Germany and South Korea tolerate premium pricing for pharmaceutical-grade GMP certification.
Supply Chain Analysis
Contract manufacturing concentration sits with sports nutrition specialists in Denver, Austin, and Sydney retrofitting production lines for low-temperature spray drying parameters. Geographic supply concentration centers on New Zealand, the United States, and Germany, where dairy cooperative networks and pharmaceutical-grade processing infrastructure overlap. Raw material dependencies include first 72-hour post-calving collection windows, cold-chain logistics for liquid concentrates, and immunoglobulin assay reagents for quality verification. Single-source vulnerability runs through New Zealand's fractionation capacity expansion, where processor consolidation threatens downstream supply security. Distribution runs through direct-to-consumer subscription platforms and practitioner-exclusive channels, displacing traditional health retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bovine colostrum market sits in early-cycle expansion, with sports nutrition recovery formulations displacing commodity whey and gut microbiome clinical evidence opening digestive health positioning beyond traditional immune modulation.
For Market Incumbents: Entrench supply security through backward integration into farm-level collection networks in New Zealand and the United States, securing first 72-hour post-calving volumes against seasonal concentration risks. Commission EFSA-compliant human intervention studies to defend immunoglobulin content claims against emerging precision-fermentation alternatives. Prioritize ISO 17025 laboratory accreditation investments to resolve batch-to-batch variability disputes and sustain premium pricing power. For New Entrants and Emerging Players: South Korean functional food expenditure and Traditional Chinese Medicine integration pathways represent the most penetrable entry point for clinically positioned antimicrobial peptide formulations. Practitioner-supervised dispensing through telehealth-integrated channels in Australia and the United States offers white-space access outside commoditized mass-market protein positioning. Pursue gut health applications leveraging emerging growth factor and intestinal flora research to differentiate from established immune support incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated processors with captive clinical research capabilities and established EFSA health claim portfolios. Long-term viability across a 5-10 year horizon rests on immunoglobulin assay standardization leadership and fractionation technology differentiation. Watch for immunoglobulin assay harmonization across ISO 17025 laboratories as the inflection signal indicating commoditization pressure or premium consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Substantiation | Human intervention studies validate immunoglobulin content claims for European sports nutrition shelf placement. |
| Low-Temperature Processing Scale-Up | Retrofitted spray drying lines in Denver and Austin collapse bioactive protein preservation cost structures. |
| Farm-Level Collection Network Expansion | Backward integration into New Zealand dairy cooperatives secures first 72-hour post-calving supply windows. |
| Direct-to-Consumer Subscription Launch | Athlete influencer partnerships disintermediate traditional health retail in United States and Australian markets. |
| Gut Microbiome Clinical Research Program | Antimicrobial peptide and growth factor studies support digestive health positioning beyond immune modulation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dairy cooperative procurement directors, sports nutrition contract manufacturing executives, regulatory affairs specialists at FDA and EFSA, and functional medicine practitioners; and secondary validation through FDA New Dietary Ingredient notification databases, EFSA health claim substantiation filings, WHO Codex Alimentarius dairy hygiene standards, and ISO 17025 laboratory accreditation records. Bottom-up volume modeling triangulated against top-down expenditure analysis across direct-to-consumer channels and practitioner-supervised dispensing networks.
Forecast inputs considered product type segmentation across dried powder, capsule, liquid, and chewable tablet formats; end-use application across sports nutrition, immune support, gut health, and animal feed; and distribution channel evolution across online retail, pharmacy, health store, and direct sales. CAGRs were derived from demand elasticity modeling against protein substitute pricing and immunoglobulin content premium retention. Industry-specific forecast inputs included seasonal calving pattern concentration and EFSA evidentiary requirement tightening timelines.
Practitioners should monitor immunoglobulin assay standardization progress, precision fermentation protein cost curves, and MFDS regulatory pathway developments for early signals of competitive intensity shifts. Forecasts embed assumptions regarding EFSA health claim approval velocity and cold-chain infrastructure expansion in Asia-Pacific markets. Quarterly review of fractionation capacity utilization rates and plant-based protein pricing trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Colostrum Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Global GMO Testing Market