
 Colostrum Market | 2026-2036
Colostrum Market Size, Share, and Industry Trends Forecast 2026-2036
Colostrum Market Analysis
Plant-based protein isolates is decoupling from dairy-derived colostrum in select sports nutrition lines, though bovine colostrum retains bioactive density advantages that synthetic alternatives cannot replicate. PanTheryx, Inc. leverages vertical integration across its US processing facilities to control immunoglobulin yields from raw collection through finished powder. Ingredia SA anchors European supply with specialized fractionation capabilities at its French dairy complex. NOW Foods competes on retail channel density, stocking colostrum capsules across North American pharmacy and e-commerce networks.
Colostrum denotes the antibody-rich mammary secretion produced in the first 72 hours post-parturition, containing immunoglobulin G concentrations typically ranging from 15% to 30% by weight in bovine sources alongside lactoferrin, growth factors, and cytokines. Manufacturers deploy low-temperature spray drying or freeze-drying to preserve bioactivity for nutraceutical and clinical applications. Powdered colostrum commands the largest volume share due to extended shelf stability and formulation flexibility across immune support and gut health applications. Capsules represent the fastest-growing format as fitness enthusiasts and preventive health consumers prioritize precise dosing convenience over bulk powders.
EFSA novel food regulations in Europe mandate comprehensive safety dossiers for colostrum-derived ingredients entering human food chains, while FDA GRAS self-affirmation pathways govern US market entry without pre-market approval. USDA organic certification and ISO 17025 testing standards further segment premium from commodity supply tiers. Stakeholders must monitor evolving novel food classifications across jurisdictions and invest in batch-level immunoglobulin assay transparency to defend shelf positioning against tightening label-claim enforcement.
Market Dynamics
EFSA novel food regulations are compressing ingredient verification timelines while New Zealand supply concentration creates procurement bottlenecks for European nutraceutical formulators seeking immunoglobulin-standardized inputs.
Growth Catalysts
- Immune support formulations:Post-pandemic preventive health consumption is pulling bovine colostrum into sports nutrition and senior wellness portfolios across pharmacy retail chains.
- EFSA novel food pathways:Regulatory clarity on safety dossier requirements is enabling compliant suppliers to capture shelf space previously occupied by unverified alternatives.
- Low-temperature spray drying:Processing technology advances are preserving bioactive density for clinical-grade applications previously limited to raw frozen supply.
Market Restraints
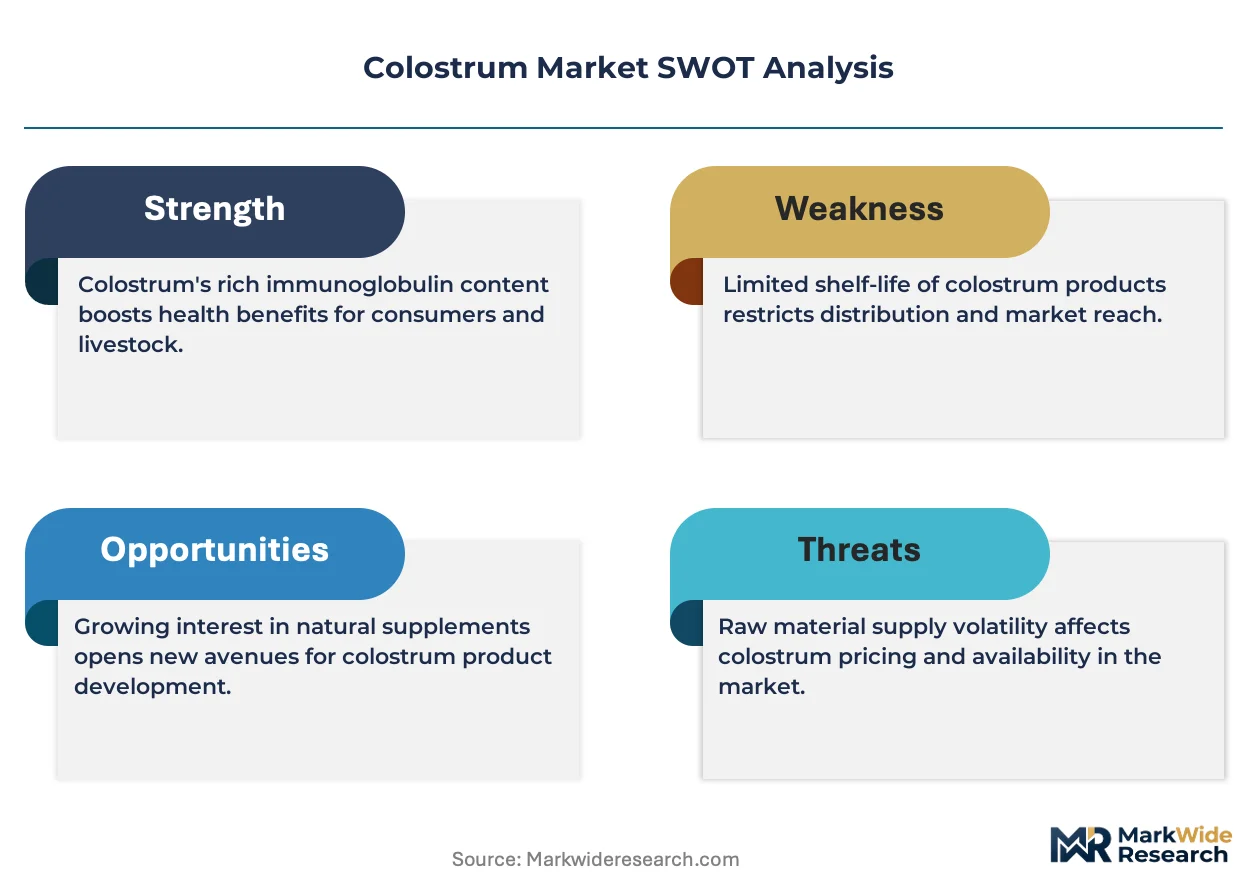
- Seasonal raw material volatility:Bovine calving cycles concentrate collection windows, forcing processors to absorb working capital spikes for cold storage infrastructure.
- New Zealand supply concentration:Premium export volumes cluster in Canterbury and Waikato regions, exposing buyers to climate disruption and freight cost surges.
- Plant protein substitution:Pea and rice protein isolates are capturing price-sensitive sports nutrition segments where immunoglobulin content carries less consumer recognition.
Strategic Opportunities
- USDA organic certification tiers:Premium positioning through certified organic colostrum commands 40-60% price multiples over conventional powder in North American natural retail channels.
- Capsule format expansion:Precision-dosing convenience is opening preventive health segments among fitness enthusiasts who reject bulk powder handling.
- Gut health microbiome research:Emerging clinical validation of colostrum's oligosaccharide content is creating entry points into digestive wellness formulations beyond immune positioning.
Industry Challenges
- ISO 17025 assay standardization:Batch-level immunoglobulin testing transparency requires capital investment in chromatography infrastructure that mid-tier processors struggle to fund.
- Cross-jurisdiction label claims:Divergent FDA GRAS self-affirmation and EFSA novel food enforcement timelines create compliance fragmentation for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colostrum Market |
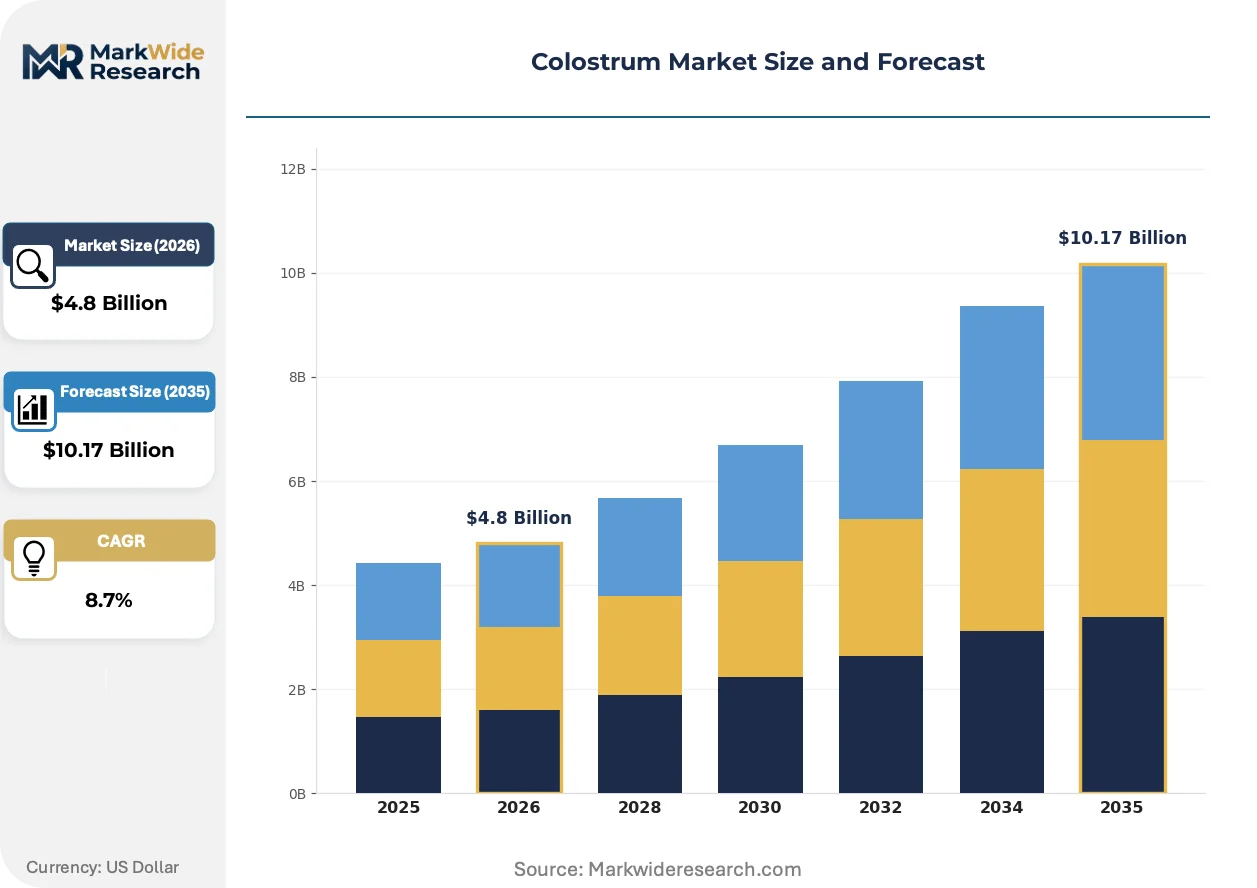
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Colostrum, Powdered Colostrum, Capsules, Tablets End User: Healthcare Providers, Fitness Enthusiasts, Nutraceutical Manufacturers, Veterinary Clinics Application: Immune Support, Muscle Recovery, Gut Health, Anti-Aging Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | The Saskatoon Colostrum Company Ltd., Ingredia SA, Colostrum BioTec GmbH, Deep Blue Health NZ, Biotaris, PanTheryx, Inc., NOW Foods, SwissBioColostrum AG, Glanbia PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colostrum Market Emerging Trajectories
Processing technology convergence with clinical validation requirements is splitting the market between commodity powder traders and vertically integrated bioactive specialists capable of certificate-of-analysis transparency.
Microfiltration and low-temperature spray drying systems are modularizing production lines, allowing mid-scale processors to pivot between nutraceutical and clinical-grade outputs without full facility reconfiguration. Sports nutrition contract manufacturers in Germany and the Netherlands are adopting these systems to serve dual customer bases from shared infrastructure. This modularization is compressing minimum efficient scale thresholds and enabling regional processors to challenge New Zealand incumbents on lead times.
EFSA's tightened novel food safety dossier requirements are extending approval timelines for colostrum-derived ingredients entering European food chains, forcing suppliers to front-load toxicology and stability studies before market entry. Manufacturers with existing approvals are capturing shelf space as later entrants face 18-24 month qualification delays. The regulatory friction is most acute for fractionated ingredients targeting infant nutrition applications where EFSA scrutiny intensifies.
Direct-to-consumer subscription models are displacing bulk powder purchases among preventive health adopters who prioritize convenience and dosing consistency over per-gram economy. Fitness-focused e-commerce platforms in North America are unbundling colostrum from multi-ingredient stacks, selling standalone capsules with certificate-of-analysis transparency. This channel shift is most visible in urban coastal markets where consumer education investments have built immunoglobulin literacy ahead of heartland penetration.
Colostrum Market Segmentation
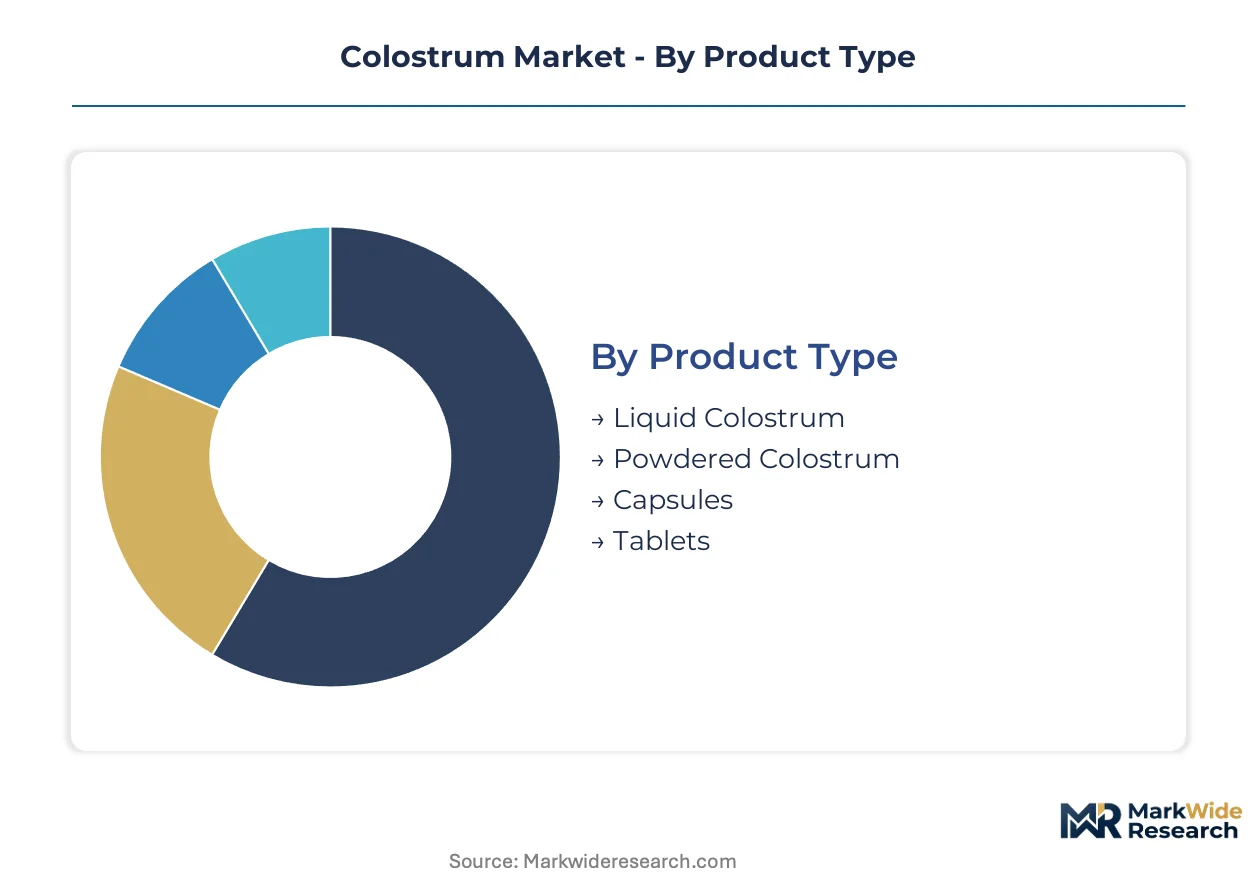
Colostrum segmentation reveals divergent capital requirements across processing technologies and distribution architectures. Manufacturers allocate investment toward bioactive preservation systems or channel infrastructure depending on margin targets and regulatory exposure.
Product Type:
Capital intensity peaks in low-temperature processing infrastructure, with spray-drying and freeze-drying systems demanding distinct upfront commitments and operating cost profiles.
- Powdered Colostrum:Low-temperature spray-drying or freeze-drying reduces immunoglobulin denaturation while extending shelf stability to 24-36 months. Nutraceutical manufacturers in Germany and the United States anchor procurement for immune support formulations, though EFSA novel food dossier requirements compress margin structures for European entrants.
- Capsules:Precision-dosing convenience drives preventive health adoption among fitness enthusiasts who reject bulk powder handling. North American e-commerce platforms and pharmacy retail chains absorb expanding volumes as certificate-of-analysis transparency becomes a purchase prerequisite.
- Liquid Colostrum:Cold-chain dependency limits distribution radius and concentrates demand within veterinary clinics and specialized healthcare settings requiring raw bioactivity.
- Tablets:Compression binding agents and coating technologies compete with capsule formats on production efficiency but sacrifice dissolution speed valued in clinical applications.
Powdered colostrum absorbs the bulk of installed capacity; capsules are expanding most quickly.
End User:
Customer sophistication determines pricing power, with institutional buyers commanding batch-level assay transparency that commoditizes undifferentiated supply.
- Nutraceutical Manufacturers:Formulators require immunoglobulin-standardized inputs with ISO 17025 documentation for EFSA novel food compliance and FDA GRAS self-affirmation pathways. German and Dutch contract manufacturers consolidate procurement around verified suppliers to defend shelf positioning against tightening label-claim enforcement.
- Healthcare Providers:Clinical-grade specifications demand growth factor quantification and cytokine profiling previously limited to research supply tiers. University medical centers and functional medicine clinics in the United States and Switzerland drive validation requirements.
- Fitness Enthusiasts:Sports nutrition consumers prioritize convenience formats and immunoglobulin literacy over per-gram economy, shifting volume toward subscription-based capsule purchases.
- Veterinary Clinics:Neonatal livestock applications consume bulk liquid supply with minimal processing overhead, anchoring regional collection infrastructure in agricultural zones.
Nutraceutical manufacturers command the deepest supplier relationships; fitness enthusiasts are climbing the fastest as direct-to-consumer channels disintermediate traditional distribution.
Application:
Clinical validation intensity varies sharply, with immune positioning backed by decades of research while microbiome applications require fresh evidence generation.
- Immune Support:Immunoglobulin G concentrations of 15-30% by weight in bovine sources provide the evidentiary foundation for preventive health claims. Post-pandemic consumption patterns pull colostrum into senior wellness portfolios across pharmacy retail chains in the United States and Germany.
- Gut Health:Oligosaccharide content and lactoferrin interactions with intestinal microbiota are attracting formulation interest beyond traditional immune positioning. Japanese and Australian researchers are generating clinical validation that could resegment competitive positioning.
- Muscle Recovery:Growth factor content targets sports nutrition applications where synthetic alternatives compete on price recognition.
- Anti-Aging:Cytokine and growth factor claims require heavier toxicology investment for novel food approvals, limiting compliant supply.
Immune support holds the largest revenue base; gut health is gaining share fastest as microbiome research matures.
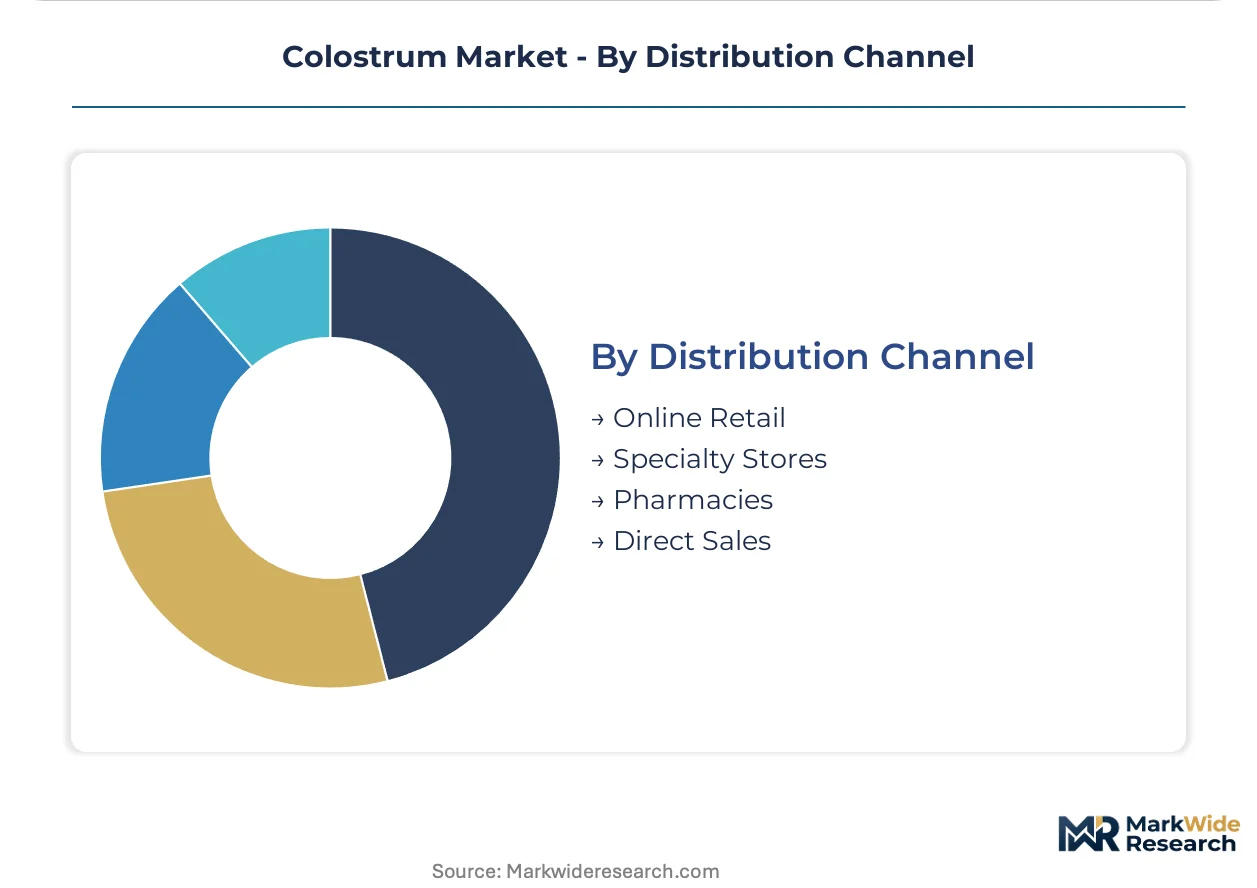
Distribution Channel:
Channel selection determines working capital intensity and customer education burden, with direct models requiring front-loaded investment in immunoglobulin literacy.
- Online Retail:Subscription models displace bulk powder purchases among preventive health adopters prioritizing dosing consistency. Fitness-focused platforms in North America unbundle colostrum from multi-ingredient stacks, selling standalone capsules with certificate-of-analysis transparency.
- Pharmacies:NOW Foods and comparable retail channel competitors stock colostrum capsules across North American networks where pharmacist recommendation drives trial.
- Specialty Stores:Natural retail channels in the United States command 40-60% price multiples for USDA organic certification tiers over conventional powder.
- Direct Sales:Practitioner-only distribution in functional medicine networks limits scale but defends margin through clinical consultation bundling.
Online retail captures the steepest volume trajectory; pharmacies retain the largest established footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bovine colostrum concentrates in New Zealand's Canterbury and Waikato regions, with German nutraceutical formulators and North American fitness consumers pulling distinct supply chain configurations.
New Zealand
Deep Blue Health NZ and Biotaris anchor premium export supply chains serving European and North American nutraceutical manufacturers. The country's Ministry for Primary Industries enforces strict dairy export certification that underpins immunoglobulin-standardized product credibility. Canterbury's dairy processing clusters concentrate spray-drying capacity for global immune support formulation supply.
Germany
Contract manufacturers in Bavaria and North Rhine-Westphalia expand procurement of powdered colostrum for immune support and gut health product lines. EFSA novel food regulations mandate comprehensive safety dossiers that compress margin structures for new entrants while rewarding compliant incumbents. Frankfurt-area logistics hubs coordinate distribution across EU pharmacy retail networks.
United States
PanTheryx operates vertically integrated processing facilities controlling immunoglobulin yields from raw collection through finished powder. FDA GRAS self-affirmation pathways govern market entry without pre-market approval, accelerating product launches relative to European timelines. NOW Foods stocks colostrum capsules across pharmacy and e-commerce networks where certificate-of-analysis transparency drives purchase decisions.
Switzerland
SwissBioColostrum AG and functional medicine clinics in Zurich and Geneva drive clinical-grade specification requirements for growth factor quantification. Swissmedic oversight of novel food ingredients maintains rigorous batch-level documentation standards that segment premium from commodity supply tiers. Basel-area research institutions validate microbiome applications beyond traditional immune positioning.
Canada
The Saskatoon Colostrum Company Ltd. leverages prairie dairy infrastructure for North American bulk powder supply. Health Canada and PMRA regulate natural health product claims, requiring evidence substantiation for immunoglobulin content labeling. Alberta and Saskatchewan agricultural zones provide regional raw material collection windows tied to seasonal calving cycles.
Colostrum Market Vendor Landscape
Backward integration into raw collection infrastructure dominates the current landscape as processors seek immunoglobulin yield control. The market structures around three tiers: vertically integrated bioactive specialists with certificate-of-analysis transparency, regional powder traders serving commodity nutraceutical channels, and retail-brand competitors competing on pharmacy shelf density. Strategic archetypes include New Zealand-based export specialists, European fractionation experts, and North American direct-to-consumer platforms. M&A activity concentrates on spray-drying capacity acquisition, while geographic expansion targets USDA organic certification for premium North American natural retail positioning.
Among New Zealand-based exporters, Deep Blue Health NZ and Biotaris exemplify the vertically integrated archetype controlling supply from Canterbury dairy farms through finished powder export. Colostrum BioTec GmbH represents the European fractionation specialist tier with capabilities at its German processing complex. NOW Foods occupies a position within the retail-channel density archetype, stocking finished formats across North American pharmacy networks where consumer education investments have built immunoglobulin literacy ahead of competitor penetration.
| Leading Market Players |
|---|
| The Saskatoon Colostrum Company Ltd. |
| Ingredia SA |
| Colostrum BioTec GmbH |
| Deep Blue Health NZ |
| Biotaris |
| PanTheryx, Inc. |
| NOW Foods |
| SwissBioColostrum AG |
| Glanbia PLC |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap processors in New Zealand and Germany anchor supply discipline through captive dairy farm relationships, translating seasonal collection constraints into premium pricing power for immunoglobulin-standardized outputs. This ownership pattern insulates bioactive yield control from quarterly earnings pressure while concentrating procurement leverage among verified suppliers.
Pricing Analysis
Volume-mass commodity powder trades at per-kilogram spot rates while clinical-grade capsules capture subscription-based recurring revenue with certificate-of-analysis transparency. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified supply from conventional powder and bulk liquid veterinary grades. Cost compression in standard-tier powder is intensifying because EFSA novel food dossier requirements force toxicology investment that commodity traders cannot fund. Fitness enthusiasts demonstrate lowest price sensitivity, accepting per-capsule premiums for dosing convenience, while veterinary clinics drive hardest bargain on bulk liquid procurement.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch contract manufacturers require parallel qualification of New Zealand and North American suppliers to mitigate climate disruption exposure. Geographic supply concentrates in New Zealand, the United States, and Canada, with raw material dependencies spanning seasonal bovine calving cycles, cold-chain infrastructure, and chromatography assay capacity. Single-source vulnerability runs through Canterbury processing clusters where Deep Blue Health NZ and Biotaris control premium export volumes. Distribution runs through Frankfurt logistics hubs for European pharmacy networks and direct-to-consumer platforms for North American fitness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature spray drying is displacing legacy freeze-drying infrastructure as the dominant bioactive preservation technology, compressing capital thresholds for regional processors seeking clinical-grade certification.
For Market Incumbents: Extend certificate-of-analysis transparency into batch-level immunoglobulin tracking to defend shelf positioning against tightening EFSA label-claim enforcement. Deepen backward integration into organic-certified dairy farm networks in Canterbury and Saskatchewan to secure supply ahead of climate volatility. Plant protein substitution in price-sensitive sports nutrition segments threatens volume retention; counter with gut health microbiome positioning backed by emerging oligosaccharide research. For New Entrants and Emerging Players: Enter via capsule format specialization targeting fitness-focused e-commerce platforms in urban coastal North America where immunoglobulin literacy exceeds heartland penetration. White-space exists in USDA organic certified tier where 40-60% price multiples reward certification investment. Gut health applications beyond immune positioning offer formulation differentiation with lighter clinical validation burden than anti-aging cytokine claims. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European processors with modular spray-drying lines capable of pivoting between nutraceutical and clinical outputs without facility reconfiguration. Long-term viability hinges on regulatory compliance infrastructure rather than commodity trading relationships. Watch EFSA novel food approval timelines as inflection indicator: 18-24 month delays for fractionated ingredients signal consolidation pressure on undercapitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic-Certified Dairy Farms | Captive supply from Canterbury and Saskatchewan farms secures climate-resilient raw material access. |
| Modular Low-Temperature Spray Drying Deployment | German and Dutch processors pivot between nutraceutical and clinical-grade outputs from shared infrastructure. |
| Certificate-of-Analysis Transparency Investment | Batch-level immunoglobulin assay documentation defends shelf positioning against EFSA enforcement tightening. |
| Direct-to-Consumer Capsule Launch | North American fitness platforms unbundle colostrum from multi-ingredient stacks with subscription pricing. |
| Gut Health Microbiome Research Partnership | Swiss and Japanese clinical validation opens digestive wellness formulations beyond traditional immune positioning. |
Methodological Framework
Document review covered EFSA novel food safety dossiers, FDA GRAS self-affirmation filings, and ISO 17025 laboratory accreditation records, complemented by interviews with nutraceutical formulation directors, dairy processing plant managers, and pharmacy retail category buyers. Secondary validation drew from customs trade data, USDA organic certification registries, and dairy export statistics published by New Zealand's Ministry for Primary Industries. Bottom-up demand modeling across end-user segments triangulated against top-down supply capacity assessments from processing facility disclosures.
Cross-referencing historical immunoglobulin yield trends against expert panel input on regulatory timeline expectations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application type, certification tier, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating seasonal calving cycle constraints and cold-chain infrastructure expansion rates. Industry-specific forecast inputs encompass EFSA novel food approval velocity and fitness e-commerce platform penetration metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA reclassification of colostrum-derived ingredients or sustained drought disruption in Canterbury dairy regions. Deviation in EFSA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Biopreservation Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Direct-Fed Microbial Products Market