
 Caramel Malt Market | 2026-2036
Caramel Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Caramel Malt Market Outlook
Aftermarket service revenue for malt technical support and recipe consulting is narrowing as producers integrate these capabilities in-house. Weyermann leverages its German heritage and vertical malting expertise to command premium positioning in specialty caramel varieties. Crisp Malting Group anchors its competitive stance through controlled germination and kilning technology leadership. Simpsons Malt differentiates via heritage barley sourcing and small-batch roasting precision.
Caramel malt consists of germinated barley subjected to higher kiln temperatures that convert starches into crystallized sugars, producing color ratings from 10 to 120 EBC depending on roast duration and moisture content. Brewers deploy these malts primarily for body enhancement, head retention, and flavor complexity in ales, lagers, and stouts. Crystal-type caramel malts dominate volume given their versatility across beer styles and consistent fermentability profiles. Specialty-grade products capture disproportionate margin pools as craft brewers prioritize traceability and terroir-specific flavor signatures. Bulk packaging leads industrial procurement while retail bags sustain homebrewing channel growth.
EU REACH and EFSA frameworks govern chemical residue limits and food-contact material standards for malt processing equipment, compelling producers to validate supply chain purity. Germany's BfR and the UK's FSA enforce additional national specifications on acrylamide formation during high-temperature roasting stages. Stakeholders must monitor evolving organic certification requirements under EU Regulation 2018/848 and assess backward integration into heritage barley cultivation to secure premium-grade raw material streams.
Market Dynamics
Specialty craft brewing is fragmenting procurement patterns across the caramel malt value chain, as small-batch producers demand traceable heritage varieties that conflict with industrial-scale supply economics.
Growth Catalysts
- EU REACH purity mandates:Tightening chemical residue limits for food-contact materials are compelling maltsters to upgrade processing equipment, creating replacement demand for certified roasting systems.
- Heritage barley terroir:German Bavaria's traditional brewing culture sustains premium consumption clusters that absorb high-margin specialty caramel varieties at volume premiums.
- Homebrewing channel expansion:Retail bag formats for amateur brewers are capturing incremental volume as craft beer enthusiasm diffuses beyond commercial production.
Market Restraints
- Input cost volatility:Barley feedstock prices fluctuate with agricultural commodity cycles, compressing malting margins during drought-affected harvests in major cultivation zones.
- Roasting energy intensity:Kiln operations require sustained high-temperature thermal input, exposing producers to natural gas price spikes and carbon cost pass-through pressures.
- Acrylamide formation limits:Germany's BfR enforces strict thermal processing thresholds that constrain roast intensity and color development in darker caramel varieties.
Strategic Opportunities
- Organic certification acceleration:EU Regulation 2018/848 creates compliant supply gaps that early-adopting maltsters can fill through certified heritage barley cultivation partnerships.
- Recipe consulting integration:Technical support services are migrating from third-party consultants toward producer-captive capabilities, opening margin capture in advisory relationships.
- Small-batch roasting precision:Micro-malting equipment enables localized production of terroir-specific varieties for regional craft brewery clusters.
Industry Challenges
- Kiln operator skill scarcity:Controlled germination and precision roasting require experienced technicians, with training pipelines failing to match craft sector expansion rates.
- Multi-jurisdiction compliance layering:Simultaneous adherence to EU REACH, EFSA frameworks, and national regulators like the UK's FSA fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramel Malt Market |
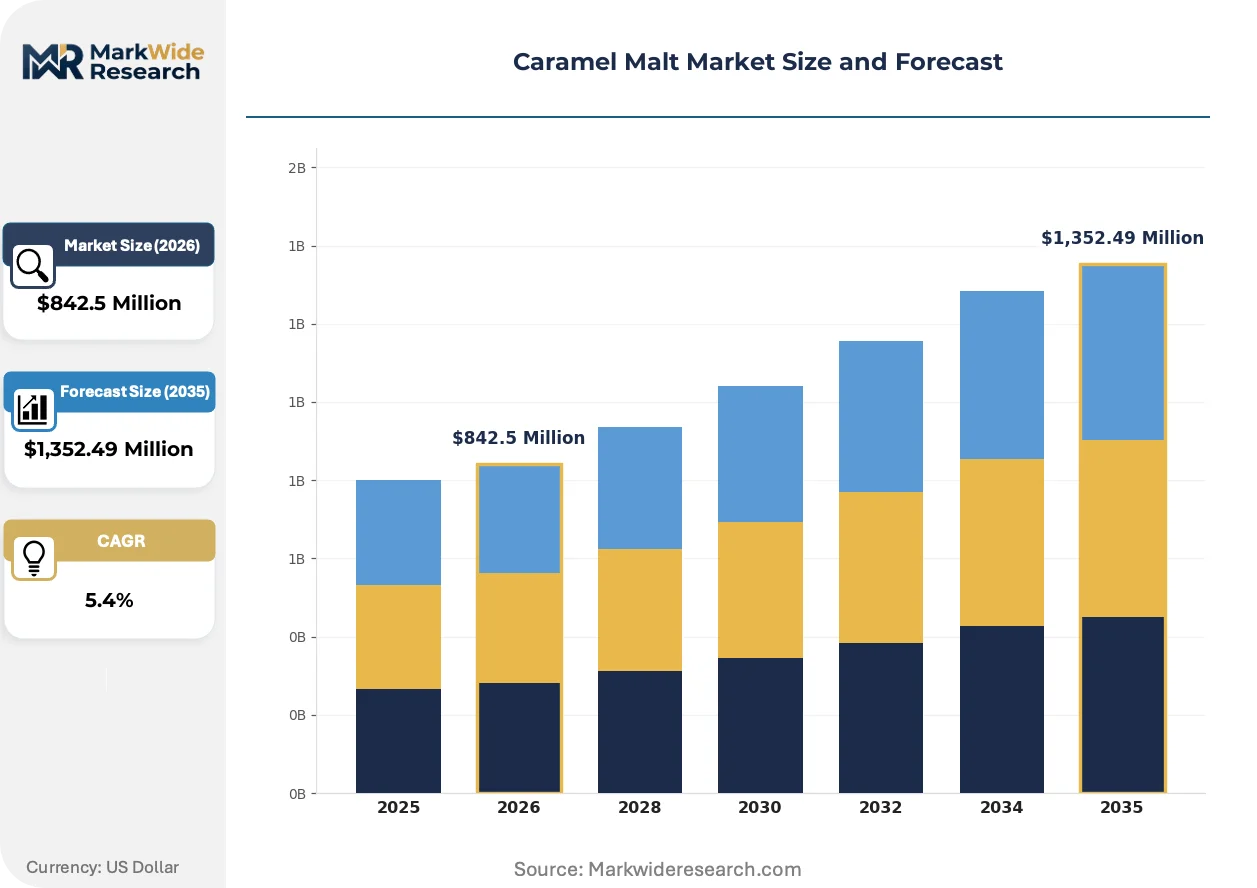
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,352.49 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crystal, Roast, Dark, Amber Application: Brewing, Baking, Confectionery, Flavoring Grade: Specialty, Organic, Conventional, Premium Packaging Type: Bulk, Retail Bags, Tubs, Sachets |
| Companies Covered | Weyermann, Bairds Malt Limited, Crisp Malting Group, Malteurop Group, Briess Malt & Ingredients, Cargill, Muntons Plc, Viking Malt, Simpsons Malt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramel Malt Market Strategic Shifts
Automation and precision control systems are penetrating traditional malting operations, compressing batch-to-batch variation while enabling flavor profile customization at previously uneconomical scales.
Automated moisture control sensors paired with AI-driven kiln temperature modulation are rendering obsolete manual roasting judgment that historically required decades of operator experience. Mid-size craft maltsters in Belgium and the Netherlands are deploying these systems fastest, lured by labor cost reduction and consistency guarantees. The technology is rendering obsolete the apprenticeship-based skill transfer model that concentrated expertise within legacy European malting families.
EU F-Gas Regulation phase-down schedules are accelerating thermal system retrofits across malt processing facilities, banning high-global-warming-potential refrigerants in favor of ammonia-based or transcritical CO2 alternatives. Industrial malting groups face capital-intensive equipment replacement timelines, with larger producers absorbing compliance costs more readily than smaller competitors. Germany and Czech Republic roasting operations are responding fastest, driven by national carbon neutrality commitments that exceed baseline EU requirements.
Brewery technical staff are bypassing traditional distribution intermediaries to source directly from specialty maltsters, collapsing the three-tier procurement hierarchy that long insulated regional wholesalers. Direct relationships enable collaborative recipe development and just-in-time delivery scheduling that bulk distributors cannot match. This disintermediation is most visible across Scandinavian craft brewing clusters, where brewers prioritize terroir transparency over logistical convenience.
Caramel Malt Market Segmentation
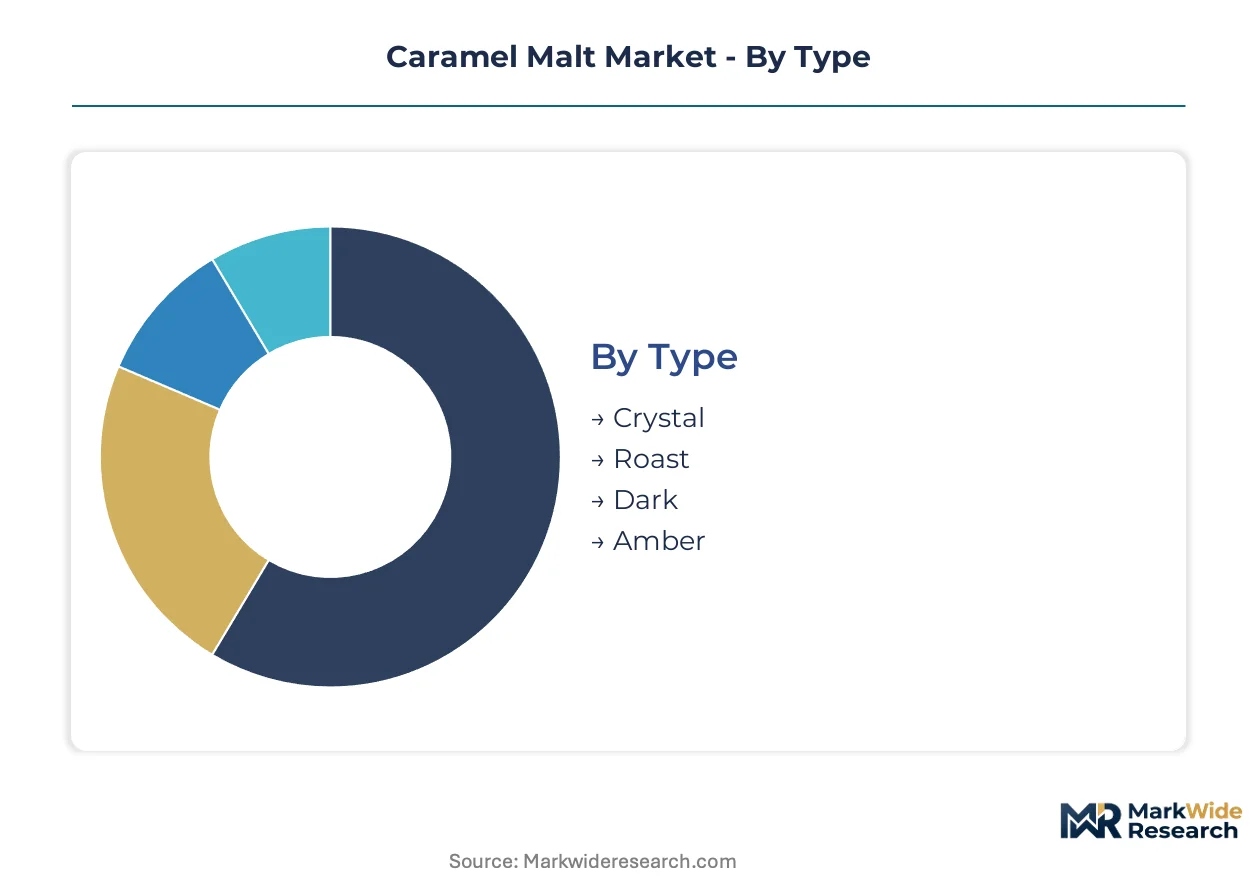
Caramel malt segmentation reflects divergent technical requirements across brewing, food processing, and artisanal channels. Each dimension carries distinct margin profiles and regulatory exposure that shape procurement behavior and supplier positioning.
Type:
After-sales service intensity varies sharply across malt types, with precision-roasted varieties demanding ongoing technical calibration support that commodity grades rarely require.
- Crystal:Germinated barley undergoes controlled stewing before kilning, converting starches into crystallized sugars that resist full fermentation. Craft breweries in Germany's Bavaria region absorb the majority of specialty crystal volumes, driven by traditional lager production protocols that specify exact color ratings from 20 to 120 EBC.
- Roast:Higher-temperature finishing develops intense color and bitter-sweet flavor compounds through Maillard reactions. Small-batch producers in Belgium and the Netherlands are expanding roast malt procurement fastest, lured by flavor complexity differentiation in competitive craft markets.
- Dark:Extended kilning at elevated temperatures produces deep color contributions with minimal enzymatic activity. Baking applications in France and Italy concentrate demand for this type.
- Amber:Moderate roasting balances color development with preserved diastatic power. Regional ale traditions in the UK sustain steady consumption clusters.
Crystal holds the largest share; momentum sits with Roast as craft brewers pursue darker flavor profiles.
Application:
Application segmentation tracks divergent purity standards, with food-contact regulations under EU REACH and EFSA frameworks imposing stricter residue limits on non-brewing uses.
- Brewing:Body enhancement, head retention, and flavor complexity drive deployment across ales, lagers, and stouts. Heritage barley sourcing and traceability certification now dominate procurement criteria for craft producers.
- Baking:Color development and moisture retention properties suit bread and pastry applications. Germany's BfR enforces acrylamide thresholds that constrain roast intensity for darker caramel varieties used in baked goods.
- Confectionery:Controlled sweetness and binding characteristics serve chocolate and candy production. Swiss and Belgian processors lead specialty-grade demand.
- Flavoring:Extracted malt syrups and powders flavor beverages and sauces. Industrial-scale procurement favors bulk packaging formats.
Brewing commands the dominant volume position; confectionery exhibits the steepest expansion trajectory as premium chocolate makers adopt heritage malt signatures.
Grade:
Grade stratification mirrors supply chain certification depth, with organic and specialty tiers requiring backward integration into controlled barley cultivation.
- Specialty:Terroir-specific varieties with documented provenance and small-batch processing protocols. EU Regulation 2018/848 organic certification gaps are creating supply constraints that early-adopting maltsters are exploiting.
- Organic:Certified cultivation excluding synthetic inputs, with full traceability from field to kiln. German and Czech roasting operations are responding fastest to organic demand, driven by national carbon neutrality commitments.
- Conventional:Standard agricultural inputs with baseline quality assurance. Volume brewing operations sustain procurement.
- Premium:Elevated specifications on protein content, moisture, and color consistency. UK craft breweries absorb disproportionate premium-grade share.
Conventional grade retains volume leadership; organic certification is climbing the fastest as supply gaps create first-mover advantages.
Packaging Type:
Packaging segmentation reflects channel fragmentation between industrial-scale brewing and dispersed homebrewing communities.
- Bulk:Silo and tote deliveries serve commercial malt houses and large breweries. Logistics efficiency and just-in-time scheduling dominate procurement criteria.
- Retail Bags:Consumer-facing formats for amateur brewers capture incremental volume as craft enthusiasm diffuses beyond commercial production. Scandinavian markets show particular retail bag strength.
- Tubs:Intermediate containers suit mid-size craft operations with limited silo infrastructure. Belgian and Dutch micro-malting clusters favor this format.
- Sachets:Single-use portions serve experimental and recipe development applications. Specialty maltsters deploy sachets for direct-to-brewery sampling programs.
Bulk packaging holds the largest share; retail bags are gaining share fastest as homebrewing channel expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty malting capacity clusters in Germany, Belgium, the United Kingdom, and the Czech Republic, with heritage barley cultivation partnerships sustaining premium-grade output. Regional demand fragmentation intensifies as craft breweries in Scandinavia and the Netherlands source directly from maltsters, bypassing traditional distribution hierarchies.
Germany
Bavaria's traditional brewing heritage sustains concentrated demand for crystal and dark caramel varieties across 20-120 EBC color ratings. Germany's BfR enforces strict acrylamide formation thresholds during high-temperature roasting stages, constraining darker product development. Bamberg and Munich anchor specialty malt consumption clusters, with regional maltsters integrating organic certification under EU Regulation 2018/848.
Belgium
Small-batch craft breweries in Flanders and Wallonia drive accelerating procurement of roast-type caramel malts for flavor complexity differentiation. ECHA's REACH framework governs chemical residue limits in food-contact processing equipment, compelling equipment upgrades. Ghent and Leuven host micro-malting clusters deploying automated moisture control systems for precision roasting.
United Kingdom
Regional ale traditions sustain steady amber-type consumption, while craft sector expansion absorbs disproportionate premium-grade share. The UK's FSA imposes additional national specifications on thermal processing beyond baseline EU requirements. Yorkshire and Scotland concentrate heritage barley sourcing partnerships, with Simpsons Malt anchoring small-batch roasting precision capabilities.
Czech Republic
Carbon neutrality commitments exceeding baseline EU requirements accelerate organic certification adoption among roasting operations. EFSA frameworks on food-contact material standards drive supply chain purity validation investments. Plzeň and Prague sustain lager-focused demand for crystal-type varieties with consistent fermentability profiles.
Netherlands
Mid-size craft maltsters deploy AI-driven kiln temperature modulation fastest among European peers, lured by labor cost reduction and batch consistency guarantees. EU F-Gas Regulation phase-down schedules mandate thermal system retrofits banning high-global-warming-potential refrigerants. Amsterdam and Rotterdam clusters pioneer direct-to-brewery sourcing relationships that collapse traditional three-tier procurement hierarchies.
Caramel Malt Market Competitive Environment
Heritage-rooted specialists and diversified agricultural conglomerates split the market along premium-commodity fault lines. Consolidation pressure concentrates among mid-tier regional maltsters lacking backward integration into controlled barley cultivation. Three archetypes dominate: vertically integrated European heritage houses, North American craft-focused specialists, and multinational grain processors with malting divisions. Capacity expansion into certified organic supply chains and captive recipe consulting capabilities represent the dominant competitive moves.
Among German heritage houses, Weyermann exemplifies vertical malting expertise commanding premium positioning in specialty caramel varieties. Crisp Malting Group anchors technology leadership through controlled germination and precision kilning investments. Simpsons Malt occupies the heritage barley sourcing tier, leveraging small-batch roasting precision for UK craft brewery relationships. These three represent distinct strategic postures—heritage branding, process technology, and terroir traceability—that other competitors must match or circumvent.
| Leading Market Players |
|---|
| Weyermann |
| Bairds Malt Limited |
| Crisp Malting Group |
| Malteurop Group |
| Briess Malt & Ingredients |
| Cargill |
| Muntons Plc |
| Viking Malt |
| Simpsons Malt |
| Others |
Value Chain & Pricing Dynamics
Bamberg's vertically integrated malting clusters concentrate specialty caramel capacity, translating controlled germination expertise into sustained premium capture across 20-120 EBC color tiers. This geographic concentration enables maltsters to resist commodity pricing pressure through heritage branding and recipe consulting bundling.
Pricing Analysis
After-sales technical support and recipe consulting contracts drive lifetime value capture as brewers integrate advisory relationships into procurement decisions. Three-tier pricing structure across specialty, organic, and conventional certification levels segments buyer willingness-to-pay, with EU Regulation 2018/848 compliance commanding measurable premiums. Cost compression in conventional grades is intensifying because barley feedstock volatility and natural gas price spikes squeeze malting margins. Industrial-scale breweries exhibit highest price sensitivity, while craft producers absorbing heritage varieties demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between UK and EU malt processing equipment suppliers dominates supply chain risk planning as post-Brexit customs friction fragments procurement timelines. Production gravity centers on Germany, Belgium, and the United Kingdom, with heritage barley cultivation partnerships in Bavaria and Yorkshire anchoring premium-grade raw material security. Kiln roasting systems and automated moisture control sensors draw from specialized German and Dutch engineering bases. Single-source vulnerability in precision malting equipment constrains capacity expansion flexibility. Distribution runs through direct-to-brewery relationships collapsing traditional three-tier hierarchies, particularly across Scandinavian craft clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The caramel malt market sits in early-cycle expansion as craft brewing penetration accelerates specialty-grade absorption beyond traditional lager strongholds. Organic certification gaps under EU Regulation 2018/848 create first-mover tailwinds for compliant supply chain investment.
For Market Incumbents: Insulate premium positioning by deepening backward integration into heritage barley cultivation partnerships in Bavaria and Yorkshire, securing terroir-specific raw material streams against emerging micro-malting competitors. Accelerate captive recipe consulting capabilities to capture advisory margins previously lost to third-party technical services, responding to brewery staff bypassing distribution intermediaries. For New Entrants and Emerging Players: Scandinavian craft brewing clusters present the most penetrable white-space opportunity, as direct sourcing relationships remain underdeveloped relative to German and Belgian market saturation. Belgian and Dutch micro-malting equipment deployments demonstrate viable small-batch roasting precision at previously uneconomical scales. Target retail bag formats for homebrewing channel expansion, leveraging craft enthusiasm diffusion beyond commercial production. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because organic supply gaps under EU Regulation 2018/848 will persist through mid-decade, rewarding early-adopting maltsters with sustained margin premiums. Acquisition targets should display backward integration into controlled barley cultivation and automated kiln technology deployment. Monitor EFSA and BfR acrylamide threshold enforcement as inflection signal for darker caramel variety development constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Partnership | EU Regulation 2018/848 compliance secures premium-grade positioning in supply-constrained segments. |
| Automated Kiln Technology Deployment | AI-driven temperature modulation reduces labor dependency while guaranteeing batch-to-batch consistency. |
| Direct-to-Brewery Distribution | Collapsing three-tier hierarchies enables collaborative recipe development and just-in-time scheduling. |
| Heritage Barley Cultivation Integration | Backward control over terroir-specific varieties protects against commodity input volatility. |
| Recipe Consulting Capability Buildout | Capturing advisory margins from brewery technical staff seeking formulation support. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with maltsters, craft brewery procurement managers, and equipment engineering specialists, combined with secondary validation through EU REACH regulatory filings, EFSA food-contact material standards, and malt processing trade association publications. Bottom-up volume modeling triangulated against top-down market sizing across crystal, roast, dark, and amber type segments.
Forecast inputs considered malt type, application channel, certification grade, and packaging format across the projection horizon. CAGRs derived from segment-level growth trajectories weighted by regional consumption clusters in Germany, Belgium, the United Kingdom, and the Czech Republic. Industry-specific inputs included craft brewery formation rates, organic barley cultivation expansion, and thermal equipment retrofit cycles under EU F-Gas Regulation phase-down schedules.
Practitioners should monitor barley harvest yields, natural gas price volatility, and acrylamide regulatory threshold adjustments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vegetable Extract Market
Ingredients
Collagen Casings Market
Ingredients
Corn Oil Cake Market
Ingredients
Cocoa Butter Market
Ingredients
Commercial Flour Market
Ingredients
Mirepoix Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
US Plant-Based Oils Market
Ingredients
Beverage Ingredients Market
Ingredients
Omega 6 Market
Ingredients
South America Fats and Oil Market
Ingredients
Acetylated Starch Market
Ingredients
Corn Steep Liquor Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Pet Food Ingredients Market