
 Vegan Confectionery Market | 2026-2036
Vegan Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Confectionery Market Intelligence
The divergence in R&D investment for dairy-free formulations is redrawing competitive lines between established confectioners and specialized vegan brands. Large corporations like Mondelēz International adapt existing product portfolios, while Barry Callebaut leverages its extensive cocoa sourcing capabilities to produce plant-based chocolate at scale. In contrast, specialized firms such as Plamil Foods Ltd. differentiate through dedicated allergen-free manufacturing facilities and expertise in novel ingredients, creating a distinct value proposition.
Vegan confectionery refers to sweet food products formulated entirely without animal-derived ingredients, including dairy, gelatin, honey, and certain colorants like carmine. Production relies on substitutes such as oat milk for creaminess and pectin or agar-agar for gelling in gummies. The primary purpose is to cater to ethical vegan consumers and individuals with lactose intolerance or dairy allergies. Chocolate bars remain the dominant product type, while the gummies category shows significant growth potential driven by texture innovation.
The market operates within strict food safety and labeling frameworks. Regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern allergen declarations and "free-from" claims. Furthermore, third-party certifications, such as the Vegan Society trademark, provide an essential layer of consumer trust and brand validation. Future success for manufacturers depends on securing transparent supply chains for novel ingredients and navigating the evolving landscape of clean-label verification.
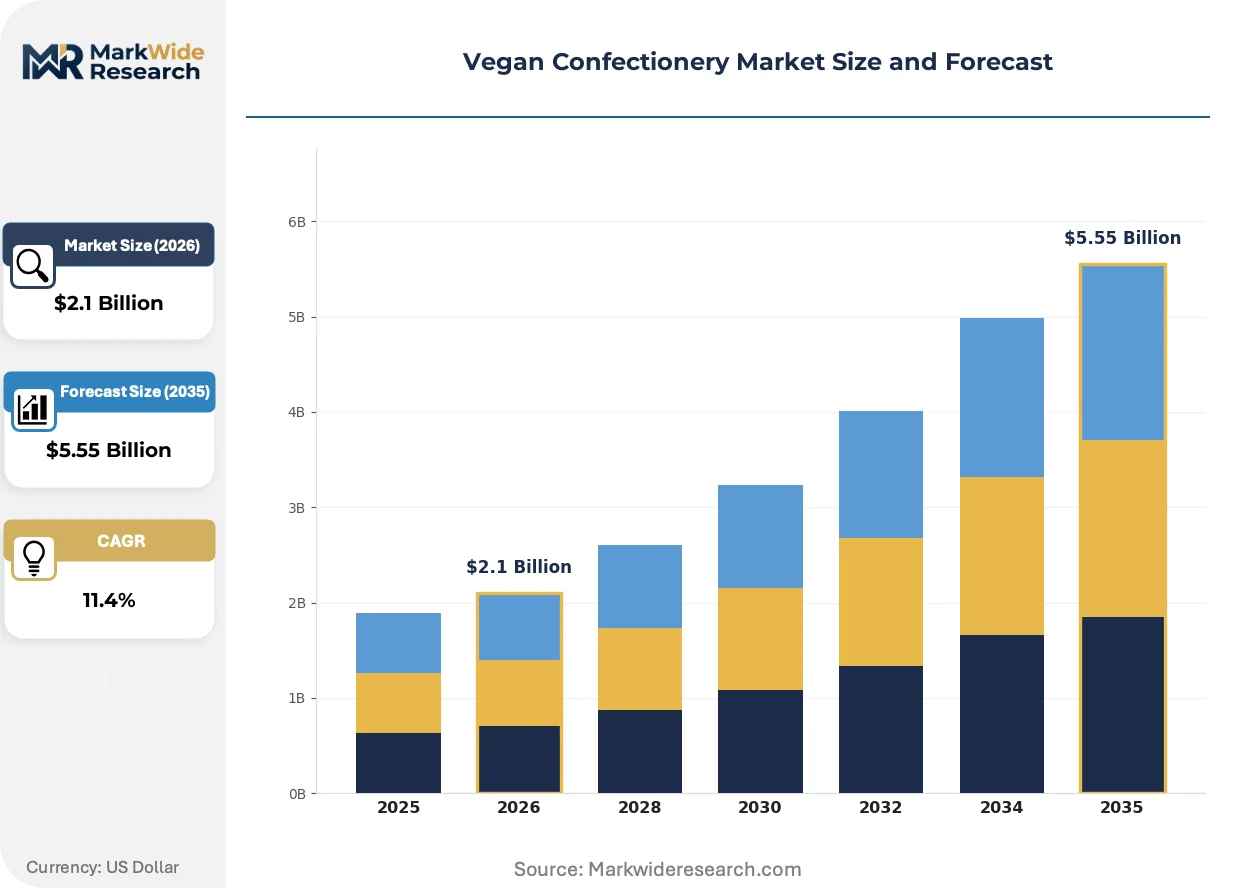
Market Dynamics
The convergence of stringent food labeling regulations and rising consumer demand for ingredient transparency is the central force shaping the vegan confectionery market. Mandates from the US FDA and the EU's Regulation (EU) No 1169/2011 provide the framework that validates brand claims, building the consumer confidence necessary for market expansion.
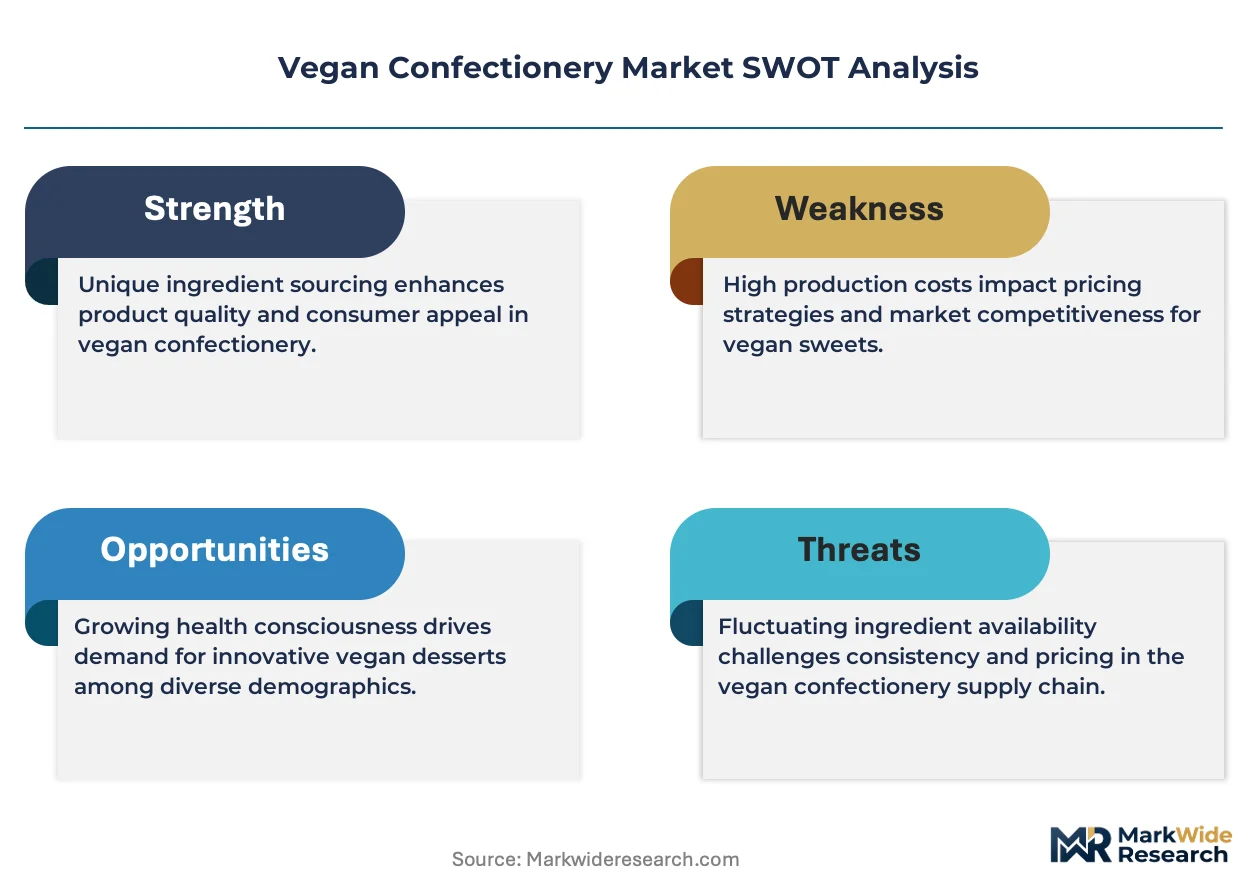
Growth Catalysts
- Regulatory Clarity:The European Union's Regulation (EU) No 1169/2011 on food information to consumers requires explicit declaration of allergens like dairy, which simplifies product selection for consumers and reinforces trust in vegan-labeled goods.
- Flexitarian Consumerism:A growing flexitarian demographic in Western economies, particularly Germany and the United Kingdom, is expanding the consumer base beyond ethical vegans to include individuals seeking to reduce animal product consumption for health or environmental reasons.
- Ingredient Innovation:Advances in plant-based milk alternatives, including oat and soy milk formulations, are significantly improving the texture and mouthfeel of vegan chocolates and cream-based confections, closing the sensory gap with traditional dairy products.
Market Restraints
- Input Cost Premiums:Specialized ingredients such as certified fair-trade cocoa, agar-agar as a gelling agent, and high-quality nut butters carry a significant cost premium over their conventional counterparts, elevating the final product price for consumers.
- Supply Chain Fragility:The supply chains for certain novel ingredients, like specific hydrocolloids or allergen-free oat milk powders, are often concentrated with a few suppliers or in limited geographic areas, creating risks of price volatility and sourcing disruptions.
- Texture Replication Challenges:Replicating the precise chewiness of gelatin in gummies and the specific melting profile of dairy butterfat in chocolate remains a significant technical hurdle, which can impact product acceptance among mainstream consumers.
Strategic Opportunities
- Geographic Expansion:Untapped markets in Asia-Pacific, including South Korea and Japan, present significant growth opportunities as wellness trends and disposable income levels rise, creating new demand for premium plant-based indulgences.
- Functional Confectionery:The development of vegan confections fortified with functional ingredients like probiotics, vitamins, or plant-based proteins opens a new market segment targeting health-conscious consumers seeking benefits beyond simple indulgence.
- Channel Diversification:Launching direct-to-consumer (DTC) e-commerce platforms and subscription box services enables brands to bypass retail gatekeepers, cultivate brand loyalty, and collect valuable consumer data on flavor and format preferences.
Industry Challenges
- Certification Hurdles:Securing and maintaining third-party certifications, such as the Vegan Society trademark, is a costly and time-consuming process that, while essential for credibility, poses a significant operational barrier for small-scale producers and new market entrants.
- Cross-Contamination Risk Management:Manufacturers using shared facilities face the constant operational challenge of preventing cross-contamination with dairy and other animal-derived allergens, requiring investment in stringent cleaning protocols or dedicated, segregated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Confectionery Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Bars, Gummies, Hard Candies, Marshmallows End User: Retail Customers, Food Service Providers, Online Shoppers, Event Organizers Packaging Type: Boxes, Pouches, Jars, Bulk Packaging Sweetening Agent: Agave Syrup, Coconut Sugar, Maple Syrup, Stevia |
| Companies Covered | Barry Callebaut, Nestlé, Plamil Foods Ltd., iChoc GmbH, Lovechock B.V., Moo Free Chocolate Ltd., Mondelēz International, Vego Food GmbH, Veganz Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Confectionery Market Strategic Shifts & Innovations
Ingredient science and consumer demand for "clean label" products are converging, pushing manufacturers toward formulations that are not only free from animal products but also minimally processed and ethically sourced. This shift prioritizes both molecular innovation and supply chain transparency as key competitive differentiators.
Precision fermentation is a key enabling technology used to produce animal-free dairy proteins like whey and casein that are molecularly identical to their bovine counterparts. Ingredient technology firms and agile startups are pioneering its adoption, with larger confectioners actively monitoring its progress. This technology is decomposing the established boundary between vegan and conventional ingredients, creating a future where product performance is uncoupled from animal agriculture.
New guidance from the US Food and Drug Administration (FDA) on the use of the "healthy" claim on food packaging is influencing product development. This regulatory pressure compels manufacturers to reformulate items to meet specific criteria for positive nutrients while limiting saturated fat and added sugars. The chocolate and confectionery bar categories are most affected, accelerating innovation in formulations that utilize natural, low-glycemic sweeteners to align with evolving health-focused labeling standards.
Consumer purchasing decisions are evolving from a singular focus on the "vegan" label to a multi-attribute evaluation that includes ethical sourcing, sustainable packaging, and minimal processing. This behavior disrupts mass-market retail channels, creating an advantage for specialty health food stores and online platforms that offer detailed product provenance. This trend is especially visible in European markets like Germany, where fair-trade and organic certifications are gaining parity with the vegan claim itself.
Vegan Confectionery Market Segmentation
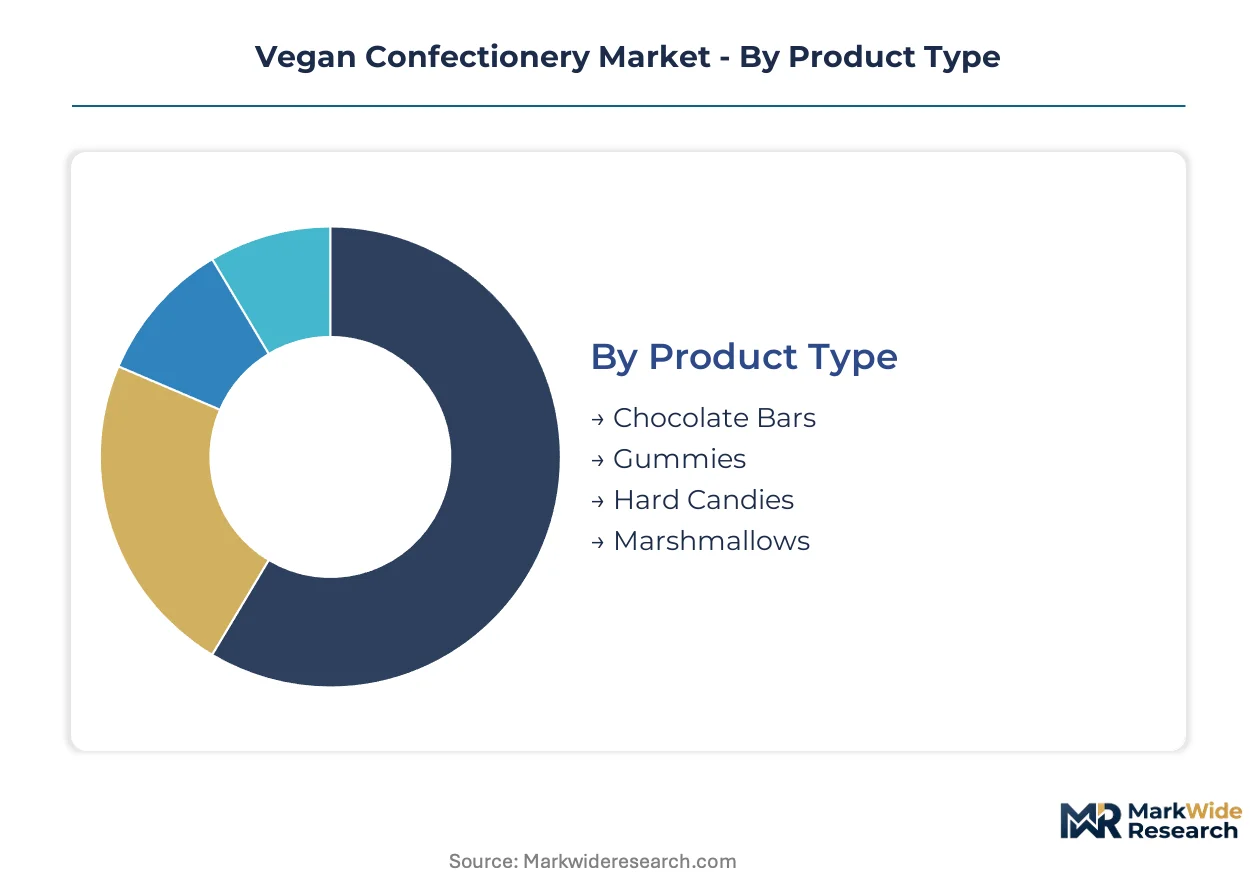
The vegan confectionery market exhibits diverse segmentation driven by consumer preferences and production innovations. Analyzing these distinct segments helps manufacturers tailor product development and distribution strategies. This granular view reveals opportunities for targeted market penetration and competitive differentiation.
Product Type:
The distribution channels for vegan confectionery products vary significantly by product type, influencing retail placement and consumer access.
- Chocolate Bars:These solid confections, often made with oat or rice milk, dominate the market due to established consumer familiarity and versatility. Demand concentrates in Germany, where plant-based chocolate is a staple, driven by a strong ethical consumer base.
- Gummies:Gelatin-free chewy candies, utilizing pectin or agar-agar for texture, represent a significant growth area. Innovation in texture and flavor profiles drives expansion, particularly among younger consumers in the United Kingdom.
- Hard Candies:These sugar-based, long-lasting confections provide a traditional vegan indulgence option.
- Marshmallows:Animal-free marshmallows, typically made with plant proteins, cater to specific dietary needs and traditional dessert applications.
By volume, Chocolate Bars lead the segment. By growth pace, the Gummies category is ahead.
End User:
Understanding the distinct purchasing behaviors of different customer types is critical for optimizing marketing efforts and product offerings within the vegan confectionery space.
- Retail Customers:Individual consumers purchasing vegan confections through supermarkets, health food stores, and convenience outlets form the largest customer base. Their purchasing decisions are influenced by clear labeling and readily available product information.
- Food Service Providers:Restaurants, cafes, and catering companies integrate vegan confectionery into their menus to meet growing demand for plant-based options. Adoption within this segment is accelerating, driven by menu diversification.
- Online Shoppers:Consumers purchasing directly from brand websites or e-commerce platforms prioritize convenience and product variety. This channel allows niche brands to reach a wider audience.
- Event Organizers:These entities source vegan confections for parties, corporate events, and festivals, catering to diverse dietary requirements.
The Retail Customers segment generates the largest sales volume. Food Service Providers demonstrate the steepest expansion trajectory.
Packaging Type:
The volume of product contained within each packaging type directly impacts logistics, shelf presence, and consumer purchasing habits in the vegan confectionery market.
- Boxes:Premium vegan chocolates and assortments frequently utilize boxes, conveying a gift-like or high-end product image. This packaging type is prevalent in specialty stores.
- Pouches:Flexible pouches offer convenience and portability for individual or multi-serve vegan snacks and gummies. This format is gaining share fastest in on-the-go consumption.
- Jars:Reusable jars are often used for bulk candies or specialty items, appealing to sustainability-conscious consumers.
- Bulk Packaging:Large quantities of vegan confections are supplied in bulk to food service providers or for repackaging.
Boxes capture the highest revenue per unit. Pouches are climbing the fastest in terms of market penetration.
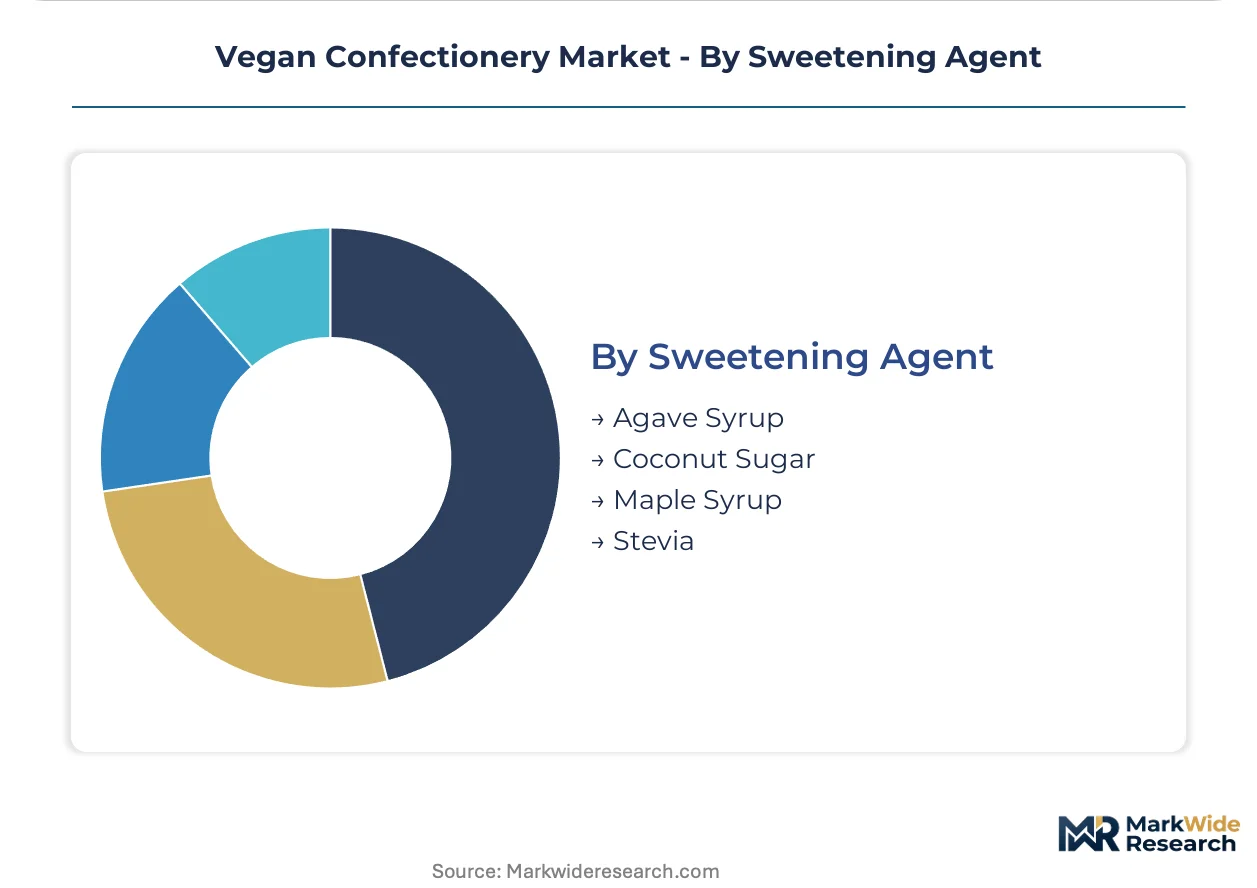
Sweetening Agent:
The maturity of various sweetening agents dictates their market penetration and consumer acceptance within vegan confectionery formulations.
- Agave Syrup:This natural sweetener, derived from the agave plant, provides a neutral flavor and is widely used in many vegan confectionery products. It is a mature ingredient with broad market acceptance.
- Stevia:A natural, zero-calorie sweetener extracted from the Stevia rebaudiana plant, it is gaining traction in health-focused vegan confections. Regulatory guidance from the US FDA influences its application in new product development.
- Coconut Sugar:This unrefined sweetener, sourced from coconut palm sap, offers a caramel-like flavor profile.
- Maple Syrup:A natural syrup derived from maple tree sap, it imparts a distinct flavor to vegan confections.
Agave Syrup holds the largest share by volume. Stevia-sweetened products are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for vegan confectionery varies significantly across regions. Consumers in established markets like Germany demonstrate lower price sensitivity for premium plant-based offerings. Conversely, price remains a critical purchasing factor in emerging Asian markets, influencing market entry strategies.
Germany
Strong consumer preference for plant-based products drives demand for premium vegan chocolates. Regulation (EU) No 1169/2011 ensures clear allergen labeling, building consumer trust. Berlin's vibrant food scene fosters innovation in specialized vegan confectionary startups.
United States
Health-conscious consumers and flexitarians fuel the expansion of dairy-free gummies and snack bars. The US Food and Drug Administration (FDA) guidance on "healthy" claims influences product reformulation. California's food tech hubs attract investment in novel ingredient development for plant-based sweets.
United Kingdom
A growing flexitarian demographic seeks ethical and sustainable vegan confectionery options. The Vegan Society trademark provides essential third-party certification, validating product claims. London's diverse retail landscape supports both established brands and niche artisan vegan confectioners.
Japan
Rising wellness trends and disposable incomes are creating new demand for premium plant-based indulgences. The Ministry of Health, Labour and Welfare (MHLW) oversees food safety standards for imported and domestic products. Tokyo's sophisticated consumer base drives innovation in aesthetically pleasing vegan desserts.
South Korea
The increasing popularity of plant-based diets among younger generations boosts demand for innovative vegan sweets. The Ministry of Food and Drug Safety (MFDS) ensures product safety and labeling compliance. Seoul's dynamic culinary scene experiments with unique flavor combinations in vegan chocolate and pastries.
Vegan Confectionery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the vegan confectionery market. This tiered structure features large, diversified food corporations adapting existing product portfolios alongside agile, dedicated plant-based brands. Strategic archetypes include established confectioners leveraging scale and specialized firms focusing on allergen-free manufacturing. Companies are actively pursuing portfolio diversification into new product categories and geographic expansion into untapped markets.
Within the specialized tier, firms such as Plamil Foods Ltd. exemplify dedicated allergen-free manufacturing facilities and expertise in novel ingredients, creating a distinct value proposition for consumers with specific dietary needs. Barry Callebaut, a major ingredient supplier, anchors the market by leveraging its extensive cocoa sourcing capabilities to produce plant-based chocolate at scale for various brands globally. Germany-based Veganz Group AG also sits within the segment of brands focusing exclusively on plant-based food products, including a diverse range of confectionery items, targeting ethically-driven consumers and expanding its market presence.
| Leading Market Players |
|---|
| Barry Callebaut |
| Nestlé |
| Plamil Foods Ltd. |
| iChoc GmbH |
| Lovechock B.V. |
| Moo Free Chocolate Ltd. |
| Mondelēz International |
| Vego Food GmbH |
| Veganz Group AG |
| Others |
Cost & Logistics Intelligence
The Vegan Society trademark gates both ingredient supply qualification and price differentiation across the vegan confectionery market. This certification reinforces consumer trust, allowing brands to command premium pricing for validated products.
Pricing Analysis
Premium product lines, driven by brand loyalty and repeat purchases, generate sustained value across the vegan confectionery market. The dominant pricing model remains per-unit transactional, with price differentiation stemming from ingredient quality and third-party certifications like the Vegan Society trademark. Upward pricing pressure arises from specialized input costs, including certified fair-trade cocoa and agar-agar. Ethical vegan consumers exhibit lower price sensitivity for premium offerings, while flexitarian consumers remain more price-conscious.
Supply Chain Analysis
Concentrated sourcing of novel ingredients creates supply chain chokepoints for the vegan confectionery market. West Africa supplies much of the global cocoa, while specific hydrocolloids like agar-agar often originate from limited producers in Southeast Asia. This reliance on a few suppliers introduces single-source vulnerability and commodity price volatility. Distribution runs through a multi-channel network, including retail, food service providers, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan confectionery market represents an early-cycle expansion story, driven significantly by the rising flexitarian consumerism across Western economies. This demographic shift broadens the consumer base beyond strict vegans, accelerating product penetration.
For Market Incumbents:Fortify existing product portfolios through aggressive R&D in advanced dairy-free formulations to counter specialized vegan brands. Secure long-term supply agreements for novel ingredients like hydrocolloids to mitigate supply chain fragility. Leverage extensive cocoa sourcing capabilities, similar to Barry Callebaut, to achieve scale in plant-based chocolate production. This strategy addresses the threat from agile firms differentiating through dedicated allergen-free manufacturing.
For New Entrants and Emerging Players:Anchor in niche segments by specializing in functional confectionery, such as products fortified with probiotics or vitamins. Target underpenetrated geographic markets like South Korea and Japan, leveraging rising wellness trends. A direct-to-consumer e-commerce model provides a cost-effective go-to-market angle, bypassing traditional retail gatekeepers. Focus on texture innovation in the gummies category, which still presents significant growth potential.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across the ingredient innovation sub-segment, signaling long-term viability for the vegan confectionery market. Prioritize acquisition targets that possess proprietary ingredient science or dedicated allergen-free manufacturing facilities, like Plamil Foods Ltd. Monitor the commercialization progress of precision fermentation technologies for animal-free dairy proteins as a key inflection indicator. This technology could redefine production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Ingredient Innovation R&D | Drives product differentiation and closes the sensory gap with traditional confectionery. |
| Supply Chain Transparency | Builds consumer trust, especially for ethically sourced and clean-label products. |
| Geographic Expansion (Asia-Pacific) | Taps into rising wellness trends and disposable incomes in new markets like South Korea. |
| Direct-to-Consumer (DTC) Channel Launch | Cultivates brand loyalty and gathers valuable consumer data on preferences. |
| Precision Fermentation Investment | Enables production of molecularly identical animal-free dairy proteins at scale. |
Research Approach
Operator-level perspectives from confectioners, ingredient suppliers, retail buyers, and food service managers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research, including US FDA filings, EFSA reports, and industry association publications. This approach ensured a robust bottom-up and top-down validation of market dynamics and trends.
Sensitivity analysis informed the forecast framework, modeling market evolution across the analysis window. Segmentation dimensions included product type, end user, packaging type, sweetening agent, and regional demand patterns. Compound Annual Growth Rates were derived from historical data, integrating projected impacts of consumer preference shifts and evolving regulatory clarity.
Material uncertainties — macroeconomic volatility and rapid technological breakthroughs — sit outside the modeled envelope, reflecting inherent forecast assumptions. Specific risk factors like input cost premiums could revise projections. Practitioners should keep alternative scenarios live as consumer health perceptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Computer Peripherals Market
Others
Content Experience Platforms Market
Others
Ammeters Market
Others
Bimodal Identity Management Solutions Market
Others
Billet Market
Others
Moveable Water Tap Market
Others
Advanced Combat Helmet Market
Others
Global Application Testing Services Market
Others
United States Cigarette Market
Others
Grna Market
Others
China Automotive LED Lighting Market
Others
Mainframe Market
Others
Mexico Retail Market
Others
Solar Lighting Tower Market
Others
Programmatic Display Market
Others
5G Enabled Healthcare Services Market