
 Insoluble Sulfur Market | 2026-2036
Insoluble Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Insoluble Sulfur Market Intelligence
The insoluble sulfur supply base is pivoting away from undifferentiated bulk powder toward high-dispersion and oil-treated grades that command specification premiums in radial tire manufacturing. Eastman Chemical Company leverages backward integration into sulfur refining to secure feedstock consistency across its polymer additive portfolio. LANXESS anchors European supply through specialized rubber chemical complexes serving premium tire brands. Oriental Carbon & Chemicals Limited competes on cost-optimized thermal process routes tailored to volume buyers in South Asia.
Insoluble sulfur denotes a polymeric allotrope of sulfur stabilized in an insoluble, high-molecular-weight form, typically containing 60-90% cyclic S8 chains with the remainder as soluble sulfur; manufacturers produce it via thermal polymerization of molten sulfur followed by rapid quenching and solvent extraction to achieve the desired insolubility index above 90%. The material functions primarily as a vulcanizing agent that prevents sulfur bloom in rubber compounds while maintaining cross-link density during tire curing cycles. Granular and dispersion grades capture the deepest margin pools as tire makers prioritize dust-free handling and pre-dispersed masterbatch formats that reduce mixing variability. Powder grades remain structurally important in smaller rubber product batches where capital investment in automated dosing lags. Thermal process technology dominates installed capacity, though chemical process variants gain traction where energy costs and carbon intensity thresholds tighten.
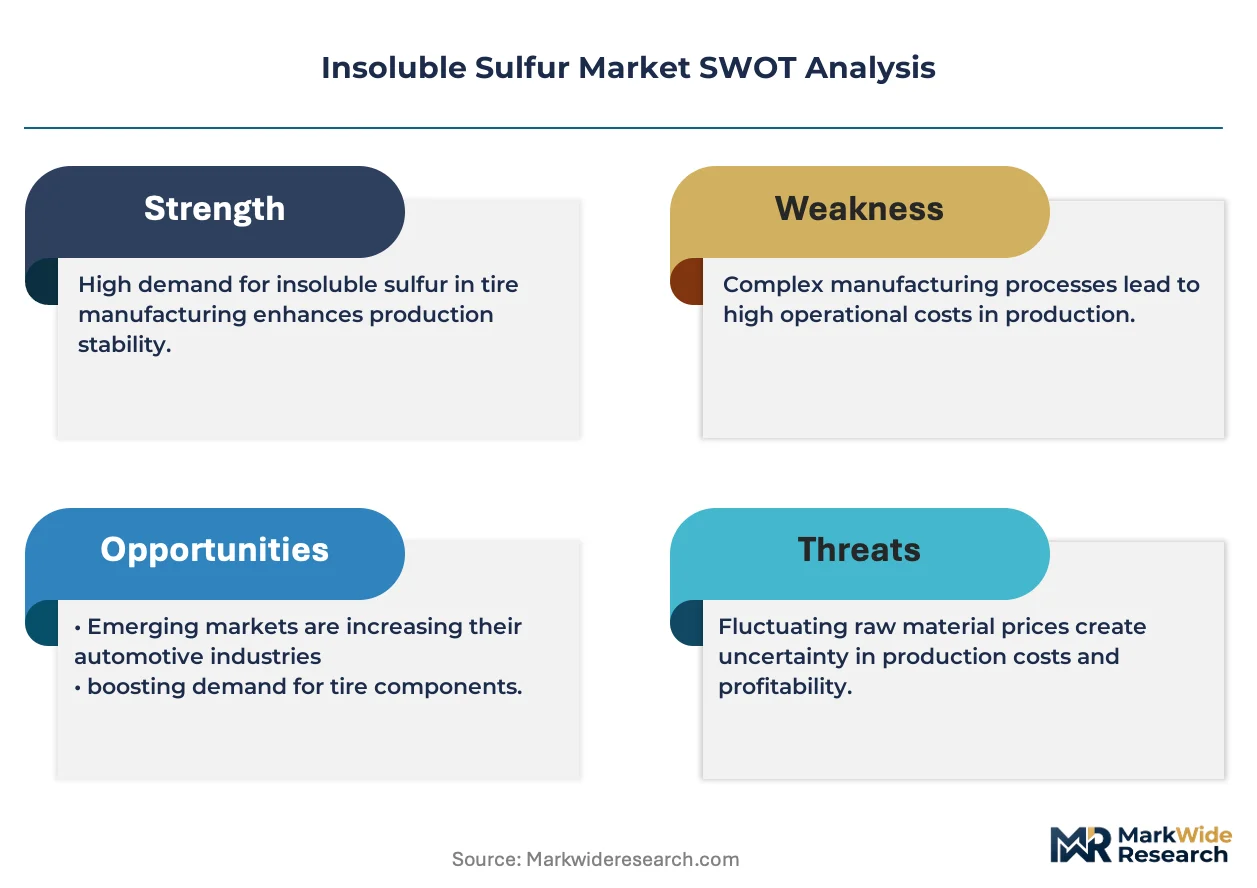
REACH registration requirements in Europe and China's GB/T rubber chemical standards constrain market entry for non-compliant producers while elevating testing documentation burdens across supply chains. EPA air emissions rules and India's BIS certification for rubber chemicals further fragment compliance obligations by geography. Buyers must monitor regulatory divergence on polymeric sulfur purity thresholds and solvent residue limits that threaten cross-border product interchangeability.
Market Dynamics
Tire manufacturers are consolidating procurement around high-dispersion insoluble sulfur grades as China's GB standards and India's BIS norms tighten rolling-resistance mandates, forcing feedstock upgrades across Asian rubber chemical complexes.
Growth Catalysts
- REACH registration thresholds:ECHA compliance requirements in Europe screen out non-compliant producers, elevating specification premiums for registered suppliers serving premium tire brands.
- Radial tire production corridors:East Asian automotive supply chains are expanding captive rubber chemical capacity to serve just-in-time vulcanization needs.
- Thermal process optimization:Energy-efficient quenching technologies are lowering carbon intensity in high-volume sulfur polymerization, aligning with China's dual carbon goals.
Market Restraints
- Molten sulfur feedstock volatility:Refinery output fluctuations and sulfur recovery from oil sands create input cost instability for thermal process operators.
- Solvent extraction dependence:Carbon disulfide and other extraction solvents face tightening EPA air emissions rules, raising compliance capital intensity.
- Soluble sulfur substitution:Lower-grade rubber goods manufacturers in price-sensitive segments tolerate surface bloom risks to avoid insoluble sulfur premiums.
Strategic Opportunities
- Pre-dispersed masterbatch formats:Dust-free handling systems are opening specification slots in automated tire mixing lines where dust exposure liability previously blocked adoption.
- India's PLI scheme for chemicals:Production-linked incentives for advanced rubber chemicals are attracting greenfield investment in Gujarat and Tamil Nadu chemical corridors.
- Digital dosing integration:IoT-enabled compound management systems are creating data-locked supplier relationships through real-time vulcanization monitoring.
Industry Challenges
- Cross-border product interchangeability:Divergent purity thresholds between China's GB/T standards and REACH solvent residue limits force dual-certification inventory strains.
- Specialized process engineering talent:Thermal polymerization expertise concentrates among aging technical workforces in Germany and Japan, constraining knowledge transfer to new capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insoluble Sulfur Market |
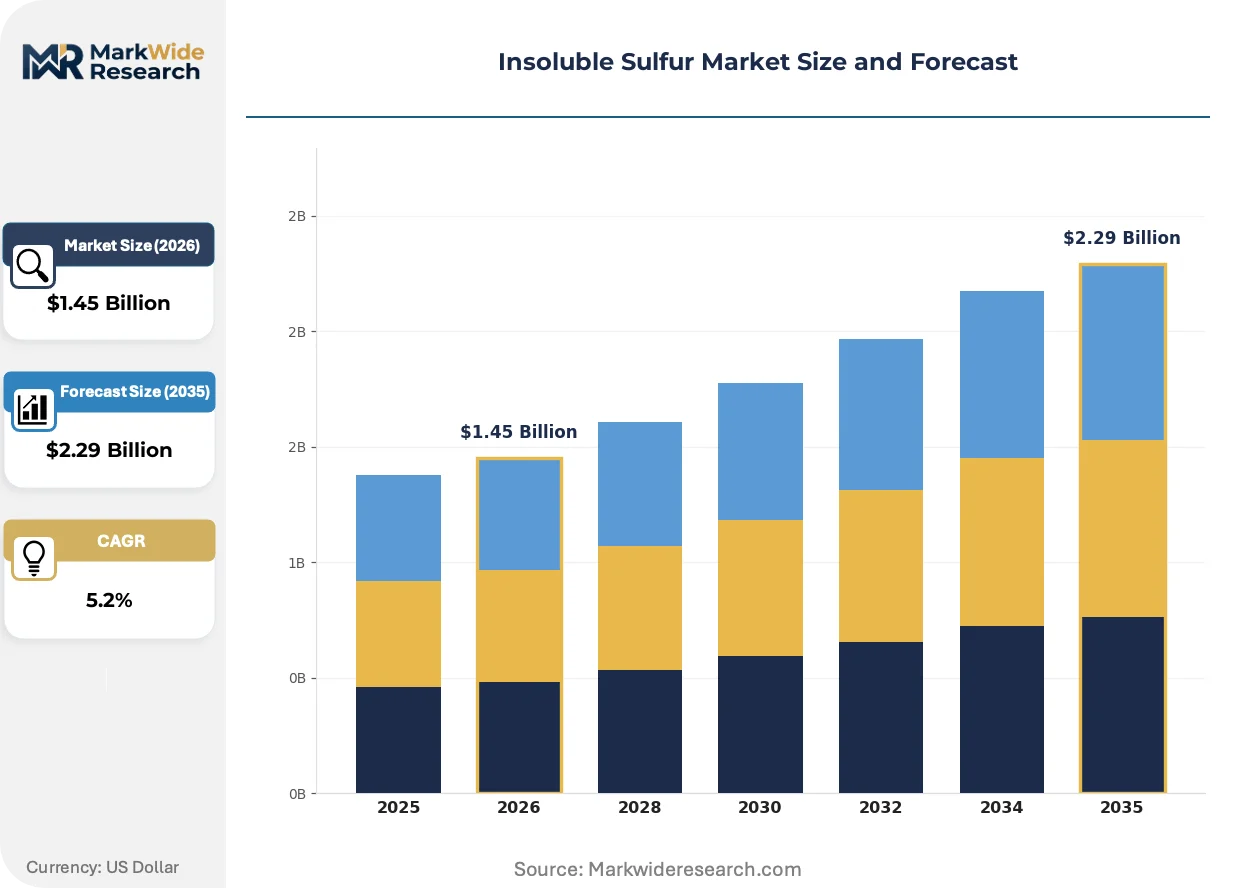
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
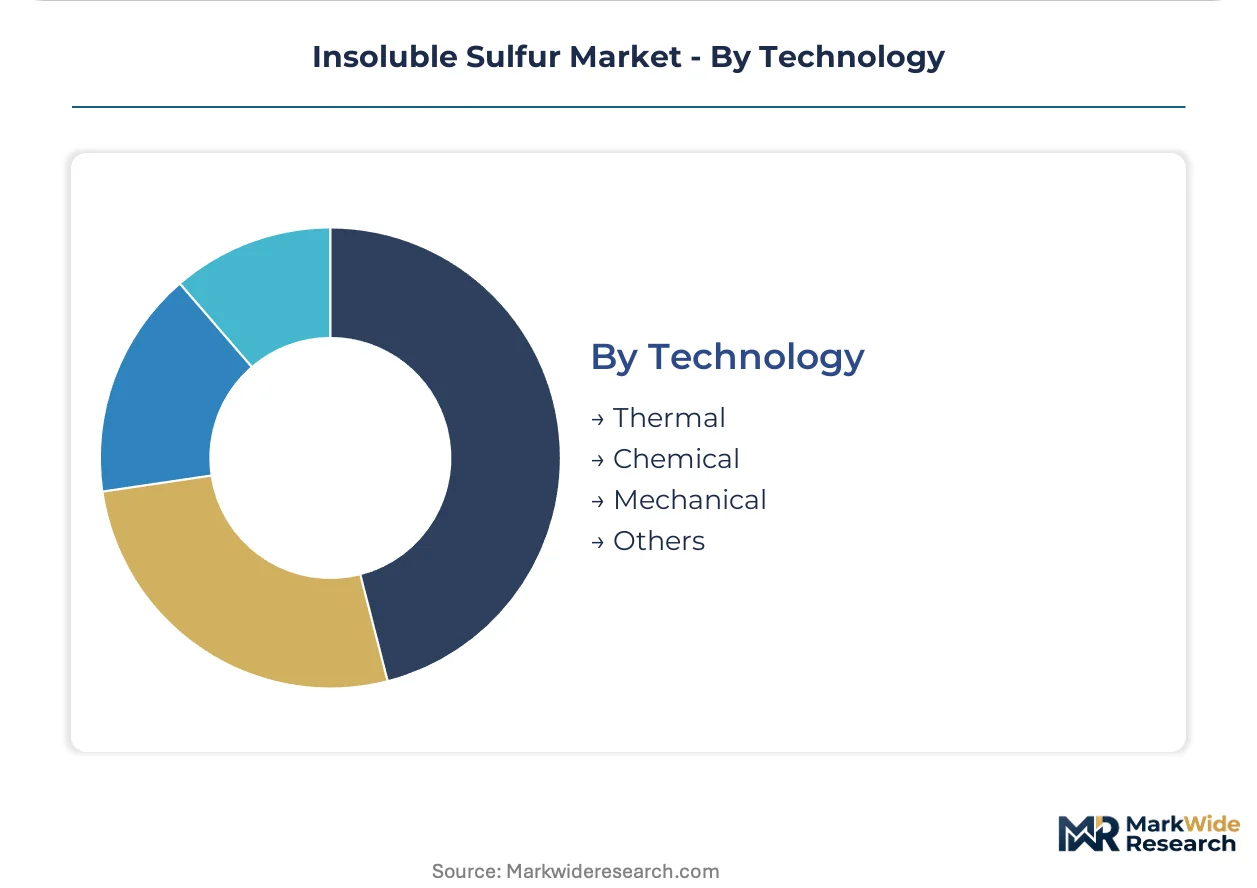
| Segmentation | Product Type: Granular, Powder, Liquid, Dispersion Application: Tires, Rubber Products, Sealants, Coatings End User: Automotive, Construction, Consumer Goods, Industrial Technology: Thermal, Chemical, Mechanical, Others |
| Companies Covered | China Sunsine Chemical Holdings Limited, Eastman Chemical Company, LANXESS, SHIKOKU CHEMICALS CORPORATION, Grupa Azoty, Oriental Carbon & Chemicals Limited, Henan Kailun Chemical Co., Ltd., Willing New Materials Technology Co., Ltd., Flexsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insoluble Sulfur Market Strategic Shifts & Innovations
Manufacturing technology is pivoting toward closed-loop solvent recovery and automated dispersion systems that compress variability in tire curing cycles while tightening environmental compliance.
Oil-treated insoluble sulfur grades are absorbing specification premiums in radial tire manufacturing as dust-free handling requirements harden across automated mixing lines. Major tire makers in Germany and South Korea are phasing in these grades at 15-20% substitution rates annually. The technology is absorbing margin pools previously captured by conventional powder grades while compressing supplier differentiation around dispersion uniformity metrics.
China's GB/T rubber chemical standards and India's BIS certification frameworks are converging on stricter polymeric sulfur purity thresholds that exceed legacy soluble sulfur tolerances. This regulatory tightening fragments cross-border product interchangeability and elevates testing documentation burdens. Tire makers operating multi-country supply chains are responding by consolidating procurement around dual-certified suppliers with laboratory networks in both jurisdictions.
Compound managers at tier-one tire manufacturers are unbundling after-sales technical service from material supply contracts, treating vulcanization optimization as a separate purchased expertise. This procurement model change disrupts traditional chemical supplier relationships and elevates independent rubber consulting firms. The shift is most visible in Japan and Germany, where METI and KBA vehicle efficiency mandates drive precise cross-link density requirements.
Insoluble Sulfur Market Segmentation
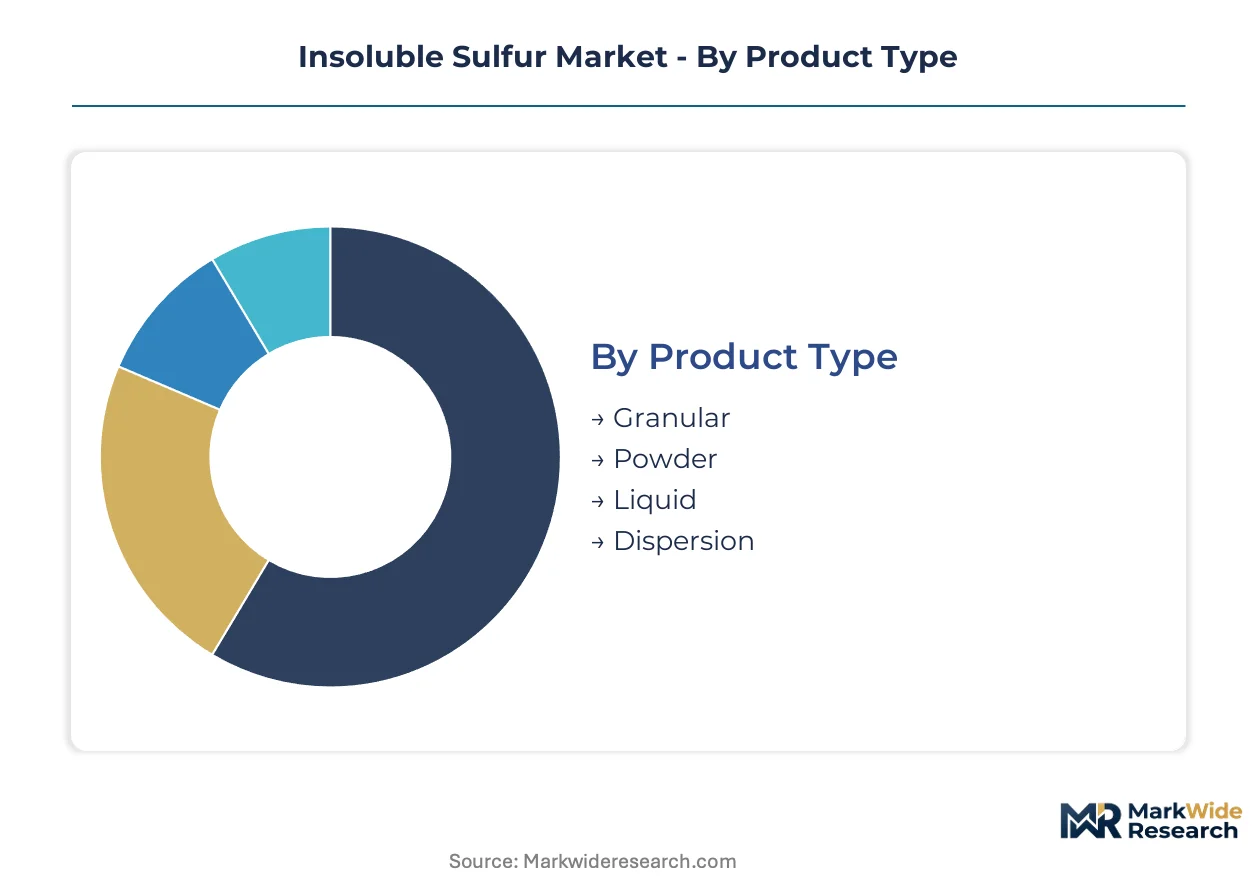
Insoluble sulfur markets fragment across four distinct category axes, each governed by divergent capital requirements and specification premiums. Tire makers drive grade selection through automated dosing compatibility and rolling-resistance mandates, while process technology choices lock in long-term carbon intensity profiles.
Product Type:
Granular and dispersion formats demand the heaviest upfront investment in closed-loop solvent recovery and automated dispersion systems, compressing supplier economics around scale thresholds.
- Granular:Dust-free spherical particles engineered for pneumatic conveying systems in high-volume tire plants. Procurement concentrates among radial tire manufacturers in South Korea and Germany where automated mixing lines eliminate dust exposure liability. REACH registration requirements in Europe elevate specification premiums for registered granular suppliers serving premium tire brands.
- Dispersion:Pre-dispersed masterbatch formats containing insoluble sulfur suspended in polymer carriers, enabling direct addition to rubber compounds without dust generation. Demand is climbing fastest in Japan and China where METI efficiency mandates and GB standards tighten cross-link density tolerances. IoT-enabled compound management systems are creating data-locked supplier relationships through real-time vulcanization monitoring.
- Powder:Conventional pulverized grades retain structural importance in smaller rubber product batches where capital investment in automated dosing lags.
- Liquid:Oil-treated suspensions serving niche coating applications requiring sprayable sulfur delivery.
Most installed capacity flows through granular grades. Expansion is steepest in dispersion formats.
Application:
Tire manufacturing absorbs the deepest specification premiums, while rubber goods and sealant applications compete on cost-optimized thermal process routes.
- Tires:Radial tire curing cycles demand high-dispersion insoluble sulfur to prevent sulfur bloom while maintaining cross-link density under China's GB standards and India's BIS norms. East Asian automotive supply chains are expanding captive rubber chemical capacity to serve just-in-time vulcanization needs.
- Rubber Products:Industrial hoses, belts, and molded goods tolerate wider specification bands where lower-grade manufacturers accept surface bloom risks to avoid premium grades.
- Sealants:Construction-grade elastomeric sealants employ oil-treated grades for enhanced adhesion in building envelope applications.
- Coatings:Protective industrial coatings utilize liquid sulfur suspensions for corrosion-resistant film formation.
Tire applications dominate revenue concentration. Rubber products segment offers volume scale in price-sensitive procurement.
End User:
Automotive OEMs impose the most stringent purity thresholds, while construction and consumer goods segments fragment across regional certification requirements.
- Automotive:Tier-one tire manufacturers serving German and South Korean vehicle producers specify oil-treated grades with 15-20% annual substitution rates. KBA vehicle efficiency mandates drive precise cross-link density requirements that unbundle technical service from material supply contracts.
- Construction:Building sealant and waterproofing membrane producers in India and China source cost-optimized powder grades under BIS and GB/T frameworks.
- Consumer Goods:Footwear and sporting goods manufacturers in Vietnam and Indonesia prioritize dust-free handling in labor-intensive mixing environments.
- Industrial:Conveyor belt and mining hose producers in Australia and Brazil accept soluble sulfur substitution in non-critical applications.
Automotive end users command specification premiums. Industrial segment provides baseline volume absorption.
Technology:
Thermal polymerization dominates installed base economics, though chemical process variants gain traction where energy costs and carbon intensity thresholds tighten.
- Thermal:Molten sulfur polymerization followed by rapid quenching and solvent extraction achieves insolubility indices above 90%. Energy-efficient quenching technologies are lowering carbon intensity in high-volume sulfur polymerization, aligning with China's dual carbon goals.
- Chemical:Catalytic polymerization routes reduce solvent extraction dependence where EPA air emissions rules tighten. Process expertise concentrates among aging technical workforces in Germany and Japan, constraining knowledge transfer to new capacity.
- Mechanical:High-shear milling approaches serve niche dispersion production with lower capital barriers.
- Others:Emerging electrochemical and plasma-assisted routes remain pre-commercial.
Thermal capacity underpins current supply. Chemical process expansion is gaining share fastest in European and East Asian corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal polymerization expertise concentrates among aging technical workforces in Germany and Japan, constraining knowledge transfer to emerging capacity centers while regional demand patterns diverge under divergent regulatory frameworks.
China
Radial tire manufacturers in Jiangsu and Shandong provinces are expanding procurement of high-dispersion grades to meet stricter rolling-resistance mandates under GB standards. MIIT's dual carbon goals are accelerating adoption of energy-efficient quenching technologies in sulfur polymerization plants. The Yangtze River Delta hosts integrated rubber chemical complexes serving just-in-time automotive supply chains.
India
Tire makers in Gujarat and Tamil Nadu are upgrading feedstock specifications to comply with BIS certification tightening for rubber chemicals. The PLI scheme for advanced chemicals is attracting greenfield investment in chemical corridors. Mumbai-Pune industrial belt suppliers are consolidating procurement around dual-certified inventory to manage cross-border interchangeability strains.
Germany
Premium tire brands specify oil-treated grades with precise cross-link density requirements under KBA vehicle efficiency mandates. REACH registration requirements screen out non-compliant producers, elevating specification premiums for registered suppliers. The Ruhr industrial region anchors European rubber chemical capacity with specialized complexes serving automotive OEMs.
Japan
METI efficiency mandates are driving unbundling of after-sales technical service from material supply contracts among tier-one tire manufacturers. Osaka-based compound managers are prioritizing pre-dispersed masterbatch formats with IoT-enabled vulcanization monitoring. Chubu region technical expertise in thermal polymerization remains concentrated among aging workforces.
South Korea
Automotive supply chains are phasing in oil-treated grades at 15-20% annual substitution rates to meet export market specifications. Busan-Ulsan chemical corridor producers are expanding captive rubber chemical capacity for just-in-time vulcanization needs. Seoul Capital Area tire makers are consolidating procurement around dust-free handling systems in automated mixing lines.
Insoluble Sulfur Market Key Industry Players
Top-tier vendors anchor specification-premium segments serving premium tire brands, while mid-tier operators compete on cost-optimized thermal process routes for volume buyers in South Asia. The supply base fragments across backward-integrated chemical conglomerates, specialized rubber additive producers, and regional fabricators with captive sulfur refining. Three archetypes dominate: integrated petrochemical players with feedstock control, standalone rubber chemical specialists with formulation expertise, and emerging Asian producers leveraging scale economics. Capacity expansion and portfolio diversification toward high-dispersion grades constitute the dominant competitive moves.
Among integrated chemical conglomerates, Eastman Chemical Company and LANXESS occupy positions defined by backward integration into sulfur refining and specialized rubber chemical complex operations. China Sunsine Chemical Holdings Limited exemplifies the scale-driven Asian producer archetype competing on cost-optimized thermal process routes. Oriental Carbon & Chemicals Limited sits within the regional specialist tier serving volume procurement in South Asian corridors. SHIKOKU CHEMICALS CORPORATION represents Japanese technical expertise concentration in thermal polymerization. These named entities anchor industry-level patterns without implying specific strategic actions or market positions beyond their evident geographic and structural characteristics.
| Leading Market Players |
|---|
| China Sunsine Chemical Holdings Limited |
| Eastman Chemical Company |
| LANXESS |
| SHIKOKU CHEMICALS CORPORATION |
| Grupa Azoty |
| Oriental Carbon & Chemicals Limited |
| Henan Kailun Chemical Co., Ltd. |
| Willing New Materials Technology Co., Ltd. |
| Flexsys |
| Others |
Cost & Logistics Intelligence
Tier-one tire manufacturers in Germany and South Korea concentrate procurement power around oil-treated and high-dispersion grades, forcing suppliers into contract-based long-term offtake structures with unbundled technical service pricing. This buyer consolidation rewards REACH-registered and dual-certified suppliers with specification premiums while compressing margins for undifferentiated powder grades serving price-sensitive rubber goods producers.
Pricing Analysis
Bundled technical service contracts are unbundling across Japanese and German tire manufacturing corridors, with compound managers purchasing vulcanization optimization expertise separately from material supply. Price differentiation hinges on REACH registration status and dispersion uniformity metrics, with oil-treated grades commanding premiums over conventional powder formats. Cost compression in standard powder tiers is intensifying because soluble sulfur substitution tolerates surface bloom risks in non-critical applications. Rubber goods manufacturers in Vietnam and Indonesia exhibit highest price sensitivity, while automotive OEMs in South Korea prioritize dust-free handling over unit cost.
Supply Chain Analysis
REACH and BIS certification requirements gate supplier participation in European and Indian procurement channels, fragmenting cross-border product interchangeability. Manufacturing concentrates in China, Germany, and Japan, with thermal polymerization expertise anchored in aging technical workforces constraining knowledge transfer. Feedstock draws from refinery sulfur recovery and oil sands extraction, exposing operators to molten sulfur price volatility. Single-source vulnerability concentrates in solvent extraction inputs, particularly carbon disulfide facing tightening EPA air emissions enforcement. Distribution runs through integrated rubber chemical complexes serving regional automotive supply chains with just-in-time vulcanization scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insoluble sulfur market functions as a regulatory compounder, with China's GB standards and India's BIS norms tightening polymeric sulfur purity thresholds and forcing feedstock upgrades across Asian rubber chemical complexes.
For Market Incumbents: Deepen backward integration into sulfur refining to secure feedstock consistency against molten sulfur volatility, while expanding laboratory networks in China and India to capture dual-certification premiums. Soluble sulfur substitution in price-sensitive rubber goods segments threatens volume absorption in powder grades, making energy-efficient quenching technology investment the critical defensive lever for thermal process operators. For New Entrants and Emerging Players: Industrial conveyor belt and mining hose producers in Australia and Brazil represent underserved buyer archetypes tolerating specification trade-offs for cost-optimized supply. Pre-dispersed masterbatch formats for automated mixing lines in China's Yangtze River Delta corridor offer the most penetrable entry point, with IoT-enabled vulcanization monitoring as the distinguishing go-to-market mechanism to lock in data-dependent supplier relationships. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates with captive sulfur refining are the most active acquirer in this space, targeting standalone rubber chemical specialists with formulation expertise and regional certification access. The five-to-ten year viability window favors assets with demonstrated dual-certification capabilities spanning REACH and GB/T frameworks. Thermal polymerization talent scarcity in Germany and Japan serves as the critical inflection signal, with successful knowledge transfer to emerging capacity centers determining competitive durability.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Greenfield investment in Gujarat and Tamil Nadu chemical corridors leverages India's PLI scheme for advanced rubber chemicals. |
| Backward Integration | Control over sulfur refining secures feedstock consistency against refinery output fluctuations and oil sands recovery volatility. |
| Green Manufacturing Transition | Energy-efficient quenching technologies align thermal polymerization with China's MIIT dual carbon goals. |
| Long-term Supply Agreement | Contract-based offtake structures with tier-one tire makers stabilize revenue against soluble sulfur substitution pressure. |
| Joint Venture | Technology partnerships with Japanese thermal polymerization specialists accelerate knowledge transfer to emerging Asian capacity centers. |
Research Approach
Bottom-up tire manufacturing demand modeling reconciled against top-down sulfur refining capacity tracking forms the analytical core of this study. Primary interviews with compound managers at tier-one tire manufacturers, procurement leads at rubber chemical distributors, thermal process engineers, and regulatory affairs specialists at REACH-registered suppliers combined with secondary validation from customs trade data, SEC 10-K filings of listed chemical conglomerates, BIS certification registries, and MIIT industrial policy disclosures. This dual approach enables triangulation between consumption patterns and production economics.
Historical trendline analysis of grade substitution rates and thermal process energy intensity informed the projection framework across the analysis window. Segmentation dimensions modeled include product format tier, end-use application, automotive OEM versus industrial buyer type, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating rolling-resistance mandate stringency indices and carbon intensity threshold trajectories. Forecast inputs incorporate solvent extraction cost curves and dual-certification penetration rates by supplier geography.
Underlying measurement precision varies by segment; oil-treated and dispersion grades carry tighter precision than powder grades given concentrated buyer transparency. Forecasts reflect documented assumptions regarding regulatory convergence timelines and thermal polymerization technology transfer velocity. A model refresh is warranted upon material change in China's GB standard purity thresholds or EPA enforcement posture on carbon disulfide emissions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Active Speaker Market
Others
Delumper Market
Others
Residential Electrical Conduit Market
Others
Industrial Gauges Market
Others
Ammeters Market
Others
Military Wearable Market
Others
Lightweight Compact Wheel Loader Market
Others
Fluorapatite Market
Others
Channel-In-A-Box (Ciab) Market
Others
North America Wiring Duct Market
Others
Global Smartphone ODM Market
Others
Thailand Travel Retail Market
Others
United States Air Furnaces Market
Others
Canada 3D Printing Construction Market
Others
Global Emergency Spill Response Market
Others
Belt Press Filter Market