
 Allogeneic T Cell Therapies Market | 2026-2036
Allogeneic T Cell Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Allogeneic T Cell Therapies Market Outlook
Oncology departments are rebalancing toward outpatient allogeneic protocols as inpatient autologous capacity strains hospital budgets. Allogene Therapeutics leverages centralized manufacturing to reduce per-dose production costs across multiple hematologic indications. Cellectis anchors European engineering capabilities with its TALEN platform, while CRISPR Therapeutics competes through multiplexed gene-editing approaches that broaden donor compatibility.
Allogeneic T cell therapies comprise donor-derived lymphocytes engineered ex vivo to express tumor-targeting receptors, cryopreserved for off-the-shelf administration without patient-specific manufacturing. These cellular products typically undergo expansion in bioreactors over 7-14 days, with viability thresholds dictating release criteria for clinical use. CAR-T cell therapy dominates current development pipelines, while TCR therapy occupies solid tumor applications where surface antigen targeting proves insufficient. Gamma delta T cells represent the fastest-growing segment due to their MHC-independent recognition and reduced alloreactivity risk.
The FDA regulates these products through the Center for Biologics Evaluation and Research under regenerative medicine advanced therapy designation, while the EMA's Committee for Advanced Therapies coordinates European centralized assessment. Both frameworks mandate extensive pharmacovigilance for cytokine release syndrome and graft-versus-host events that shape clinical trial design and post-market surveillance requirements. Stakeholders must monitor evolving manufacturing standards from the FDA and EMA as scale-out pressures collide with batch consistency demands.
Market Dynamics
Centralized manufacturing economics are compressing cost structures as academic medical centers strain under inpatient autologous capacity constraints and seek outpatient alternatives.
Growth Catalysts
- RMAT Designation:The FDA's regenerative medicine advanced therapy pathway accelerates clinical development timelines and compresses regulatory review periods for eligible candidates.
- Cryopreservation Advances:Improved cell viability protocols enable distributed inventory models that reduce vein-to-vein time and expand treatment access.
- Gamma Delta Biology:MHC-independent recognition mechanisms unlock donor compatibility pools while reducing graft-versus-host disease risk profiles.
Market Restraints
- Donor Material Scarcity:Qualified leukapheresis collection networks concentrate in the United States and Western Europe, creating geographic supply bottlenecks.
- Alloreactivity Management:Persistent immune rejection mechanisms require sophisticated gene-editing interventions that extend manufacturing timelines.
- Bioreactor Scale Limits:Single-use expansion vessels face capacity ceilings that constrain batch sizes below commercial demand thresholds.
Strategic Opportunities
- Solid Tumor Expansion:TCR-engineered platforms penetrate carcinoma indications where surface antigen density limits CAR-T efficacy.
- Japan's PMDA Acceleration:Sakigake designation pathways compress review timelines and create first-mover advantages in Asia-Pacific commercialization.
- Multiplexed Editing Convergence:CRISPR-Cas9 combined with base-editing technologies enables simultaneous knockout of multiple rejection mediators.
Industry Challenges
- Vector Manufacturing Bottleneck:Lentiviral and electroporation reagent production capacity lags behind cell therapy expansion demand.
- Pharmacovigilance Infrastructure:Cytokine release syndrome monitoring requires specialized nursing protocols that strain outpatient clinic staffing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allogeneic T Cell Therapies Market |
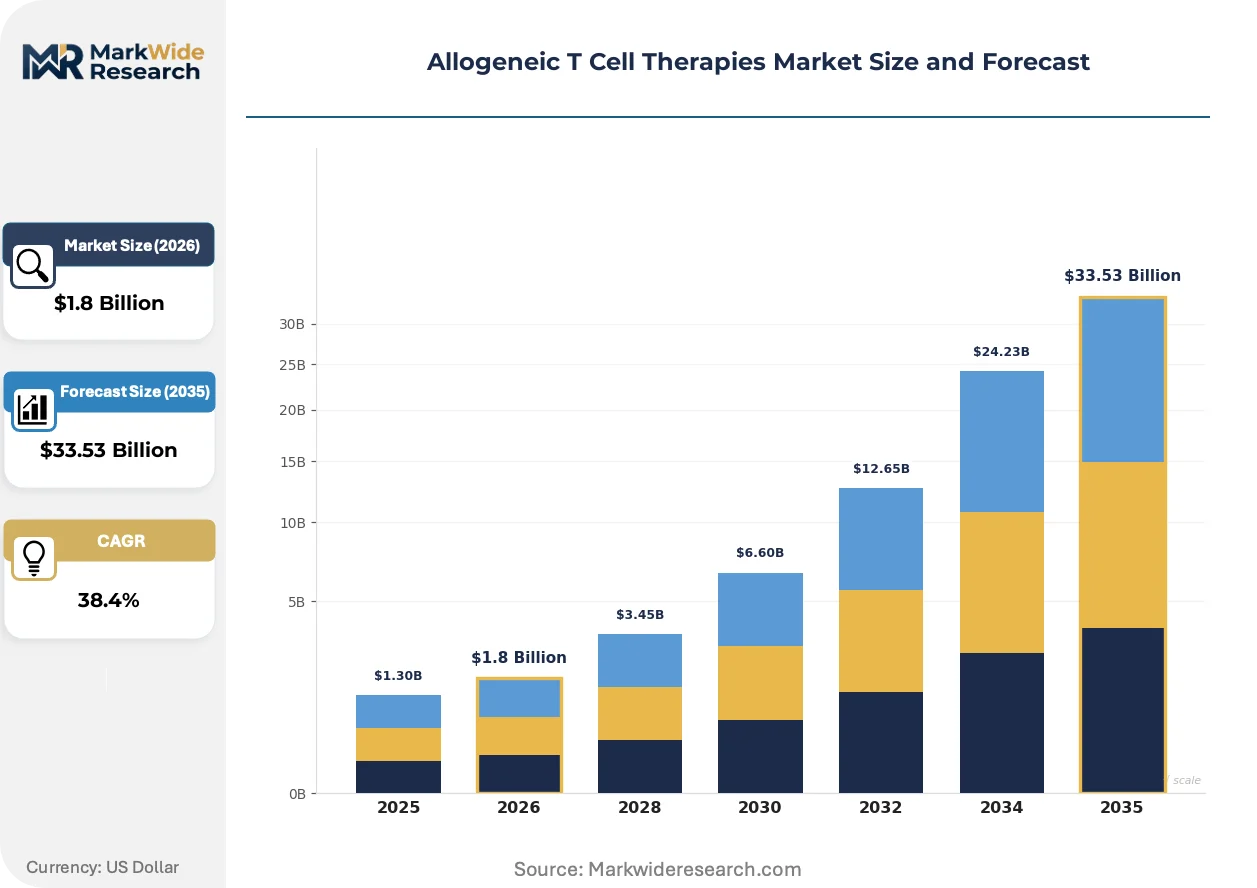
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: CAR-T Cell, TCR Therapy, Gamma Delta T Cells, NK Cell Therapy Application: Oncology, Autoimmune Diseases, Infectious Diseases, Hematological Disorders Delivery Mode: Intravenous, Intra-tumoral, Subcutaneous, Intracranial End User: Hospitals, Research Institutes, Specialty Clinics, Contract Research Organizations |
| Companies Covered | Allogene Therapeutics, Inc., Cellectis S.A., CRISPR Therapeutics AG, Fate Therapeutics, Inc., Atara Biotherapeutics, Inc., Adaptimmune Therapeutics plc, Caribou Biosciences, Inc., Precision BioSciences, Inc., Celyad Oncology SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allogeneic T Cell Therapies Market Strategic Shifts
Process intensification and closed-system automation are compressing manufacturing footprints while regulatory harmonization efforts reshape trial design requirements across major jurisdictions.
Closed-system bioreactors are automating expansion workflows that previously demanded open manipulation in biosafety cabinets. Contract development and manufacturing organizations are adopting these platforms at accelerating rates to reduce contamination risk and operator labor intensity. This automation is automating quality control sampling intervals and enabling real-time process analytical technology integration that compresses release timelines.
The EMA's Committee for Advanced Therapies has tightened comparability protocol requirements for post-manufacturing change assessments. Sponsors must now demonstrate analytical and functional equivalence across process modifications with greater statistical rigor. European hematology centers are responding by locking manufacturing processes earlier in development cycles to avoid costly bridging studies.
Academic medical center purchasing committees are consolidating supplier relationships around vendors offering integrated manufacturing and logistics services. CDMOs with captive vector production and cryogenic distribution networks are displacing fragmented procurement models. This concentration is most visible in the United States, where hospital systems negotiate enterprise contracts spanning multiple cell therapy programs.
Allogeneic T Cell Therapies Market Segmentation
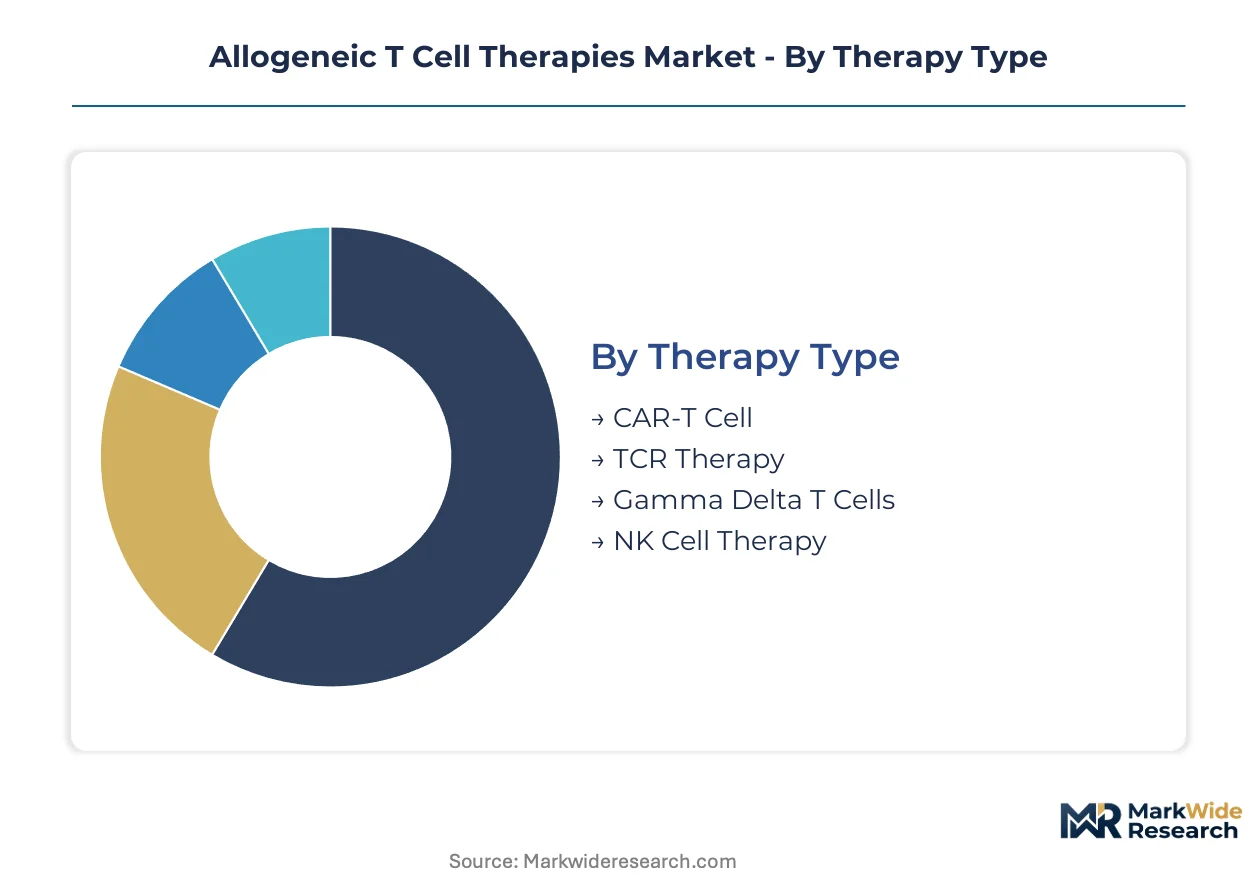
Segmentation in allogeneic T cell therapies reveals how manufacturing scale, clinical infrastructure, and reimbursement pathways align with specific product modalities. Therapy type determines centralized versus distributed production economics, while application focus shapes regulatory strategy and pharmacovigilance requirements.
Therapy Type:
Standalone engineered platforms dominate current pipelines, with embedded gene-editing capabilities becoming the integration differentiator across manufacturing tiers.
- CAR-T Cell:Chimeric antigen receptor constructs redirect T cell specificity against surface antigens without MHC restriction. Demand concentrates in United States hematology centers where inpatient monitoring infrastructure supports cytokine release syndrome management.
- TCR Therapy:T cell receptor engineering enables targeting of intracellular antigens presented on MHC molecules, penetrating solid tumor indications where surface density limits CAR-T efficacy. Academic medical centers in Germany and Japan are establishing dedicated TCR infusion protocols.
- Gamma Delta T Cells:Innate lymphocyte subsets with MHC-independent recognition reduce alloreactivity risk and expand donor compatibility pools.
- NK Cell Therapy:Natural killer cell platforms leverage antibody-dependent cellular cytotoxicity without prior antigen sensitization.
CAR-T Cell leads volumes today; Gamma Delta T Cells is gaining share fastest.
Application:
Cost tier stratification separates curative oncology indications from chronic disease management protocols with differing reimbursement and dosing economics.
- Oncology:Hematologic malignancies drive initial commercialization with established infusion protocols and specialized nursing infrastructure. United States cancer centers account for the dominant procedure volume given FDA RMAT pathway maturity and CAR-T-specific reimbursement codes.
- Autoimmune Diseases:Lupus and multiple sclerosis applications are emerging where B cell depletion mechanisms translate from oncology experience. European rheumatology departments are piloting outpatient infusion models to reduce hospitalization costs.
- Infectious Diseases:Pathogen-specific T cell banks target cytomegalovirus and Epstein-Barr virus in immunocompromised hosts.
- Hematological Disorders:Sickle cell disease and thalassemia programs leverage HSC-compatible editing platforms.
Oncology commands premium pricing today; Autoimmune Diseases is climbing the fastest as outpatient protocols expand.
Delivery Mode:
Volume concentration tracks with administration complexity, where systemic delivery scales broadly versus localized approaches requiring interventional infrastructure.
- Intravenous:Peripheral vein administration enables standardized nursing protocols and distributed treatment access. United States hospital systems are consolidating procurement around cryopreserved IV formulations that reduce vein-to-vein logistics.
- Intra-tumoral:Direct lesion injection concentrates cellular payload at solid tumor sites with reduced systemic exposure. Interventional radiology departments at MD Anderson and Memorial Sloan Kettering are establishing image-guided delivery protocols.
- Subcutaneous:Dermal administration is under evaluation for gamma delta T cell persistence advantages.
- Intracranial:CNS-directed delivery requires neurosurgical collaboration for glioblastoma applications.
Intravenous dominates procedure counts today; Intra-tumoral is expanding most quickly with solid tumor pipeline maturation.
End User:
Customer type segmentation reflects purchasing authority concentration, where integrated health systems negotiate enterprise contracts versus fragmented research procurement.
- Hospitals:Academic medical centers with cellular therapy accreditation anchor commercial demand through dedicated infusion units and pharmacy compounding capabilities. United States hospital systems including Mayo Clinic and Cleveland Clinic are locking multi-year supply agreements.
- Research Institutes:National cancer centers and university laboratories drive early-phase clinical trial enrollment with investigator-initiated protocol flexibility. Francis Crick Institute and Karolinska Institutet anchor European preclinical translation.
- Specialty Clinics:Outpatient oncology networks are adopting allogeneic protocols to bypass autologous manufacturing bottlenecks.
- Contract Research Organizations:CDMOs with captive vector production are displacing fragmented procurement through integrated manufacturing and logistics services.
Hospitals lead purchasing volume today; Specialty Clinics is gaining share fastest as outpatient administration protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston corridor anchors cell therapy infrastructure through Dana-Farber Cancer Institute and Massachusetts General Hospital. FDA RMAT pathway maturity and Medicare reimbursement codes concentrate clinical trial enrollment and first commercial deployments in this cluster.
United States
Academic medical centers in Houston and New York City strain under autologous manufacturing bottlenecks while expanding outpatient allogeneic protocols. The FDA's regenerative medicine advanced therapy designation compresses development timelines for eligible candidates. MD Anderson Cancer Center and Memorial Sloan Kettering anchor interventional radiology networks for intra-tumoral delivery development.
Germany
University hospitals in Heidelberg and Munich establish dedicated TCR infusion protocols for solid tumor applications. The EMA's Committee for Advanced Therapies coordinates centralized assessment under advanced therapy medicinal product frameworks. The National Center for Tumor Diseases in Heidelberg drives European preclinical translation with investigator-initiated protocol flexibility.
Japan
Sakigake designation pathways compress PMDA review timelines for first-mover advantages in Asia-Pacific commercialization. Tokyo and Osaka hematology centers pilot gamma delta T cell outpatient models to reduce hospitalization costs. The Japan Agency for Medical Research and Development funds manufacturing automation for cryopreserved inventory distribution.
Switzerland
Swissmedic's streamlined assessment procedures attract development-stage sponsors seeking European market entry. Basel and Zurich biotech clusters leverage proximity to Novartis manufacturing expertise in CAR-T infrastructure. The Swiss Federal Office of Public Health coordinates pharmacovigilance requirements with German and French regulators for cross-border trial enrollment.
United Kingdom
The Francis Crick Institute and Karolinska Institutet partnerships drive early-phase clinical trial enrollment with centralized engineering capabilities. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit frameworks with FDA RMAT standards to maintain trial access. London cancer centers negotiate enterprise contracts spanning multiple cell therapy programs through NHS England specialized commissioning.
Allogeneic T Cell Therapies Market Competitive Environment
Strategic partnerships dominate the current landscape as sponsors secure vector manufacturing capacity and cryogenic distribution networks. The vendor base concentrates around three tiers: integrated pharmaceutical platforms with captive manufacturing, gene-editing technology licensors, and contract development organizations with closed-system automation. Two archetypes define positioning: centralized manufacturing specialists leveraging scale economics, and distributed inventory platforms emphasizing vein-to-vein speed. Technology licensing and geographic expansion constitute the dominant competitive moves as firms secure regional regulatory approvals.
Among gene-editing technology providers, Cellectis S.A. and CRISPR Therapeutics AG exemplify divergent engineering philosophies. Allogene Therapeutics, Inc. occupies a position within the centralized manufacturing tier. Fate Therapeutics, Inc. represents the induced pluripotent stem cell platform archetype. These named entities anchor broader patterns visible across development pipelines without implying specific strategic actions or market positions.
| Leading Market Players |
|---|
| Allogene Therapeutics, Inc. |
| Cellectis S.A. |
| CRISPR Therapeutics AG |
| Fate Therapeutics, Inc. |
| Atara Biotherapeutics, Inc. |
| Adaptimmune Therapeutics plc |
| Caribou Biosciences, Inc. |
| Precision BioSciences, Inc. |
| Celyad Oncology SA |
| Others |
Value Chain & Pricing Dynamics
Gene-editing scientists concentrated in Greater Boston and Basel command compensation premiums that compress margins at emerging cell therapy developers and widen pricing spreads between premium-grade engineered products and standard-tier alternatives.
Pricing Analysis
Vector manufacturing costs pass through to finished-dose pricing with minimal absorption capacity across development-stage sponsors. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade clinical products from research-use materials and compendial-grade reagents. Pricing pressure stems from single-source lentiviral supplier concentration and electroporation reagent bottlenecks. Academic medical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while integrated pharmaceutical platforms absorb premiums through captive manufacturing.
Supply Chain Analysis
Leukapheresis collection capacity rests on United States and Western European donor networks, with qualified apheresis centers in Germany and Switzerland anchoring European supply. Critical inputs span donor lymphocytes, viral vectors, and synthetic guide RNA chemistries. Single-source vulnerability concentrates in lentiviral vector production, where manufacturing capacity lags cell therapy expansion demand. Distribution runs through cryogenic logistics networks with vapor-phase liquid nitrogen storage maintaining chain-of-custody from manufacturing site to clinical infusion center.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allogeneic T cell therapy market compounds steadily as outpatient administration protocols displace inpatient autologous manufacturing and compress per-patient care costs across health systems.
For Market Incumbents: Deploy centralized manufacturing scale as the primary defensive lever. Lock multi-year supply agreements with academic medical centers to secure volume commitments against emerging gamma delta T cell competitors. Build captive vector production capacity to escape single-source dependencies that constrain batch release timelines.
For New Entrants and Emerging Players: Contract development and manufacturing organizations represent the most accessible channel partner type for market access without infrastructure buildout. Target autoimmune disease applications where outpatient B cell depletion protocols remain underpenetrated and reimbursement pathways are stabilizing. Pursue technology licensing arrangements with established gene-editing platforms to accelerate regulatory submission timelines.
For Investors and Strategic Acquirers: Large-cap pharmaceutical companies with existing CAR-T infrastructure are the most active acquirers in this space. Five-to-ten year viability hinges on manufacturing automation and cryopreservation protocol maturation. Acquisition targets with closed-system bioreactor capabilities and distributed inventory models warrant priority evaluation. Watch FDA RMAT designation velocity as the signal indicating regulatory pathway efficiency and development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system automation reduces contamination risk and compresses per-dose production economics at Allogene Therapeutics. |
| Regulatory Approval Pathway | FDA RMAT designation accelerates clinical development timelines and enables priority review for eligible allogeneic candidates. |
| Licensing Agreement | Technology partnerships with Cellectis TALEN platform broaden gene-editing access for emerging development programs. |
| Clinical Trial Advancement | Gamma delta T cell outpatient protocols at Tokyo hematology centers demonstrate reduced hospitalization cost profiles. |
| Pipeline Diversification | TCR-engineered platforms penetrate solid tumor indications where surface antigen density limits CAR-T efficacy. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market cluster. The analysis combines structured interviews with cell therapy development executives, regulatory affairs leads at sponsors, hospital procurement managers, and payer access specialists with secondary validation. Sources include FDA RMAT filings, EMA Committee for Advanced Therapies assessments, ClinicalTrials.gov enrollment data, and hospital formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the projection horizon. Segmentation dimensions encompass therapy type, application focus, delivery mode, and end-user purchasing authority. CAGRs derive from patient population incidence, treatment penetration assumptions, and dose pricing trajectories. Forecast inputs incorporate manufacturing automation adoption curves and cryopreservation viability improvements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory approval timelines, reimbursement code expansions, and vector manufacturing capacity buildout. Forecasts reflect documented assumptions regarding patient eligibility criteria and treatment persistence. Manufacturing scale-out risks, pharmacovigilance infrastructure constraints, and competitive entry velocity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Reinforcement Geosynthetics Market
Others
Channel-In-A-Box (Ciab) Market
Others
Aircraft Lighting Market
Others
Stand-Up Pouch Valves Market
Others
Germany 3D Printing Construction Market
Others
UK 3D Printing Construction Market
Others
Process Instrumentation Equipment Market
Others
Vortexers Market
Others
Underwater Lighting Market
Others
Global Simulation in Healthcare Market
Others
Hookah Tobacco Market
Others
Africa Lime Market
Others
Smart Plug Market
Others
China Packaging Primers Market
Others
Smart Card Contactless Ticketing Market
Others
Calendered Polyvinyl Chloride Flexible Films Market